
 Europe Medical Automation Market | 2026-2036
Europe Medical Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Automation Market Foresight
Multi-source procurement of automation subsystems is broadening across European hospital networks. Siemens Healthineers anchors its position through in-house manufacturing of imaging-integrated surgical robotics. Medtronic competes by leveraging its Dublin-based European distribution infrastructure for minimally invasive platforms. Koninklijke Philips differentiates through specialized patient monitoring automation that connects acute care to home settings.
Europe medical automation encompasses electromechanical systems, software-controlled devices, and AI-driven platforms that execute clinical, diagnostic, or operational tasks with minimal human intervention, typically operating at throughput rates exceeding manual processing by an order of magnitude while maintaining ISO 13485-compliant quality traceability. Its primary purpose is to reduce clinical error rates, optimize resource utilization, and enable continuous care delivery across fragmented European health systems. Robotic surgery systems command the largest installed base and generate substantial recurring revenue from consumables and service contracts. Laboratory automation is expanding fastest as diagnostic laboratories face staffing shortages and rising test volumes from personalized medicine protocols. Workflow automation solutions concentrate margin pools in software licensing, where cloud-based architectures reduce capital barriers for mid-sized clinics.
The EU Medical Device Regulation and EMA guidance on software-as-a-medical-device impose rigorous clinical validation and post-market surveillance obligations on automation vendors. CE marking under the MDR requires notified body involvement for higher-risk categories including active implantable controllers and AI-based diagnostic algorithms. France's ANSM and Germany's BfArM enforce national variations in vigilance reporting timelines that shape product launch sequencing. Stakeholders must monitor evolving harmonized standards under the EU AI Act that will classify certain clinical decision-support tools as high-risk systems requiring conformity assessments.
Market Dynamics
The EU Medical Device Regulation's tightened conformity assessment timelines are compressing product launch windows, forcing vendors to front-load clinical validation spending and restructure European distribution networks around notified body capacity constraints.
Growth Catalysts
- Laboratory automation hardware:Diagnostic laboratories across France and Germany face acute staffing shortages while test volumes surge from personalized medicine protocols.
- AI-integrated workflow platforms:French hospital network tenders increasingly mandate software-controlled patient routing and resource allocation systems.
- EU AI Act harmonized standards:High-risk classification of clinical decision-support tools creates compliance-driven replacement cycles for legacy diagnostic software.
Market Restraints
- Notified body bottleneck:CE marking under MDR requires third-party assessment for active implantable controllers, stretching approval timelines to 18-24 months.
- Semiconductor input volatility:Surgical robotics and imaging systems depend on specialized sensor chips concentrated in East Asian foundry capacity.
- Interoperability fragmentation:Proprietary data formats from incumbent vendors lock hospitals into single-source maintenance contracts.
Strategic Opportunities
- Eastern European hospital networks:Poland and Romania show underpenetrated installed bases for robotic surgery systems relative to Western European penetration rates.
- Cloud-native workflow platforms:Subscription licensing models reduce capital barriers for mid-sized clinics in Spain and Italy.
- Home-to-hospital monitoring convergence:Philips and Siemens are bridging acute care automation with remote patient monitoring for chronic disease management.
Industry Challenges
- Clinical engineering talent scarcity:European hospitals lack sufficient biomedical technicians to maintain expanding fleets of automated diagnostic equipment.
- Legacy system integration friction:New AI-driven platforms require costly middleware development to connect with existing hospital information systems.
- Post-market surveillance burden:MDR mandates continuous clinical data collection that strains vendor quality management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Automation Market |
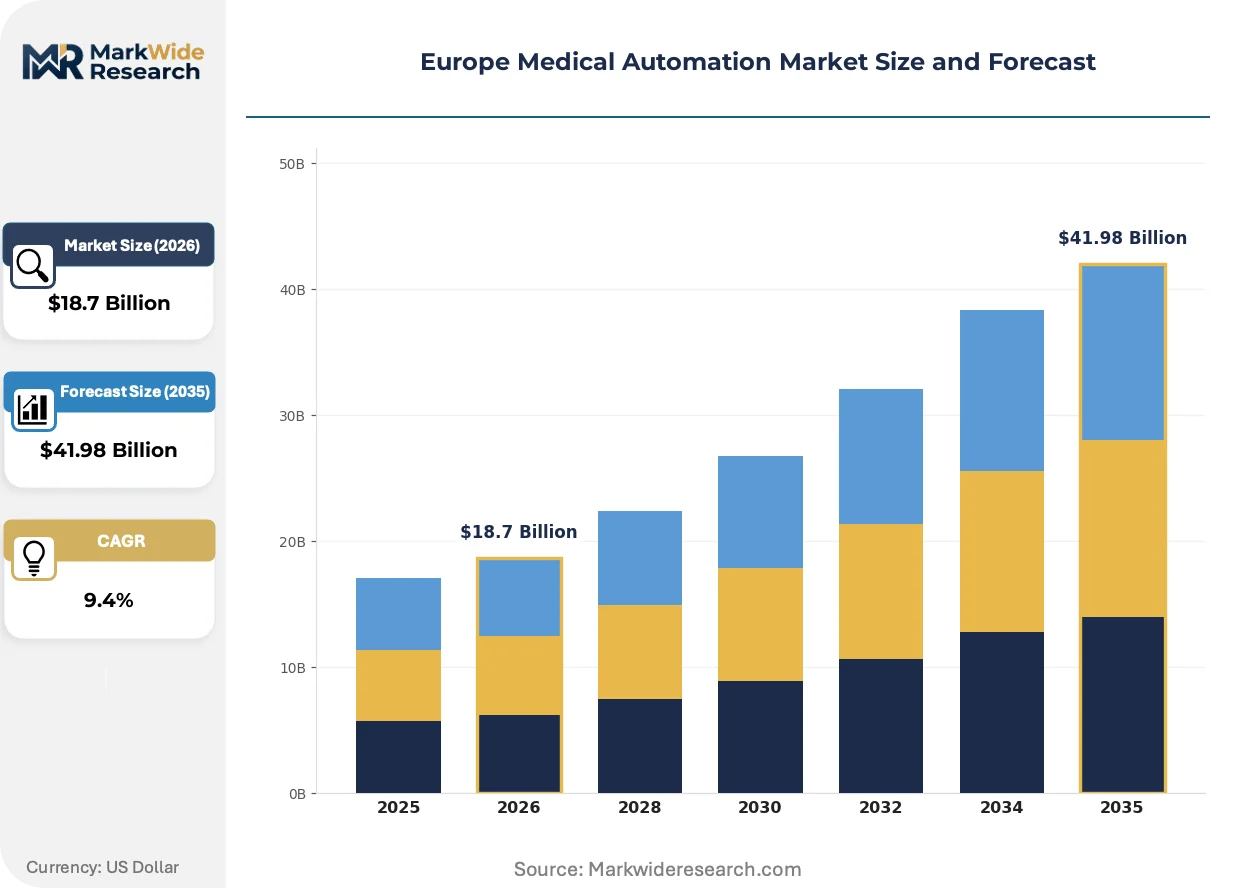
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgery Systems, Automated Medication Dispensing, Laboratory Automation, Workflow Automation Solutions End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Technology: Artificial Intelligence, Machine Learning, IoT Solutions, Cloud Computing Application: Surgical Automation, Patient Monitoring, Data Management, Process Optimization |
| Companies Covered | Siemens Healthineers, Brainlab AG, Medtronic, Koninklijke Philips, GE Healthcare, Stryker Corporation, Intuitive Surgical, Omnicell, Thermo Fisher Scientific, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Automation Market Shifts & Advancements
Digital pathology and AI-augmented diagnostic imaging are compressing turnaround times for oncology and histopathology workflows, while regulatory pressure on algorithmic transparency accelerates vendor investment in explainable AI architectures.
Digital pathology platforms combining whole-slide imaging with convolutional neural networks are rewriting diagnostic throughput benchmarks in European cancer centers. Pathology departments at University Hospital Heidelberg and Gustave Roussy Institute are deploying these systems for routine immunohistochemistry screening. The technology is rewriting staffing models by enabling centralized remote diagnosis across multi-site hospital networks.
The EU AI Act's high-risk system classification for clinical decision-support algorithms imposes mandatory conformity assessments before CE marking. Vendors must now document training data provenance and algorithmic performance across demographic subgroups. France's ANSM and Germany's BfArM are issuing supplementary guidance on post-market algorithmic drift monitoring that affects radiology and pathology AI deployments most acutely.
French public hospital tenders are bundling automation hardware with long-term service contracts that unbundle capital expenditure from operational budgets. University hospital consortia in Lyon and Marseille are piloting pay-per-procedure models for robotic surgery platforms. This shift is most visible in oncology and cardiovascular service lines where procedure volumes justify outcome-based vendor commitments.
Europe Medical Automation Market Segmentation
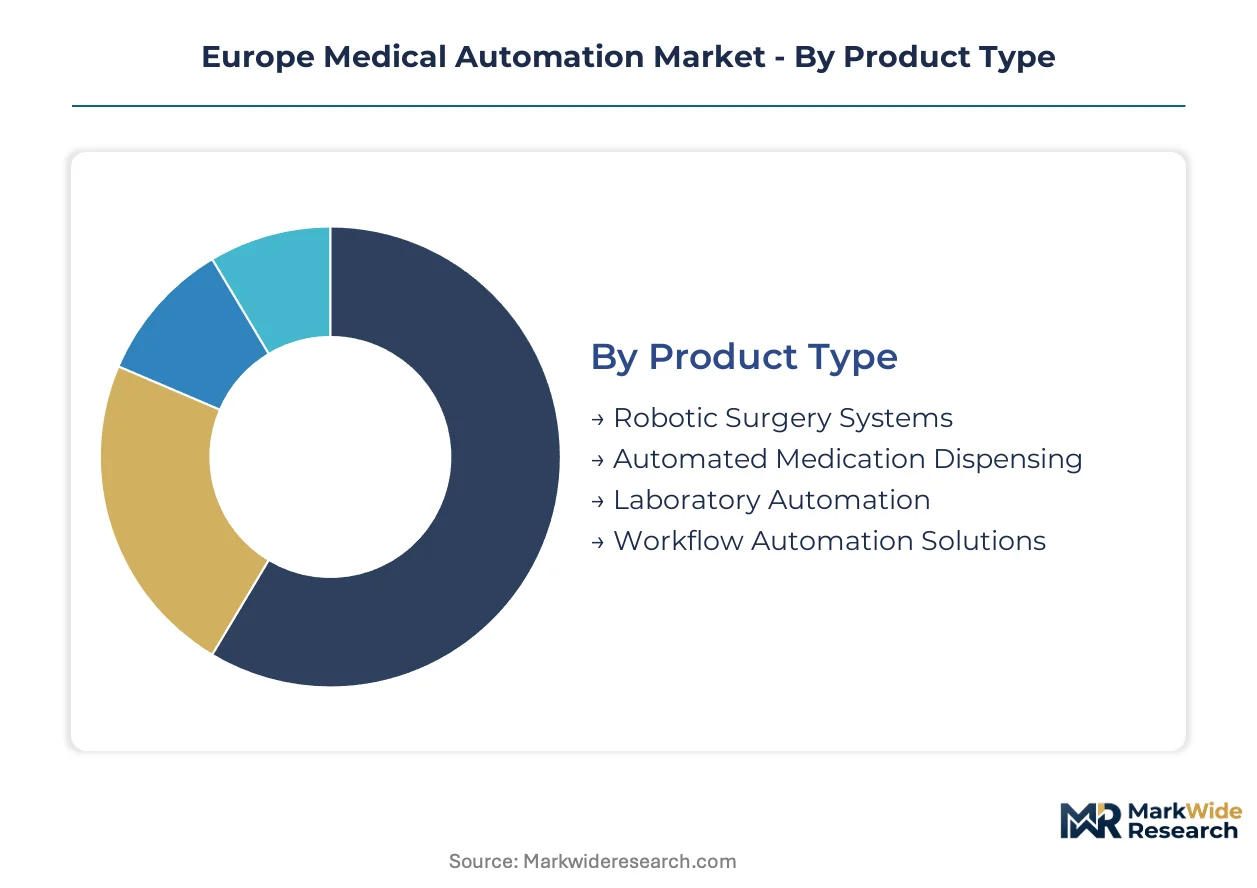
Segmentation reveals how procurement priorities diverge across European healthcare systems. Hospitals prioritize capital-intensive robotic platforms while diagnostic laboratories drive automation hardware volumes through consumables and service contracts.
Product Type:
Procurement committees weigh upfront capital against recurring revenue potential when selecting automation platforms.
- Robotic Surgery Systems:Electromechanical platforms with haptic feedback and imaging integration enable minimally invasive procedures with sub-millimeter precision. German university hospitals are expanding installed bases as surgical backlogs intensify staffing pressures. Da Vinci and Versius systems generate substantial recurring revenue from instrument sterilization protocols and preventive maintenance contracts.
- Laboratory Automation:Pre-analytical and analytical workstations automate sample handling, centrifugation, and aliquoting with throughput exceeding manual processing by an order of magnitude. French and German diagnostic laboratories face acute technologist shortages while personalized medicine protocols multiply test volumes. Liquid handling robots and track-based specimen transport systems command the steepest expansion trajectory in this category.
- Automated Medication Dispensing:Cabinet-based storage with barcode verification and inventory tracking reduces dispensing errors in high-volume pharmacy operations.
- Workflow Automation Solutions:Software-controlled patient routing and resource allocation platforms integrate with hospital information systems to optimize bed management and surgical scheduling.
Robotic surgery systems lead on scale; laboratory automation leads on momentum.
End User:
Budget authority and care delivery models shape automation adoption patterns across European provider types.
- Hospitals:Acute care facilities with centralized procurement functions deploy multi-modal automation across surgical, diagnostic, and operational domains. French public hospital networks specify AI-integrated workflow platforms in consolidated tenders covering multiple sites.
- Diagnostic Laboratories:High-throughput reference labs and hospital-based pathology departments drive demand for pre-analytical automation and digital pathology platforms. University Hospital Heidelberg and Gustave Roussy Institute deploy whole-slide imaging with convolutional neural networks for routine screening.
- Clinics:Ambulatory surgical centers and specialty practices adopt point-of-care automation for limited procedure volumes.
- Research Institutions:Academic medical centers and translational research facilities procure automation for clinical trial specimen processing and biomarker discovery workflows.
Hospital networks concentrate procurement authority; diagnostic laboratories are expanding most quickly.
Technology:
Regulatory classification under the EU AI Act determines validation burdens and time-to-market for algorithmic platforms.
- Artificial Intelligence:Clinical decision-support algorithms for radiology and pathology face mandatory conformity assessments as high-risk systems under EU AI Act harmonized standards. France's ANSM and Germany's BfArM issue supplementary guidance on post-market algorithmic drift monitoring.
- Machine Learning:Supervised learning models trained on curated datasets enable predictive analytics for patient deterioration and resource allocation. Vendors must document training data provenance and performance across demographic subgroups.
- IoT Solutions:Networked sensors and connected devices enable real-time equipment monitoring and predictive maintenance in distributed hospital networks.
- Cloud Computing:Subscription-based software delivery reduces capital barriers for mid-sized clinics in Spain and Italy while centralizing data aggregation for population health analytics.
Artificial intelligence leads on strategic priority; cloud computing leads on accessibility expansion.
Application:
Clinical outcome metrics and operational efficiency targets determine automation investment sequencing.
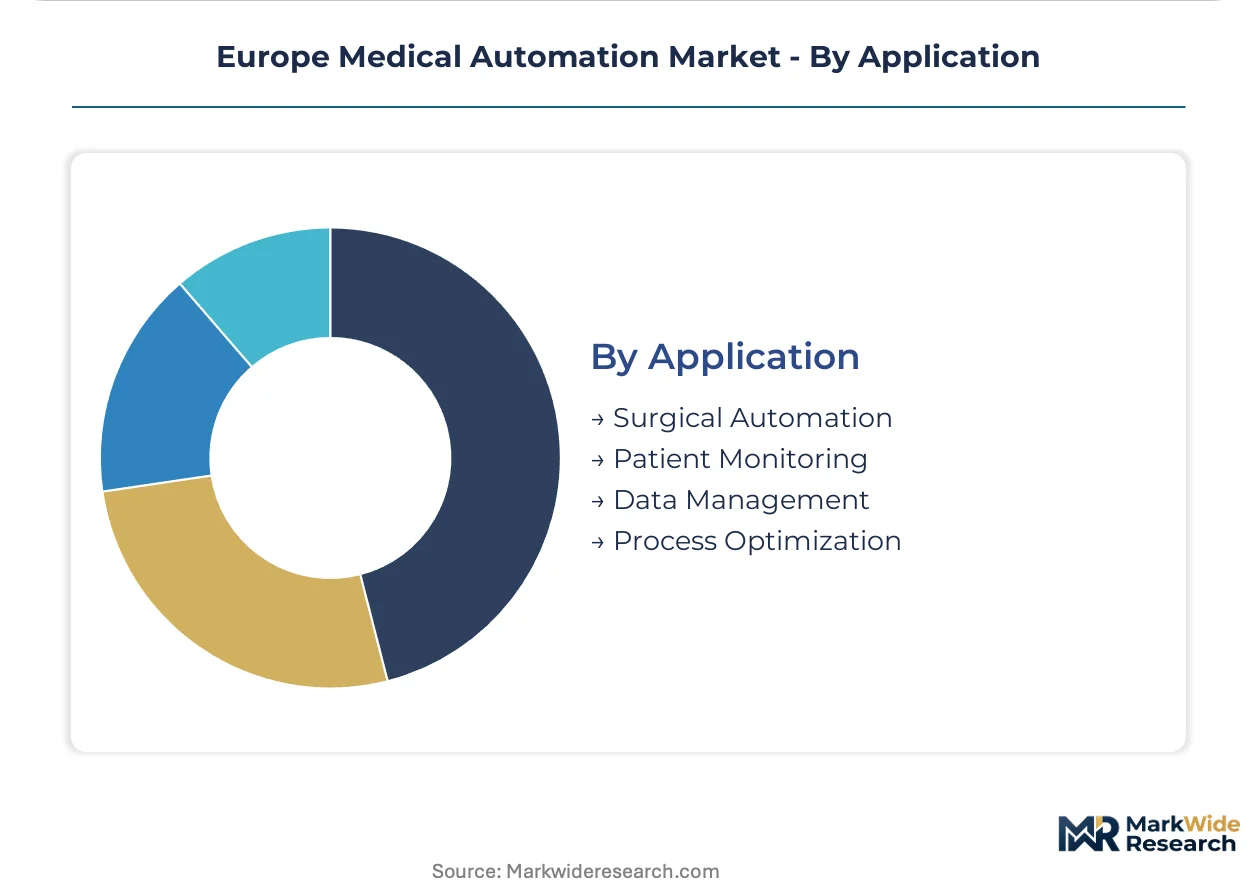
- Surgical Automation:Robotic platforms with instrument tracking and procedure logging support quality assurance and training credentialing. French university hospital consortia pilot pay-per-procedure models that unbundle capital expenditure from operational budgets.
- Patient Monitoring:Automated surveillance with early warning scoring reduces intensive care admissions through timely intervention. Philips and Siemens bridge acute care automation with remote patient monitoring for chronic disease management.
- Data Management:Interoperability platforms aggregate fragmented electronic health records for clinical decision support and regulatory reporting.
- Process Optimization:Lean manufacturing principles applied to patient flow reduce length-of-stay and emergency department boarding times.
Surgical automation commands capital allocation; patient monitoring gains share fastest through home-to-hospital convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors European medical automation demand through its dense concentration of university hospitals and diagnostic laboratory networks. Procurement committees across the continent are consolidating vendor relationships around CE-marked platforms that satisfy the EU Medical Device Regulation's tightened conformity timelines. National health technology assessment bodies in France, Germany, and the Netherlands are synchronizing reimbursement criteria for AI-integrated diagnostic systems.
Germany
German university hospitals in Heidelberg, Munich, and Berlin are expanding robotic surgery installations as surgical backlogs intensify staffing pressures. The BfArM enforces national vigilance reporting timelines that shape product launch sequencing for AI-based diagnostic algorithms. The Baden-Württemberg cluster around Stuttgart and Tübingen concentrates pre-clinical validation partnerships between automation vendors and Fraunhofer research institutes.
France
French public hospital networks specify AI-integrated workflow platforms in consolidated tenders covering multiple sites in Lyon, Marseille, and Paris. The ANSM issues supplementary guidance on post-market algorithmic drift monitoring that affects radiology and pathology AI deployments. The Gustave Roussy Institute in Villejuif deploys whole-slide imaging with convolutional neural networks for routine immunohistochemistry screening.
United Kingdom
NHS England's imaging networks are centralizing digital pathology procurement across regional cancer alliances in London, Manchester, and Birmingham. The Medicines and Healthcare products Regulatory Agency aligns with EMA guidance on software-as-a-medical-device validation requirements. The Cambridge-Oxford-London golden triangle concentrates venture capital flows into clinical decision-support startups.
Netherlands
Dutch hospital networks in the Randstad region prioritize interoperability certification when selecting automation platforms for laboratory and pharmacy operations. The Health and Youth Care Inspectorate enforces post-market surveillance obligations that parallel EU MDR mandates. The Eindhoven Brainport cluster supplies specialized sensor components to surgical robotics manufacturers.
Switzerland
Swiss university hospitals in Zurich, Geneva, and Basel maintain premium procurement budgets for robotic surgery systems with haptic feedback capabilities. Swissmedic maintains autonomous regulatory pathways for medical devices that exceed EU MDR baseline requirements in certain conformity assessment categories. The Basel pharmaceutical corridor drives demand for automated clinical trial specimen processing platforms.
Europe Medical Automation Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure and regulatory navigation capabilities. The vendor base stratifies into three tiers: diversified healthcare conglomerates with in-house manufacturing, specialized automation pure-plays with targeted clinical applications, and emerging software-native platforms with cloud-based delivery models. Dominant competitive moves include strategic partnerships with university hospitals for clinical validation data and portfolio diversification into adjacent diagnostic workflows.
Within the diversified healthcare conglomerate tier, Siemens Healthineers, Medtronic, and Koninklijke Philips occupy positions defined by vertical integration depth and European distribution reach. Siemens Healthineers exemplifies the imaging-integrated surgical robotics archetype through its in-house manufacturing capabilities. Medtronic leverages its Dublin-based European infrastructure to anchor minimally invasive platform distribution. Koninklijke Philips represents the patient monitoring convergence archetype, bridging acute care automation with remote chronic disease management.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Brainlab AG |
| Medtronic |
| Koninklijke Philips |
| GE Healthcare |
| Stryker Corporation |
| Intuitive Surgical |
| Omnicell |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
EU MDR sustainability mandates for device lifecycle traceability gate qualified supply access and premium-tier pricing for vendors demonstrating full conformity documentation. French and German hospital procurement committees now weight total cost of ownership calculations that embed circular economy compliance premiums into vendor selection criteria.
Pricing Analysis
Input-cost pass-through from specialized semiconductor sensors and precision electromechanical components shapes pricing structures across robotic surgery and diagnostic automation tiers. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked AI-integrated platforms from legacy hardware and refurbished installations. Price differentiation hinges on MDR certification tier and bundled service contract duration. Cost compression in standard-tier laboratory automation is intensifying because notified body bottlenecks stretch validation timelines for mid-tier vendors. Mid-sized clinics in Spain and Italy exhibit highest price sensitivity, while German university hospitals prioritize performance specifications over capital expenditure constraints.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Frankfurt, and Milan operate hub-and-spoke patterns for spare parts and consumables serving hospital networks within 24-hour response windows. Manufacturing concentration centers on Germany, Switzerland, and the Netherlands for surgical robotics assembly, while specialized sensor chips draw from Taiwan and South Korea foundry capacity. Raw material dependencies include rare earth magnets for robotic actuators, high-purity optical glass for imaging systems, and medical-grade stainless steel for surgical instruments. Single-source vulnerability in East Asian semiconductor supply creates procurement contingency planning requirements for European automation vendors. Distribution runs through authorized service partnerships that lock hospitals into proprietary maintenance ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification functions as a regulatory compounder, accelerating replacement cycles for legacy diagnostic software lacking algorithmic transparency documentation.
For Market Incumbents: Anticipate margin compression from cloud-native workflow platforms by deepening in-house production of imaging-integrated surgical robotics and securing exclusive service contracts with French university hospital consortia. Lock in notified body capacity through multi-year conformity assessment retainers to defend CE marking timelines against emerging software-native competitors.
For New Entrants and Emerging Players: Capture underpenetrated robotic surgery demand in Polish and Romanian hospital networks where Western European penetration benchmarks have not yet transferred. Prioritize subscription licensing models for mid-sized Italian and Spanish clinics capital-constrained by public budget cycles. Lead with interoperability certification against proprietary incumbent data formats.
For Investors and Strategic Acquirers: Valuations sit cheapest among laboratory automation pure-plays with consumables-recurring revenue models and established track-based specimen transport installations. Long-term viability over the next decade hinges on MDR transition completion and EU AI Act compliance infrastructure. Monitor algorithmic drift monitoring guidance issuance from France's ANSM and Germany's BfArM as inflection indicators for regulatory-driven consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR conformity assessment acceleration compresses product launch windows for AI-diagnostic vendors. |
| Hospital System Partnership | French public tender consolidation favors vendors with multi-site workflow platform deployments. |
| Software Companion Development | Cloud-native patient routing modules reduce capital barriers for mid-sized clinic penetration. |
| Reimbursement Strategy | Alignment with national health technology assessment bodies in Germany and Netherlands determines market access. |
| Backward Integration | In-house sensor component production mitigates East Asian semiconductor supply concentration risk. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Nordic markets, with primary inputs from each regional cluster combined with secondary validation. Interviews with hospital procurement managers, biomedical engineering directors, regulatory affairs leads at automation vendors, and GPO contracts managers informed demand-side and supply-side perspectives. Secondary sources include EMA guidance documents, EU MDR harmonized standards databases, hospital procurement tender records, and notified body conformity assessment disclosures. Bottom-up installed base modeling triangulates against top-down healthcare expenditure allocation estimates.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology tier, and clinical application, with additional granularity on MDR risk classification and AI Act system categorization. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns and regulatory milestone impacts. Forecast inputs incorporate notified body capacity constraints and personalized medicine test volume trajectories.
Regulatory timeline delays, semiconductor supply disruptions, and hospital capital budget freezes are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions on MDR implementation pace and AI Act harmonized standard adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Medical Tubing Market
Medical Equipment
Electric Bed Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Global Microtome Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Benchtop Platelet Agitator Market