
 Global Steam Autoclaves Market | 2026-2036
Global Steam Autoclaves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Steam Autoclaves Market Foresight
Hospital procurement consolidation is rebalancing contract volumes toward group purchasing organizations and multi-facility networks. Steris Corporation leverages its installed base of sterilization equipment to sustain recurring service revenues across North American health systems. Getinge Group anchors European supply through its dominance in large-capacity horizontal autoclaves for central sterile services departments. Tuttnauer Co. Ltd. competes aggressively in the mid-market tabletop segment where price sensitivity shapes vendor selection.
Steam autoclaves are pressure vessels that use saturated steam at temperatures typically ranging from 121°C to 134°C to achieve microbial inactivation through protein denaturation and enzyme destruction. These systems serve as the backbone of sterile processing in healthcare, pharmaceutical manufacturing, and research environments where validated kill assurance is mandatory. Horizontal autoclaves occupy the largest value share due to throughput requirements in high-volume hospital central sterile departments, while pre-vacuum technology segments command premium positioning where air removal efficiency determines cycle validation outcomes. Tabletop autoclaves represent the fastest-expanding product category as point-of-use sterilization migrates into outpatient surgical centers and dental clinics seeking workflow autonomy.
The FDA enforces sterilization process validation under 21 CFR Part 820 quality system regulations, while the EU MDR requires updated technical documentation and conformity assessment for legacy autoclave installations across European member states. ISO 17665 provides the international reference for moist heat sterilization development, validation, and routine control that manufacturers must integrate into equipment design and commissioning protocols. Stakeholders should monitor how evolving sustainability mandates from the EU Green Deal reshape steam generation efficiency requirements and material specifications for pressure vessel construction.
Market Dynamics
Hospital consolidation into multi-facility networks is compressing vendor relationships and forcing autoclave manufacturers to restructure service architectures around centralized procurement platforms rather than individual facility sales cycles.
Growth Catalysts
- EU MDR conformity deadlines:Legacy equipment replacement cycles across German, French, and Italian health systems are accelerating capital expenditure on validated sterilization platforms that meet updated technical documentation requirements.
- Pharmaceutical manufacturing expansion:Sterile injectable production lines in the United States and Japan require additional large-capacity pre-vacuum autoclaves to support biologics fill-finish operations.
- Outpatient surgical migration:Ambulatory surgery centers and dental clinics in Brazil and Mexico are installing tabletop autoclaves to achieve point-of-use sterilization autonomy without central sterile department dependency.
Market Restraints
- Stainless steel price volatility:Pressure vessel construction costs fluctuate with nickel and chromium input markets, squeezing margins for mid-capacity autoclave producers.
- Regional supply concentration:Critical vacuum pump and control system component manufacturing clusters in Germany and Japan create single-source vulnerability for non-integrated assemblers.
- Ethylene oxide residual limits:FDA enforcement of reduced EtO exposure thresholds in medical device sterilization is not directly substitutable with steam, limiting autoclave applicability for heat-sensitive polymers.
Strategic Opportunities
- India hospital infrastructure:Government health scheme expansion into tier-2 and tier-3 cities under Ayushman Bharat is generating first-time demand for affordable horizontal autoclaves in state-run medical colleges.
- EU Green Deal thermal efficiency mandates:Steam generator redesign requirements are creating openings for heat-recovery and condensate-return technologies that reduce energy intensity per sterilization cycle.
- Remote monitoring convergence:Integration of IoT sensors with predictive maintenance algorithms is enabling outcome-based service contracts that lock in multi-year revenue streams.
Industry Challenges
- Validation engineering scarcity:Qualified professionals capable of executing IQ/OQ/PQ protocols per ISO 17665 are concentrated in Western Europe and North America, creating commissioning bottlenecks in emerging markets.
- Legacy system integration:Hospital information system connectivity requirements for electronic batch records demand middleware development that stretches delivery timelines and inflates project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Steam Autoclaves Market |
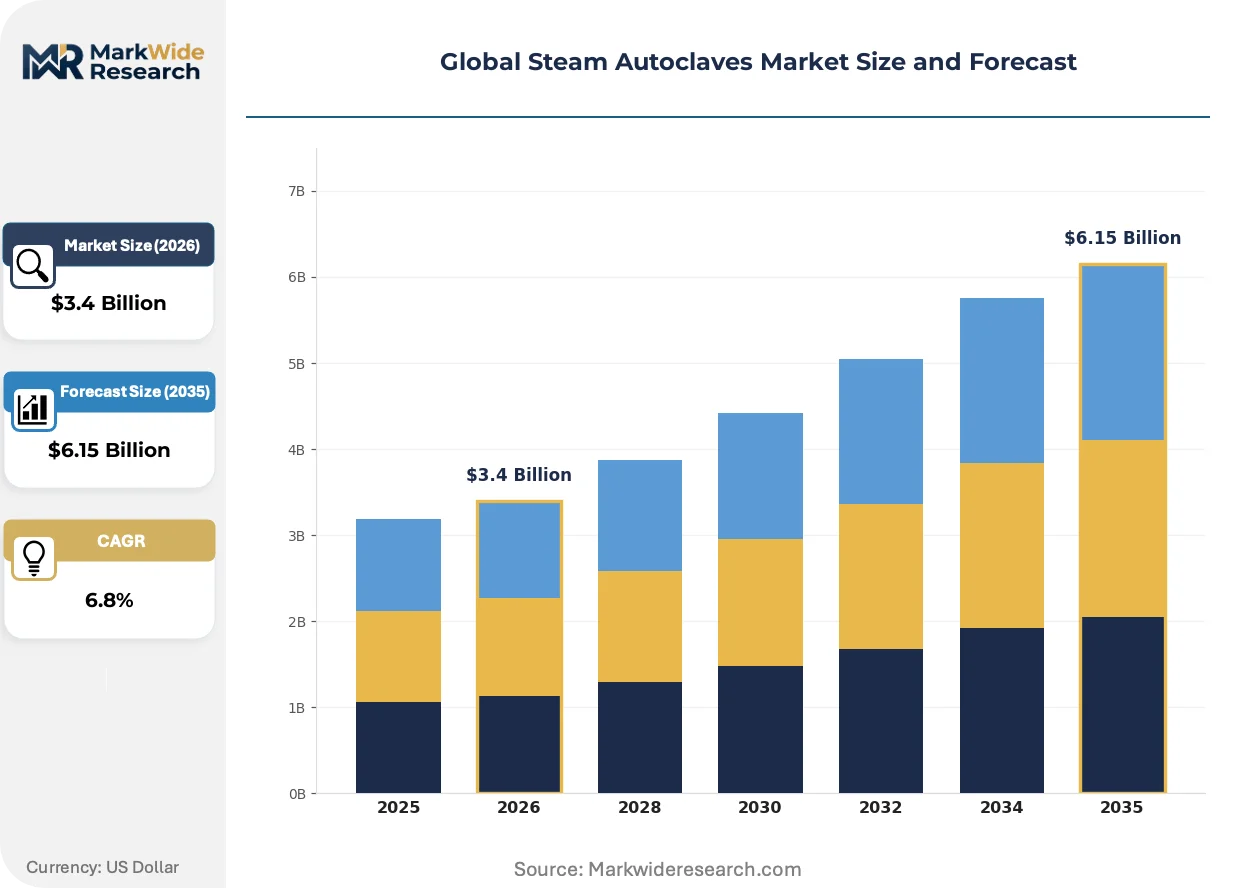
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Autoclaves, Horizontal Autoclaves, Tabletop Autoclaves, Portable Autoclaves, Batch Sterilizers Technology: Gravity Displacement, Pre-Vacuum, Steam-Flush Pressure Pulse, Liquid Cycle, Vacuum Assisted Application: Medical Instrument Sterilization, Laboratory Equipment Sterilization, Pharmaceutical Processing, Food & Beverage Sterilization, Textile Treatment End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Food Processing Plants, Veterinary Clinics |
| Companies Covered | Tuttnauer Co. Ltd., Astell Scientific Ltd., Steris Corporation, Priorclave Ltd., LTE Scientific Ltd., Getinge Group, Matachana, MELAG Medizintechnik GmbH & Co. KG, Belimed GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Steam Autoclaves Market Shifts & Advancements
Steam autoclave architecture is undergoing fundamental redesign as energy efficiency mandates intersect with digitalization requirements and point-of-care workflow autonomy demands.
Superheated steam injection systems are absorbing the performance gap between conventional saturated steam cycles and rapid sterilization requirements in emergency surgical workflows. University hospital networks in Germany and Switzerland are piloting these platforms to compress turnaround times for critical instrument sets. The technology is absorbing volume that previously required redundant autoclave installations, reducing capital footprints in constrained central sterile department layouts.
EU MDR technical documentation updates are forcing manufacturers to revalidate legacy pressure vessel designs under notified body supervision. Equipment suppliers must submit updated conformity assessments for existing installed bases across French and Italian health systems. Large-capacity horizontal autoclaves with pre-2007 pressure equipment directives face the steepest compliance burden, accelerating replacement decisions in centralized sterilization departments.
Group purchasing organization consolidation is compressing vendor negotiation leverage and standardizing equipment specifications across multi-hospital networks. Catholic health systems and for-profit chains in the United States are mandating unified preventive maintenance contracts that bundle autoclave service with washer-disinfector coverage. This pattern is most visible in Texas and Florida metropolitan markets where three GPOs control the majority of acute care procurement spend.
Global Steam Autoclaves Market Segmentation
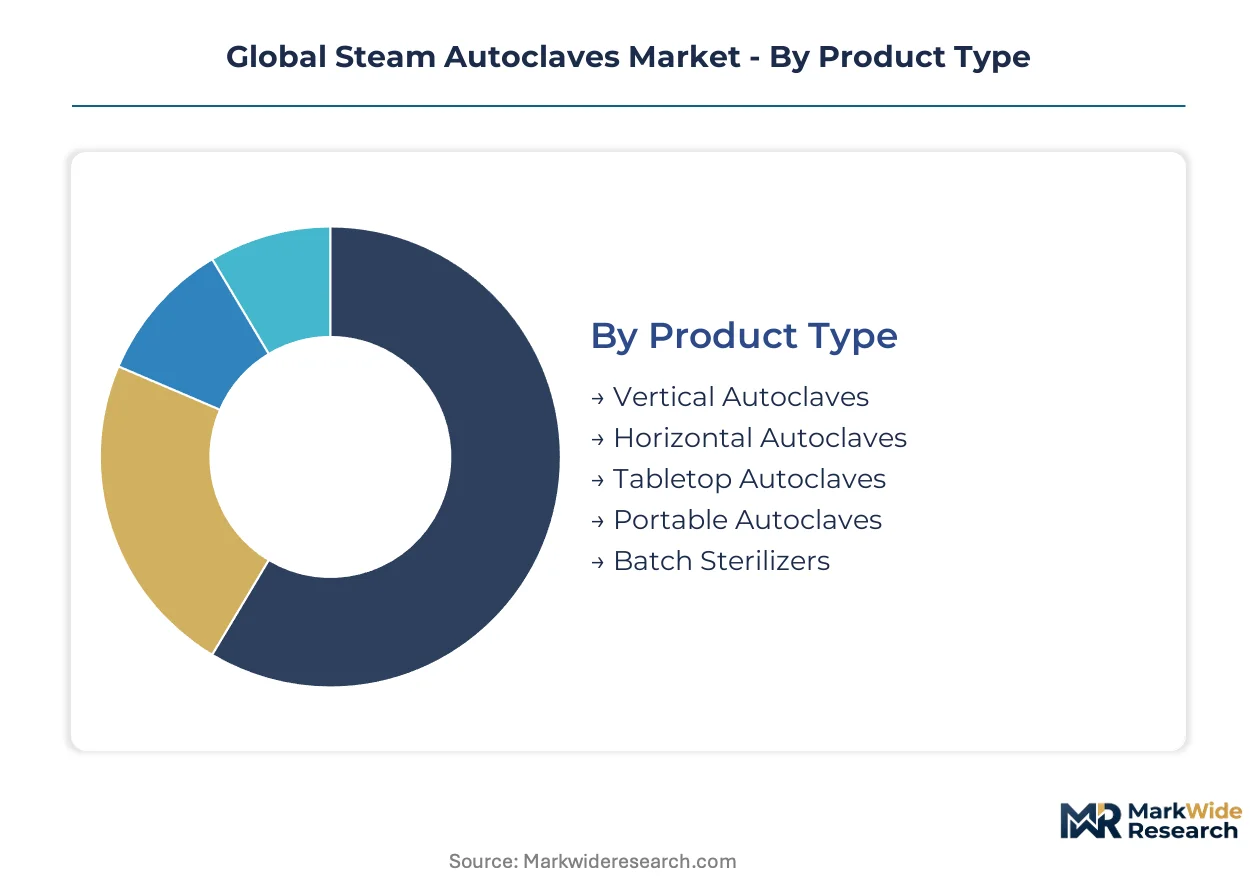
Steam autoclave purchasing decisions pivot on throughput requirements, validation protocols, and physical footprint constraints. Procurement committees evaluate total cost of ownership across sterilization cycles, maintenance intervals, and energy consumption rather than upfront capital expenditure alone.
Product Type:
Facility throughput and space constraints determine which vessel geometry delivers optimal sterilization economics.
- Horizontal Autoclaves:These front-loading pressure vessels accommodate high-density instrument sets on rolling carts for central sterile departments. German university hospitals and Japanese general hospitals are expanding installed bases to handle rising surgical volumes under consolidated procurement contracts.
- Tabletop Autoclaves:Compact countertop units deploy saturated steam chambers under 100 liters for immediate-use sterilization. Outpatient surgical centers in Brazil and dental clinics in Mexico are absorbing volume fastest as point-of-care autonomy displaces central sterile dependency.
- Vertical Autoclaves:Top-loading cylindrical chambers suit laboratories and small clinics with moderate throughput needs and floor space limitations.
- Portable Autoclaves:Mobile units with independent steam generation serve field hospitals, military medical units, and disaster response scenarios requiring rapid deployment.
- Batch Sterilizers:Large rectangular chambers process palletized loads for pharmaceutical manufacturing and industrial-scale sterilization operations.
Horizontal autoclaves lead on scale; tabletop autoclaves lead on momentum.
Technology:
Air removal efficiency separates validated kill assurance from compliance risk in regulatory inspections.
- Pre-Vacuum:Multiple vacuum pulses evacuate air from porous loads before steam penetration, achieving faster cycle times and deeper penetration into wrapped instrument sets. FDA 510(k) submissions for pre-vacuum platforms dominate new equipment approvals as hospitals replace gravity-displacement legacy units.
- Gravity Displacement:Steam enters from above and displaces air downward through a vent, suitable for unwrapped solid instruments with simple geometries. Cost-sensitive facilities in India and Southeast Asia retain this technology where validation budgets constrain capital planning.
- Steam-Flush Pressure Pulse:Alternating steam injection and pressure pulses remove air without deep vacuum, balancing speed with reduced pump maintenance for mid-tier hospitals.
- Liquid Cycle:Controlled heating and cooling profiles prevent boil-over in media and solution sterilization for research laboratories.
- Vacuum Assisted:Hybrid approaches combine partial vacuum with gravity displacement for mixed-load processing in multi-purpose facilities.
Pre-vacuum technology commands the premium tier; gravity displacement retains the volume base.
Application:
Load characteristics dictate cycle parameter selection and validation documentation requirements.
- Medical Instrument Sterilization:Surgical instrument sets, implantable devices, and flexible endoscopes require validated moist heat cycles under ISO 17665. Central sterile departments in U.S. health systems and European hospitals drive replacement demand as EU MDR technical documentation deadlines approach.
- Pharmaceutical Processing:Sterile injectable manufacturing, aseptic fill-finish operations, and biologics production demand large-capacity pre-vacuum autoclaves with electronic batch record integration. Expansion in Massachusetts and North Carolina biotech corridors is absorbing specialized equipment with isolator interfaces.
- Laboratory Equipment Sterilization:Glassware, media, and waste decontamination in research facilities require programmable cycle flexibility for diverse load types.
- Food & Beverage Sterilization:Retort processing and container sterilization for shelf-stable products apply steam autoclave principles at industrial scale.
- Textile Treatment:Surgical gown and drape sterilization in centralized laundries employs large horizontal chambers with specialized textile cycles.
Medical instrument sterilization anchors revenue concentration; pharmaceutical processing shows the steepest expansion trajectory.
End User:
Capital allocation authority and reimbursement models shape equipment specification and service contract structures.
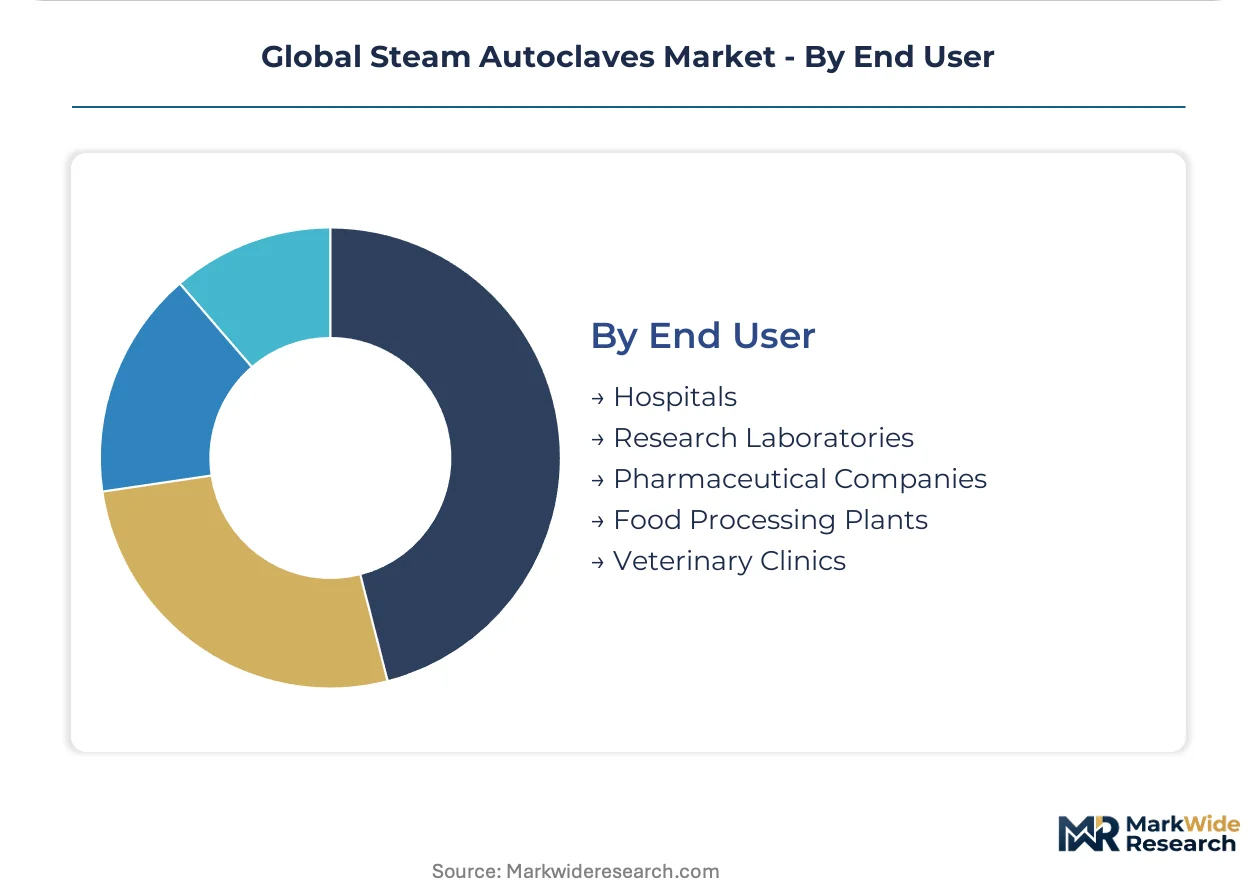
- Hospitals:Acute care facilities with centralized sterile departments purchase large horizontal autoclaves through group purchasing organizations. Catholic health systems and for-profit chains in Texas and Florida are bundling preventive maintenance contracts across washer-disinfector and autoclave portfolios.
- Pharmaceutical Companies:Sterile manufacturing operations require validated equipment with IQ/OQ/PQ documentation for regulatory submissions. FDA inspection readiness drives specification rigor in New Jersey and California manufacturing clusters.
- Research Laboratories:Academic and commercial R&D facilities prioritize cycle flexibility and compact footprints over throughput maximization.
- Food Processing Plants:Commercial sterilization operations apply steam autoclave technology to packaged food safety and shelf-life extension.
- Veterinary Clinics:Small animal practices and equine hospitals deploy tabletop units for surgical instrument sterilization with lower regulatory documentation burdens.
Hospitals dominate absolute spend; pharmaceutical companies set the specification ceiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Validation engineers and sterile processing technicians concentrate in German, American, and Japanese healthcare systems, anchoring equipment procurement expertise and service infrastructure density in these markets.
United States
Group purchasing organizations in Texas and Florida metropolitan markets bundle autoclave procurement with washer-disinfector service contracts across Catholic health systems and for-profit chains. FDA enforcement of 21 CFR Part 820 quality system regulations drives replacement of gravity-displacement units with pre-vacuum platforms in acute care facilities. Massachusetts and North Carolina biotech corridors absorb specialized large-capacity autoclaves for sterile injectable manufacturing.
Germany
University hospital networks in Bavaria and Baden-Württemberg pilot superheated steam injection systems to compress surgical instrument turnaround times. EU MDR technical documentation deadlines force revalidation of legacy pressure vessel designs under notified body supervision, accelerating capital expenditure in centralized sterilization departments. Eindhoven-based vacuum pump suppliers create component sourcing concentration for domestic assemblers.
Japan
General hospitals in Tokyo and Osaka expand installed bases of horizontal autoclaves to handle rising surgical volumes under consolidated procurement frameworks. PMDA alignment with ISO 17665 moist heat sterilization standards shapes equipment qualification protocols for pharmaceutical manufacturers. METI industrial policy supports domestic control system fabrication clusters around Nagoya.
India
State-run medical colleges in Maharashtra and Karnataka generate first-time demand for affordable horizontal autoclaves under Ayushman Bharat health scheme expansion. CDSCO medical device regulations tighten validation requirements for imported equipment, favoring domestic assembly partnerships. Cost-sensitive facilities retain gravity-displacement technology where capital budgets constrain pre-vacuum adoption.
Brazil
Ambulatory surgery centers in São Paulo and Rio de Janeiro install tabletop autoclaves to achieve point-of-use sterilization autonomy. ANVISA medical device conformity assessment procedures extend commissioning timelines for European and American imports. Dental clinic chains in southeastern states drive fastest volume expansion in compact countertop segments.
Global Steam Autoclaves Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: large-scale sterilization platform providers with integrated service networks, mid-market tabletop specialists competing on price accessibility, and regional fabricators serving localized validation requirements. M&A activity concentrates service capabilities into multi-product preventive maintenance contracts, while technology licensing agreements accelerate IoT sensor integration for predictive maintenance offerings.
Among diversified platform providers, Steris Corporation and Getinge Group exemplify the integrated service network archetype, anchoring recurring revenue streams through installed base coverage. Tuttnauer Co. Ltd. occupies a position within the mid-market tabletop specialization tier. MELAG Medizintechnik GmbH & Co. KG represents German-engineered precision positioning in premium clinical segments. Priorclave Ltd., LTE Scientific Ltd., and Astell Scientific Ltd. sit within the UK-based laboratory and research equipment fabrication cluster.
| Leading Market Players |
|---|
| Tuttnauer Co. Ltd. |
| Astell Scientific Ltd. |
| Steris Corporation |
| Priorclave Ltd. |
| LTE Scientific Ltd. |
| Getinge Group |
| Matachana |
| MELAG Medizintechnik GmbH & Co. KG |
| Belimed GmbH |
| Others |
Supply & Pricing Matrix
Nickel and chromium alloy costs cascade from commodity exchanges through pressure vessel fabricators into three distinct pricing tiers for end-users. Stainless steel price volatility in German and Japanese supply markets compresses margins for mid-capacity autoclave assemblers while premium pre-vacuum platforms absorb input fluctuations through long-term service bundling.
Pricing Analysis
Bundled preventive maintenance contracts versus unbundled equipment-only procurement splits the market into divergent value capture models. Steris Corporation and Getinge Group anchor the bundled tier, locking multi-year revenue through installed base service coverage, while Tuttnauer and regional tabletop specialists compete on accessible capital expenditure for price-sensitive outpatient clinics. Price differentiation hinges on FDA 510(k) validation tier and ISO 17665 documentation depth, with pharmaceutical manufacturers least sensitive and Indian state-run hospitals most sensitive to upfront cost. Cost compression in gravity-displacement segments intensifies as CDSCO regulations tighten import validation requirements, forcing domestic assembly partnerships that alter traditional margin structures.
Supply Chain Analysis
Single-source vulnerability sits with German vacuum pump manufacturers and Japanese control system fabricators, creating chokepoints for non-integrated assemblers sourcing from Eindhoven and Nagoya industrial clusters. Pressure vessel construction draws from Swedish and Finnish stainless steel mills, while precision instrumentation feeds from Swiss and German sensor specialists. Tariff exposure on European pressure equipment imports into Brazil and India extends commissioning timelines and inflates landed costs. Distribution runs through group purchasing organizations in Texas and Florida, direct hospital procurement in Germany, and government tender platforms in Maharashtra and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Steam Autoclaves Market functions as a geographic-arbitrage play where EU MDR compliance costs in French and Italian health systems create replacement demand that outpaces price-sensitive expansion in Indian tier-2 cities by a factor of three to one on margin contribution.
For Market Incumbents: Anticipate accelerated replacement cycles in German university hospitals by pre-positioning superheated steam injection platforms before EU MDR technical documentation deadlines harden procurement specifications. Defend service contract renewals through IoT-enabled predictive maintenance integration that raises switching costs for Catholic health systems in consolidated Texas and Florida networks. Vertical integration into vacuum pump supply buffers margin pressure from Eindhoven component concentration. For New Entrants and Emerging Players: Group purchasing organization partnerships offer the most penetrable channel for mid-market tabletop autoclaves targeting Brazilian ambulatory surgery centers and Mexican dental clinic chains. White-space concentration sits in affordable horizontal autoclaves for Indian state-run medical colleges under Ayushman Bharat infrastructure expansion, where CDSCO localization requirements favor domestic assembly joint ventures. Go-to-market positioning should emphasize point-of-use sterilization autonomy messaging over central sterile department dependency reduction. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with captive validation engineering capabilities because ISO 17665 IQ/OQ/PQ protocol execution scarcity concentrates in Western Europe and North America, creating pricing power in emerging market commissioning. Long-term viability favors platforms with installed base density in pharmaceutical manufacturing corridors. Monitor FDA enforcement patterns on EtO residual limits as inflection signal for steam autoclave substitution elasticity in heat-sensitive polymer sterilization applications.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Integration | Enables predictive maintenance contracts that lock Steris and Getinge into multi-year hospital system relationships. |
| EU MDR Conformity Pathway | Forces revalidation of legacy Getinge and Belimed pressure vessels under notified body supervision in French health systems. |
| Domestic Assembly Partnership | Positions Tuttnauer and MELAG to meet CDSCO localization requirements for Indian state-run medical college tenders. |
| Superheated Steam Platform Launch | Compresses instrument turnaround times for German university hospitals piloting emergency surgical workflow acceleration. |
| Group Purchasing Organization Contract | Bundles autoclave and washer-disinfector coverage across Catholic health system networks in Texas metropolitan markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with central sterile department managers, biomedical engineers, GPO contracts managers, pharmaceutical manufacturing qualification leads, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EU MDR notified body assessments, hospital procurement databases, and ISO 17665 technical documentation. Bottom-up equipment shipment analysis and top-down healthcare capital expenditure triangulation anchored volume estimates.
Segment-weighting approaches distributed value across product type, technology tier, application vertical, and end-user category dimensions throughout the forecast period. CAGRs derived from regression analysis against surgical volume growth, pharmaceutical manufacturing capacity expansion, and regulatory replacement cycle timing. Model inputs incorporated PMDA alignment trajectories in Japan, Ayushman Bharat infrastructure buildout rates in India, and ANVISA conformity assessment processing durations in Brazil.
Revisions become necessary when EU Green Deal thermal efficiency mandates accelerate steam generator redesign requirements, stainless steel alloy markets experience sustained volatility, or FDA EtO enforcement shifts materially alter sterilization modality substitution patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Cell Washer Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Medical Physics Market
Medical Equipment
Centrifuge Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Electric Bed Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
Operating Light Market