
 Global Laboratory Grinders Market | 2026-2036
Global Laboratory Grinders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Grinders Market Foresight
Premium laboratory grinder specifications is decoupling from commodity-grade equipment as pharmaceutical and materials science clients demand validated traceability, automated particle-size reporting, and GMP-ready documentation. Retsch GmbH leverages its ISO 17025-aligned calibration services to anchor premium positioning in European research laboratories. NETZSCH Group competes through wet grinding specialization, sustaining dominance in nanomaterial preparation for battery research.
Laboratory grinders are precision size-reduction instruments engineered to process samples to micrometer or nanometer scales, with rotor speeds ranging from 3,000 to 20,000 RPM and temperature-controlled chambers preventing thermal degradation of sensitive compounds. Their primary purpose spans pharmaceutical dissolution testing, polymer characterization, and food allergen analysis where reproducible particle distribution determines regulatory compliance. Planetary grinder configurations command the steepest price premiums due to multi-station parallel processing and orbital motion mechanics that yield sub-micron fineness. Cryogenic grinder adoption accelerates fastest in biobanking and RNA extraction workflows where liquid nitrogen cooling preserves molecular integrity. Dry grinding technology retains the largest installed base across quality control labs, though margin pools are thinning as ultrasonic grinding displaces conventional blade methods in nanoparticle synthesis.
FDA 21 CFR Part 11 electronic records requirements shape software-enabled grinder demand in United States pharmaceutical labs, while REACH substance restriction lists in the European Union drive stainless-steel alloy certification and contaminant testing protocols. EMA's Annex 15 qualification standards and ISO 17025 calibration mandates collectively raise capital barriers for equipment vendors serving regulated industries. Stakeholders must weigh in-house particle analysis capability against outsourced contract testing relationships as grinder-as-a-service models emerge from specialized distributors.
Market Dynamics
Pharmaceutical dissolution testing protocols are compressing particle-size tolerance windows, forcing laboratories to retire legacy blade grinders in favor of validated planetary and cryogenic systems with ISO 17025 traceability.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in United States pharmaceutical labs are accelerating replacement cycles for software-enabled grinders with audit-trail capabilities.
- Battery research:Nanomaterial preparation for solid-state electrolyte development is pulling wet grinding capacity into materials science departments across Germany and Japan.
- RNA extraction workflows:Biobanking expansion in the United States and Switzerland is driving liquid nitrogen-cooled cryogenic grinder procurement for molecular integrity preservation.
Market Restraints
- Stainless-steel alloy certification:REACH substance restriction lists in the European Union are elevating raw material testing costs and supplier qualification timelines.
- Calibration service concentration:ISO 17025-accredited calibration providers cluster in Western Europe, creating service-access bottlenecks for Asia-Pacific laboratories.
- Ultrasonic grinding substitution:Non-contact particle synthesis methods are capturing nanoparticle research budgets that previously flowed to mechanical grinders.
Strategic Opportunities
- India's pharmaceutical corridor:CDSCO quality-control mandates are creating first-time demand for GMP-ready grinding systems in Hyderabad and Mumbai contract labs.
- Grinder-as-a-service models:Specialized distributors in Germany and the United States are unbundling capital expenditure into subscription-based equipment access with bundled validation.
- AI-enabled particle analysis:Convergence of automated imaging and grinding control software is opening premium pricing tiers for real-time fineness feedback systems.
Industry Challenges
- Cross-functional talent scarcity:Laboratories struggle to hire technicians fluent in both mechanical maintenance and GMP documentation protocols.
- Legacy system integration:Retrofitting electronic signature capture onto 10-15 year old grinder fleets demands custom software bridges that stretch validation timelines.
- EMA Annex 15 qualification:Equipment qualification documentation requirements are extending sales-to-revenue recognition cycles for vendors serving European pharma.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Grinders Market |
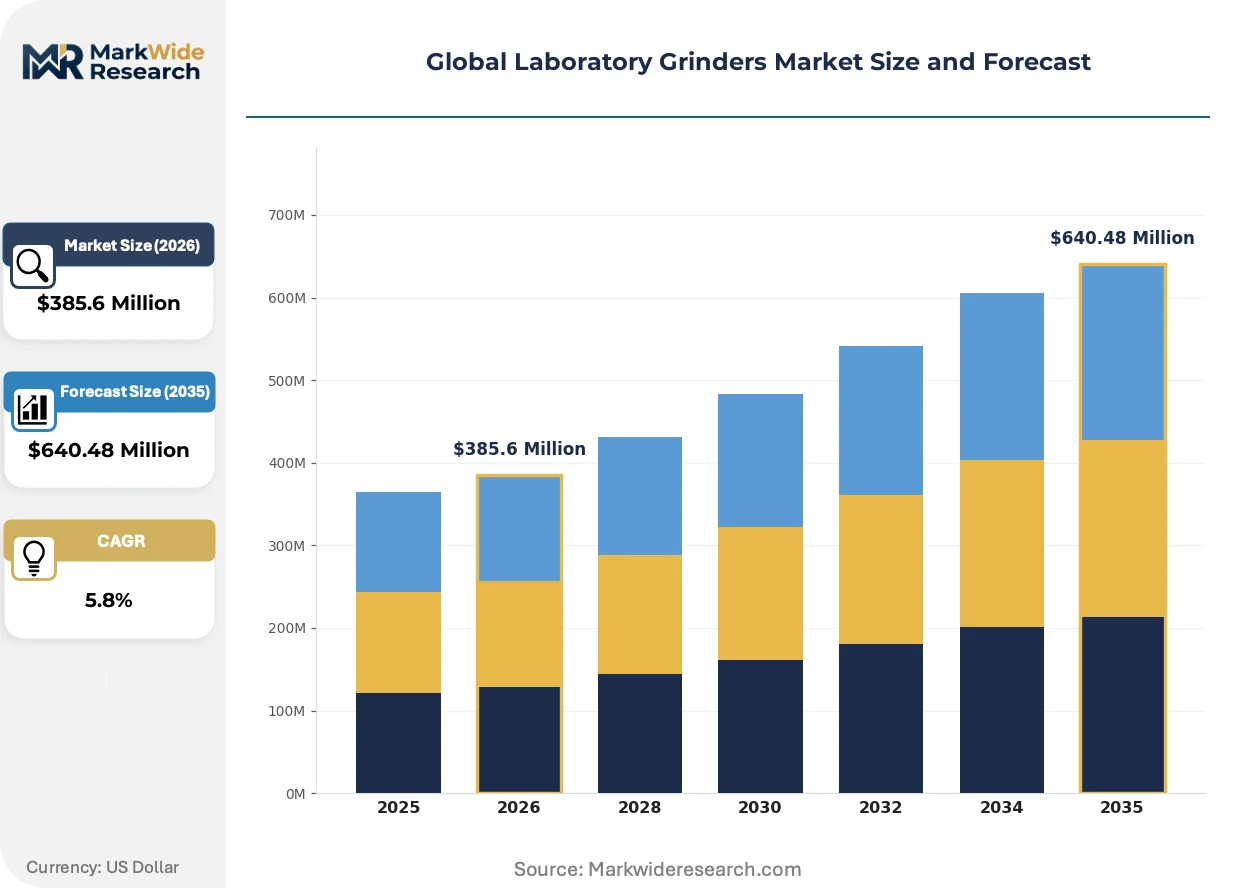
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Mill, Planetary Grinder, Mortar Grinder, Cryogenic Grinder, Hammer Mill Technology: Wet Grinding, Dry Grinding, Ultrasonic Grinding, Jet Milling, Vibratory Grinding Application: Pharmaceutical Testing, Chemical Analysis, Material Characterization, Food Processing, Soil Testing End User Industry: Research Laboratories, Academic Institutions, Quality Control Labs, Contract Testing Facilities |
| Companies Covered | Retsch GmbH, NETZSCH Group, Fritsch GmbH, IKA Werke GmbH & Co. KG, Buehler, GEA Group AG, Union Process, Spectris, MRC Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Grinders Market Shifts & Advancements
Automation and regulatory digitization are compressing the gap between grinding operation and compliance documentation, while service models decouple equipment ownership from analytical capability.
Ultrasonic grinding is overtaking conventional blade methods in nanoparticle synthesis workflows. Battery research facilities in Germany and Japan are adopting non-contact cavitation systems for sub-100 nanometer particle production without thermal degradation. This shift is compressing margin pools for mechanical grinder vendors serving materials science segments.
REACH substance restriction lists are forcing stainless-steel alloy requalification across European supply chains. ECHA documentation requirements now extend to contaminant testing protocols for all contact surfaces in pharmaceutical-grade equipment. German and Swiss manufacturers are responding by vertically integrating metallurgical certification to preserve market access.
Service unbundling is fragmenting traditional capital equipment relationships. Contract laboratories in Boston and San Diego are gravitating toward validation-included rental arrangements that transfer calibration burden to distributors. This behavior is most visible among mid-sized pharma R&D shops seeking to preserve balance sheet flexibility for clinical trial stages.
Global Laboratory Grinders Market Segmentation
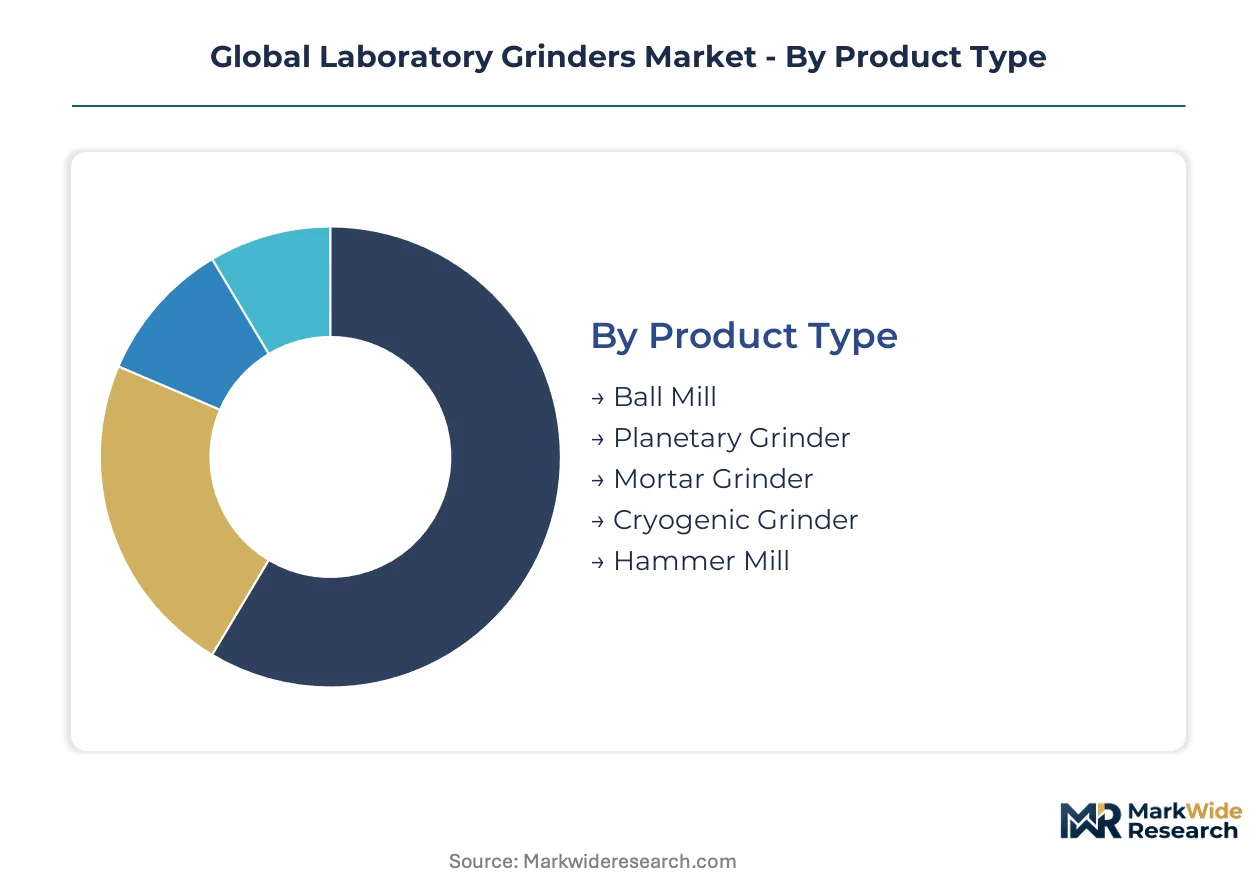
Laboratory grinder procurement patterns diverge sharply between regulated pharmaceutical workflows and exploratory research environments. Equipment specifications, validation requirements, and service bundling all shift across these boundaries.
Product Type:
Standalone benchtop units dominate routine quality control, while integrated processing stations serve high-throughput screening facilities.
- Ball Mill:Cylindrical chambers with grinding media achieve consistent particle reduction for mineral and ceramic samples. Demand clusters in German materials science departments developing solid-state battery electrolytes, constrained by thermal management limitations on heat-sensitive polymers.
- Planetary Grinder:Multi-station orbital motion mechanics deliver sub-micron fineness through centrifugal acceleration. Swiss biobanking facilities and Boston pharmaceutical R&D corridors prioritize these systems for RNA extraction protocols requiring molecular integrity preservation.
- Mortar Grinder:Pressure-shear mechanisms suit traditional sample preparation with minimal heat generation. Academic laboratories in India and Brazil retain significant installed base for teaching and basic research applications.
- Cryogenic Grinder:Liquid nitrogen cooling chambers prevent thermal degradation of temperature-sensitive compounds. Procurement accelerates fastest in United States biobanking and European pharmaceutical dissolution testing workflows.
- Hammer Mill:High-speed rotor impact systems process fibrous and elastic materials. Food allergen analysis laboratories in Germany and Japan deploy these for coarse pre-grinding ahead of fine milling stages.
Volume placements concentrate in Ball Mill configurations; the faster expansion belongs to Cryogenic Grinder systems.
Technology:
Cost tiers separate capital-intensive precision platforms from commodity methods with thinner margin structures.
- Wet Grinding:Slurry-based processing with liquid dispersants enables nanoparticle synthesis without agglomeration. NETZSCH Group anchors European supply for battery research facilities in Germany and Japan pursuing sub-100 nanometer solid-state electrolyte development.
- Dry Grinding:Air-swept or mechanical impact methods retain the largest installed base across quality control laboratories. Margin compression intensifies as ultrasonic methods displace conventional blade approaches in nanoparticle research budgets.
- Ultrasonic Grinding:Non-contact cavitation systems generate extreme localized energy for sub-micron particle production. Materials science departments in Japan and Germany favor these for thermal-sensitive nanomaterial synthesis.
- Jet Milling:High-velocity gas streams achieve ultrafine reduction through particle-on-particle collision. Pharmaceutical micronization facilities in Switzerland and the United States deploy these for inhalable drug formulations.
- Vibratory Grinding:Oscillating motion with grinding media suits brittle and crystalline materials. Geological survey laboratories in Australia and Canada maintain steady demand for mineral specimen preparation.
Revenue concentration sits with Wet Grinding platforms; Ultrasonic Grinding climbs the fastest as materials science budgets shift toward non-contact synthesis.
Application:
Customer maturity levels separate validated GMP workflows from exploratory research with flexible protocols.
- Pharmaceutical Testing:Dissolution testing and content uniformity analysis demand ISO 17025 traceability with automated particle-size reporting. FDA 21 CFR Part 11 compliance drives software-enabled grinder replacement cycles in United States contract laboratories.
- Chemical Analysis:Spectroscopic and chromatographic sample preparation requires contaminant-free reduction with certified alloys. REACH substance restriction lists elevate stainless-steel qualification costs for European Union equipment vendors.
- Material Characterization:Polymer, ceramic, and composite testing spans academic and industrial R&D. Battery research facilities in Germany and Japan pull specialized wet grinding capacity for nanomaterial development.
- Food Processing:Allergen detection and nutritional analysis require reproducible particle distribution for regulatory compliance. FSSAI mandates in India and EFSA protocols in Europe shape equipment specifications.
- Soil Testing:Environmental remediation and agricultural chemistry applications favor robust mechanical systems. Government laboratories in Australia and Brazil sustain demand for heavy-duty grinding configurations.
Margin pools concentrate in Pharmaceutical Testing; Food Processing gains share fastest as allergen regulation tightens across Asia-Pacific markets.
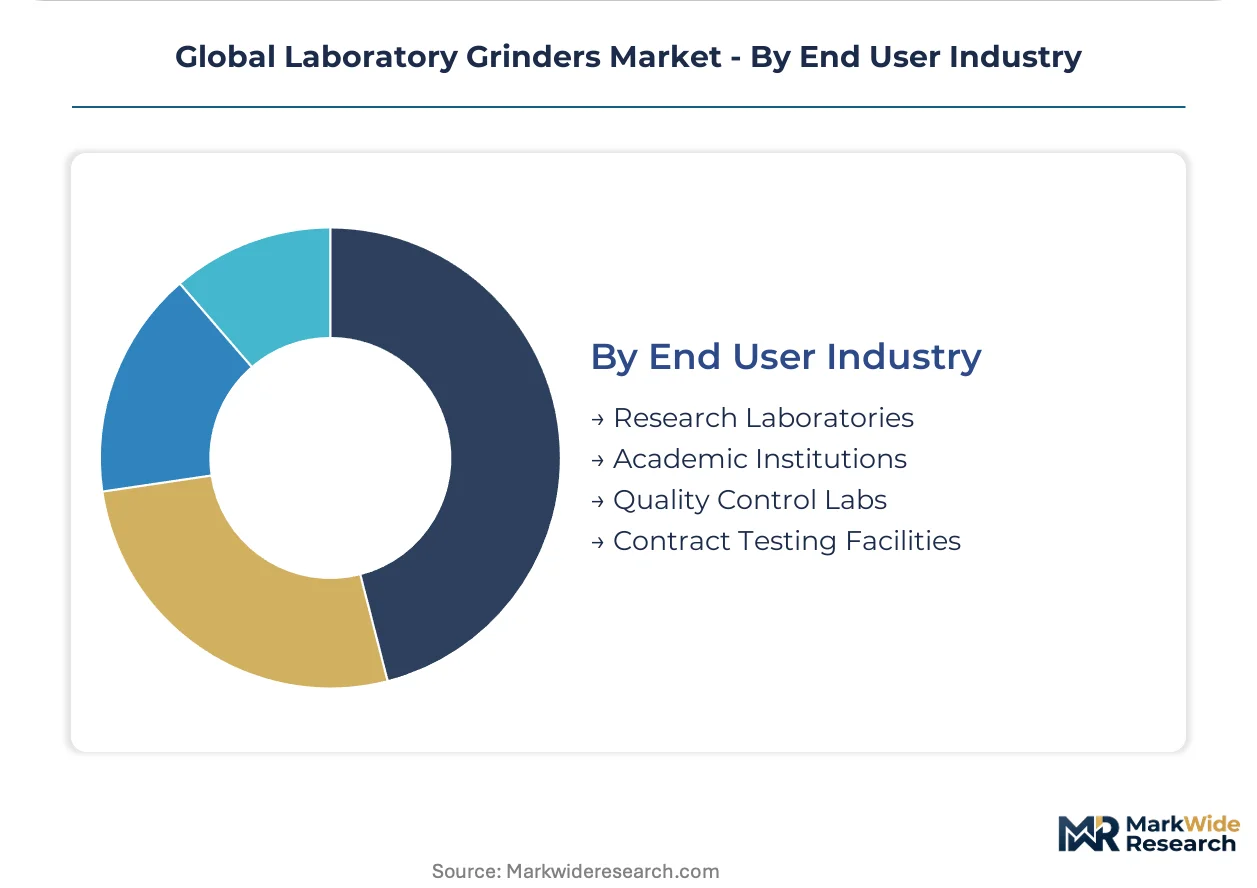
End User Industry:
Procurement authority structures separate centralized capital budgeting from distributed purchasing decisions.
- Research Laboratories:Corporate and government R&D facilities prioritize performance specifications and service responsiveness. Boston and San Diego biotech clusters drive premium grinder demand with bundled validation requirements.
- Academic Institutions:University departments balance equipment cost against teaching versatility. Budget constraints in India and Brazil sustain demand for manual mortar grinders alongside entry-level automated systems.
- Quality Control Labs:In-house manufacturing testing demands GMP-ready documentation and calibration traceability. EMA Annex 15 qualification standards extend European sales cycles for equipment vendors.
- Contract Testing Facilities:Outsourced analytical services seek balance sheet flexibility through grinder-as-a-service models. German and United States distributors pioneer subscription-based equipment access with bundled validation.
Equipment placements concentrate in Quality Control Labs; Contract Testing Facilities expand most quickly as service unbundling fragments traditional capital relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech cluster and San Diego's pharmaceutical R&D corridor concentrate United States demand for validated grinding systems with FDA 21 CFR Part 11 compliance. Procurement patterns across major economies diverge sharply between GMP-ready pharmaceutical workflows and exploratory materials science applications.
United States
FDA electronic records mandates accelerate replacement cycles for software-enabled grinders with audit-trail capabilities. Biobanking expansion in Boston and Switzerland drives cryogenic grinder procurement for RNA extraction workflows. Contract laboratories in San Diego's pharmaceutical corridor pioneer grinder-as-a-service models with bundled validation.
Germany
Battery research facilities in Baden-Württemberg pull specialized wet grinding capacity for solid-state electrolyte development. REACH substance restriction lists elevate stainless-steel alloy certification costs across European supply chains. Pharmaceutical testing laboratories in Bavaria expand procurement of cryogenic grinding systems with ISO 17025 traceability.
Switzerland
Swissmedic qualification standards extend equipment validation timelines for vendors serving European pharma. Biobanking facilities in Basel prioritize planetary grinder systems for molecular integrity preservation. The country's precision manufacturing heritage anchors premium grinder demand across pharmaceutical and materials science segments.
Japan
METI funding for next-generation battery research drives wet grinding adoption in materials science departments. PMDA quality standards shape pharmaceutical laboratory equipment specifications. Osaka-based industrial clusters sustain demand for nanoparticle synthesis systems in electronics and chemical applications.
India
CDSCO quality-control mandates create first-time demand for GMP-ready grinding systems in Hyderabad and Mumbai contract labs. FSSAI allergen detection protocols expand food processing laboratory equipment procurement. Academic institutions in Maharashtra and Karnataka balance teaching versatility against budget constraints for manual and automated systems.
Global Laboratory Grinders Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration service alignment and GMP documentation capability. The vendor base stratifies between ISO 17025-accredited specialists and generalist equipment fabricators. Three archetypes dominate: precision grinding specialists with wet processing dominance, calibration-anchored premium positioning holders, and diversified industrial equipment conglomerates with laboratory divisions. Competitive moves concentrate on vertical integration into metallurgical certification and subscription-based service unbundling.
Among German-based precision specialists, Retsch GmbH and Fritsch GmbH exemplify calibration-anchored premium positioning through ISO 17025-aligned service offerings. NETZSCH Group occupies a distinct position representing wet grinding specialization for nanomaterial preparation. These three entities collectively illustrate how European manufacturers leverage regulatory proximity and qualification expertise to defend margin tiers against commoditization pressures from generalist competitors.
| Leading Market Players |
|---|
| Retsch GmbH |
| NETZSCH Group |
| Fritsch GmbH |
| IKA Werke GmbH & Co. KG |
| Buehler |
| GEA Group AG |
| Union Process |
| Spectris |
| MRC Lab |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between ISO 17025-aligned systems and unvalidated commodity equipment manifests in pricing spreads exceeding threefold and supply chain configurations that concentrate precision manufacturing in Germany and Switzerland while commodity fabrication disperses across lower-cost European and Asian hubs. Pharmaceutical laboratories in Boston and Basel absorb these premiums for GMP-ready documentation, whereas academic buyers in India and Brazil prioritize cost-minimized alternatives with thinner after-sales support.
Pricing Analysis
Value-based pricing anchored to validated throughput outcomes dominates pharmaceutical and biobanking procurement, with cryogenic and planetary systems commanding substantial premiums tied to molecular integrity preservation and automated particle-size reporting. Price differentiation rests on ISO 17025 calibration alignment and FDA 21 CFR Part 11 software compliance, with stainless-steel alloy certification under REACH elevating raw material costs for European-facing vendors. Cost compression in dry grinding segments intensifies as ultrasonic methods capture nanomaterial research budgets. Contract testing facilities in San Diego and Boston exhibit lowest price sensitivity due to grinder-as-a-service subscription models, while academic institutions in emerging markets remain most cost-constrained.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical corridor and local-sourcing preferences under CDSCO procurement guidelines are reshaping sourcing patterns for GMP-ready equipment, pressuring multinational vendors to establish regional assembly or certification partnerships. Precision grinder manufacturing concentrates in Germany, Switzerland, and Japan, drawing from specialized stainless-steel foundries in Bavaria and Baden-Württemberg alongside precision motion-control components from Japanese industrial clusters. Single-source vulnerability persists for ISO 17025-accredited calibration services clustered in Western Europe, creating service-access bottlenecks for Asia-Pacific laboratories. Distribution runs through specialized scientific equipment distributors with validation bundling capabilities, particularly in Boston, San Diego, and German pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025-accredited calibration capacity constraints prop pricing power for validated equipment tiers, as pharmaceutical laboratories cannot substitute uncertified alternatives without jeopardizing regulatory compliance. Supply limitations in qualified service infrastructure sustain margin premiums for incumbent specialists.
For Market Incumbents: Anticipate ultrasonic grinding substitution in materials science segments by deepening wet grinding specialization for battery electrolyte applications and securing captive metallurgical certification capacity to deflect REACH-driven cost pressures. Backward integration into stainless-steel alloy testing preserves European market access against ECHA documentation requirements. Calibration service network expansion into Asia-Pacific addresses the geographic imbalance in ISO 17025-accredited providers. For New Entrants and Emerging Players: Specialized distributors with validation bundling capabilities offer the most penetrable channel for grinder-as-a-service models targeting mid-sized contract laboratories in Boston and San Diego seeking balance sheet flexibility. India's CDSCO-mandated quality control expansion in Hyderabad and Mumbai contract labs represents underserved first-time demand for GMP-ready systems. Partner with regional certification bodies to accelerate EMA Annex 15 qualification timelines for European market entry. For Investors and Strategic Acquirers: Re-rating potential sits with wet grinding specialists given METI-funded battery research acceleration in Japan and Germany, where nanomaterial preparation demand outpaces specialized capacity expansion. Long-term viability favors vendors with dual competence in precision mechanical engineering and regulatory documentation software. Acquisition targets should demonstrate ISO 17025 service anchoring or vertical control over contaminant-free alloy supply chains. Watch for inflection when grinder-as-a-service penetration in contract testing exceeds critical mass, signaling permanent demand migration from capital purchase to subscription models.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Calibration Network Expansion | Addresses Asia-Pacific service-access bottlenecks threatening pharmaceutical laboratory compliance timelines. |
| Backward Integration into Metallurgical Certification | Preserves European market access under ECHA contaminant testing protocols for contact surfaces. |
| Grinder-as-a-Service Model Rollout | Captures balance-sheet-constrained contract laboratories in Boston and San Diego biotech corridors. |
| Wet Grinding Capacity Addition | Serves METI-funded solid-state battery research in German and Japanese materials science departments. |
| AI-Enabled Particle Analysis Integration | Opens premium pricing tiers through real-time fineness feedback converging automated imaging with grinding control. |
Research Methodology
Multi-period observation of grinder procurement patterns, regulatory submission timelines, and calibration service capacity expansion anchored the trend analysis, supplemented by interviews with equipment validation specialists, pharmaceutical quality control directors, and scientific distribution channel managers. Primary fieldwork engaged laboratory procurement officers at contract testing facilities in Boston and San Diego, maintenance directors at German battery research facilities, and academic buyers in Indian pharmaceutical corridors. Secondary validation drew from FDA 510(k) filings for software-enabled grinding systems, EMA qualification documentation databases, REACH substance restriction updates, and ISO 17025 accreditation registries. Bottom-up equipment placement tracking triangulated against top-down market sizing through distributor shipment data and capital expenditure disclosures from major pharmaceutical R&D spenders.
Segment-weighting approaches modeled demand across product type, technology, application, and end-user industry dimensions, with additional granularity for regulatory compliance tier and service bundling intensity. CAGRs derived from fitted growth curves across the projection horizon, incorporating battery research funding trajectories in Germany and Japan, CDSCO mandate implementation schedules in India, and biobanking expansion rates in Switzerland and the United States. Industry-specific inputs included pharmaceutical dissolution testing protocol revisions, solid-state electrolyte development timelines, and RNA extraction workflow automation adoption curves.
Caveats apply where REACH substance restriction list expansions, FDA software validation requirement changes, or ultrasonic grinding technology breakthroughs could materially shift the outlook for mechanical grinder demand. Forecasts reflect assumptions about regulatory enforcement consistency, research funding continuity, and substitution technology maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Benchtop Centrifuges Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Human Milk Analyzers Market