
 Healthcare Simulators Market | 2026-2036
Healthcare Simulators Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Simulators Market Foresight
A shift from single-source procurement to multi-vendor contracting is hardening among large hospital networks and medical school consortia. CAE Inc. anchors its position through captive manufacturing of physiological modeling software and hardware. Laerdal Medical leverages its Nordic R&D base to sustain technology leadership in patient simulator haptics. Kyoto Kagaku competes through specialized anatomical fidelity in Asian medical education markets.
Healthcare simulators are electromechanical or software-based systems replicating human anatomy, physiology, or clinical scenarios for training and competency assessment, typically incorporating pneumatic actuators, fluid-filled vasculature, or real-time physiological algorithms with response latencies under 200 milliseconds. Their primary purpose is to reduce medical error rates by enabling repeatable procedural practice without patient risk. Patient simulators command the largest installed base due to universal pre-clinical curriculum requirements, while virtual reality simulators represent the fastest-expanding margin pool as headset costs decline and software subscription models displace capital-heavy hardware sales. Surgical simulators occupy a mature niche where robotic-assisted platforms now require vendor-specific training modules.
FDA 510(k) pathways and the EU MDR compel manufacturers to submit clinical validation data for software-enabled training devices, elevating barriers for entrants lacking bench testing infrastructure. The EU AI Act and HIPAA training record requirements in the United States further shape data governance for simulation platforms that capture learner performance metrics. Stakeholders must monitor how regulatory divergence between the FDA's software-as-medical-device framework and EMA's emerging digital health guidance affects cross-border product certification timelines.
Market Dynamics
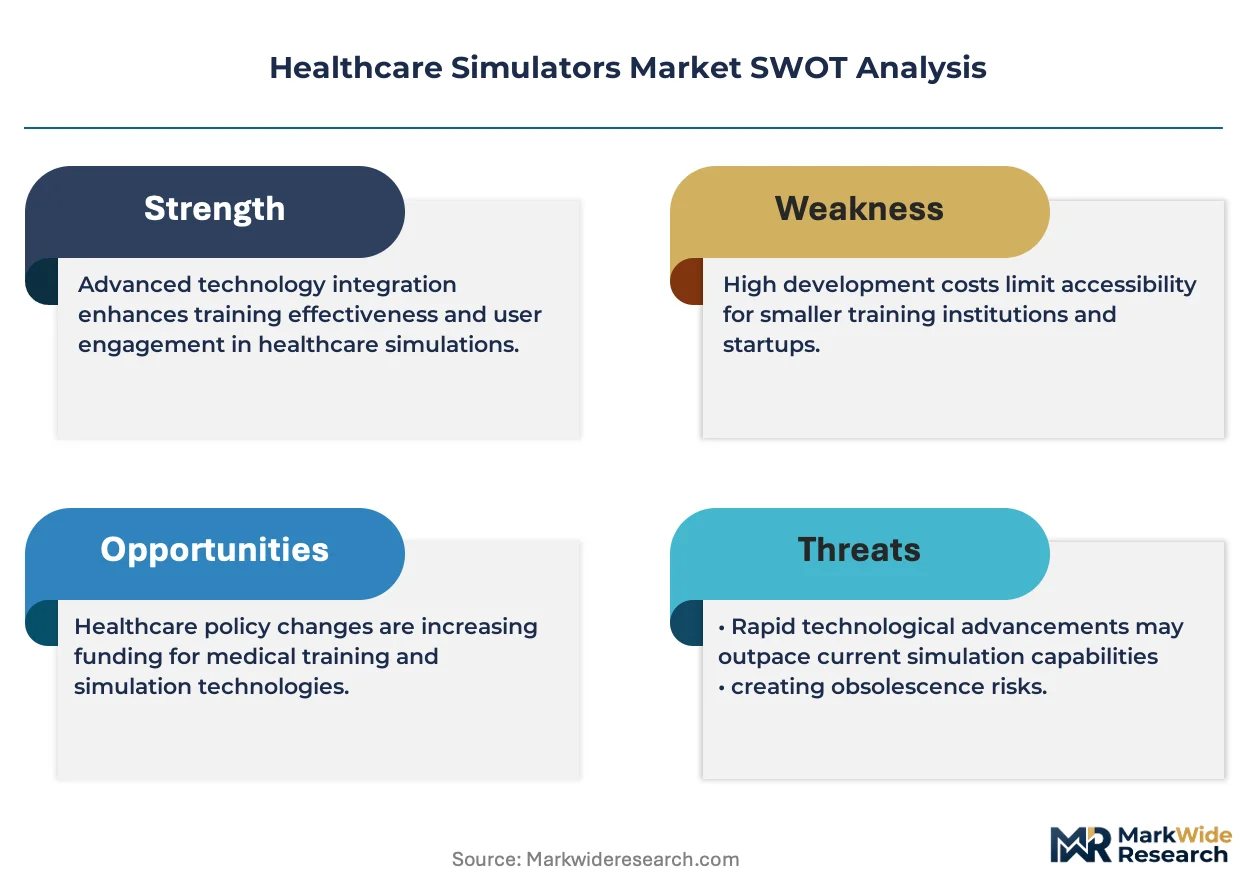
Multi-vendor contracting is hardening procurement power among hospital networks and medical school consortia, compressing margins for simulator manufacturers while elevating software subscription models over capital-heavy hardware sales.
Growth Catalysts
- FDA 510(k) clearance momentum:Software-enabled surgical simulators gaining regulatory validation elevates clinical credibility and opens institutional procurement channels across academic medical centers.
- EU Medical Device Regulation:Performance validation standards tighten for training devices, creating competitive moats for established manufacturers with bench testing infrastructure.
- VR headset cost decline:Hardware economics improving accelerates adoption of immersive simulation platforms in nursing schools and community health programs.
Market Restraints
- Pneumatic actuator supply concentration:Specialized electromechanical components rely on limited Japanese and German component suppliers, creating input vulnerability.
- EU AI Act compliance burden:Learner performance data capture triggers algorithmic transparency requirements, extending certification timelines for AI-enabled feedback systems.
- High-fidelity hardware substitution:Lower-cost screen-based simulation and standardized patient programs compete for curriculum budget allocation in resource-constrained institutions.
Strategic Opportunities
- Underpenetrated Indian medical education:Government medical college expansion and National Medical Commission accreditation requirements create procurement windows for patient simulator vendors.
- Robotic surgery training convergence:Integration of haptic feedback systems with vendor-specific surgical platforms opens recurring revenue from OEM certification partnerships.
- Subscription-based software distribution:Cloud-delivered physiological modeling enables recurring revenue capture from institutions previously priced out of capital purchases.
Industry Challenges
- Biomedical engineer talent scarcity:Cross-disciplinary expertise spanning physiology, software, and electromechanics constrains R&D throughput and field service capacity.
- Cross-border certification fragmentation:Divergent FDA software-as-medical-device frameworks and EMA digital health guidance create redundant validation costs and launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Simulators Market |
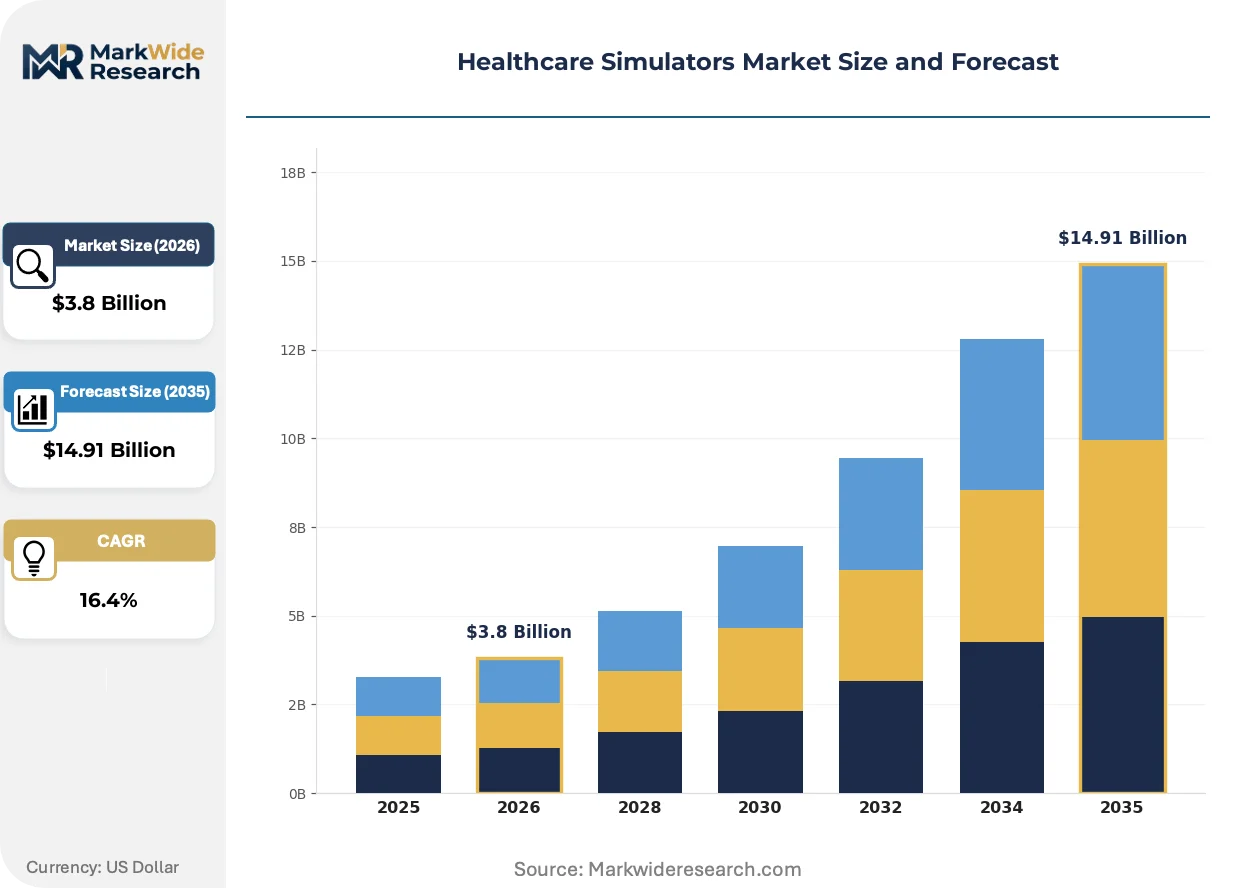
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Simulators, Surgical Simulators, Dental Simulators, Virtual Reality Simulators Technology: High-Fidelity, Low-Fidelity, Augmented Reality, Simulation Software End User: Medical Schools, Hospitals, Clinics, Military Training Facilities Application: Skills Training, Assessment, Continuing Education, Emergency Response |
| Companies Covered | Gaumard Scientific, Limbs & Things, CAE Inc., 3D Systems, Mentice AB, Laerdal Medical, Kyoto Kagaku, Simulab Corporation, Surgical Science Sweden AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Simulators Market Shifts & Advancements
Simulation platforms are fragmenting into composable software layers and interoperable hardware peripherals, enabling institutions to assemble customized training ecosystems rather than purchasing monolithic systems.
Haptic feedback technology is modularizing across patient simulator product lines. Medical schools in Germany and Japan now specify interchangeable tactile response modules for different procedural training scenarios. This architecture compresses replacement cycles and shifts vendor competition toward software ecosystem breadth rather than hardware durability.
The EU AI Act's risk classification framework for educational algorithms is forcing manufacturers to restructure data governance architectures. Simulation platforms capturing learner competency metrics must now implement explainable AI documentation and human oversight protocols. High-stakes certification programs in France and the Netherlands face the steepest compliance adjustments.
Academic medical centers are consolidating simulation procurement through shared service organizations. Hospital networks in the United States now negotiate enterprise licenses spanning multiple campuses, displacing department-level purchasing autonomy. This concentration is most visible in Texas and California where large health systems operate centralized simulation training facilities serving dozens of clinical sites.
Healthcare Simulators Market Segmentation
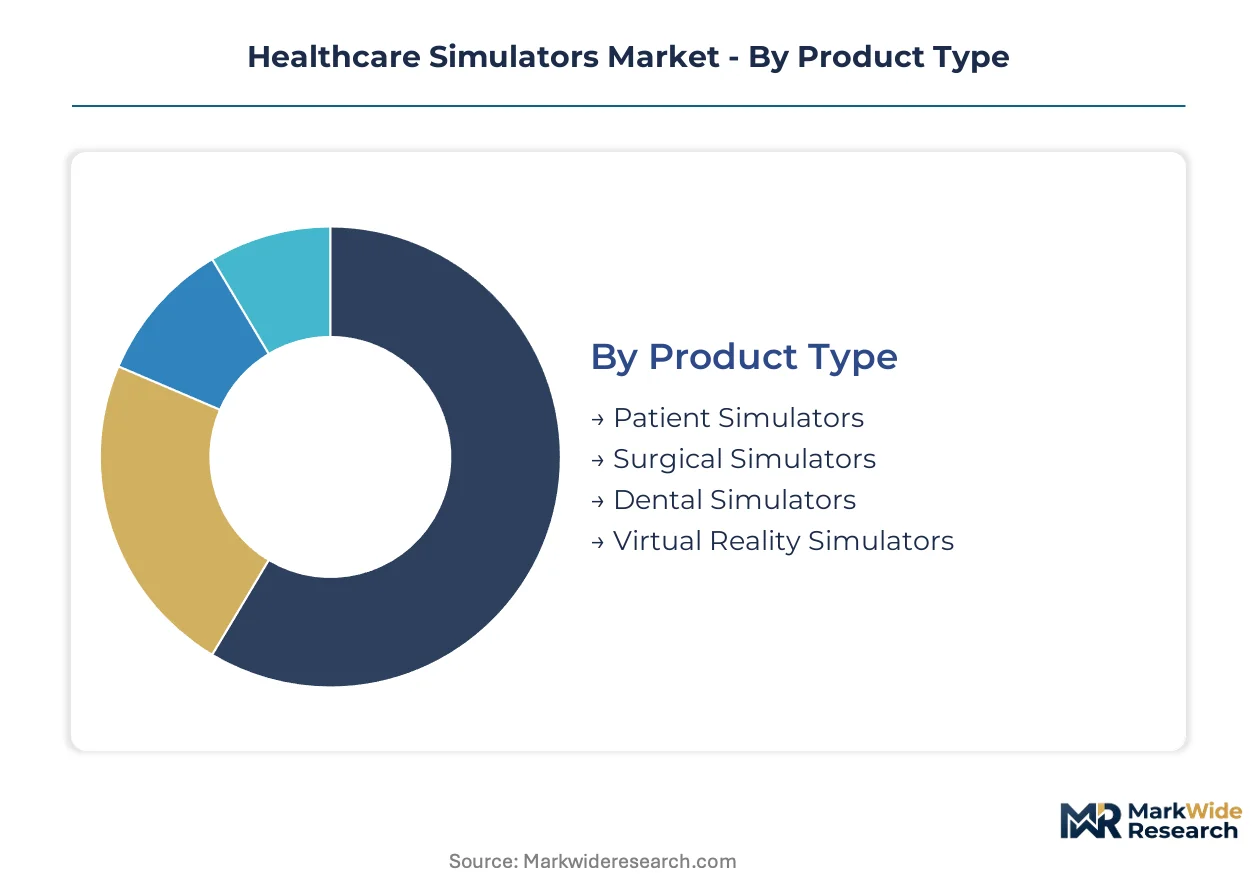
Healthcare simulator procurement varies sharply by institutional budget tier and curriculum mandate. Product architecture, fidelity specifications, and end-use setting each create distinct margin profiles and replacement cycles across vendor portfolios.
Product Type:
Capital-intensity stratifies most aggressively here, with electromechanical patient simulators demanding the largest upfront outlays while software-centric platforms shift cost structures toward recurring licensing.
- Patient Simulators:Full-body electromechanical manikins integrate pneumatic actuators, fluid-filled vasculature, and real-time physiological algorithms with sub-200 millisecond response latencies. Medical schools across the United States, Germany, and Japan anchor procurement volumes as accreditation bodies mandate pre-clinical competency demonstration.
- Surgical Simulators:Hardware platforms replicate instrument-tissue interaction through haptic feedback systems, with robotic-assisted variants now requiring vendor-specific training modules. Academic medical centers in Texas and California consolidate enterprise licenses across multi-campus networks.
- Dental Simulators:Phantom head systems with articulating jaws and periodontal tissue analogs serve fixed prosthodontics and endodontics curricula.
- Virtual Reality Simulators:Headset-delivered immersive environments displace capital-heavy hardware through subscription-based software distribution models.
Patient simulators absorb the bulk of installed capacity; virtual reality simulators are expanding most quickly.
Technology:
Curriculum requirements now span the full fidelity spectrum, with high-stakes certification programs demanding physiological precision while community health programs prioritize accessibility.
- High-Fidelity:Systems replicate cardiopulmonary, neurological, and metabolic responses with algorithm-driven variability for crisis resource management training. FDA 510(k) clearance pathways and EU MDR performance validation standards elevate barriers for entrants lacking bench testing infrastructure.
- Simulation Software:Cloud-delivered physiological modeling enables scenario libraries, competency analytics, and multi-site synchronization without dedicated hardware per seat. HIPAA training record requirements in the United States and EU AI Act algorithmic transparency mandates reshape data governance architectures.
- Low-Fidelity:Task trainers and part-task models isolate specific procedural skills without integrated physiological response systems.
- Augmented Reality:Overlay systems project anatomical visualizations onto physical manikins or standardized patients, bridging screen-based and immersive modalities.
High-fidelity systems command the largest procurement budgets; simulation software is climbing the fastest as institutions exit capital purchase cycles.
End User:
Customer type determines contracting scale, with multi-hospital networks extracting volume discounts while standalone clinics face minimum order constraints.
- Medical Schools:Universal pre-clinical curriculum requirements sustain the largest installed base, with North American and European institutions expanding high-fidelity patient simulator fleets. Multi-vendor contracting is hardening procurement power among medical school consortia.
- Hospitals:Graduate medical education programs and procedural credentialing drive demand for surgical and emergency simulation. Hospital networks in Texas and California operate centralized training facilities serving dozens of clinical sites.
- Clinics:Resource-constrained settings compete for curriculum budget allocation against lower-cost screen-based simulation and standardized patient programs.
- Military Training Facilities:Combat casualty care and field trauma protocols require ruggedized platforms with expeditionary deployment specifications.
Medical schools anchor the largest cumulative installed base; military training facilities are gaining share fastest as defense medical modernization accelerates.
Application:
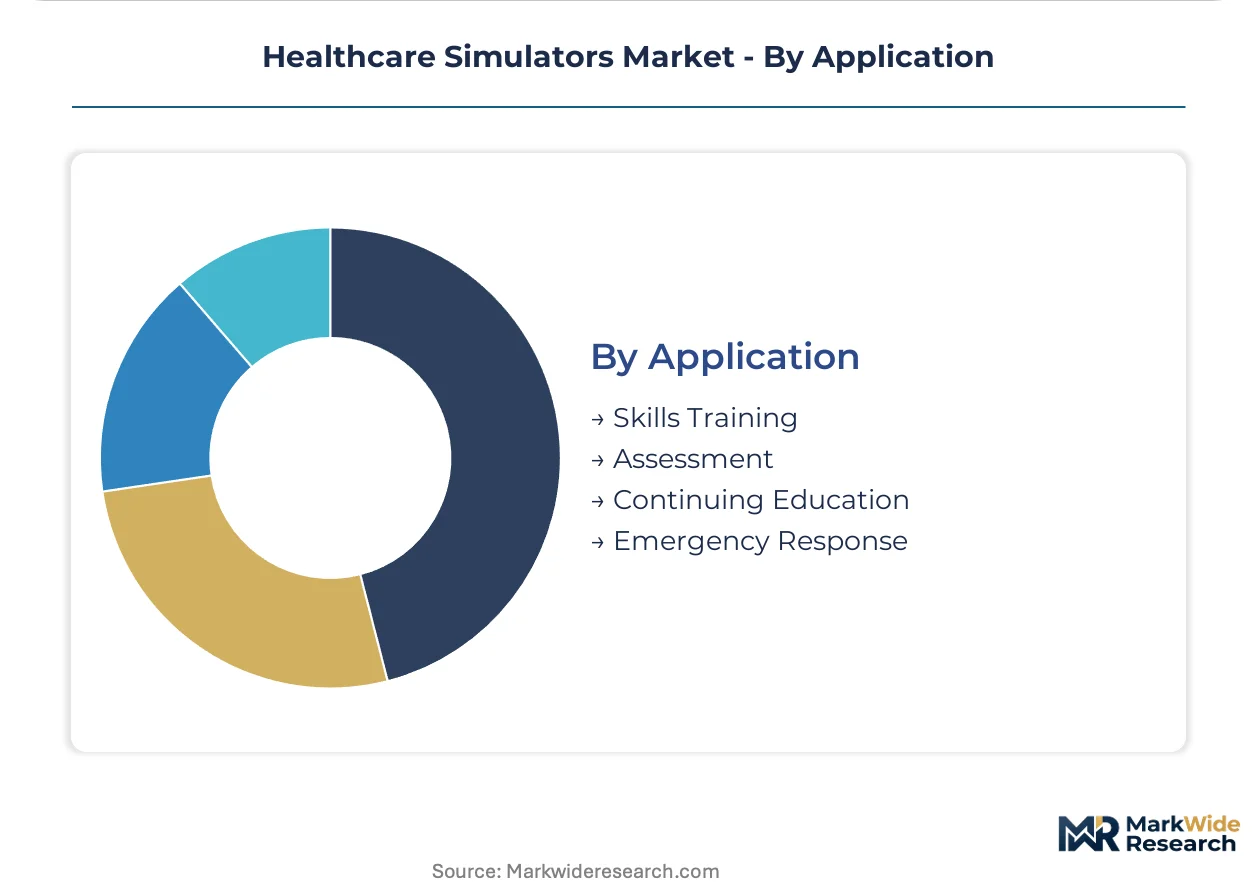
Use case determines performance validation requirements, with high-stakes assessment triggering regulatory scrutiny that skills training often avoids.
- Skills Training:Repeatable procedural practice without patient risk constitutes the foundational use case across all product categories. Medical error reduction mandates from hospital risk management departments sustain procurement priority.
- Assessment:Competency certification for licensure and privileging requires psychometric validation and audit trails. EU AI Act risk classification frameworks for educational algorithms force explainable AI documentation and human oversight protocols in France and the Netherlands.
- Continuing Education:Maintenance of certification programs for practicing clinicians create recurring revenue through content subscription renewal.
- Emergency Response:Crisis resource management and team coordination training for code blue and mass casualty scenarios.
Skills training commands the broadest installed base; assessment applications are steepening fastest as regulators tighten validation standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pneumatic actuator supply chains concentrate in Japanese and German industrial clusters, anchoring high-fidelity simulator manufacturing capacity. Academic medical centers in the United States, Germany, and Japan drive procurement volumes through accreditation-mandated curriculum investments.
United States
Academic medical centers in Texas and California operate centralized simulation training facilities serving multi-campus hospital networks. FDA 510(k) clearance pathways for software-enabled surgical simulators tighten performance validation standards. Greater Boston anchors biomedical engineering talent pipelines feeding simulator R&D operations.
Germany
Medical schools specify interchangeable haptic feedback modules for procedural training scenarios. EU Medical Device Regulation compliance elevates barriers for training device manufacturers lacking bench testing infrastructure. Bavaria's precision engineering clusters supply electromechanical components for patient simulator actuators.
Japan
Kyoto Kagaku competes through specialized anatomical fidelity in Asian medical education markets. METI industrial standards shape domestic simulator certification requirements. Tokyo-Osaka medical device manufacturing corridors concentrate high-fidelity manikin production capacity.
India
Government medical college expansion and National Medical Commission accreditation requirements create procurement windows for patient simulator vendors. CDSCO medical device regulations are tightening import compliance for training equipment. Maharashtra and Karnataka host emerging distributor networks serving institutional buyers.
France
EU AI Act risk classification frameworks force explainable AI documentation for simulation platforms capturing learner competency metrics. ANSM oversight extends to software-enabled training devices with assessment functions. Île-de-France academic hospitals consolidate simulation procurement through shared service organizations.
Healthcare Simulators Market Competitive Landscape
Global majors compete with regional champions across technology licensing and curriculum integration dimensions. The vendor base stratifies into three tiers: integrated physiology-hardware platforms, specialized haptic surgical systems, and software-centric VR distribution models. Dominant competitive moves include multi-vendor contracting consolidation among hospital networks and captive manufacturing of electromechanical components.
Within the integrated platform tier, CAE Inc. and Laerdal Medical occupy positions anchored by captive software ecosystems and Nordic R&D infrastructure respectively. Kyoto Kagaku represents the regional specialist archetype, while Surgical Science Sweden AB exemplifies European surgical simulation software development. These three entities illustrate how geographic clustering around medical education hubs shapes competitive positioning.
| Leading Market Players |
|---|
| Gaumard Scientific |
| Limbs & Things |
| CAE Inc. |
| 3D Systems |
| Mentice AB |
| Laerdal Medical |
| Kyoto Kagaku |
| Simulab Corporation |
| Surgical Science Sweden AB |
| Others |
Supply & Pricing Matrix
Biomedical engineer scarcity in Greater Boston and Bavaria compresses R&D throughput and field service capacity, widening labor-cost differentials between integrated platform vendors and software-centric entrants. Three-tier pricing structure across premium, standard, and economy levels separates vendors with captive manufacturing from those sourcing electromechanical subsystems externally.
Pricing Analysis
Warranty and field service bundling separates CAE Inc. and Laerdal Medical from emerging VR distributors selling unbundled software licenses. Premium tiers incorporate multi-year maintenance contracts and scenario library updates, while economy positioning strips after-sales support to hit procurement floors at community health programs. Price differentiation hinges on FDA 510(k) clearance status and haptic fidelity specifications. Cost compression in mid-fidelity hardware is intensifying because screen-based simulation and standardized patient programs compete for constrained curriculum budgets. Medical school consortia exhibit highest price sensitivity; military training facilities with expeditionary deployment specifications show lowest.
Supply Chain Analysis
Pneumatic actuator supply rests on Japanese and German specialty component producers, with SMC Corporation and Festo AG anchoring precision electromechanical output. Fluid-filled vasculature systems draw from medical-grade silicone processors in the United States and Switzerland. Real-time physiological algorithm development centers on Nordic and North American software engineering clusters. Single-source vulnerability concentrates in sub-200 millisecond response latency controllers sourced from limited Japanese suppliers. Distribution runs through academic medical center procurement consortia and GPO contracts rather than direct institutional sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive manufacturing of electromechanical components to escape pneumatic actuator supply concentration and compress replacement cycle economics.
For Market Incumbents: Hedge against VR headset cost decline by deepening software ecosystem breadth and physiological modeling IP. Acquire haptic feedback module specialists to modularize across product lines before multi-vendor contracting hardens further. Prioritize bench testing infrastructure investment to exploit EU MDR compliance moats against capital-light entrants lacking validation capabilities. For New Entrants and Emerging Players: Enter via underpenetrated Indian medical education procurement windows created by National Medical Commission accreditation expansion. Target subscription-based software distribution to institutions previously priced out of capital purchases, bypassing electromechanical manufacturing barriers entirely. Lead with cloud-delivered scenario libraries and competency analytics rather than hardware-dependent go-to-market models. For Investors and Strategic Acquirers: Re-rating potential sits with software-centric VR distributors given FDA 510(k) clearance momentum for immersive surgical training platforms. Long-term viability favors vendors with recurring revenue capture and minimal exposure to pneumatic actuator supply chains. Watch for CDSCO regulatory tightening in India as inflection indicator for import compliance cost structures affecting emerging market expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Manufacturing of Pneumatic Actuators | In-house production of electromechanical components insulates margins from Japanese and German supply concentration. |
| FDA 510(k) Clearance Pathway Investment | Software-as-medical-device validation opens academic medical center procurement channels and elevates clinical credibility. |
| Subscription-Based Software Distribution | Cloud-delivered physiological modeling captures recurring revenue from nursing schools and community health programs. |
| Multi-Vendor Contracting Consolidation | Enterprise licenses across Texas and California hospital networks displace department-level purchasing autonomy. |
| EU AI Act Compliance Architecture | Explainable AI documentation for learner performance metrics satisfies ANSM oversight in French assessment applications. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contracts, complemented by interviews with biomedical engineers, simulation center directors, and medical school purchasing committees. Secondary validation drew from CMS Medicare training reimbursement data, academic accreditation body mandates, and medical device trade association reports. Bottom-up installed base estimates triangulated against top-down market sizing from capital expenditure disclosures.
Segmented revenue and unit forecasts incorporate product type stratification across patient simulators, surgical platforms, and VR headsets; technology tiers spanning high-fidelity electromechanical, software-only, and augmented reality overlay systems; and end-user categories including medical schools, hospital networks, and military training facilities. CAGRs were derived from elasticity modeling against accreditation mandate expansion and headset cost decline curves across the projection horizon. Scenario libraries and competency analytics penetration served as software-centric growth inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement intensity divergence between France and Germany. Forecasts reflect assumptions regarding National Medical Commission procurement timeline acceleration in India and pneumatic actuator supply chain resilience. Regulatory fragmentation between FDA software-as-medical-device frameworks and EMA emerging digital health guidance, plus CDSCO import compliance evolution, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Global Operating Table Mattresses Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Medical Equipment Rental Market