
 Flat Panel Antenna Market | 2026-2036
Flat Panel Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Panel Antenna Market Analysis
Modular packaging of flat panel antennas with integrated RF front-ends and software-defined modems is hardening as the default procurement configuration for enterprise and defense buyers. Kymeta Corporation leverages its metamaterials expertise to sustain premium positioning in mobile satellite terminals. L3Harris Technologies anchors defense-sector demand through ruggedized phased-array programs. ThinKom Solutions differentiates via proprietary VICTS architecture for aeronautical applications.
Flat panel antennas are low-profile, electronically steerable radiating elements fabricated from printed circuit boards, liquid crystal substrates, or metamaterial layers, designed to transmit and receive signals without mechanical gimbals across azimuth and elevation planes. Active antenna architectures now lead product-type revenue pools because integrated transmit-receive modules eliminate separate amplifier chains and reduce overall system mass. Satellite communication applications command the largest application share, while 5G network deployments represent the fastest-expanding demand channel as mmWave small cells require compact beamforming arrays.
The FCC governs spectrum licensing and equipment authorization for flat panel antennas operating in Ku, Ka, and V-bands within the United States, while the EU AI Act and CE marking frameworks shape product compliance for European deployments. Military procurement falls under ITAR and EAR export controls administered by the US State and Commerce Departments, constraining supplier eligibility and technology transfer pathways. Stakeholders must monitor evolving spectrum auction outcomes and dual-use technology classification reviews to anticipate access barriers and qualification timelines.
Market Dynamics
Defense procurement cycles and commercial aviation retrofit programs are compressing supplier lead times while metamaterials-based beamforming architectures displace mechanically steered legacy terminals across Ku, Ka, and V-band deployments.
Growth Catalysts
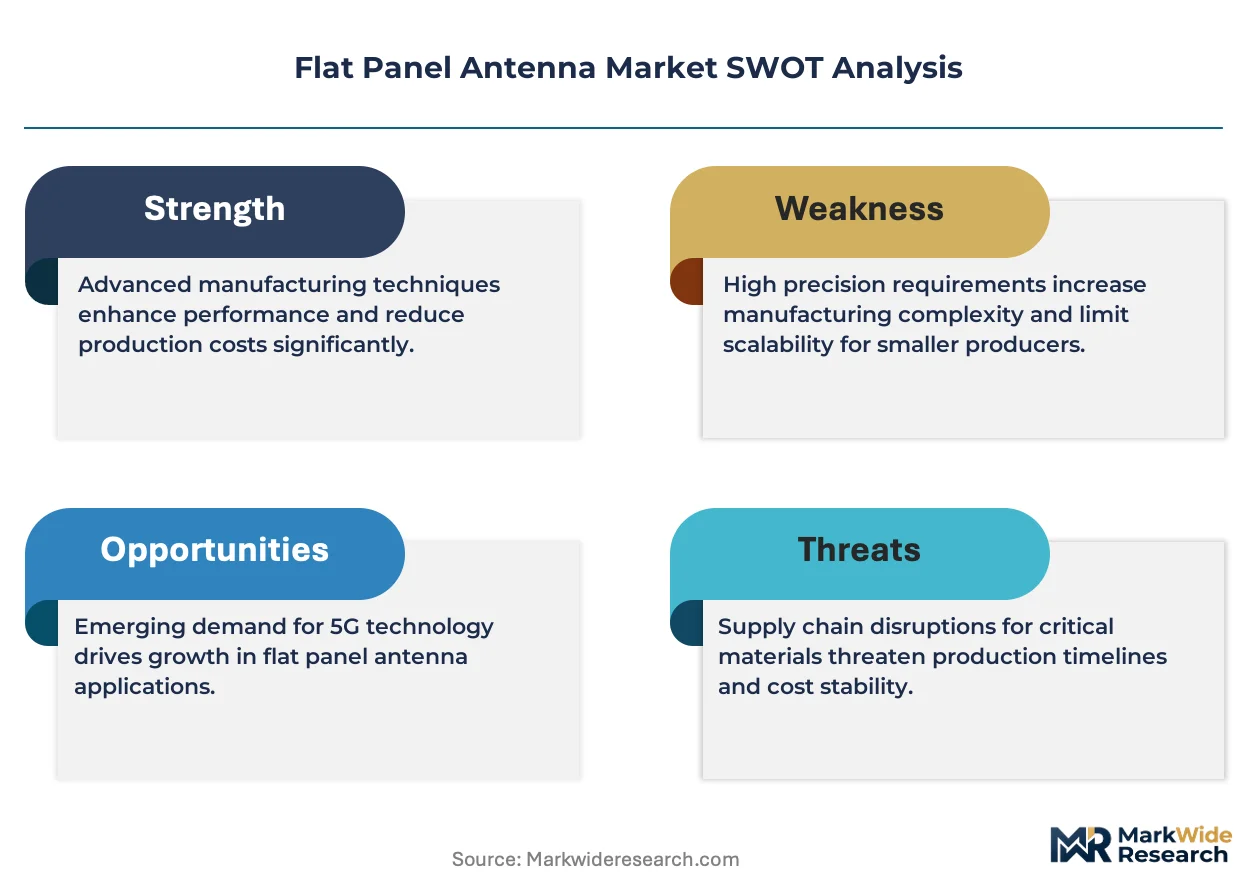
- 5G Mid-Band Spectrum Reallocation:FCC compression of legacy antenna footprints is forcing infrastructure vendors toward compact flat panel arrays for mmWave small cell densification.
- Aeronautical Connectivity Mandates:Commercial aviation fleets are retrofitting satellite-linked terminals to meet passenger bandwidth expectations on long-haul routes.
- Metamaterials Fabrication:Liquid crystal and printed circuit board substrates enable electronic steering without mechanical gimbals, reducing mass and power budgets for mobile platforms.
Market Restraints
- Gallium Nitride Foundry Concentration:Active antenna transmit-receive modules depend on GaN semiconductor supply concentrated in East Asian fabrication facilities.
- ITAR Export Controls:US State Department classification of phased-array technology constrains supplier eligibility and cross-border technology transfer for defense-qualified programs.
- Thermal Management Complexity:High-power density in compact apertures creates cooling bottlenecks that degrade link reliability in elevated-temperature operating environments.
Strategic Opportunities
- Maritime Mobility Gaps:Commercial shipping fleets remain underpenetrated for LEO constellation connectivity, creating retrofit demand for weatherized flat panel terminals.
- Software-Defined Modem Convergence:Integration of RF front-ends with reprogrammable baseband processors enables multi-orbit, multi-frequency operation from single apertures.
- EU Defense Procurement Harmonization:Permanent Structured Cooperation (PESCO) frameworks are consolidating member-state satellite terminal requirements toward interoperable flat panel standards.
Industry Challenges
- Phased-Array Calibration Expertise:Beamformer alignment and element-level testing require specialized RF engineering talent scarce outside defense contractor ecosystems.
- Multi-Agency Certification Timelines:FCC equipment authorization, FAA airworthiness qualification, and DoD MIL-STD validation create sequential approval bottlenecks for dual-use products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Panel Antenna Market |
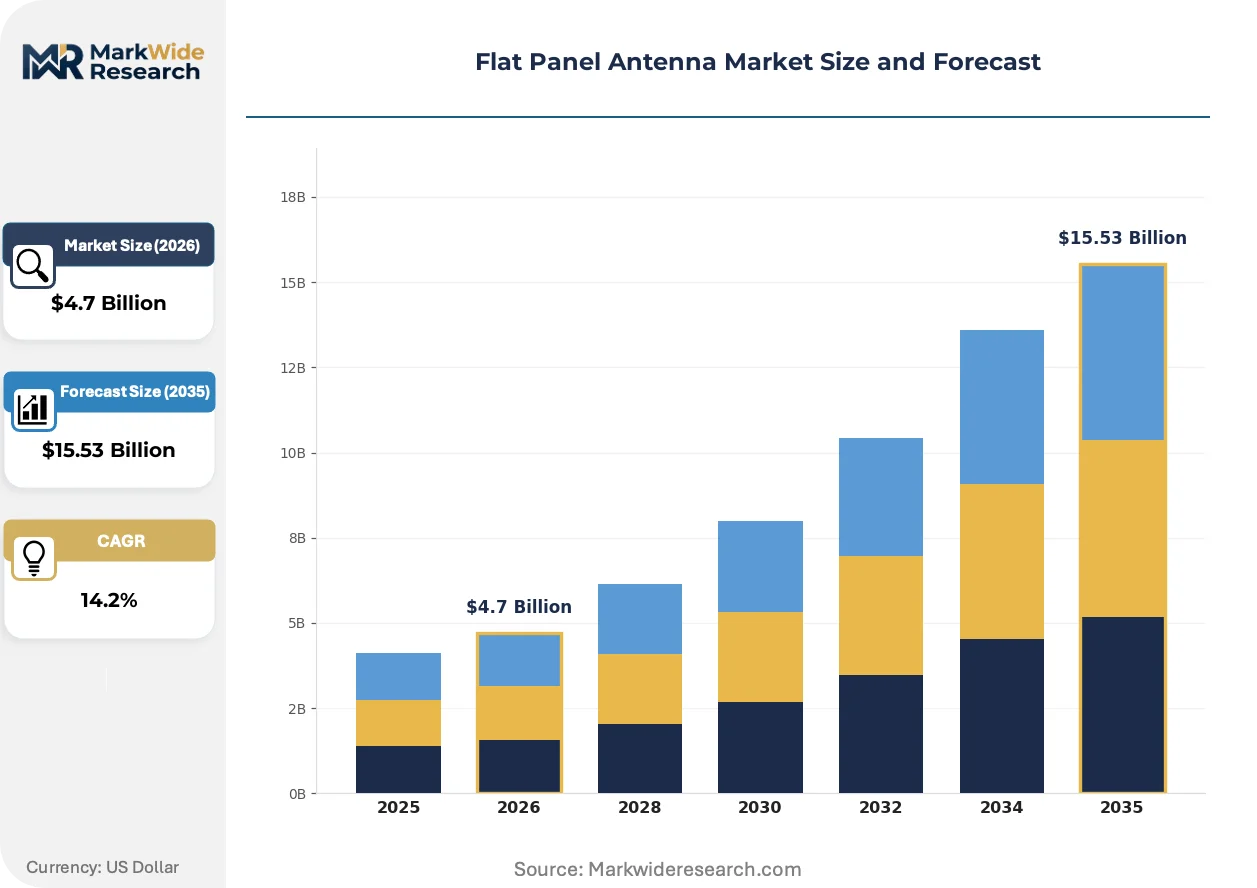
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Antennas, Passive Antennas, Smart Antennas, Multi-band Antennas End User: Telecommunications, Military, Aerospace, Consumer Electronics Application: Satellite Communication, Wi-Fi Connectivity, 5G Networks, IoT Devices Technology: Phased Array, Beamforming, MIMO, Signal Processing |
| Companies Covered | TTI Norte, Ball Aerospace, Kymeta Corporation, China Starwin, L3Harris Technologies, ThinKom Solutions, Gilat Satellite Networks, Intellian Technologies, ALCAN Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Panel Antenna Market Emerging Trajectories
Beamforming architectures are converging with software-defined radio platforms while regulatory pressure on spectrum efficiency accelerates hardware miniaturization across defense and commercial procurement channels.
Metamaterials-based electronic steering is automating antenna repositioning for mobile satellite terminals. Defense integrators and maritime operators are adopting liquid crystal substrates to eliminate mechanical actuators. This automation is compressing system mass budgets and enabling installation on weight-constrained platforms including unmanned aerial vehicles and small maritime vessels.
EU AI Act conformity requirements are reshaping autonomous beam management systems deployed in European airspace and territorial waters. Equipment vendors must document algorithmic decision pathways for interference mitigation and handoff protocols. Dual-use terminal manufacturers are responding by partitioning civilian and military software loads to isolate classified control functions from CE-marked commercial variants.
Airline procurement departments are unbundling hardware acquisition from connectivity service contracts, shifting capital expenditure models toward operational leasing structures. Lessor entities are aggregating terminal fleets across multiple carrier clients to amortize certification costs. This restructuring is most visible in North American and Middle Eastern hub carriers retrofitting narrow-body fleets for transcontinental routes.
Flat Panel Antenna Market Segmentation
Flat panel antenna procurement diverges sharply across defense, commercial aviation, and telecommunications verticals, with each end-use imposing distinct thermal, spectral, and form-factor constraints on subsystem design. Segmentation reveals where electronic steering architectures command premium positioning versus where passive substrates suffice.
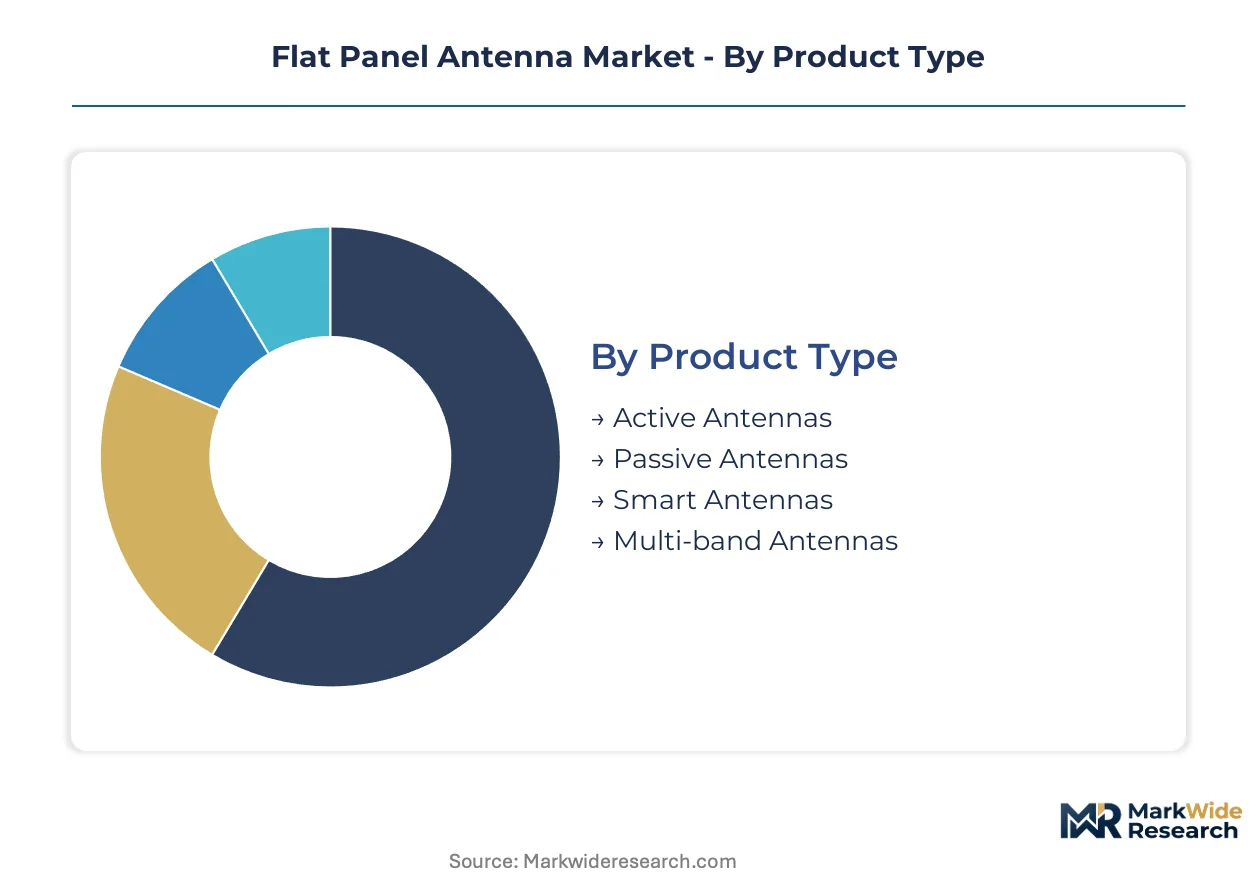
Product Type:
Customization intensity spans from fully integrated active arrays to commodity passive substrates, with buyer sophistication and platform power budgets determining standardization feasibility.
- Active Antennas:Transmit-receive modules integrate Gallium Nitride amplifiers and phase shifters directly into the radiating aperture, eliminating external amplifier chains. Defense procurement and commercial aviation retrofit programs in the United States concentrate demand here, driven by FAA airworthiness mandates for reduced mass on narrow-body fleets.
- Smart Antennas:Embedded baseband processors enable real-time beam adaptation and interference nulling without external modem hardware. Telecommunications infrastructure vendors in Germany and South Korea prioritize these for 5G mmWave small cell densification, where spectral efficiency requirements outpace passive alternatives.
- Passive Antennas:Printed circuit board substrates without integrated electronics serve cost-constrained IoT and consumer applications where mechanical steering remains acceptable.
- Multi-band Antennas:Stacked aperture designs cover Ku, Ka, and V-band from single installations, addressing maritime and enterprise satellite terminal requirements.
Most installed capacity flows through Active Antennas. Expansion is steepest in Smart Antennas.
End User:
Defense qualification timelines and commercial aviation certification burdens create divergent margin structures across buyer categories.
- Telecommunications:Base station and small cell deployments drive volume procurement of compact beamforming arrays, with FCC spectrum reallocation compressing legacy antenna footprints. Infrastructure vendors in the United States and Japan prioritize mmWave-capable designs for mid-band 5G densification.
- Military:ITAR-controlled phased-array programs demand ruggedized apertures with MIL-STD-810 environmental qualification, constraining supplier pools to defense contractors with existing security clearances.
- Aerospace:Commercial airline retrofit programs concentrate in North American and Middle Eastern hub carriers, where passenger connectivity expectations drive satellite terminal installation on transcontinental narrow-body routes.
- Consumer Electronics:Low-profile designs for fixed and mobile satellite broadband terminals target residential and recreational vehicle markets with cost-optimized liquid crystal substrates.
Telecommunications absorbs the highest unit volumes. Military applications sustain the steepest pricing premiums.
Application:
Spectral allocation decisions by national regulators reshape addressable demand across connectivity use cases.
- Satellite Communication:Electronically steerable terminals for LEO and GEO constellation connectivity dominate commercial aviation and maritime mobility segments, with metamaterials-based architectures displacing mechanically gimballed legacy systems.
- 5G Networks:mmWave small cell densification requires compact beamforming arrays with integrated RF front-ends, with Japanese and South Korean carriers leading infrastructure deployment timelines.
- Wi-Fi Connectivity:Enterprise and residential access points adopt flat panel form factors for aesthetic integration and simplified installation logistics.
- IoT Devices:Low-power, narrowband designs serve agricultural monitoring and industrial sensor networks where directional gain compensates for limited transmit power.
Satellite Communication commands the largest revenue share. 5G Networks are expanding most quickly.
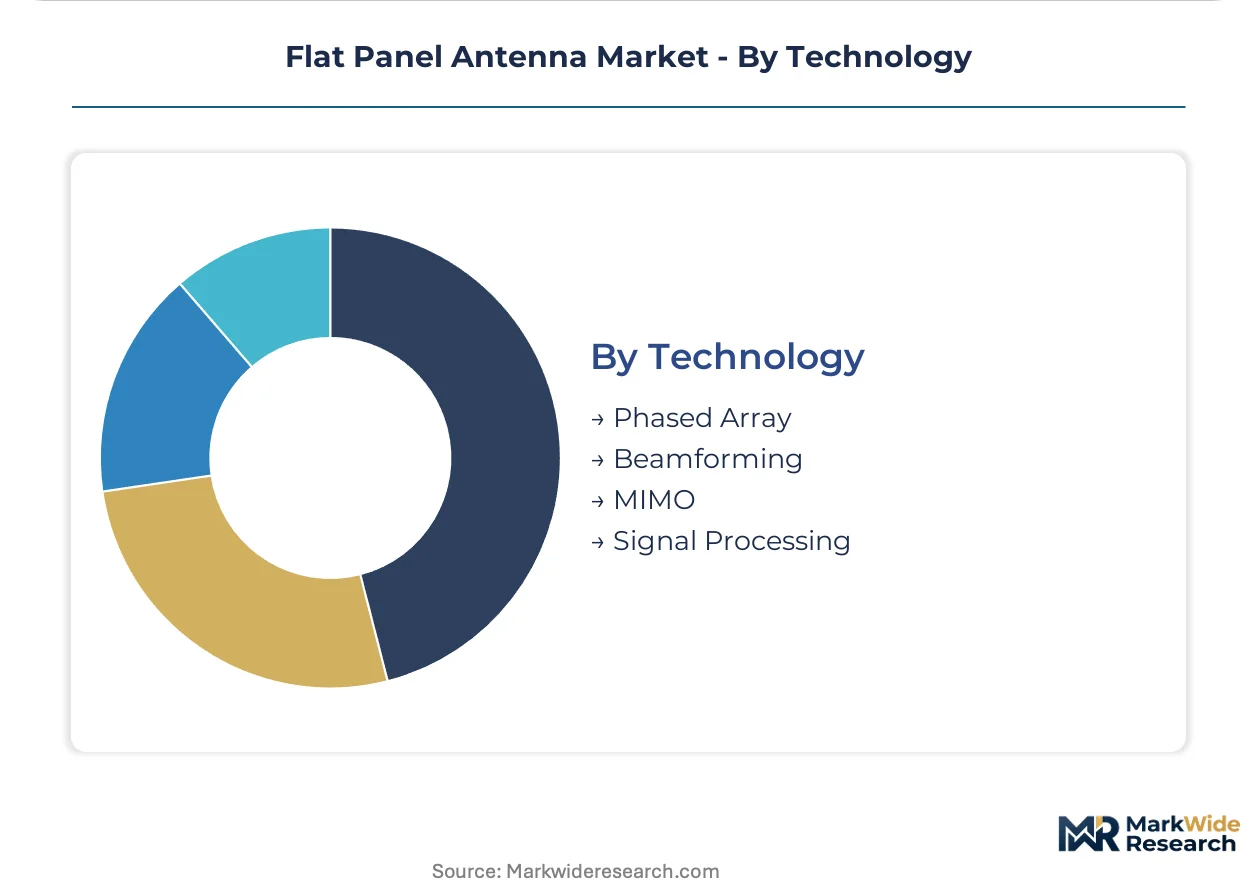
Technology:
Intellectual property concentration in beamformer calibration and metamaterials fabrication creates asymmetric competitive positions across technical approaches.
- Phased Array:Element-level phase control enables electronic steering without mechanical actuators, with liquid crystal and printed circuit board substrates reducing system mass for weight-constrained platforms including unmanned aerial vehicles.
- Beamforming:Algorithmic weight optimization for interference mitigation and spectral efficiency drives adoption in defense and telecommunications applications, with EU AI Act conformity requirements reshaping autonomous beam management systems for European deployments.
- MIMO:Multiple spatial streams increase link capacity for terrestrial wireless backhaul and enterprise connectivity.
- Signal Processing:Baseband algorithms for channel estimation and equalization enable software-defined modem convergence with RF front-end hardware.
Phased Array dominates defense procurement. Beamforming is gaining share fastest in commercial infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flat panel antenna manufacturing originated in United States defense aerospace clusters during the 1990s phased-array radar programs. Commercial satellite terminal demand subsequently migrated production capacity toward East Asian electronics corridors. Procurement patterns now concentrate in jurisdictions with active spectrum reallocation and military modernization timelines.
United States
Defense procurement and commercial aviation retrofit programs drive concentrated demand for active antenna architectures. FCC spectrum reallocation for 5G mid-band operations compresses legacy antenna footprints across infrastructure deployments. California aerospace corridors and Massachusetts RF engineering clusters host the primary defense contractor ecosystems qualifying ITAR-controlled phased-array programs.
Germany
Telecommunications infrastructure vendors prioritize smart antenna procurement for 5G mmWave small cell densification. EU AI Act conformity requirements reshape autonomous beam management systems for European airspace deployments. Bavarian industrial automation corridors and Stuttgart automotive electronics clusters integrate flat panel terminals into connected vehicle testbeds.
China
Domestic LEO constellation deployment accelerates demand for electronically steerable satellite terminals across maritime and enterprise segments. MIIT spectrum licensing frameworks govern Ku and Ka-band equipment authorization with increasing emphasis on indigenous semiconductor supply chains. Shenzhen electronics manufacturing corridors and Beijing satellite system integration clusters scale metamaterials-based aperture production.
South Korea
Telecommunications carriers lead infrastructure deployment timelines for mmWave small cell densification requiring compact beamforming arrays. National spectrum auctions prioritize mid-band 5G capacity expansion in dense urban corridors. Seoul metropolitan area hosts concentrated RF front-end engineering talent pools serving domestic infrastructure vendors.
United Kingdom
Defense satellite terminal requirements consolidate under Permanent Structured Cooperation frameworks toward interoperable flat panel standards. Civil aviation regulators align airworthiness qualification protocols with FAA timelines for narrow-body fleet retrofits. Surrey satellite technology clusters and Bristol aerospace engineering corridors specialize in dual-use terminal qualification pathways.
Flat Panel Antenna Market Vendor Landscape
Premium-margin players sit above commodity-margin players across defense qualification and commercial certification dimensions. The vendor base stratifies into three tiers: ITAR-cleared defense integrators, FAA-qualified aviation specialists, and telecommunications infrastructure suppliers. Two dominant competitive moves define current positioning: strategic partnerships between metamaterials developers and satellite operators, plus vertical integration of RF front-end fabrication into terminal assembly operations.
Within the defense-integrated tier, L3Harris Technologies and Ball Aerospace exemplify ITAR-cleared suppliers anchoring ruggedized phased-array programs. Kymeta Corporation occupies a distinct position in metamaterials-based mobile satellite terminals, representing the liquid crystal substrate specialization vector. ThinKom Solutions sits within the aeronautical qualification tier, its proprietary VICTS architecture serving commercial aviation retrofit demand. These three anchors demonstrate how intellectual property concentration in beamformer calibration creates asymmetric competitive positions across technical approaches.
| Leading Market Players |
|---|
| TTI Norte |
| Ball Aerospace |
| Kymeta Corporation |
| China Starwin |
| L3Harris Technologies |
| ThinKom Solutions |
| Gilat Satellite Networks |
| Intellian Technologies |
| ALCAN Systems |
| Others |
Supply Flow & Price Mechanics
Commercial aviation fleet retrofit mandates for satellite-linked connectivity are compressing supplier lead times and forcing volume commitments that reshape component sourcing economics. Defense procurement cycles for ITAR-cleared phased-array programs run parallel, creating dual-track pricing structures that reward qualification depth over unit scale.
Pricing Analysis
Three-tier pricing structure across ITAR-cleared defense, FAA-qualified aviation, and telecommunications infrastructure levels dominates procurement contracts. Price differentiation stems from certification grade—FCC equipment authorization versus MIL-STD-810 environmental qualification—and volume scale across enterprise versus government buyers. Cost compression in telecommunications infrastructure tiers is intensifying because mmWave small cell densification demands commoditized beamforming arrays. Telecommunications vendors exhibit highest price sensitivity; defense integrators with security clearance requirements show lowest.
Supply Chain Analysis
Regional distribution centers in California aerospace corridors and Massachusetts RF engineering clusters feed hub-and-spoke patterns into defense contractor ecosystems. Manufacturing concentrates in United States, Taiwan, and South Korea, with GaN semiconductor fabrication anchored in East Asian foundries. Raw material dependencies include liquid crystal substrates, printed circuit board laminates, and Gallium Nitride wafers. Single-source vulnerability in GaN foundry concentration creates supply chain risk. Distribution runs through authorized defense distributors and commercial aviation lessor entities aggregating terminal fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC spectrum reallocation for 5G mid-band operations compounds procurement velocity across dual-use terminal categories, creating regulatory-driven demand inflection.
For Market Incumbents: Lock in metamaterials fabrication partnerships and captive GaN semiconductor supply to defend against emerging liquid crystal substrate specialists. Secure FAA airworthiness qualification pathways ahead of narrow-body fleet retrofit waves. ITAR clearance renewal cycles represent the critical defensive lever. For New Entrants and Emerging Players: Maritime shipping operators remain underserved for LEO constellation connectivity, presenting white-space entry through weatherized flat panel terminals. Software-defined modem convergence enables multi-orbit operation without aperture duplication. Partner with satellite operators for bundled service-hardware offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with metamaterials-based beamformer calibration specialists holding defense-adjacent intellectual property. Five-to-ten year viability hinges on dual-use qualification pathway breadth. Monitor EU PESCO framework consolidation timelines as interoperability standard adoption signal.| Strategic Initiative | Industry Significance |
|---|---|
| Metamaterials Fabrication Partnership | Kymeta Corporation's liquid crystal substrate expertise accelerates mobile terminal mass reduction for UAV platforms. |
| FAA Airworthiness Qualification | ThinKom Solutions' VICTS architecture satisfies passenger connectivity mandates for transcontinental narrow-body routes. |
| GaN Semiconductor Backward Integration | L3Harris Technologies' captive amplifier production insulates against East Asian foundry concentration risk. |
| Software-Defined Modem Convergence | Multi-orbit operation from single apertures reduces maritime fleet retrofit capital expenditure burdens. |
| EU PESCO Framework Alignment | Permanent Structured Cooperation harmonization creates interoperable terminal standards across member-state defense procurement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, commercial aviation fleet managers, telecommunications infrastructure vendors, and metamaterials R&D directors with secondary validation. FCC equipment authorization databases, FAA airworthiness directive filings, ITAR-controlled program announcements, and satellite operator capex disclosures anchored source triangulation. Bottom-up terminal shipment estimates and top-down spectrum auction value allocations were reconciled.
Segment-weighting approaches modeled active antenna, smart antenna, and passive antenna product categories alongside defense, aerospace, telecommunications, and consumer electronics end-use verticals across the projection horizon. CAGRs derived from installed base replacement cycles and LEO constellation deployment timelines. Phased-array calibration expertise scarcity and thermal management complexity served as industry-specific forecast modifiers.
Underlying measurement precision varies by segment; defense procurement and commercial aviation categories carry tighter precision than consumer electronics projections. Forecasts reflect documented assumptions regarding spectrum auction outcomes, ITAR classification reviews, and dual-use technology transfer pathways. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
CATV RF Amplifiers Market
RF Components
SMD Resonator Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
US RFID Tags Market
RF Components
Radio Frequency Duplexer Market
RF Components
Analog Phase Shifter Market
RF Components
Multilayer Coupled Inductor Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
Low Noise Amplifier Market
RF Components
RF Spectrum Analyzer Market
RF Components
Frequency Synthesizer Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
Europe Small Signal Transistor Market
RF Components
FBAR Devices Market
RF Components
High-Frequency RF Evaluation Board Market