
 Gaas RF Switch Market | 2026-2036
Gaas RF Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Gaas RF Switch Market Insights
REACH compliance is realigning the cost-of-entry calculus for European GaAs RF switch suppliers by mandating restricted substance documentation across compound semiconductor supply chains. Skyworks Solutions leverages captive GaAs fabrication capacity to sustain margin control across defense and commercial aerospace programs. Qorvo anchors its position through deep vertical integration into epitaxial wafer growth and back-end packaging for high-reliability applications. Infineon Technologies differentiates via silicon-GaAs hybrid roadmaps that bridge legacy radar upgrade cycles with 5G infrastructure refresh timelines.
GaAs RF switches are compound semiconductor devices fabricated on gallium arsenide substrates, typically employing PHEMT or MESFET process nodes with switching speeds below 10 nanoseconds and isolation exceeding 30 dB for microwave and millimeter-wave signal routing. These devices serve as critical signal path selectors in radar front-ends, cellular base stations, and satellite communication payloads where silicon alternatives fail to deliver comparable power-added efficiency at frequencies above 3 GHz. The SPDT product category occupies the largest volume share due to its ubiquity in antenna diversity and transmit-receive modules, while multi-pole configurations represent the fastest-growing segment as phased array architectures proliferate across military and 5G mmWave deployments. MMIC technology leads revenue generation through monolithic integration of multiple switch functions with low-noise amplifiers and attenuators, whereas MEMS-based GaAs switches remain confined to niche test equipment applications where electrostatic actuation delivers superior linearity.
FCC spectrum auctions and NTIA frequency coordination rules shape US demand by determining which bands require GaAs-based switching in next-generation base station and handset architectures. ECHA substance restrictions and EU Green Deal material traceability requirements compound compliance burdens for importers of GaAs epitaxial wafers and packaged die. China's GB standards for telecommunications equipment and SAMR semiconductor import certification create additional market access friction for non-domestic suppliers. Stakeholders must monitor how national security-driven supply chain segmentation between allied and non-allied semiconductor ecosystems reshapes qualification requirements and foundry partner selection for GaAs RF switch procurement programs.
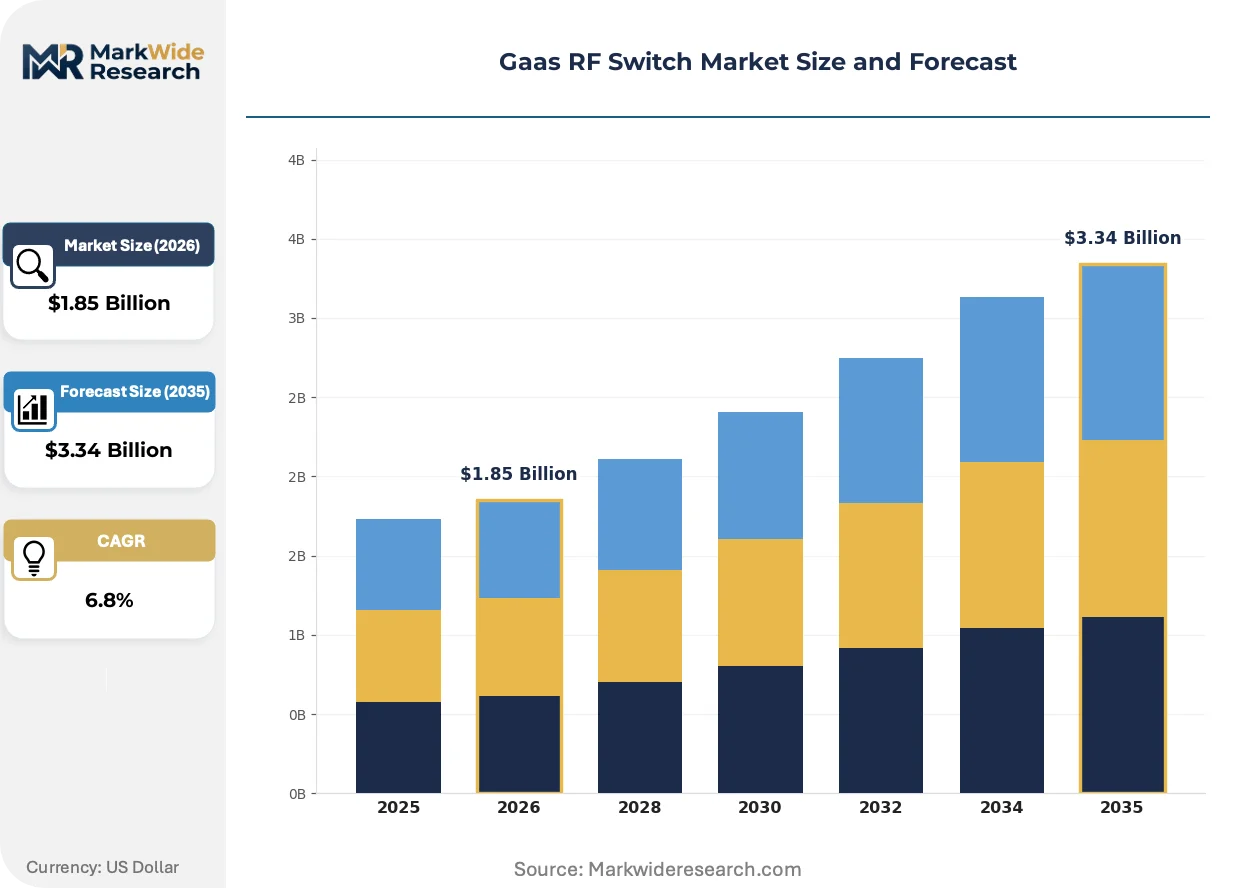
Market Dynamics
Defense procurement programs across the United States, China, and allied nations are concentrating GaAs RF switch demand into qualified supply chains with captive epitaxial wafer capacity, compressing vendor selection criteria toward vertically integrated compound semiconductor specialists.
Growth Catalysts
- US defense procurement:Pentagon radar and electronic warfare modernization programs mandate GaAs components for transmit-receive modules, locking in multi-year foundry allocations.
- REACH compliance:ECHA substance restrictions force European suppliers to document restricted materials across compound semiconductor supply chains, advantaging pre-qualified vendors with existing compliance infrastructure.
- Phased array proliferation:5G mmWave base station deployments and military radar upgrades require multi-pole switch configurations, expanding addressable content per system.
Market Restraints
- Epitaxial wafer concentration:Six-inch GaAs substrate supply concentrates among Japanese and German producers, exposing buyers to single-source disruption risk.
- Silicon-on-insulator substitution:SOI switches below 6 GHz threaten GaAs incumbency in cellular handset diversity applications, compressing volume in consumer-grade segments.
- MIIT localization mandates:China's Ministry of Industry and Information Technology semiconductor self-sufficiency targets restrict foreign foundry access to domestic equipment certification programs.
Strategic Opportunities
- Satellite constellation buildouts:Low-earth orbit communication payloads require radiation-hardened GaAs switches for Ka-band signal routing, opening specialized qualification tracks.
- EU Green Deal material traceability:Mandatory supply chain documentation creates competitive moats for European suppliers with established circular economy compliance.
- Hybrid silicon-GaAs integration:Converged process nodes enable single-package solutions bridging legacy radar refresh cycles with 5G infrastructure timelines.
Industry Challenges
- Compound semiconductor process engineering:PHEMT and MESFET fabrication expertise concentrates among aging specialist workforces, constraining foundry expansion.
- ITAR and EAR certification timelines:US State Department and Commerce Department export control classifications add 12-18 months to defense-qualified switch qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaas RF Switch Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Pole, Multi-Pole, SPDT, DPDT End User: Aerospace, Telecommunications, Consumer Electronics, Industrial Technology: MEMS, MMIC, PHEMT, MESFET Application: Power Amplifiers, RF Front-Ends, Antenna Switching, Test Equipment |
| Companies Covered | Skyworks Solutions, Qorvo, Analog Devices, Infineon Technologies, Broadcom, MACOM Technology Solutions, NXP Semiconductors, Murata Manufacturing, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaas RF Switch Market Trends and Innovations
Monolithic microwave integrated circuit architectures are displacing discrete switch assemblies across defense and telecommunications equipment, compressing bill-of-materials complexity while demanding higher functional integration from compound semiconductor foundries.
MMIC technology is modularizing switch, amplifier, and attenuator functions onto single GaAs die, eliminating inter-device bond wire parasitics. Prime defense contractors and 5G infrastructure OEMs are standardizing on these integrated configurations for phased array front-ends. The shift is compressing vendor count per program while raising barriers for discrete component specialists.
REACH substance restrictions and RoHS amendments are mandating lead-free plating and restricted substance documentation across European-imported GaAs die and packaged components. Compound semiconductor suppliers must now maintain material traceability from epitaxial growth through final test. Automotive radar and aerospace programs constitute the most affected segments, with qualification cycles extending to accommodate documentation audits.
Defense procurement officers are consolidating vendor relationships around qualified suppliers with captive six-inch GaAs fabrication, displacing merchant foundry sourcing for critical programs. This concentration is visible across US Navy radar modernization and NATO electronic warfare upgrades, where supply chain security ratings now outweigh unit cost in source selection criteria.
Gaas RF Switch Market Segmentation
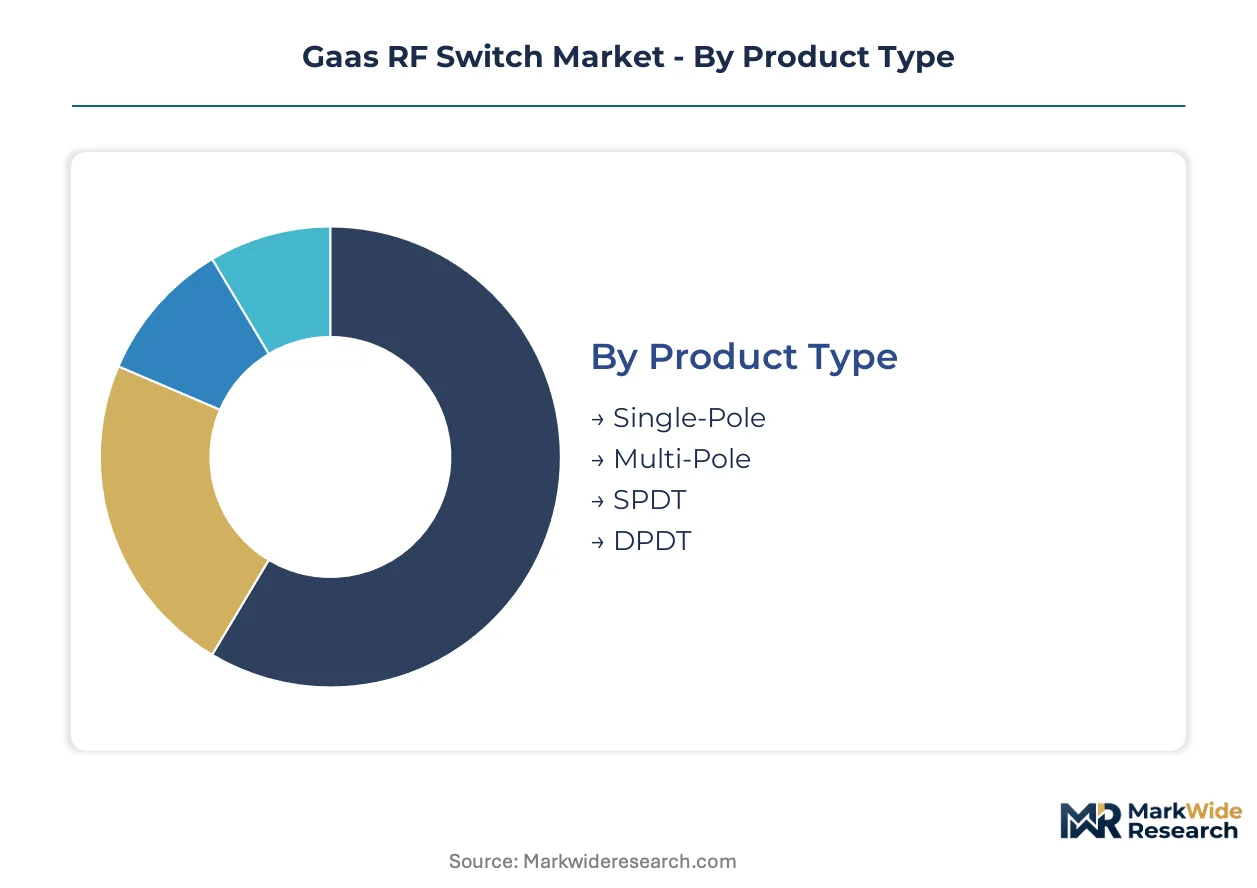
GaAs RF switch procurement patterns diverge sharply across frequency bands, reliability tiers, and integration requirements. Buyers select architectures based on phased array density, thermal constraints, and qualification overhead rather than unit cost alone.
Product Type:
Cost tier separates commodity antenna diversity modules from mission-critical radar subsystems.
- SPDT:Single-pole double-throw configurations dominate antenna transmit-receive switching with isolation exceeding 30 dB. Defense radar modernization programs across the United States and allied nations lock in multi-year foundry allocations for these devices.
- Multi-Pole:Configurations with four or more poles enable beam-steering in phased array architectures. 5G mmWave base station deployments and military electronic warfare upgrades are expanding addressable content per system.
- Single-Pole:Simpler architectures serve test equipment and lower-complexity routing functions.
- DPDT:Double-pole double-throw variants bridge legacy system upgrades requiring signal path redundancy.
SPDT leads volumes today; multi-pole configurations are gaining share fastest.
End User:
Application maturity determines whether buyers prioritize radiation tolerance, consumer-grade cost, or industrial reliability.
- Aerospace:Satellite communication payloads and military avionics demand radiation-hardened Ka-band switches. Low-earth orbit constellation buildouts are opening specialized qualification tracks for European and US suppliers.
- Telecommunications:5G infrastructure OEMs standardize on MMIC-integrated switch configurations for massive MIMO deployments. FCC spectrum auctions determine which bands require GaAs-based switching versus silicon alternatives.
- Consumer Electronics:Cellular handset diversity applications face silicon-on-insulator substitution below 6 GHz.
- Industrial:Factory automation and instrumentation programs require extended temperature range operation.
Telecommunications leads volumes today; aerospace is expanding most quickly.
Technology:
Process node selection trades switching speed against linearity and power handling.
- MMIC:Monolithic microwave integrated circuit architectures integrate switch, amplifier, and attenuator functions onto single GaAs die. Prime defense contractors are eliminating inter-device bond wire parasitics through these configurations.
- PHEMT:Pseudomorphic high electron mobility transistors deliver switching speeds below 10 nanoseconds with superior power-added efficiency. PHEMT fabrication expertise concentrates among aging specialist workforces in Japan and Germany.
- MESFET:Metal-semiconductor field-effect transistors serve legacy radar refresh cycles with established reliability databases.
- MEMS:Microelectromechanical switches remain confined to niche test equipment where electrostatic actuation delivers superior linearity.
MMIC leads volumes today; PHEMT is climbing the fastest.
Application:
Functional position in the signal chain dictates isolation requirements and integration complexity.
- RF Front-Ends:Transmit-receive modules in radar and base station architectures require simultaneous low insertion loss and high isolation. Phased array proliferation across military and 5G deployments is standardizing on integrated front-end configurations.
- Antenna Switching:Diversity and beam-selection functions in cellular handsets and satellite terminals. REACH compliance and RoHS amendments are mandating lead-free plating across European-imported components.
- Power Amplifiers:Switching elements in amplifier bias networks and load modulation circuits.
- Test Equipment:Precision signal routing in vector network analyzers and spectrum analyzers.
RF front-ends lead volumes today; antenna switching is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist PHEMT and MESFET fabrication expertise concentrates among aging workforces in Japan and Germany, constraining foundry expansion while defense procurement officers prioritize qualified suppliers with captive six-inch GaAs capacity.
United States
Pentagon radar and electronic warfare modernization programs mandate GaAs components for transmit-receive modules, locking in multi-year foundry allocations. FCC spectrum auctions and NTIA frequency coordination rules determine which bands require GaAs-based switching. Defense contractors in Massachusetts and California are consolidating vendor relationships around qualified suppliers with ITAR certification.
China
MIIT semiconductor self-sufficiency targets restrict foreign foundry access to domestic equipment certification programs. GB standards for telecommunications equipment and SAMR semiconductor import certification create market access friction. Packaging and test activity concentrates in East Asian hubs, with domestic foundries scaling six-inch GaAs capacity in Jiangsu and Zhejiang provinces.
Japan
Six-inch GaAs substrate supply concentrates among Japanese producers, exposing buyers to single-source disruption risk. METI industrial policy supports compound semiconductor supply chain resilience. Tokyo-Osaka corridor hosts specialist PHEMT fabrication facilities serving defense and satellite communication programs.
Germany
ECHA substance restrictions and EU Green Deal material traceability requirements compound compliance burdens for importers of GaAs epitaxial wafers. REACH compliance mandates restricted substance documentation across compound semiconductor supply chains. Bavaria and Baden-Württemberg anchor European packaging operations for automotive radar and aerospace applications.
South Korea
MFDS certification frameworks and national semiconductor strategy prioritize compound semiconductor self-sufficiency. Samsung and SK Hynix ecosystem spillover supports GaAs RF component packaging specialization. Seoul metropolitan area and Gyeonggi Province concentrate back-end test capacity for 5G infrastructure and defense programs.
Gaas RF Switch Market Competitive Landscape
The competitive structure tilts toward vertically integrated compound semiconductor specialists with captive epitaxial wafer capacity. Vendor selection criteria compress toward qualified suppliers with ITAR certification and six-inch fabrication. Three archetypes dominate: defense-qualified integrated manufacturers, commercial telecommunications-focused foundries, and hybrid silicon-GaAs solution providers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as procurement officers prioritize supply chain security ratings over unit cost.
Among US-based integrated manufacturers, Skyworks Solutions and Qorvo exemplify the defense-qualified archetype with positions spanning captive fabrication through back-end packaging. Infineon Technologies represents the European hybrid approach, bridging legacy radar refresh cycles with converged process roadmaps. These three anchors illustrate how qualification infrastructure and material traceability compliance now outweigh price competition in source selection for critical programs.
| Leading Market Players |
|---|
| Skyworks Solutions |
| Qorvo |
| Analog Devices |
| Infineon Technologies |
| Broadcom |
| MACOM Technology Solutions |
| NXP Semiconductors |
| Murata Manufacturing |
| STMicroelectronics |
| Others |
Pricing and Supply Chain Analysis
Six-inch GaAs epitaxial wafer costs cascade downstream through three distinct pricing tiers that separate defense-qualified integrated manufacturers from merchant foundry suppliers and spot-market traders. Raw substrate pricing from Japanese and German producers feeds into captive fabrication premiums for ITAR-certified programs, while commercial telecommunications buyers negotiate volume contracts against spot-market volatility.
Pricing Analysis
Unbundled die sales dominate defense procurement where qualification documentation carries separate line-item value, while bundled MMIC solutions with integrated amplifiers command premium positioning in 5G infrastructure. Price differentiation hinges on ITAR certification tier and captive six-inch fabrication capacity, with defense contractors least sensitive and commercial handset OEMs facing SOI substitution pressure below 6 GHz. Cost compression in consumer-grade SPDT segments is intensifying as silicon alternatives capture antenna diversity sockets.
Supply Chain Analysis
China's MIIT localization mandates and SAMR import certification rules are reshaping sourcing patterns for foreign GaAs foundries seeking domestic equipment program access. Supply concentration rests on Japan and Germany for six-inch substrates, Taiwan and South Korea for packaging and test, and the United States for defense-qualified fabrication. Single-source vulnerability in epitaxial wafer supply exposes buyers to disruption, with distribution running through qualified supplier networks rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement officers prioritize supply chain security ratings over unit cost, reflecting a demand shift toward radiation-hardened specifications for satellite constellation buildouts.
For Market Incumbents: Cement qualification moats by deepening ITAR-certified fabrication capacity in Massachusetts and California corridors against SOI substitution threats below 6 GHz. Prioritize captive six-inch GaAs epitaxial growth to control substrate cost volatility and lock multi-year defense foundry allocations.
For New Entrants and Emerging Players: Begin with European automotive radar programs where REACH compliance documentation creates incumbent friction and EU Green Deal material traceability requirements favor new qualified entrants. Target Bavaria and Baden-Württemberg packaging hubs with lead-free plating capabilities as the most penetrable entry point.
For Investors and Strategic Acquirers: Consolidation pressure builds where aging PHEMT specialist workforces in Japan and Germany constrain foundry expansion against rising defense procurement demand. Focus acquisition screening on mid-cap compound semiconductor specialists with captive epitaxial capacity and established ITAR infrastructure; watch for Pentagon radar modernization program award announcements as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Six-Inch GaAs Fabrication Expansion | Locks multi-year foundry allocations for Pentagon radar and electronic warfare programs. |
| ITAR Certification Infrastructure Investment | Accelerates defense procurement qualification timelines against 12-18 month State Department review cycles. |
| Hybrid Silicon-GaAs Process Roadmap Development | Bridges legacy radar refresh cycles with 5G infrastructure refresh timelines for dual-use revenue. |
| REACH Compliance Documentation System | Creates competitive moats for European suppliers facing ECHA substance restriction mandates. |
| Satellite Constellation Qualification Track | Opens specialized revenue streams for radiation-hardened Ka-band switch configurations. |
Research Methodology
Bottom-up telecommunications and defense procurement modeling reconciled against top-down GaAs foundry capacity tracking forms the analytical core of this study. Primary interviews with compound semiconductor process engineers, defense procurement officers, 5G infrastructure OEM sourcing managers, and satellite payload system architects combined with secondary validation from SEC 10-K filings, FCC spectrum auction records, Pentagon budget justification documents, and ECHA substance restriction databases.
Input-output matrices map PHEMT and MESFET fabrication capacity against phased array deployment schedules across the projection horizon. Segmentation dimensions span product type, end user, technology node, and application position in the signal chain, with CAGRs derived from elasticity-adjusted demand curves and supply-side capacity constraints. Forecast inputs incorporate MIIT localization policy implementation pace and ITAR certification queue lengths.
Caveats apply where Pentagon budget reauthorization delays or ECHA RoHS amendment scope expansions could materially shift the outlook. Forecasts reflect documented assumptions regarding defense procurement continuity and substrate supply concentration stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Microwave MLCC Market
RF Components
RF Tunable Filters Market
RF Components
Power Amplifier Market
RF Components
RF Power Dividers Market
RF Components
RF-Microwave for 5G Market
RF Components
RF Isolator Market
RF Components
US RFID Tags Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Europe Small Signal Transistor Market
RF Components
EMI Microwave Absorber Market
RF Components
433MHz Active RFID Reader Market
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
RF Tester Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
Global Gan RF Devices Market