
 SMD Resonator Market | 2026-2036
SMD Resonator Market Size, Share, and Industry Trends Forecast 2026-2036
SMD Resonator Market Insights
AEC-Q200 qualification is collapsing the gap between automotive-grade and commercial-grade supply pools. Murata Manufacturing leverages vertical integration across ceramic formulation and electrode deposition to sustain margin control in high-reliability tiers. Kyocera AVX anchors Japanese automotive supply chains through dedicated resonator fabs serving Toyota and Honda tier-1s. TKD Science competes on cost-optimized crystal blanks for consumer wearables, differentiating through automated tuning processes.
An SMD resonator is a surface-mount frequency-control component, typically a quartz crystal or ceramic element housed in a ceramic or metal package measuring 1.6 mm by 1.2 mm or smaller, engineered to provide stable clock references between 32.768 kHz and several hundred MHz for microcontroller timing and RF synthesis. Crystal oscillators dominate current revenue pools due to proven phase-noise performance in base stations and precision instruments, while MEMS oscillators represent the fastest-expanding technology segment as silicon MEMS processes enable integration with CMOS wafers and eliminate hermetic ceramic packages. Consumer electronics absorbs the highest unit volumes through smartphone and TWS earbud production, though automotive electronics commands premium pricing tiers tied to temperature-stability specifications.
Japan's METI enforces JIS standards on frequency stability and aging rates that filter out non-compliant suppliers from precision-equipment procurement. The EU F-Gas Regulation and REACH restrict perfluorinated compounds in resonator cleaning processes, forcing reformulation of wafer-processing chemistries. China's MIIT mandates GB standards for 5G base-station components that include SMD resonators in carrier-grade timing modules. Buyers must monitor how dual carbon goals in China and the EU Green Deal reshape energy-intensive crystal-growing operations and ceramic sintering supply.
Market Dynamics
AEC-Q200 qualification requirements are compressing supply pools as automotive ECU counts multiply, forcing resonator manufacturers to requalify production lines for temperature-stability specifications that exceed commercial-grade tolerances by an order of magnitude.
Growth Catalysts
- Automotive ECU proliferation:Electric and software-defined vehicles now embed 80-150 electronic control units per platform, each requiring precision timing references. Tier-1 suppliers in Germany and Japan are locking in multi-year resonator supply agreements.
- REACH and RoHS compliance:European environmental directives are filtering non-compliant Asian suppliers from precision-equipment procurement channels, creating qualified-supplier premiums for compliant manufacturers.
- 5G infrastructure densification:Base station timing modules demand high-stability oscillators in carrier-grade configurations. China's MIIT-mandated GB standards for 5G equipment are accelerating domestic resonator qualification cycles.
Market Restraints
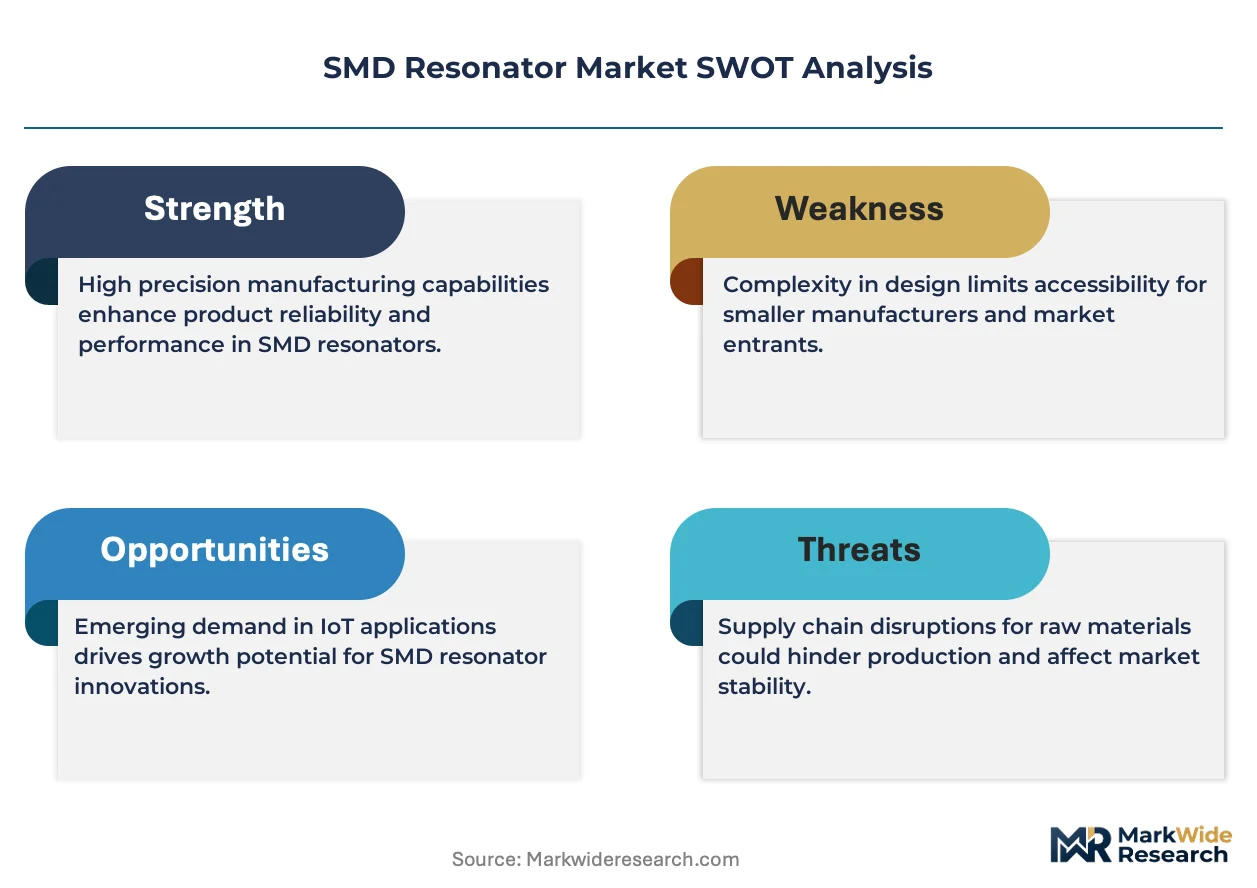
- Quartz crystal supply concentration:High-purity synthetic quartz feedstock production concentrates in Japanese and Chinese crucible-growth facilities, exposing buyers to geographic risk.
- MEMS oscillator substitution:Silicon MEMS timing devices eliminate hermetic ceramic packages and enable CMOS integration, threatening ceramic resonator volumes in consumer wearables.
- F-Gas Regulation friction:EU restrictions on perfluorinated cleaning compounds force wafer-processing chemistry reformulation, extending qualification timelines for European resonator fabs.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor assembly and test are attracting resonator packaging investments to serve domestic smartphone and automotive module production.
- Dual carbon alignment:China's MEE enforcement of carbon-intensity caps on crystal-growing furnaces creates first-mover advantage for manufacturers deploying renewable-powered sintering operations.
- Satellite timing module integration:Low-earth-orbit constellation ground terminals require radiation-tolerant oscillators, opening defense-aerospace supply tiers previously closed to commercial resonator vendors.
Industry Challenges
- AEC-Q200 certification timelines:Automotive-grade qualification cycles extend 18-24 months, locking working capital in inventory before revenue recognition.
- Frequency-tuning automation:Consumer wearable demand for 32.768 kHz units at sub-cent price points requires laser-trimming equipment that depreciates faster than process technology evolves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SMD Resonator Market |
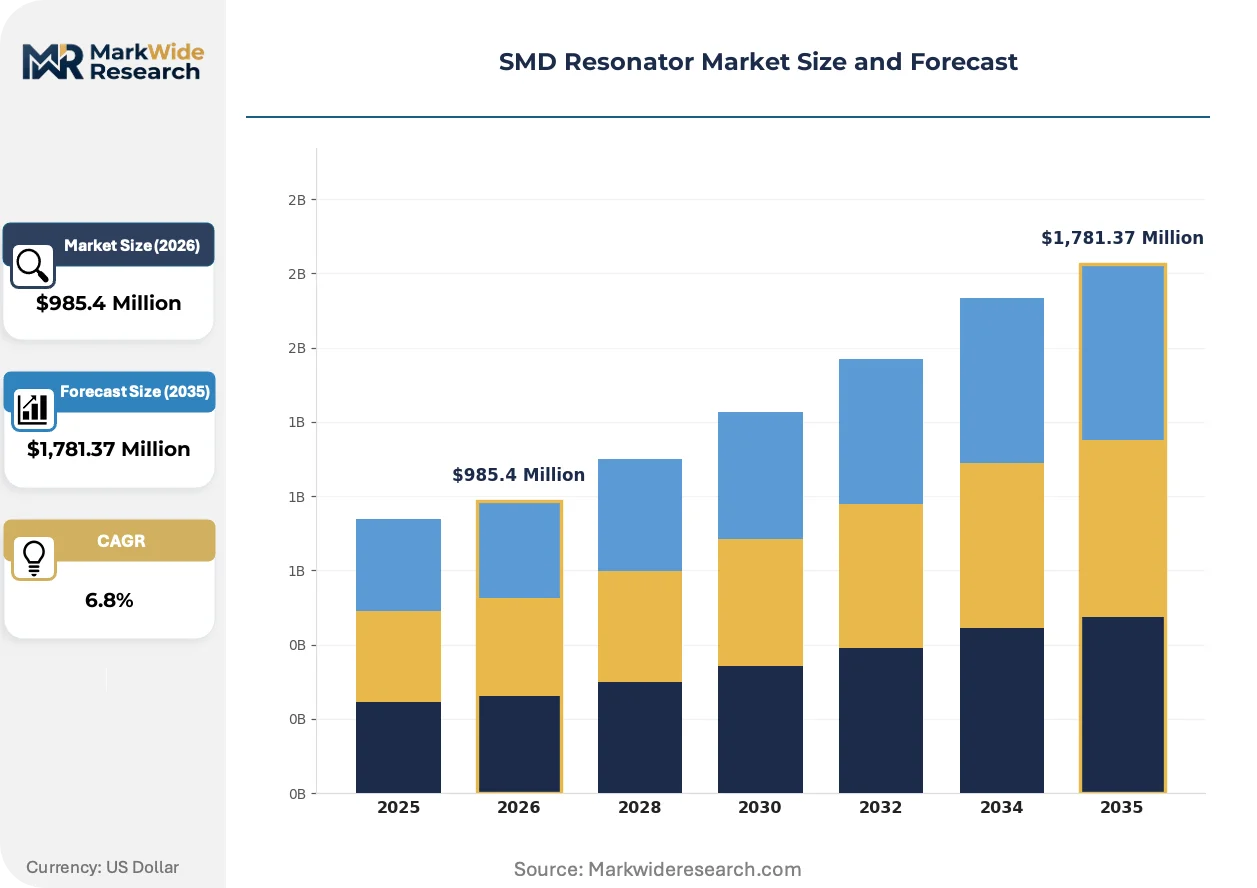
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,781.37 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RC Oscillators, Crystal Oscillators, MEMS Oscillators, Digital Oscillators Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Automation Frequency Range: Low Frequency, Medium Frequency, High Frequency, Ultra High Frequency End User: Original Equipment Manufacturers, Research Institutions, Component Distributors, Aftermarket Providers |
| Companies Covered | Murata Manufacturing, Kyocera AVX, ARGO Technology, PETERMANN-TECHNIK, Abundance Enterprise Company, ALPHA WAVE, Zhejiang Jiakang Electronics, Zhejiang Abel Electron, TKD Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SMD Resonator Market Trends and Innovations
Frequency-control component architectures are diverging along application-specific performance axes, with automotive and telecommunications buyers demanding divergent optimization targets that resist component standardization.
MEMS silicon resonator technology is fragmenting the traditional quartz-dominated landscape. These devices integrate timing elements directly onto CMOS wafers, eliminating ceramic hermetic packages and enabling chip-scale form factors. Smartphone and TWS earbud manufacturers are adopting MEMS oscillators for space-constrained designs. This convergence of semiconductor and frequency-control processes is compressing margins for conventional ceramic resonator suppliers in consumer tiers.
EU F-Gas Regulation restrictions on perfluorinated compounds are forcing reformulation of resonator wafer-cleaning chemistries. European resonator manufacturers must substitute legacy solvents with aqueous or supercritical CO2 alternatives, extending process qualification cycles. Precision-equipment and automotive timing module segments face the steepest compliance costs, with German and French fabs absorbing the bulk of capital retooling.
Automotive tier-1 procurement is consolidating resonator supplier bases around qualified dual-source arrangements. Toyota and Honda supply chains in Japan now require AEC-Q200 certification plus JIS frequency-stability documentation for all timing components. This certification-driven preference shift is disqualifying commercial-grade resonator vendors from automotive revenue pools, compressing the qualified supplier base to vertically integrated ceramic specialists and dedicated automotive crystal manufacturers.
SMD Resonator Market Segmentation
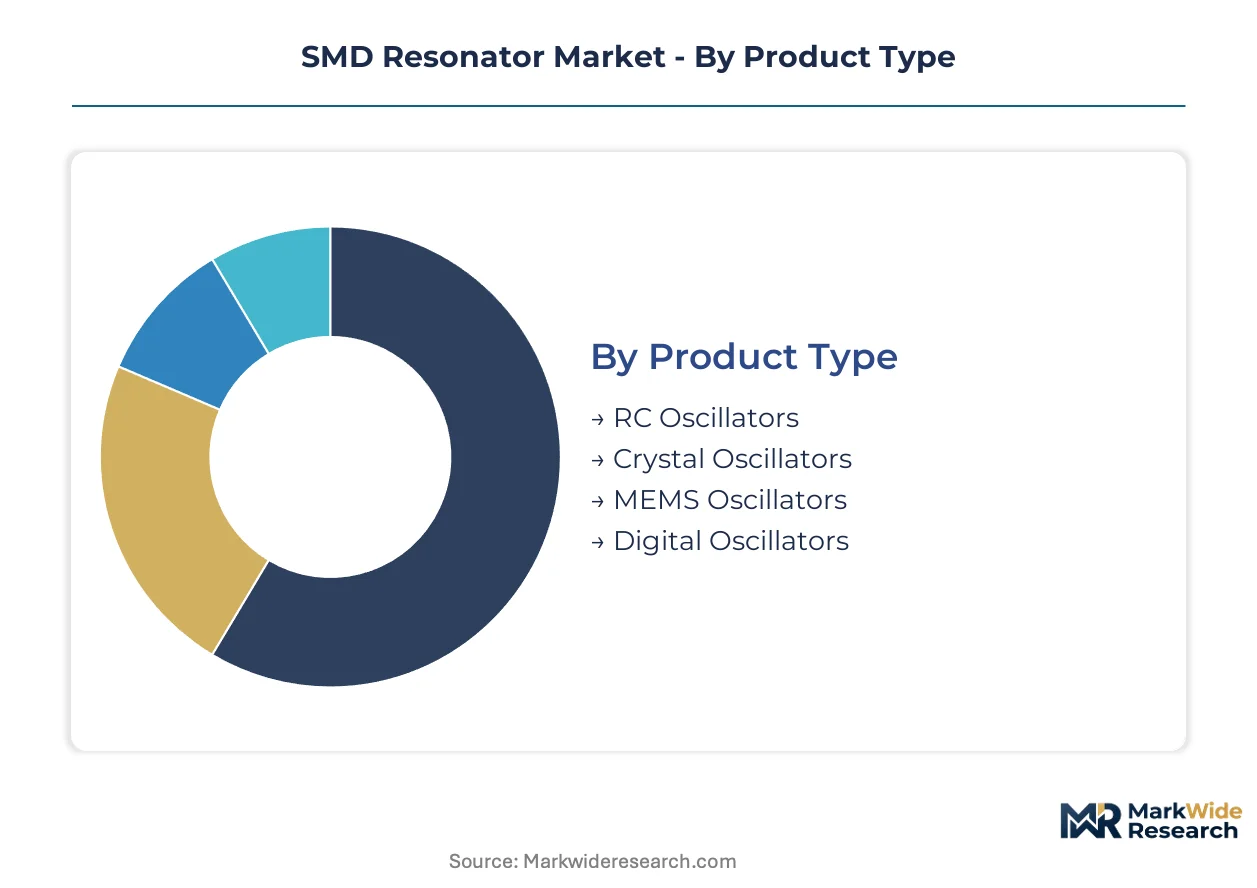
SMD resonator segmentation reveals divergent supply chain configurations across product architectures. Crystal and MEMS oscillators operate through fundamentally different manufacturing footprints, while automotive and consumer applications impose incompatible qualification regimes on shared substrate technologies.
Product Type:
Crystal oscillators concentrate production in Japanese and Chinese crucible-growth corridors, while MEMS devices diffuse across CMOS foundry networks in Taiwan and South Korea.
- RC Oscillators:Resistor-capacitor timing circuits built on silicon substrates without frequency-determining crystals. These devices serve cost-optimized microcontroller clocking in domestic Chinese white-goods manufacturing where absolute precision is secondary to bill-of-materials compression.
- Crystal Oscillators:Quartz-based resonators leveraging piezoelectric properties of synthetic alpha-quartz blanks. Base station timing modules in China's 5G densification program absorb premium temperature-compensated variants, with MIIT-mandated GB standards filtering non-qualified suppliers from carrier-grade procurement.
- MEMS Oscillators:Silicon micromechanical resonators fabricated with semiconductor lithography. TWS earbud manufacturers in South Korea and Vietnam are displacing ceramic alternatives for sub-millimeter form factors.
- Digital Oscillators:Programmable timing devices with integrated fractional-N synthesis. Network equipment vendors in Japan require these for software-defined clocking in edge computing infrastructure.
Crystal oscillators command the established base. The steepest expansion runs through MEMS oscillators.
Application:
Automotive electronics extracts price premiums through AEC-Q200 certification burdens, while consumer electronics drives volume through smartphone and wearable production scales.
- Consumer Electronics:Smartphones, tablets, and wearables requiring 32.768 kHz real-time clock references and RF synthesis timing. Chinese ODMs in Shenzhen and Dongguan dominate procurement volumes, with laser-trimmed crystal blanks hitting sub-cent price points at million-unit scales.
- Automotive Electronics:ECU timing references for powertrain, ADAS, and infotainment subsystems. Toyota and Honda tier-1s in Japan enforce JIS frequency-stability documentation plus AEC-Q200 qualification, collapsing the supply pool to dedicated automotive crystal manufacturers.
- Telecommunications:Base station and optical transport timing modules. China's MIIT GB standards for 5G equipment accelerate domestic resonator qualification cycles for carrier-grade configurations.
- Industrial Automation:Programmable logic controller and servo drive clocking. German machinery builders source high-stability oven-controlled oscillators through qualified European distributors.
Automotive electronics commands the established base. The steepest expansion runs through telecommunications.
Frequency Range:
Low-frequency 32.768 kHz devices diffuse through consumer supply chains, while ultra-high-frequency variants concentrate in defense-aerospace and satellite ground terminal applications.
- Low Frequency:32.768 kHz real-time clock crystals in compact 1.6 mm by 1.2 mm ceramic packages. Smartwatch manufacturers in Japan and South Korea specify these for sub-milliwearable power management.
- Medium Frequency:1-50 MHz fundamental-mode crystals for microcontroller clocking. Industrial automation vendors in Germany specify these for PLC timing with ±50 ppm stability tolerance.
- High Frequency:50-200 MHz third-overtone crystals for RF synthesis. 5G base station radio units in China incorporate temperature-compensated variants for sub-ppb stability.
- Ultra High Frequency:Above 200 MHz surface-acoustic-wave and bulk-acoustic-wave resonators. Satellite ground terminals for low-earth-orbit constellations require radiation-tolerant oscillators in this band.
Low frequency commands the established base. The steepest expansion runs through ultra high frequency.
End User:
Original equipment manufacturers dominate direct procurement through dedicated resonator supply agreements, while component distributors buffer volatility for mid-volume industrial accounts.
- Original Equipment Manufacturers:Apple, Samsung, and automotive tier-1s sourcing directly from Murata, Kyocera AVX, and NDK. Multi-year contracts lock in AEC-Q200-qualified volumes for platform-level ECU counts reaching 80-150 units per vehicle.
- Research Institutions:National laboratories and university physics departments procuring precision frequency references. METI-funded projects in Japan specify JIS-compliant aging rates below ±3 ppm per year.
- Component Distributors:Arrow, Avnet, and local Chinese distributors holding inventory for mid-volume industrial and medical device manufacturers. REACH and RoHS documentation requirements filter non-compliant Asian suppliers from European distribution channels.
- Aftermarket Providers:Repair and refurbishment specialists for consumer electronics and automotive modules. These channels absorb commercial-grade resonators disqualified from OEM automotive tiers.
Original equipment manufacturers command the established base. The steepest expansion runs through component distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity synthetic quartz crucible-growth capacity clusters in Japanese and Chinese facilities, creating geographic concentration risk for resonator feedstock. Automotive ECU proliferation and 5G infrastructure densification are redrawing procurement patterns across manufacturing corridors.
China
MIIT-mandated GB standards for 5G base-station timing modules are accelerating domestic resonator qualification cycles. The country's dual carbon goals enforced by MEE are reshaping energy-intensive crystal-growing furnace operations. Yangtze River Delta packaging clusters in Jiangsu and Zhejiang provinces are absorbing MEMS oscillator investments from CMOS foundry partnerships.
Japan
METI-enforced JIS standards on frequency stability and aging rates filter non-compliant suppliers from precision-equipment procurement. Toyota and Honda tier-1 supply chains require AEC-Q200 certification plus JIS documentation for all timing components. Nagoya-area automotive electronics corridors host dedicated resonator fabs serving domestic OEM platforms.
Germany
EU F-Gas Regulation and REACH restrictions on perfluorinated cleaning compounds force wafer-processing chemistry reformulation. German machinery builders source high-stability oven-controlled oscillators through qualified European distributors for PLC and servo drive applications. Bavarian precision-equipment manufacturers absorb compliance costs from solvent substitution in resonator fabs.
South Korea
TWS earbud and smartphone manufacturers are displacing ceramic resonators with MEMS oscillators for sub-millimeter form factors. Samsung Electronics and domestic ODMs drive procurement volumes through Seoul Capital Area electronics assembly corridors. Busan-Ulsan semiconductor packaging clusters integrate timing components into RF modules for export markets.
United States
FCC spectrum allocation for 5G mmWave and satellite ground terminals creates demand for ultra-high-frequency resonators in defense-aerospace tiers. NHTSA vehicle-safety regulations indirectly pressure automotive tier-1s to source AEC-Q200-qualified timing references. Greater Boston precision-instrument manufacturers specify temperature-compensated variants for laboratory frequency standards.
SMD Resonator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the SMD resonator landscape. Vertically integrated ceramic specialists dominate automotive-grade tiers through captive quartz-blank supply and electrode deposition control, while CMOS-foundry-aligned MEMS vendors capture consumer wearable volumes. Three archetypes define competitive positioning: integrated material-to-package specialists, fabless MEMS design houses, and cost-optimized crystal blank processors. Capacity expansion in ceramic sintering and strategic partnerships with automotive tier-1s represent the dominant competitive moves reshaping supply relationships.
Among Japanese integrated manufacturers, Murata Manufacturing and Kyocera AVX exemplify the vertically integrated archetype with in-house control over ceramic formulation and precision electrode processes. TKD Science occupies a position within the cost-optimized tier, representing Chinese manufacturers competing on automated tuning processes for high-volume consumer applications. These three anchors illustrate the tripartite structure separating premium automotive qualification from commoditized wearable supply.
| Leading Market Players |
|---|
| Murata Manufacturing |
| Kyocera AVX |
| ARGO Technology |
| PETERMANN-TECHNIK |
| Abundance Enterprise Company |
| ALPHA WAVE |
| Zhejiang Jiakang Electronics |
| Zhejiang Abel Electron |
| TKD Science |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month AEC-Q200 qualification timelines concentrate pricing power with Japanese and German manufacturers possessing captive automotive-grade production lines, while cost-optimized consumer tiers face relentless margin compression from automated tuning investments. This lead-time differential separates qualified automotive supply pools from commodity wearable procurement channels.
Pricing Analysis
REACH and RoHS compliance dictates the pricing tier structure across European precision-equipment procurement, filtering non-compliant Asian suppliers and creating qualified-supplier premiums for compliant manufacturers. Pricing stratifies across AEC-Q200-certified automotive, MIIT-mandated GB-standard telecommunications, and sub-cent consumer wearable tiers. Cost compression in 32.768 kHz laser-trimmed blanks intensifies because depreciation cycles outpace process evolution. Chinese ODMs exhibit highest price sensitivity; German automotive tier-1s accept premium positioning for JIS-documented stability specifications.
Supply Chain Analysis
High-purity synthetic quartz crucible-growth capacity in Japan and China anchors resonator feedstock availability, exposing buyers to geographic concentration risk. Manufacturing draws from Japanese ceramic formulation expertise, Chinese packaging clusters in Jiangsu and Zhejiang, and Taiwanese CMOS foundry partnerships for MEMS devices. Single-source vulnerability concentrates in alpha-quartz blank supply. Distribution runs through Arrow and Avnet for mid-volume industrial accounts, with direct multi-year contracts dominating automotive OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive electrode deposition expertise and AEC-Q200 certification infrastructure represent scarce capabilities that constrain supply pool expansion. Few manufacturers possess both ceramic formulation mastery and automotive qualification documentation.
For Market Incumbents: Fortify automotive-grade supply relationships through dedicated resonator fab capacity additions in Nagoya-area corridors, while accelerating MEMS oscillator R&D to counter silicon substitution threats in TWS earbud segments. JIS frequency-stability documentation investments deepen Toyota and Honda tier-1 lock-in against emerging Chinese competitors. For New Entrants and Emerging Players: Anchor in India's PLI scheme incentives for semiconductor assembly and test, where resonator packaging investments serve domestic smartphone and automotive module production with limited incumbent presence. Radiation-tolerant oscillator development for low-earth-orbit satellite ground terminals offers defense-aerospace supply tier access previously closed to commercial vendors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underoptimized frequency-control divisions lacking automotive certification focus. Long-term viability hinges on dual carbon alignment in crystal-growing operations as China's MEE enforces carbon-intensity caps. Watch for renewable-powered sintering operation deployments as inflection indicator for first-mover advantage capture.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Certification Investment | Automotive ECU proliferation requires 18-24 month qualification cycles that lock out commercial-grade competitors. |
| MEMS Foundry Partnership | CMOS integration enables sub-millimeter form factors for Samsung and South Korean TWS manufacturers. |
| Dual Carbon Sintering Transition | MEE carbon-intensity caps on crystal-growing furnaces favor renewable-powered operations in Jiangsu clusters. |
| Satellite Timing Module Development | Defense-aerospace tiers for low-earth-orbit ground terminals command radiation-tolerant oscillator premiums. |
| India PLI Packaging Investment | Domestic smartphone and automotive module production absorbs resonator assembly capacity near demand. |
Research Methodology
A standing panel of automotive tier-1 procurement managers, telecommunications equipment planners, resonator manufacturing engineers, and component distribution executives provided ongoing calibration against secondary validation from MIIT GB standard documentation, METI JIS compliance filings, customs trade data, and SEC 10-K disclosures from listed frequency-control specialists. Bottom-up unit demand modeling and top-down value aggregation triangulated across these sources.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include product architecture, application tier, frequency band, and end-user procurement channel. CAGRs derived from historical trajectory analysis and forward-looking capacity announcements, with specific inputs from AEC-Q200 certification timeline data and 5G base station deployment schedules.
Decision-makers should treat outputs as directional under assumptions of sustained automotive ECU proliferation and continued MEMS substitution in consumer wearables; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation enforcement intensity and dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Toroid Inductor Market
RF Components
UHF RFID Inlays Market
RF Components
433MHz Active RFID Reader Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
RF Tunable Filters Market
RF Components
RF Transceiver Chip Market
RF Components
Digital Phase Shifter Market
RF Components
5G Driver Amplifier Market
RF Components
Smart Antenna Market
RF Components
Embedded Antenna Systems Market
RF Components
Millimeter Wave Equipment Market
RF Components
Phase Shifters Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
Global Gan RF Devices Market
RF Components
Global RF Transceiver Market