
 Reverse Logistics for Reusable Packaging and Containers Market | 2026-2036
Reverse Logistics for Reusable Packaging and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Logistics for Reusable Packaging and Containers Market Insights
E-commerce fulfillment centers are rotating demand toward automated collection stations and third-party logistics providers for container recovery. CHEP leverages its global pallet pool to anchor network density across retail supply chains. IFCO Systems competes through specialized plastic crate washing and tracking infrastructure in fresh produce logistics. Schoeller Allibert dominates European bulk container standardization with manufacturing scale that sustains margin pools in automotive and chemical applications.
Reverse logistics for reusable packaging and containers encompasses the collection, inspection, cleaning, repair, and redistribution of multi-trip transport items such as plastic crates rated for 100+ use cycles, steel drums meeting UN dangerous goods specifications, and ISPM-15 compliant wooden pallets. The primary commercial purpose centers on replacing single-use expendable packaging with tracked, sanitized assets that circulate through closed-loop or open-pool systems. Plastic crates lead container type volumes due to food safety compliance and RFID traceability integration, while automated collection stations represent the fastest-growing return method as labor costs rise and retail footprint shrinks. Inspection and repair services command the highest margin pools within service offerings because asset life extension directly reduces capital replacement frequency for pool operators.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance standards shape product design and washing protocol requirements across European operations. FDA food contact surface regulations and EPA wastewater discharge permits govern sanitization chemistry and effluent treatment in United States-based cleaning facilities. Stakeholders must monitor how extended producer responsibility frameworks expand collection infrastructure mandates and whether pooling operators absorb compliance costs or pass them through per-trip pricing.
Market Dynamics
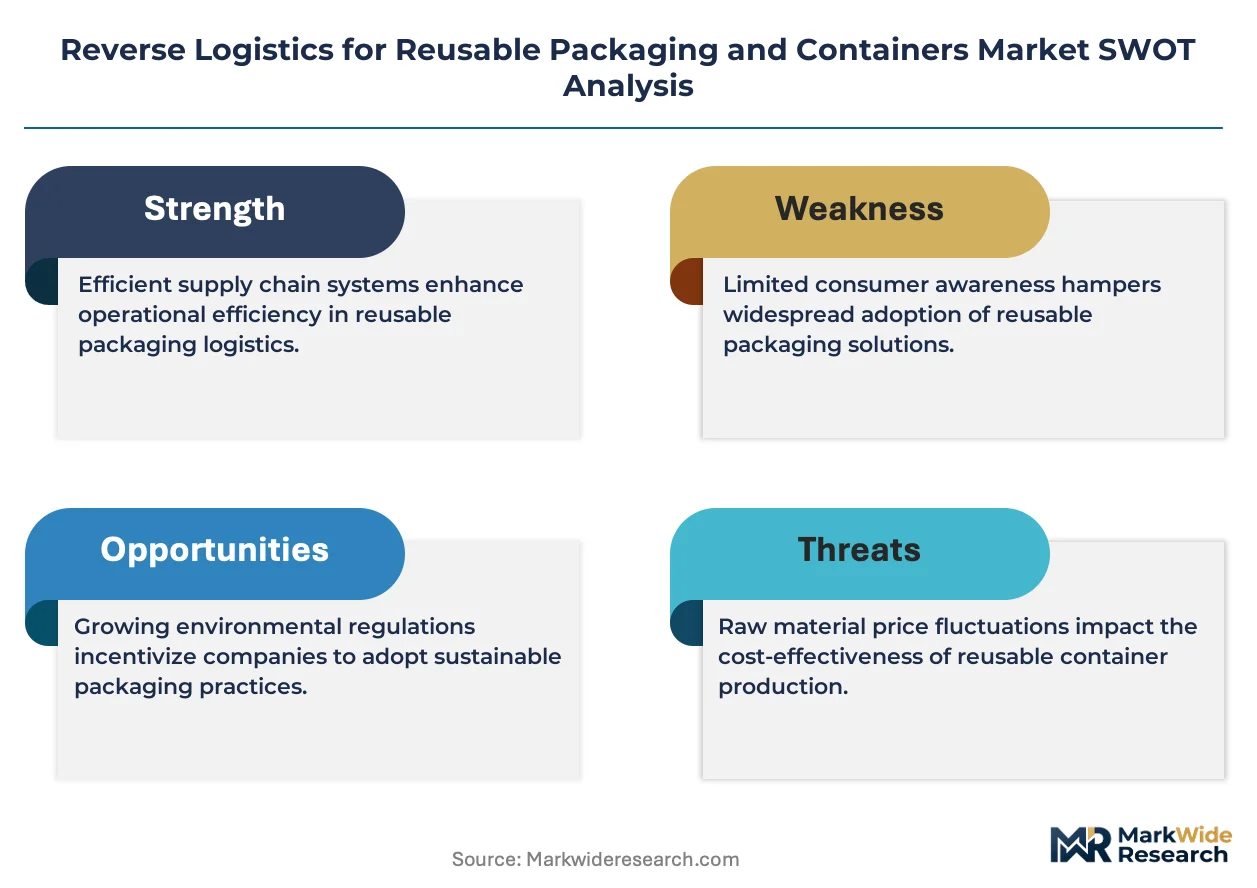
The EU Packaging and Packaging Waste Regulation is forcing producers to internalize collection infrastructure costs, collapsing the historical split between brand ownership and reverse logistics accountability across European supply chains.
Growth Catalysts
- Extended Producer Responsibility Mandates:The EU Packaging and Packaging Waste Regulation compels manufacturers to finance container recovery networks, accelerating capital deployment into automated sorting and washing facilities.
- Food Safety Compliance Integration:Fresh produce distributors now require RFID-traceable plastic crates that withstand 100+ wash cycles, linking container pooling directly to retail procurement specifications.
- Germany:Dense pooling networks in the Rhine-Ruhr and Bavarian logistics corridors concentrate standardized crate demand, generating route density that supports dedicated reverse logistics infrastructure.
Market Restraints
- Capital Intensity of Washing Infrastructure:Automated crate sanitization systems require stainless steel construction and EPA-compliant wastewater treatment, compressing returns for mid-scale operators.
- Resin Price Volatility:Polypropylene and high-density polyethylene feedstock costs fluctuate with petrochemical margins, destabilizing per-trip pricing models for plastic container pools.
- REACH Chemical Restrictions:ECHA limitations on sanitizing agents and coating chemistries constrain washing protocol flexibility, extending cycle times for compliant facilities.
Strategic Opportunities
- Pharmaceutical Cold Chain Expansion:Temperature-validated reusable shippers for biologics distribution represent an underpenetrated application with premium per-trip economics.
- CSRD Reporting Requirements:Corporate Sustainability Reporting Directive disclosure mandates create procurement preference for pooled packaging with verified carbon footprint tracking.
- Robotics-Enabled Collection Convergence:Automated guided vehicles integrated with computer vision sorting are compressing labor requirements at retail return points.
Industry Challenges
- Asset Tracking Interoperability:Pooling operators struggle to integrate proprietary RFID systems with customer ERP platforms, delaying invoice reconciliation and cycle visibility.
- Sanitization Chemistry Certification:FDA food contact surface approvals and EPA effluent permits require 18-24 month validation timelines for novel washing agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Logistics for Reusable Packaging and Containers Market |
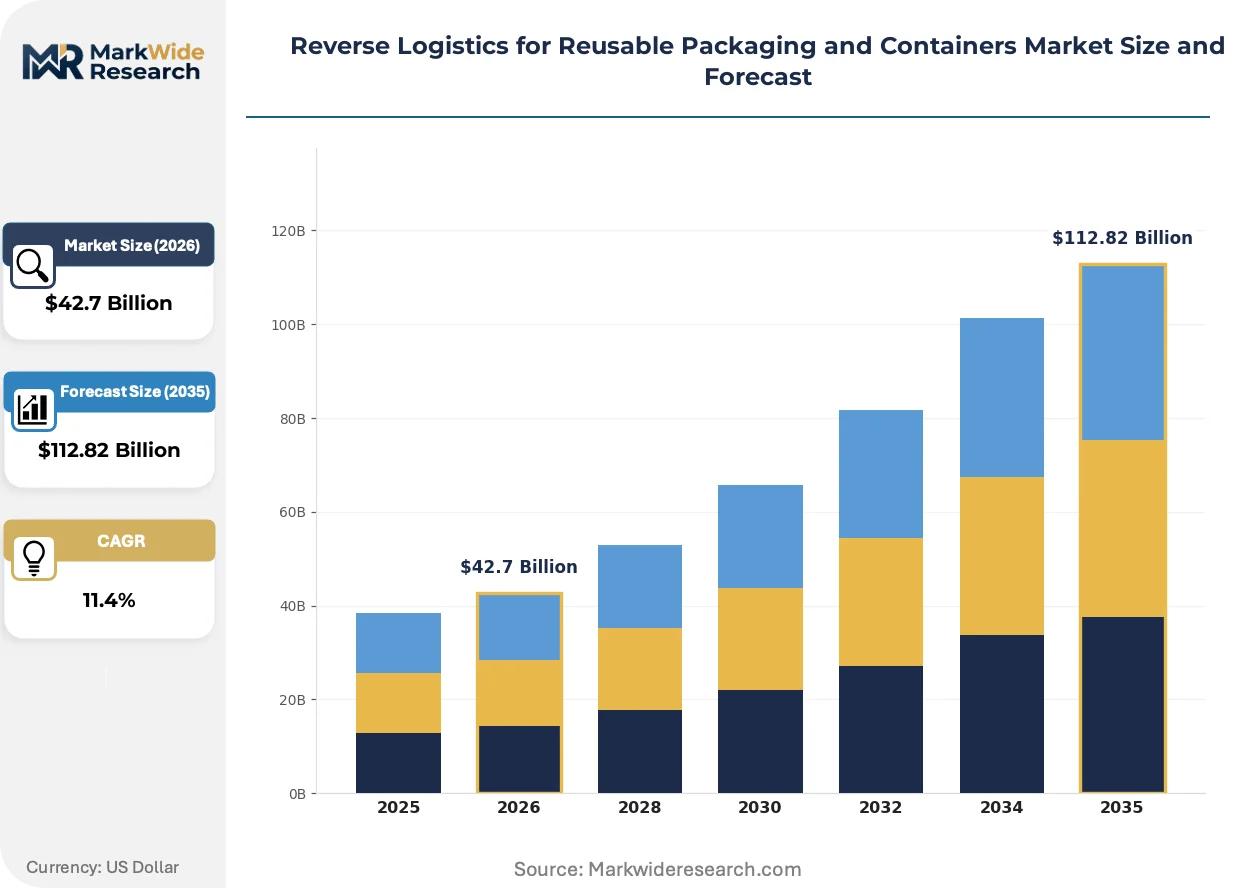
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $112.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Plastic Crates, Metal Drums, Glass Bottles, Wooden Pallets, Bulk Bins End User Industry: Food Processing, Consumer Goods, Pharmaceuticals, Electronics Assembly, Chemical Manufacturing Return Method: Direct Pickup, Drop-Off Points, Third-Party Logistics, Automated Collection Stations Service Offering: Inspection and Repair, Cleaning and Sanitization, Inventory Management, Transportation Coordination, Waste Reduction Consulting |
| Companies Covered | CHEP, IFCO Systems, Tosca, ORBIS Corporation, Schoeller Allibert, Cabka, Euro Pool System, Tri-Wall Circular, Rehrig Pacific Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Logistics for Reusable Packaging and Containers Market Trends and Innovations
Digital tracking infrastructure and automated material handling are compressing the labor component of container recovery while regulatory disclosure requirements embed packaging circularity into procurement scorecards.
Blockchain-enabled provenance tracking is decomposing opacity in multi-operator pool networks. Third-party logistics providers running shared crate circuits now deploy distributed ledger systems to record custody transfers, wash cycle counts, and damage assessments. Retailers in France and the Netherlands are piloting these platforms to satisfy CSRD supply chain transparency requirements, collapsing the audit burden of manual chain-of-custody documentation.
REACH chemical compliance standards are tightening effluent discharge thresholds for washing facilities. ECHA's 2023 updates to persistent organic pollutant restrictions now capture certain quaternary ammonium sanitizers used in crate cleaning. German pooling operators near the Dutch border are retrofitting wastewater treatment with membrane bioreactor systems to maintain operating permits, compressing margin pools for facilities without capital reserves.
Foodservice distributors are consolidating supplier relationships around full-service packaging management contracts. Large contract catering operators now bundle container supply, recovery, and sanitization into single-source agreements rather than managing asset pools internally. This concentration is most visible in the United Kingdom, where Sodexo and Compass Group have shifted procurement toward integrated pooling providers, displacing fragmented local crate rental arrangements.
Reverse Logistics for Reusable Packaging and Containers Market Segmentation
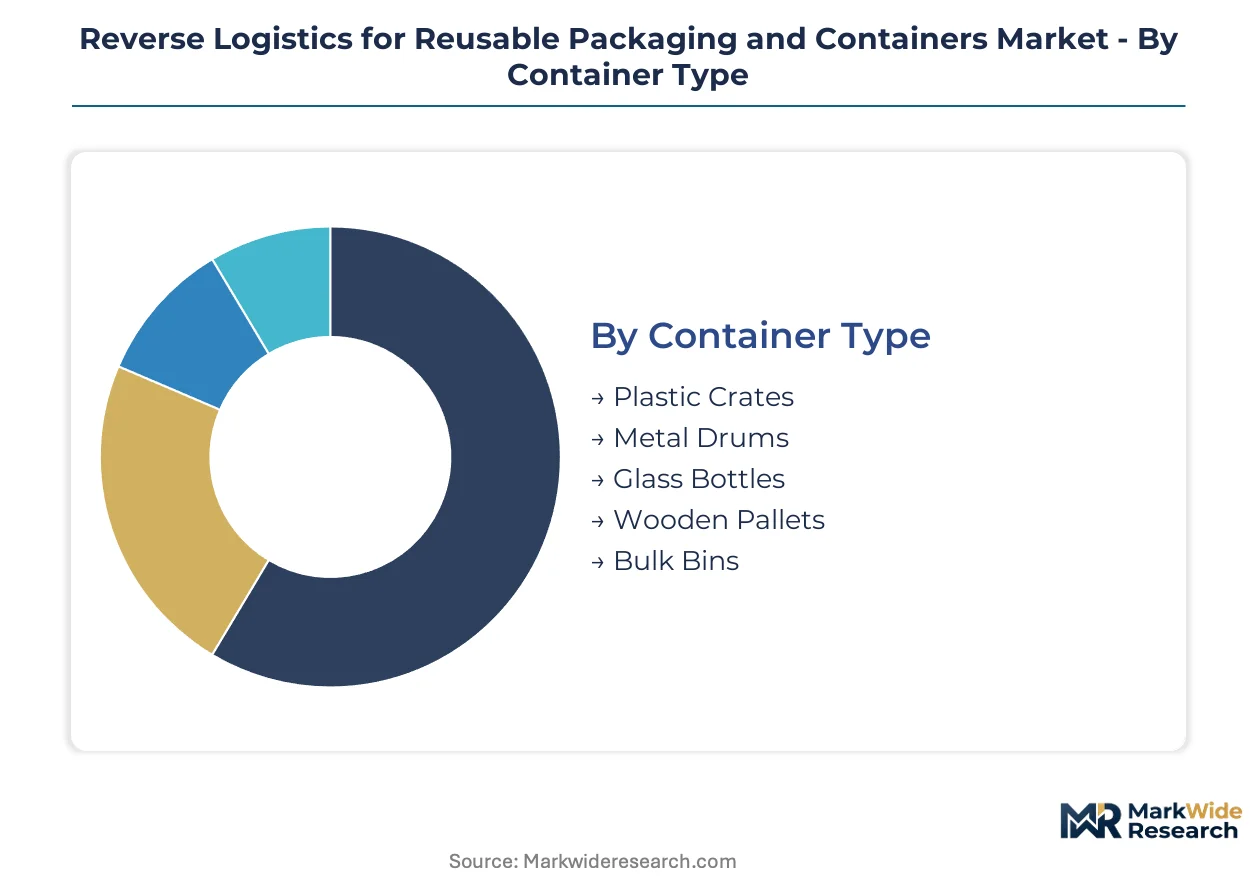
Reverse logistics operators configure service portfolios around container durability profiles and regulatory washing mandates. Segment boundaries blur where food safety compliance intersects with automated handling infrastructure.
Container Type:
German pooling networks concentrate standardized plastic crate circuits domestically, while bulk bin demand spreads across export-heavy automotive supply chains into Eastern Europe.
- Plastic Crates:Polypropylene construction rated for 100+ wash cycles integrates RFID tags for traceability. Demand concentrates in fresh produce logistics across the Netherlands and Spain, driven by EU Packaging and Packaging Waste Regulation collection mandates.
- Metal Drums:Steel construction meeting UN dangerous goods specifications for chemical transport. German chemical manufacturing clusters along the Rhine-Ruhr corridor sustain dedicated drum reconditioning infrastructure.
- Glass Bottles:Returnable beverage packaging with deposit systems in Germany and Denmark.
- Wooden Pallets:ISPM-15 compliant heat-treated hardwood for international shipment.
- Bulk Bins:Collapsible HDPE containers for automotive parts distribution.
Plastic crates hold the largest share; momentum sits with bulk bins as automotive export volumes climb.
End User Industry:
Cost tier differentiation separates premium pharmaceutical cold chain requirements from standardized food processing volumes.
- Food Processing:Fresh produce distributors mandate RFID-traceable crates with documented sanitization records. French retail consolidation around Carrefour and E.Leclerc drives pooling contract concentration.
- Pharmaceuticals:Temperature-validated reusable shippers for biologics distribution require validated cold chain documentation. Belgian and Dutch distribution hubs serve as European consolidation points.
- Consumer Goods:Personal care and household product manufacturers.
- Electronics Assembly:ESD-safe containers for component transport.
- Chemical Manufacturing:UN-certified packaging for hazardous material circulation.
Food processing dominates current volumes; pharmaceuticals are expanding most quickly on per-trip premium economics.
Return Method:
Volume concentration favors automated handling where retail footprint compression eliminates manual sorting space.
- Automated Collection Stations:Computer vision sorting and AGV integration compress labor requirements. Pilot deployments in French hypermarkets address CSRD supply chain transparency mandates.
- Third-Party Logistics:Shared crate circuits operated by specialized reverse logistics providers. German 3PLs leverage route density across Bavarian logistics corridors.
- Direct Pickup:Scheduled collection from manufacturing or retail sites.
- Drop-Off Points:Consolidated return locations for small-volume generators.
Third-party logistics holds the largest share; automated collection stations gain share fastest on labor cost pressures.
Service Offering:
Margin tiering elevates inspection and repair above commodity transportation coordination.
- Inspection and Repair:Asset life extension through damage assessment and component replacement commands premium pricing. German operators sustain margin pools through automated crack detection systems.
- Cleaning and Sanitization:Stainless steel washing systems with EPA-compliant wastewater treatment. REACH chemical restrictions constrain protocol flexibility in facilities near Dutch border zones.
- Inventory Management:RFID-enabled tracking and pool optimization.
- Transportation Coordination:Route planning for empty container repositioning.
- Waste Reduction Consulting:Packaging circularity advisory for CSRD disclosure preparation.
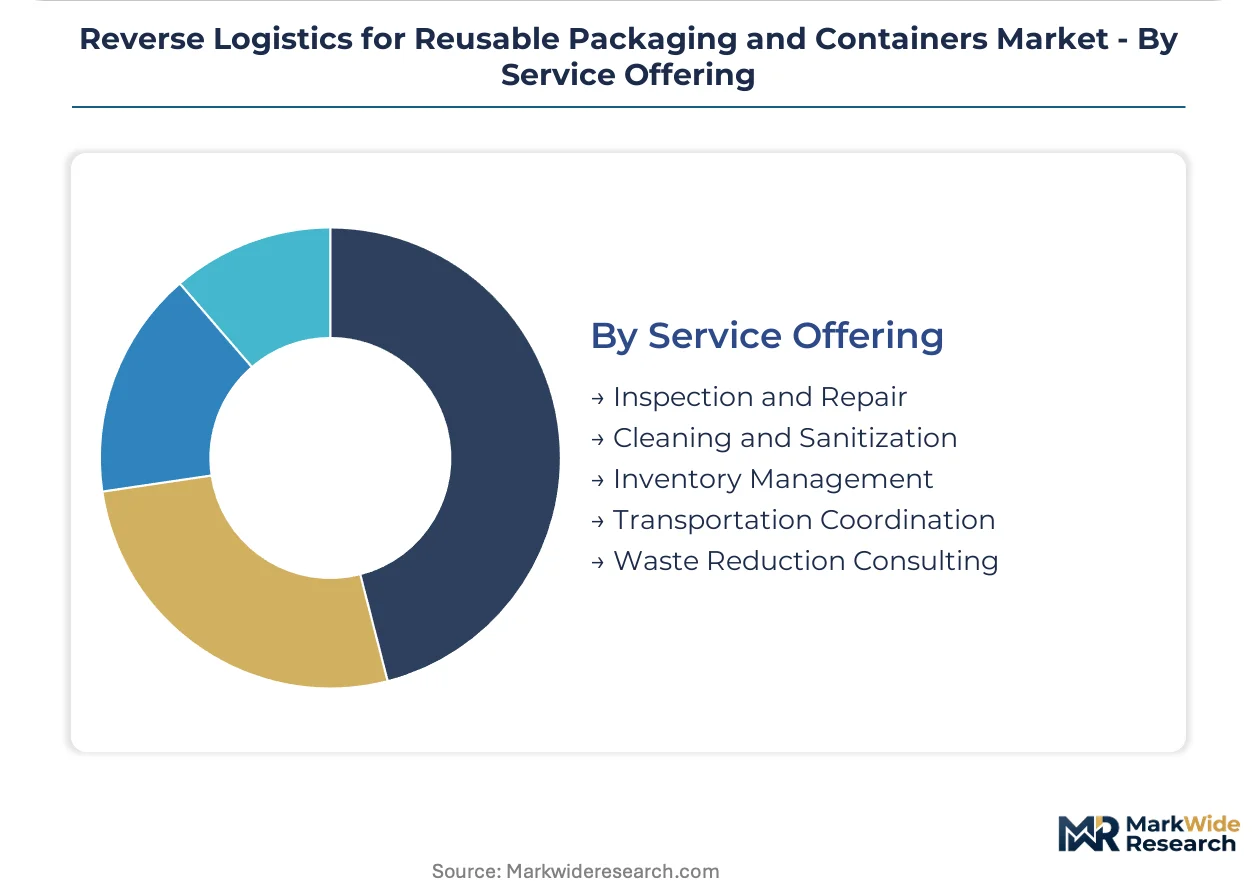
Inspection and repair holds the largest share; cleaning and sanitization shows steepest expansion trajectory on regulatory compliance intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites the Netherlands' central role in European reusable packaging circulation, while the Rhine-Ruhr rail corridor anchors Germany's dense pooling network density.
United States
Food safety compliance mandates from the FDA drive RFID-traceable plastic crate adoption across fresh produce distribution networks. EPA wastewater discharge permits govern sanitization facility siting near major agricultural processing zones. California's Central Valley hosts the largest concentration of automated washing infrastructure, serving the state's $50 billion produce sector.
Germany
Extended producer responsibility frameworks under the EU Packaging and Packaging Waste Regulation accelerate capital deployment into collection infrastructure. ECHA chemical compliance standards constrain washing protocol flexibility for pool operators. Bavarian logistics corridors between Munich and Nuremberg sustain dedicated reverse logistics networks for automotive and food processing container circuits.
Netherlands
CSRD supply chain transparency requirements push retailers toward blockchain-enabled provenance tracking for multi-operator pool networks. REACH effluent discharge thresholds drive membrane bioreactor retrofits at washing facilities near Belgian border zones. The Randstad conurbation concentrates third-party logistics providers operating shared crate circuits for European foodservice distribution.
France
Retail consolidation around major hypermarket chains drives pooling contract concentration for standardized container supply. ANSM and EFSA-aligned food contact surface regulations extend validation timelines for novel sanitizing chemistries. The Île-de-France region pilots automated collection stations with computer vision sorting to address labor cost pressures in urban logistics.
United Kingdom
Foodservice distributor consolidation shifts procurement toward integrated packaging management contracts bundling supply, recovery, and sanitization. The Environment Agency's industrial effluent permitting governs cleaning facility operations. Midlands distribution hubs serve as consolidation points for pooled container networks spanning grocery and contract catering supply chains.
Reverse Logistics for Reusable Packaging and Containers Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The market structure concentrates around three to five dominant pool operators with global pallet and crate networks, while mid-scale regional players occupy specialized end-use niches. Strategic archetypes include asset-heavy pooling incumbents, third-party logistics integrators, and equipment manufacturing specialists. Competitive moves center on network density expansion through strategic partnerships and automated handling technology licensing.
Within the asset-heavy pooling tier, CHEP and IFCO Systems exemplify scale-driven operators with established infrastructure footprints. Schoeller Allibert occupies a position among European manufacturing specialists with standardization capabilities. These three entities represent the dominant competitive anchors across retail supply chain, fresh produce logistics, and industrial bulk container applications respectively.
| Leading Market Players |
|---|
| CHEP |
| IFCO Systems |
| Tosca |
| ORBIS Corporation |
| Schoeller Allibert |
| Cabka |
| Euro Pool System |
| Tri-Wall Circular |
| Rehrig Pacific Company |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for polypropylene resin stocks anchor per-trip pricing volatility across European pooling networks, compressing margin buffers for operators without backward integration into polymer supply. This lead-time exposure concentrates pricing power with German and Dutch operators holding strategic resin reserves, while mid-scale competitors absorb feedstock cost spikes through contract renegotiation.
Pricing Analysis
Volume-discount tiering structures separate premium RFID-traceable crate circuits from standard washing-only services and economy-grade bulk bin repositioning. Price differentiation rests on certification grade (EU food contact compliance vs industrial handling) and volume scale (national retail chains vs regional distributors). Pricing pressure stems from REACH-compliant wastewater treatment capital requirements, which compress returns for facilities without membrane bioreactor infrastructure. Small-volume foodservice distributors exhibit highest price sensitivity; pharmaceutical cold chain operators show least.
Supply Chain Analysis
Just-in-time resin procurement dominates German and Dutch pooling networks, though strategic stockpiling of FDA-compliant sanitizing chemistries is emerging near California's Central Valley washing clusters. Geographic supply concentration centers on Germany (pooling network infrastructure), the Netherlands (automated handling equipment), and China (polypropylene feedstock). Raw material dependencies include polypropylene resin, stainless steel washing system components, and RFID tracking hardware. Supply chain risk manifests as single-source vulnerability for specialized membrane bioreactor membranes. Distribution runs through third-party logistics providers operating shared crate circuits across Rhine-Ruhr and Bavarian logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation mandates are accelerating capital deployment into automated collection infrastructure, creating a high-growth disruption window for operators with pre-positioned washing assets.
For Market Incumbents: Secure route density in Rhine-Ruhr and Bavarian logistics corridors through exclusive contracts with Carrefour and E.Leclerc retail consolidation. Invest in membrane bioreactor wastewater treatment to defend margin position against REACH effluent threshold tightening. Vertical integration into RFID hardware sourcing reduces tracking system cost exposure. For New Entrants and Emerging Players: Differentiate on pharmaceutical cold chain temperature validation capabilities, the most penetrable premium segment with underdeveloped reusable shipper infrastructure. Target Belgian and Dutch distribution hubs serving biologics consolidation points. Go-to-market through full-service packaging management contracts bundling supply, recovery, and sanitization. For Investors and Strategic Acquirers: Carve-out targets emerge from foodservice distributor captive packaging pools undergoing procurement consolidation. Long-term viability favors operators with CSRD-compliant carbon footprint tracking infrastructure. Watch for ECHA chemical restriction updates as inflection signal for washing facility retrofit requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Collection Station Deployment | French hypermarket pilots with computer vision sorting address CSRD transparency mandates and labor cost compression. |
| Backward Integration into Resin Supply | German operators securing polypropylene feedstock contracts insulate per-trip pricing from petrochemical margin volatility. |
| Blockchain-Enabled Provenance Tracking | Dutch and French retailers pilot distributed ledger systems to collapse manual chain-of-custody audit burdens. |
| Membrane Bioreactor Retrofit | Facilities near Dutch border zones invest to maintain operating permits under REACH effluent discharge tightening. |
| Pharmaceutical Cold Chain Validation | Belgian distribution hubs develop temperature-validated reusable shippers for biologics premium per-trip economics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, ECHA chemical restriction updates, and pooling operator financial disclosures. Interviews with logistics corridor managers, washing facility operators, retail procurement directors, and third-party logistics contract specialists anchor demand-side validation. Secondary sources include customs trade data for container import flows, EPA wastewater discharge permit databases, and FDA food contact surface approval records. Bottom-up service volume estimates triangulate against top-down market sizing from capital expenditure disclosures across automated handling infrastructure.
Segmentation dimensions modeled span container type (plastic crates, metal drums, bulk bins), end-use industry (food processing, pharmaceuticals, automotive), return method (automated stations, third-party logistics, direct pickup), and service offering tier (inspection/repair, cleaning/sanitization, inventory management). CAGRs derive from regression analysis of historical pooling contract growth rates against regulatory mandate implementation timelines. Industry-specific forecast inputs incorporate EU Packaging and Packaging Waste Regulation collection infrastructure deployment schedules and REACH chemical compliance cost pass-through assumptions.
Material uncertainties — resin price volatility, ECHA sanitizer restriction scope expansion, retail footprint compression velocity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and pooling operator pricing power retention. Revision becomes warranted when automated collection station deployment rates cross thresholds that fundamentally alter labor cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Reusable Food Wrap Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Refillable and Reusable Packaging Market