
 Global Recyclable Packaging Market | 2026-2036
Global Recyclable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recyclable Packaging Market Outlook
The gap between premium certified-recyclable packaging and commodity-grade alternatives is expanding. Amcor plc leverages its global manufacturing footprint to supply pharmaceutical and food-grade barrier films that meet stringent recyclability protocols. Tetra Pak anchors the aseptic carton segment through integrated paperboard and aluminum sourcing that sustains closed-loop collection systems in European and Latin American markets. DS Smith competes aggressively in the e-commerce corrugated channel, where box recyclability has become a non-negotiable procurement criterion for major retail platforms.
Recyclable packaging comprises materials and formats designed for recovery, reprocessing, and reintroduction into manufacturing supply chains without substantial quality degradation. Primary specifications include fiber-based substrates exceeding 80% post-consumer content, mono-material polymer structures compatible with existing mechanical recycling infrastructure, and aluminum alloys sorted through eddy-current separation at material recovery facilities. Cardboard dominates volume across food and beverage end users where lightweighting and printability drive selection, while bioplastics represent the fastest-growing material type as industrial composting infrastructure expands in Northern Europe and select Asian markets. Glass containers maintain premium positioning in personal care and healthcare segments where chemical inertness and infinite recyclability justify higher unit costs and logistics expenditure.
The EU Green Deal and REACH frameworks mandate recyclability-by-design criteria that reshape product development cycles for suppliers seeking European market access. The EPA and state-level extended producer responsibility legislation in California and New York are converging toward similar material recovery targets that will determine competitive eligibility in North American procurement channels. Stakeholders must monitor divergence between mechanical and chemical recycling pathway economics as policy incentives tilt toward technologies with divergent capital intensity and feedstock requirements.
Market Dynamics
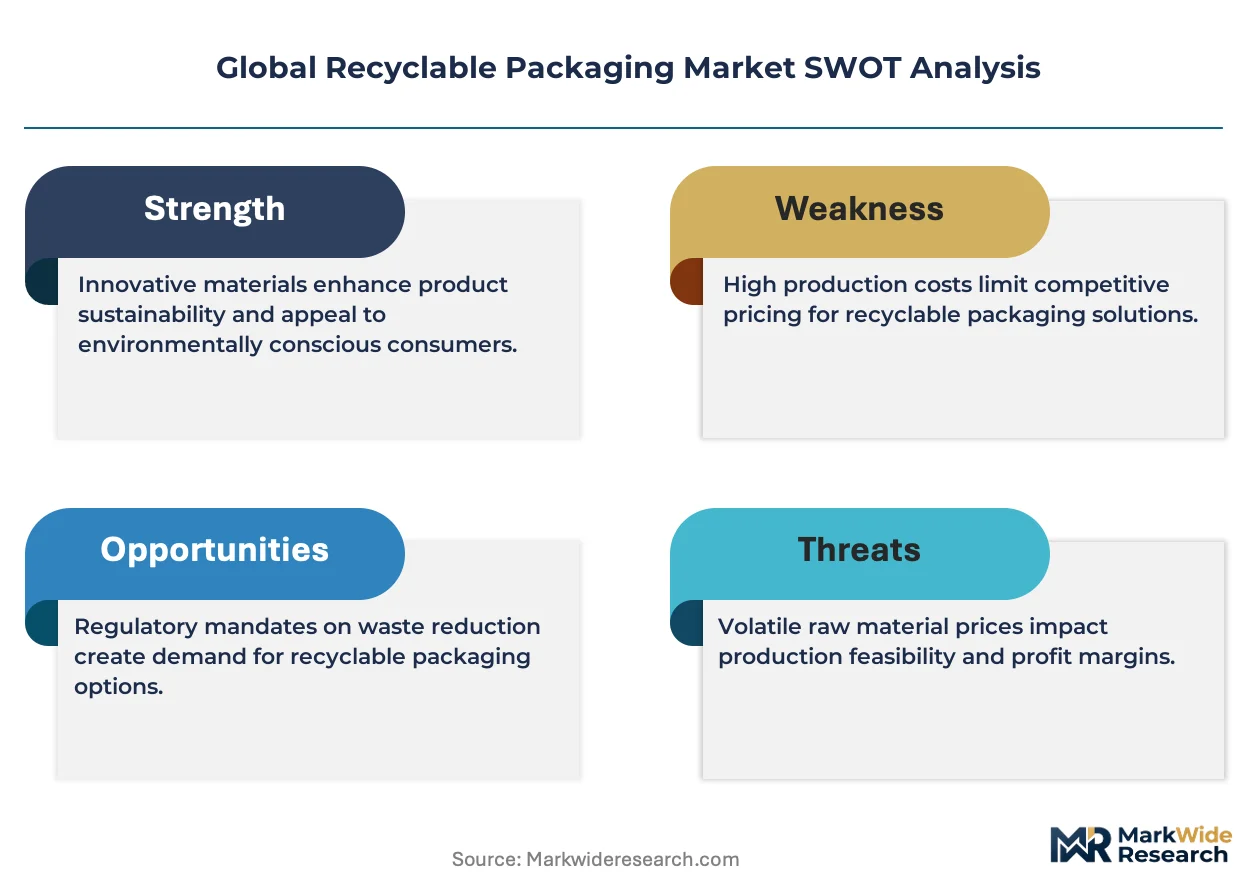
The EU Green Deal's recyclability-by-design mandates are forcing material substitutions across pharmaceutical and food-grade packaging supply chains, compressing development cycles and disqualifying legacy multi-layer structures from European procurement channels.
Growth Catalysts
- Extended Producer Responsibility frameworks:Germany's Verpackungsgesetz and California's SB 54 impose recovery targets that redirect procurement toward mono-material polymer structures and fiber-based substrates compatible with existing mechanical recycling infrastructure.
- Industrial composting infrastructure expansion:Northern European markets including Sweden and the Netherlands are deploying anaerobic digestion facilities that process PLA and PHA bioplastics, creating viable end-of-life pathways for food-contact applications previously limited to petroleum-based films.
- E-commerce platform procurement mandates:Amazon and Zalando have embedded recyclability scoring into supplier qualification protocols, converting corrugated box specifications from negotiable attributes into non-negotiable entry criteria for third-party marketplace access.
Market Restraints
- Mechanical recycling contamination thresholds:Existing MRF infrastructure cannot process adhesive-labeled flexible films or metallized multi-layer pouches, limiting viable feedstock supply for post-consumer recycled content targets mandated by EU Single-Use Plastics Directive.
- Aluminum alloy sorting constraints:Eddy-current separation equipment at European material recovery facilities lacks precision to distinguish food-grade from non-food-grade aluminum streams, forcing downcycling and quality degradation in closed-loop beverage can systems.
- Bioplastic feedstock cost volatility:Agricultural substrate prices for corn-based PLA and sugarcane-based PE fluctuate with commodity crop markets, compressing margin structures for converters attempting to price-compete against stabilized fossil-derived polyethylene supply chains.
Strategic Opportunities
- Chemical recycling pathway commercialization:Pyrolysis and depolymerization technologies capable of processing mixed polymer waste streams are achieving scale in the Netherlands and Belgium, enabling recovery of flexible packaging formats currently excluded from mechanical recycling economics.
- Healthcare aseptic barrier films:Hospitals and pharmaceutical distributors in Switzerland and Japan are piloting mono-material polypropylene syringe and vial packaging that maintains sterility assurance while satisfying emerging recyclability protocols from the country's national pharmaceutical regulator.
- Digital watermarking integration:GS1-standardized invisible markers embedded in printed packaging substrates are enabling AI-powered sortation at MRFs, with pilot deployments in France and the United Kingdom demonstrating 15-20 point improvements in polymer identification accuracy.
Industry Challenges
- Food-contact migration testing timelines:Novel barrier coatings and adhesive formulations require 18-24 month safety assessments under EFSA and FDA protocols, delaying market entry for redesigned recyclable structures even after technical validation.
- Legacy equipment retrofit requirements:Converting from multi-layer extrusion lines to mono-material production systems demands capital expenditure for new die heads and cooling configurations, straining mid-tier converters with constrained balance sheet capacity.
- Collection infrastructure fragmentation:Curbside recycling program heterogeneity across German municipalities creates compliance complexity for national brands attempting uniform packaging specifications, forcing SKU proliferation and supply chain inefficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recyclable Packaging Market |
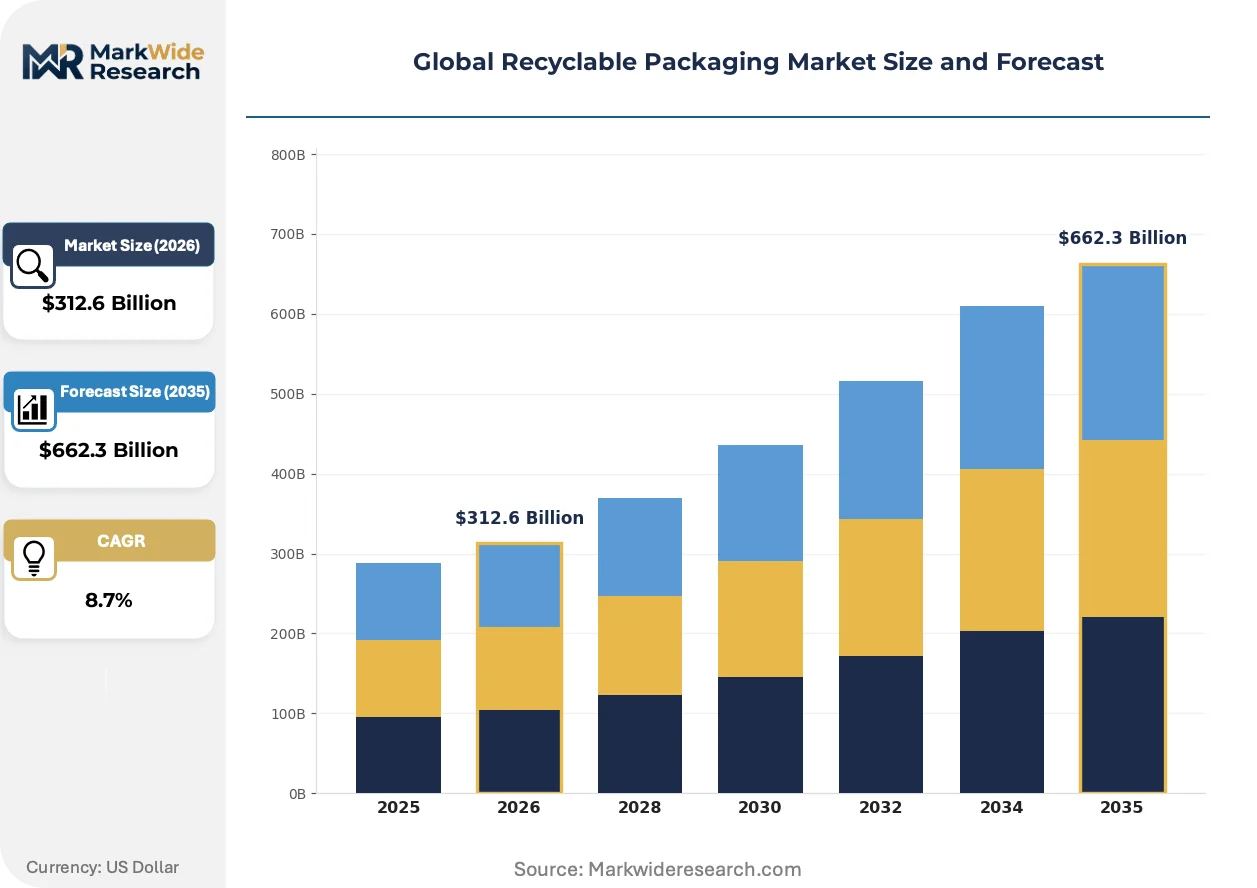
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Glass, Bioplastics, Aluminum End User: Food & Beverage, Personal Care, Healthcare, Retail Packaging Format: Bags, Containers, Boxes, Wraps Distribution Channel: E-commerce, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Amcor plc, Tetra Pak, Sealed Air, Ball Corporation, Mondi, DS Smith, Huhtamaki Oyj, WestRock Company, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recyclable Packaging Market Strategic Shifts
Active developments across material science, regulatory compliance technology, and procurement intelligence systems are compressing traditional packaging development cycles and redefining competitive differentiation criteria.
Mono-material polypropylene barrier films with enhanced oxygen and moisture resistance are overtaking conventional multi-layer PET/PE/EVOH laminates in snack and dry food applications. Major European retail private-label programs have accelerated qualification timelines from 24 months to 8 months. This acceleration is overtaking incumbent suppliers dependent on legacy co-extrusion assets and proprietary adhesive intellectual property.
REACH Article 33 disclosure requirements and the EU Packaging and Packaging Waste Regulation are mandating recycled content verification through mass-balance accounting certified by third-party auditors. Chemical recyclers in Belgium and the Netherlands are deploying blockchain-traceable feedstock documentation to satisfy these protocols. Pharmaceutical and personal care brands with European distribution are reformulating around these requirements ahead of 2030 enforcement deadlines.
Retail buyers are consolidating supplier panels around integrated design-for-recyclability services rather than transactional material procurement. Major German and French supermarket chains now require packaging suppliers to provide lifecycle assessment data and MRF compatibility testing as standard contract terms. This consolidation is most visible in the fresh produce segment, where disposable tray specifications are being standardized across buying groups to achieve volume leverage and simplify reverse logistics.
Global Recyclable Packaging Market Segmentation
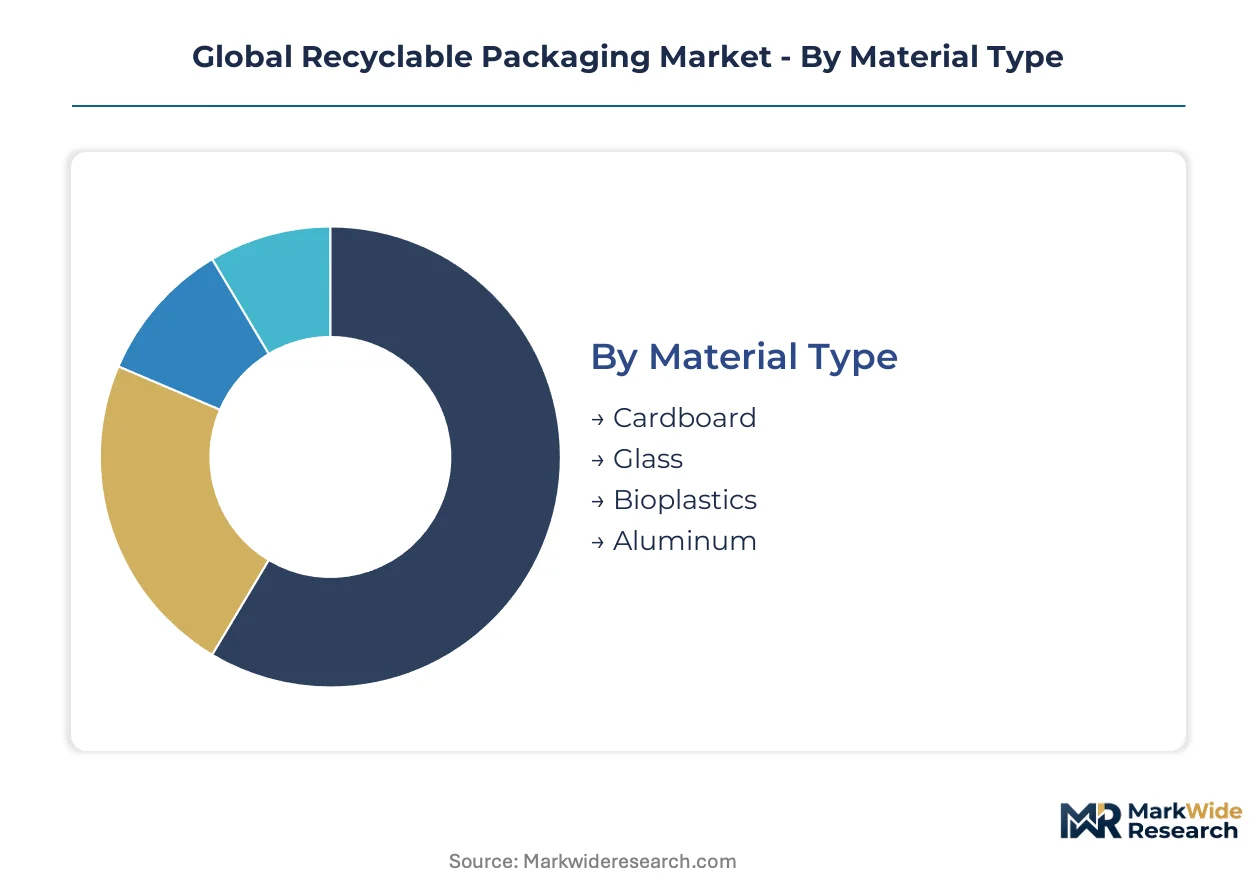
Recyclable packaging procurement decisions cascade through material specifications, end-use performance requirements, and channel-specific logistics constraints. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that reshape supplier competitive positioning.
Material Type:
The customization-to-standardization spectrum runs from engineered bioplastic compounds requiring composting infrastructure to commodity cardboard with universal MRF compatibility.
- Cardboard:Fiber-based substrates exceeding 80% post-consumer content dominate food and beverage applications where lightweighting and printability drive selection. Demand concentrates in Germany and the United States where extended producer responsibility frameworks have matured, though contamination from adhesive labels and food residue creates quality degradation in closed-loop systems.
- Bioplastics:PLA and PHA polymers derived from corn and sugarcane agricultural feedstocks represent the steepest expansion trajectory as industrial composting infrastructure deploys across Sweden and the Netherlands. Agricultural commodity price volatility compresses margin structures for converters attempting to price-compete against stabilized fossil-derived polyethylene supply chains.
- Glass:Chemically inert containers with infinite recyclability maintain premium positioning in personal care and healthcare segments where chemical resistance justifies higher unit costs and logistics expenditure.
- Aluminum:Eddy-current sortable alloys serve beverage and pharmaceutical barrier applications, though MRF separation equipment lacks precision to distinguish food-grade from non-food-grade streams.
Most installed capacity flows through cardboard. Expansion is steepest in bioplastics.
End User:
Application-driven performance requirements segment the market across contamination tolerance, barrier specifications, and regulatory scrutiny intensity.
- Food & Beverage:Aseptic carton formats with integrated paperboard and aluminum sourcing sustain closed-loop collection systems, while mono-material polypropylene barrier films displace multi-layer laminates in snack applications.
- Healthcare:Sterility assurance protocols and migration testing timelines under FDA and EFSA frameworks delay market entry for redesigned recyclable structures even after technical validation.
- Personal Care:Premium glass and aluminum formats dominate where chemical inertness and infinite recyclability support brand positioning.
- Retail:E-commerce platform procurement mandates from Amazon and Zalando have embedded recyclability scoring into supplier qualification protocols.
Food and beverage commands the largest volume share. Healthcare exhibits the most restrictive qualification barriers.
Packaging Format:
Format selection traces the tension between supply chain efficiency and end-of-life recovery pathway compatibility.
- Boxes:Corrugated specifications have converted from negotiable attributes into non-negotiable entry criteria for third-party marketplace access at major retail platforms.
- Containers:Rigid formats for beverage and personal care applications face downcycling constraints when alloy sorting precision fails at material recovery facilities.
- Bags:Flexible film recovery remains limited by mechanical recycling contamination thresholds for adhesive-labeled and metallized multi-layer structures.
- Wraps:Primary food-contact applications drive mono-material polymer development to satisfy EU Single-Use Plastics Directive requirements.
Boxes absorb the greatest capital investment. Bags face the steepest technical recovery challenges.
Distribution Channel:
Channel-specific logistics requirements and customer proximity dictate format standardization versus customization tradeoffs.
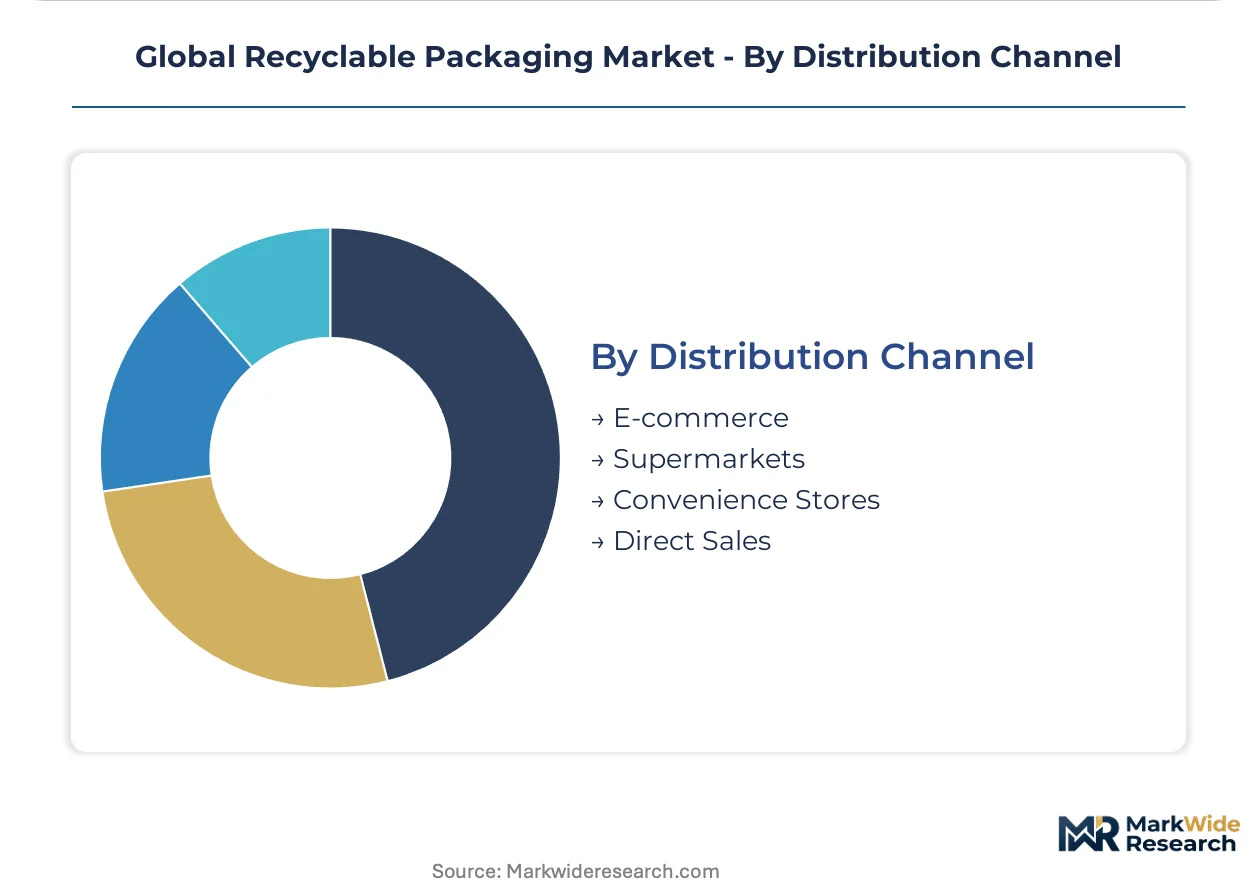
- E-commerce:Platform-embedded recyclability scoring and corrugated box mandates from Amazon and Zalando reshape supplier qualification protocols.
- Supermarkets:German and French retail chains require lifecycle assessment data and MRF compatibility testing as standard contract terms, consolidating supplier panels around integrated design services.
- Convenience Stores:Single-serve and on-the-go formats prioritize lightweighting and space efficiency over premium recyclability certifications.
- Direct Sales:Brand-controlled unboxing experiences enable customized specifications with higher post-consumer content and specialized recovery partnerships.
E-commerce channels impose the most stringent standardization requirements. Direct sales permits the greatest specification customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Verpackungsgesetz enforces stricter recovery targets than California's SB 54, yet both jurisdictions are redirecting procurement toward mono-material structures. China and the United States dominate absolute volume, while the Netherlands and Sweden pioneer bioplastic composting infrastructure.
United States
Amazon and Zalando procurement mandates convert corrugated specifications into non-negotiable marketplace entry criteria. California's SB 54 imposes recovery targets that redirect procurement toward fiber-based substrates. The Pacific Northwest hosts pilot deployments of AI-powered sortation systems demonstrating polymer identification accuracy improvements.
Germany
Extended producer responsibility frameworks under Verpackungsgesetz mature faster than neighboring jurisdictions. The EU Green Deal's recyclability-by-design criteria reshape product development cycles for suppliers seeking European market access. The Rhine-Ruhr industrial corridor concentrates closed-loop collection systems for beverage cartons and pharmaceutical barrier films.
China
E-commerce platform procurement mandates accelerate faster than retail channel standardization. National dual carbon goals and MIIT industrial policies tilt manufacturing investment toward recyclable material substitution. The Yangtze River Delta hosts integrated paperboard and aluminum sourcing operations sustaining regional closed-loop systems.
Netherlands
Industrial composting infrastructure for PLA and PHA bioplastics deploys ahead of Northern European peers. REACH Article 33 disclosure requirements mandate recycled content verification through mass-balance accounting. Chemical recyclers in Rotterdam-Antwerp corridor achieve scale in pyrolysis and depolymerization technologies processing mixed polymer waste streams.
Sweden
Anaerobic digestion facilities process bioplastics for food-contact applications previously limited to petroleum-based films. EFSA protocols govern migration testing timelines for novel barrier coatings delaying market entry. The Stockholm-Uppsala cluster concentrates pharmaceutical packaging development qualifying under emerging national regulator protocols.
Global Recyclable Packaging Market Competitive Environment
Top-tier vendors anchor premium certified-recyclable supply, while mid-tier converters struggle with legacy equipment retrofit requirements. The market exhibits tiered concentration around integrated material suppliers, specialized barrier film developers, and corrugated channel specialists. Three archetypes dominate: global footprint multinationals with pharmaceutical-grade certification, regional paperboard integrators with closed-loop collection partnerships, and bioplastic pioneers with captive agricultural feedstock arrangements. Competitive moves concentrate on M&A for technology access and strategic partnerships for composting infrastructure deployment.
Within the global multinational tier, Amcor plc and Tetra Pak occupy positions exemplifying divergent strategic anchoring. Amcor leverages manufacturing footprint breadth across pharmaceutical and food-grade barrier film supply. Tetra Pak represents integrated paperboard-aluminum sourcing models sustaining closed-loop collection systems in European and Latin American markets. DS Smith sits within the corrugated channel specialist archetype where e-commerce platform mandates have converted box recyclability from negotiable attribute to procurement prerequisite.
| Leading Market Players |
|---|
| Amcor plc |
| Tetra Pak |
| Sealed Air |
| Ball Corporation |
| Mondi |
| DS Smith |
| Huhtamaki Oyj |
| WestRock Company |
| Ardagh Group |
| Others |
Value Chain & Pricing Dynamics
Old corrugated container price indices in Germany and the United States cascade through converter margins into three distinct pricing tiers for post-consumer content grades, with EU Green Deal compliance premiums widening spreads between certified-recyclable and commodity-grade supply.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for fiber-based substrates, compressing margin structures for European converters. Three-tier pricing structure across premium certified-recyclable, standard industrial-grade, and economy virgin-material levels stratifies procurement channels. Cost compression in bioplastics runs through agricultural feedstock volatility for corn-based PLA. Retail private-label buyers exhibit highest price sensitivity, while pharmaceutical qualification barriers protect premium tier margins.
Supply Chain Analysis
Single-source vulnerability sits with Swedish and Dutch industrial composting infrastructure for PLA and PHA bioplastics. Raw material sourcing draws from German recovered paper streams, Chinese integrated paperboard operations, and Brazilian sugarcane ethanol feedstocks. Supply chain risk centers on eddy-current separation equipment precision gaps at European material recovery facilities. Distribution runs through German and French retail buying groups consolidating supplier panels around integrated design-for-recyclability services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recyclable packaging market represents a late-cycle quality story where EU Green Deal recyclability-by-design mandates and Amazon procurement protocols are shifting demand toward certified-recyclable specifications with verified mass-balance accounting.
For Market Incumbents: Hedge against chemical recycling pathway disruption by securing pyrolysis feedstock partnerships in the Netherlands and Belgium. Defend market position through backward integration into recovered paper collection networks in Germany. Certification investment for pharmaceutical-grade barrier films under EFSA protocols protects margin structures from mono-material polypropylene displacement. For New Entrants and Emerging Players: Enter via healthcare aseptic barrier film segments in Switzerland and Japan where sterility assurance requirements create qualification barriers for established suppliers. Target Swissmedic and PMDA pilot programs for mono-material polypropylene syringe packaging. White-space exists in digital watermarking integration for AI-powered MRF sortation, with GS1-standardized marker deployment as the go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters face legacy equipment retrofit requirements for mono-material production systems. Long-term viability favors integrated material suppliers with captive closed-loop collection partnerships over pure-play converters. Acquisition target archetype: regional paperboard integrators with German Verpackungsgesetz compliance infrastructure. Signal to watch is chemical recycling capacity utilization rates in the Rotterdam-Antwerp corridor as inflection indicator for mechanical recycling pathway displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Paper Collection | German Verpackungsgesetz compliance secures post-consumer content supply for premium tier positioning. |
| Chemical Recycling Capacity Buildout | Pyrolysis deployment in Belgium and Netherlands enables mixed polymer waste recovery currently excluded from mechanical economics. |
| Digital Watermarking Technology Licensing | GS1-standardized invisible markers embedded in French and UK pilot programs improve polymer identification accuracy at MRFs. |
| Pharmaceutical-Grade Certification Investment | EFSA and FDA migration testing timelines protect barrier film margins from commodity substitution in healthcare segments. |
| Industrial Composting Infrastructure Partnership | Anaerobic digestion facility access in Sweden and Netherlands creates viable end-of-life pathways for PLA and PHA bioplastics. |
Study Parameters
Coverage spans Germany, China, the United States, the Netherlands, and Sweden, with primary inputs from each market. Primary interviews combined packaging converter operations managers, retail category buyers at German and French supermarket chains, pharmaceutical regulatory affairs leads, and material recovery facility operators. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, EPA state-level extended producer responsibility legislation, MIIT industrial policy disclosures, and customs data on recovered paper trade flows. Bottom-up segment modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Granularity-level modeling deployed material type, end-use application, packaging format, and distribution channel dimensions at country-level resolution. CAGRs were derived through trend extrapolation of procurement mandate enforcement timelines and infrastructure deployment curves. Forecast inputs incorporated EU Green Deal recyclability-by-design implementation schedules and Amazon marketplace qualification protocol evolution across the projection horizon.
Inputs from German Verpackungsgesetz compliance databases and Chinese MIIT policy disclosures were available through the study window; gaps in real-time MRF sortation equipment deployment data introduce uncertainty bands around bioplastics recovery rate assumptions. Forecasts reflect documented assumptions on chemical recycling pathway economics and industrial composting infrastructure buildout trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Refillable and Reusable Packaging Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Water Bottle Market