
 Reusable Cold Chain Packaging Market | 2026-2036
Reusable Cold Chain Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Cold Chain Packaging Market Analytics
China is fragmenting as domestic manufacturers scale polyurethane molding capacity for pharmaceutical-grade insulated containers. Cryopak leverages vertically integrated foam production across North American facilities to sustain cost advantages in thermal pallet assembly. Intelsius competes through specialized qualification testing services that anchor long-term contracts with European vaccine distributors.
Reusable cold chain packaging comprises engineered thermal enclosures designed to maintain precise temperature bands, typically incorporating vacuum-insulated panels, phase-change materials, or expanded polyurethane cores with protective outer shells of polypropylene or aluminum. These systems serve pharmaceutical, food, and biotechnology supply chains where temperature excursions compromise product integrity or regulatory compliance. Insulated containers dominate current revenue pools due to their deployment flexibility across last-mile and inter-facility transfers, while thermal pallets capture expanding share as consolidated biologics shipments require pallet-scale thermal mass. Polyurethane leads material selection for its thermal resistance-to-weight ratio, though polypropylene outer casings are displacing alternatives where durability and cleaning cycles matter.
FDA validation requirements for thermal packaging in pharmaceutical distribution shape product development priorities, particularly around qualification documentation and reproducible performance. The EU Green Deal and REACH chemical restrictions are redirecting material innovation toward recyclable phase-change compounds and bio-based foam alternatives. EMA guidelines on good distribution practice reinforce inspection-ready traceability features that differentiate compliant suppliers. Stakeholders must weigh capital intensity against per-use economics as regulatory pressure tightens on single-use alternatives.
Market Dynamics
Pharmaceutical distribution networks are consolidating temperature-controlled logistics around reusable systems as regulators tighten restrictions on hydrofluorocarbon-based cooling methods. The EU F-Gas Regulation and parallel frameworks are forcing rapid substitution of active refrigeration with passive thermal protection, compressing supplier qualification timelines and reshaping procurement criteria.
Growth Catalysts
- EMA Good Distribution Practice:Inspection-ready traceability requirements are mandating documented thermal performance records, pulling vaccine distributors toward qualified reusable packaging with embedded data loggers.
- Biologics shipment consolidation:Pallet-scale thermal mass systems are capturing share as consolidated biologics loads replace fragmented parcel shipments in inter-facility transfers.
- Germany's vaccine logistics hub concentration:Cold storage infrastructure clustering around Frankfurt and Munich is concentrating demand for high-cycle reusable containers with rapid turnaround protocols.
Market Restraints
- Polyurethane feedstock volatility:Isocyanate and polyol price swings are compressing margins for molded insulated container producers without captive chemical supply.
- Qualification documentation burden:FDA thermal validation protocols require extensive stability testing, extending product development cycles to 18-24 months for new designs.
- Single-use gel pack substitution:Low-cost disposable phase-change materials retain share in non-regulated food distribution, capping price realization in adjacent segments.
Strategic Opportunities
- India's cold chain infrastructure gaps:CDSCO-regulated vaccine distribution expansion is creating first-mover advantage for reusable system providers with local service networks.
- WHO prequalification pathway:Performance standards for temperature-controlled transport are opening institutional procurement channels for validated reusable designs.
- Bio-based foam convergence:Integration of mycelium-derived insulation with conventional polypropylene shells is addressing REACH chemical restrictions while maintaining thermal performance.
Industry Challenges
- Thermal engineer scarcity:Specialized expertise in phase-change material formulation and vacuum panel integration is concentrated among legacy aerospace suppliers, constraining R&D scaling.
- Cross-border qualification reciprocity:Divergent FDA and EMA documentation requirements force redundant testing protocols, inflating compliance costs for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Cold Chain Packaging Market |
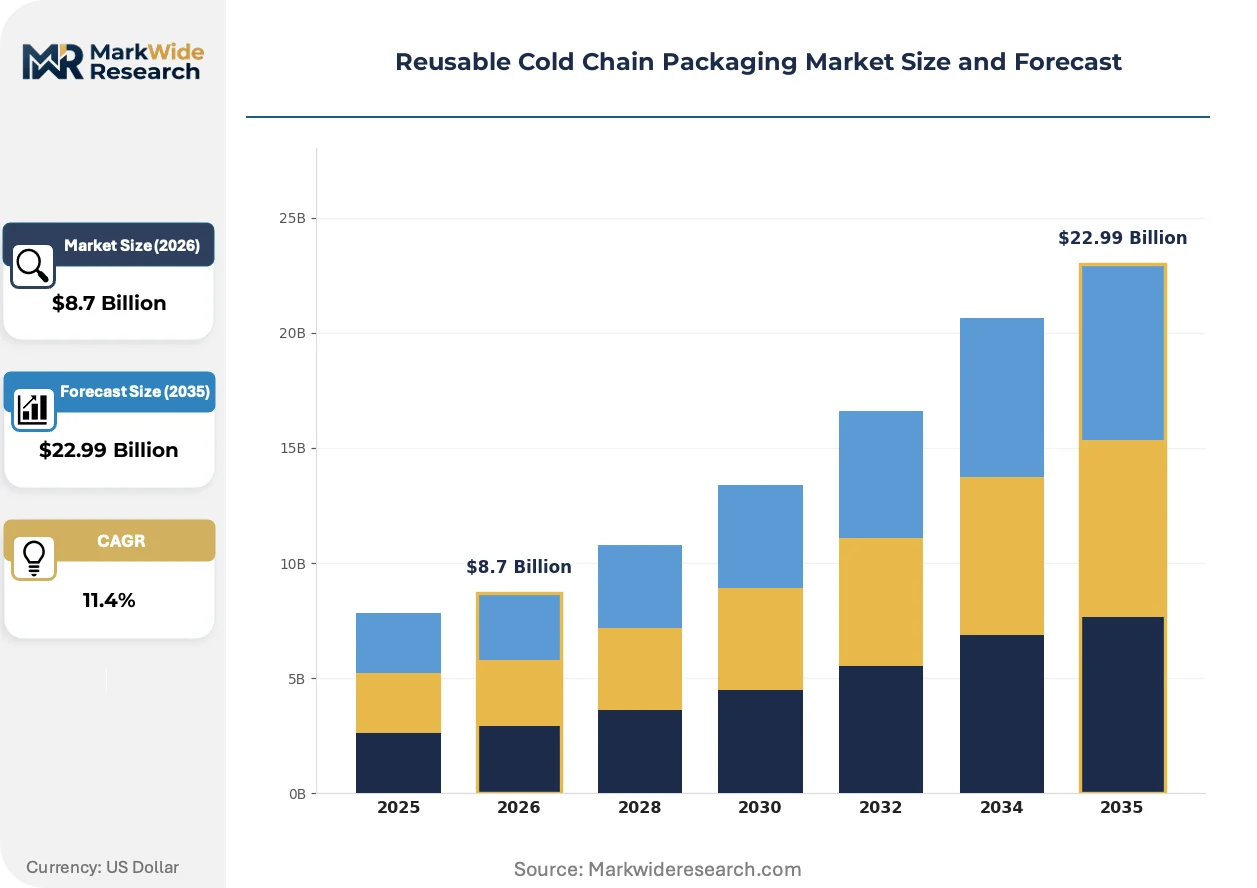
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Containers, Thermal Pallets, Shockproof Boxes, Refrigerated Trucks End User: Pharmaceuticals, Food & Beverage, Biotechnology, Electronics Material: Polyurethane, Polypropylene, Expanded Polystyrene, Aluminum Distribution Channel: Direct Sales, Online Retail, Distributors, Third-Party Logistics |
| Companies Covered | Cryopak, Intelsius, Sonoco ThermoSafe, Nordic Cold Chain Solutions, Envirotainer, Cold Chain Technologies, Sofrigam, IFCO, Pelican BioThermal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Cold Chain Packaging Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to displace incumbent thermal protection technologies. Three interconnected developments are compressing product lifecycles and redrawing competitive boundaries.
Vacuum-insulated panels with silica core substrates are rendering obsolete expanded polyurethane in ultra-low-temperature pharmaceutical shipments. Cell and gene therapy distributors are adopting VIP-based shippers for cryogenic-range stability below minus 150 degrees Celsius. The technology is compressing acceptable temperature excursion windows from hours to days, eliminating active refrigeration dependencies for intercontinental routes.
REACH chemical restrictions on persistent organic pollutants are redirecting phase-change material innovation toward bio-derived paraffin and salt hydrate compounds. ECHA substance evaluation protocols are disqualifying conventional petroleum-based formulations from new product registrations. European vaccine distributors are now specifying biodegradable phase-change media in tender requirements, forcing reformulation investments across supplier bases.
Performance-based service contracts are displacing capital purchase models among mid-size biologics manufacturers. Third-party logistics providers are assuming container fleet ownership and charging per-trip thermal guarantees, transferring qualification risk from shippers to packaging operators. Germany and the Netherlands are showing fastest contract penetration where consolidated pharmaceutical clusters enable route density economics.
Reusable Cold Chain Packaging Market Segmentation
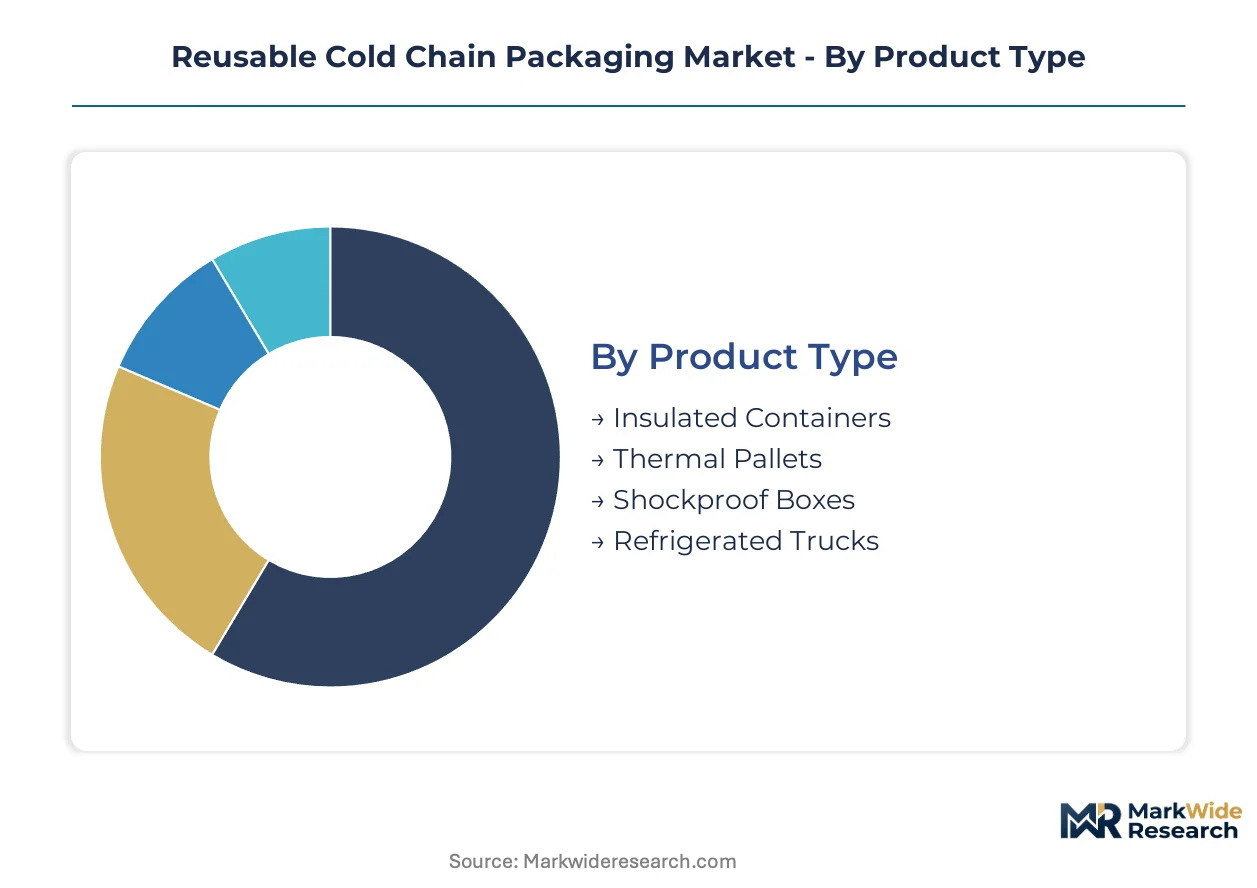
Segmentation in reusable cold chain packaging separates asset-light models from capital-intensive fleet ownership. Cycle times, cleaning protocols, and qualification burdens vary dramatically across product configurations and end-use verticals. Procurement patterns diverge between pharmaceutical validators seeking documented thermal performance and food distributors prioritizing turnaround velocity.
Product Type:
Insulated containers turn over fastest in last-mile vaccine distribution, while thermal pallets accumulate the longest depreciation cycles in consolidated biologics warehousing.
- Insulated Containers:These modular enclosures incorporate vacuum-insulated panels or expanded polyurethane cores with polypropylene shells. Demand clusters around German vaccine logistics hubs where rapid turnaround protocols require container fleets with embedded data loggers for EMA compliance.
- Thermal Pallets:Pallet-scale thermal mass systems consolidate multi-dose biologics shipments through passive temperature maintenance. Frankfurt and Munich cold storage infrastructure drives adoption as inter-facility transfers replace fragmented parcel movements.
- Shockproof Boxes:Reinforced outer casings with internal suspension protect temperature-sensitive electronics during air freight.
- Refrigerated Trucks:Active-cooled vehicle systems retain niche status as EU F-Gas Regulation accelerates passive packaging substitution.
Insulated containers dominate installed base. Thermal pallets are where expansion concentrates.
End User:
Pharmaceutical and biotechnology segments absorb the highest per-unit qualification costs, while food and beverage operations optimize for volume throughput and sanitization speed.
- Pharmaceuticals:FDA thermal validation protocols and EMA good distribution practice requirements mandate documented stability testing. CDSCO-regulated vaccine distribution in India is opening procurement channels for WHO-prequalified reusable designs.
- Biotechnology:Cell and gene therapy distributors drive cryogenic-range demand below minus 150 degrees Celsius. VIP-based shippers displace polyurethane in ultra-low-temperature intercontinental routes.
- Food & Beverage:Non-regulated distribution segments retain single-use gel pack substitution, compressing price realization for reusable alternatives.
- Electronics:Temperature-sensitive semiconductor components require shock-integrated thermal protection during precision logistics.
Pharmaceuticals anchor revenue concentration. Biotechnology is climbing the fastest.
Material:
Polyurethane and polypropylene command premium positioning through thermal resistance-to-weight ratios, while expanded polystyrene faces displacement from REACH chemical restrictions.
- Polyurethane:Molded foam cores deliver optimal thermal resistance for pharmaceutical-grade insulated containers. Isocyanate and polyol feedstock volatility compresses margins for producers without captive chemical supply.
- Polypropylene:Durable outer casings withstand repeated cleaning cycles and mechanical stress. ECHA substance evaluation protocols are accelerating bio-based foam convergence with recyclable shell materials.
- Expanded Polystyrene:Lightweight insulation retains food distribution share but faces regulatory pressure under persistent organic pollutant restrictions.
- Aluminum:Metallic outer shells provide structural rigidity for thermal pallet assemblies in consolidated biologics shipments.
Polyurethane leads material selection. Polypropylene is gaining share fastest.
Distribution Channel:
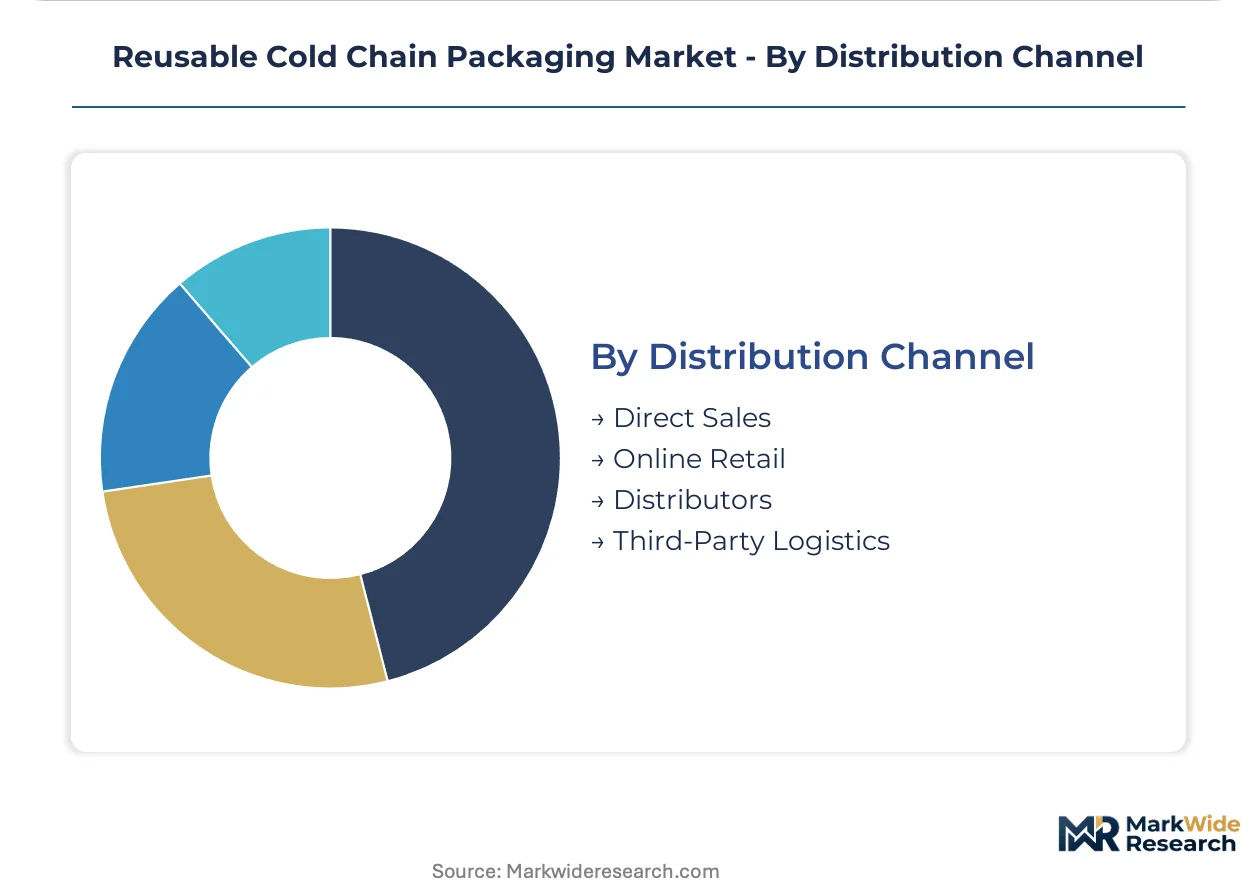
Direct sales and third-party logistics providers are displacing capital purchase models, while online retail remains peripheral to qualified pharmaceutical procurement.
- Direct Sales:Manufacturer-direct relationships anchor long-term contracts with European vaccine distributors through bundled qualification testing services.
- Third-Party Logistics:Fleet ownership transfers to 3PL operators charging per-trip thermal guarantees. Germany and the Netherlands show fastest contract penetration where route density economics enable performance-based service models.
- Distributors:Intermediary networks serve mid-size biologics manufacturers lacking internal thermal engineering expertise.
- Online Retail:Digital procurement channels capture non-regulated food segments with standardized container specifications.
Direct sales dominate qualification-heavy procurement. Third-party logistics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane molding capacity concentrates in China and Germany, while vaccine logistics infrastructure clusters around Frankfurt, Mumbai, and Boston. Cold storage investment flows toward regulatory hubs with dense biopharma manufacturing. Regional demand patterns diverge sharply between EMA-compliant European networks and FDA-validated North American distribution.
Germany
EMA good distribution practice mandates pull vaccine distributors toward qualified reusable containers with embedded data loggers. The EU F-Gas Regulation accelerates passive thermal packaging substitution across pharmaceutical networks. Frankfurt and Munich cold storage infrastructure concentrates demand for high-cycle containers with rapid turnaround protocols.
United States
FDA thermal validation protocols extend product development cycles to 18-24 months for new packaging designs. The Inflation Reduction Act's domestic manufacturing incentives reshape supply chain localization for biologics distribution. Greater Boston's cell and gene therapy cluster drives cryogenic-range demand below minus 150 degrees Celsius.
India
CDSCO-regulated vaccine distribution expansion creates first-mover advantage for reusable system providers with local service networks. The PLI scheme for pharmaceutical manufacturing attracts cold chain infrastructure investment. Maharashtra's Mumbai-Pune pharmaceutical corridor concentrates demand for WHO-prequalified thermal packaging designs.
China
NMPA pharmaceutical distribution standards tighten qualification requirements for temperature-controlled transport systems. Dual carbon goals redirect material innovation toward bio-based foam alternatives. Yangtze River Delta polyurethane molding capacity scales for pharmaceutical-grade insulated container production.
Netherlands
Performance-based service contracts penetrate fastest where consolidated pharmaceutical clusters enable route density economics. REACH chemical restrictions disqualify conventional petroleum-based phase-change formulations from new registrations. Rotterdam's logistics hub anchors third-party logistics fleet ownership models charging per-trip thermal guarantees.
Reusable Cold Chain Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and subassembly supply. The vendor base stratifies between qualification-heavy pharmaceutical validators and volume-driven food logistics operators. Three archetypes dominate: vertically integrated foam producers, specialized testing service bundlers, and third-party logistics fleet operators. Consolidation pressure intensifies through strategic partnerships and geographic expansion moves.
Among North American platform integrators, Cryopak exemplifies captive chemical supply advantages in thermal pallet assembly. Intelsius occupies a position within the European qualification services tier, anchoring long-term contract structures through bundled testing protocols. Sonoco ThermoSafe represents the diversified packaging conglomerate archetype, leveraging cross-divisional manufacturing scale.
| Leading Market Players |
|---|
| Cryopak |
| Intelsius |
| Sonoco ThermoSafe |
| Nordic Cold Chain Solutions |
| Envirotainer |
| Cold Chain Technologies |
| Sofrigam |
| IFCO |
| Pelican BioThermal |
| Others |
Value Network & Pricing Analysis
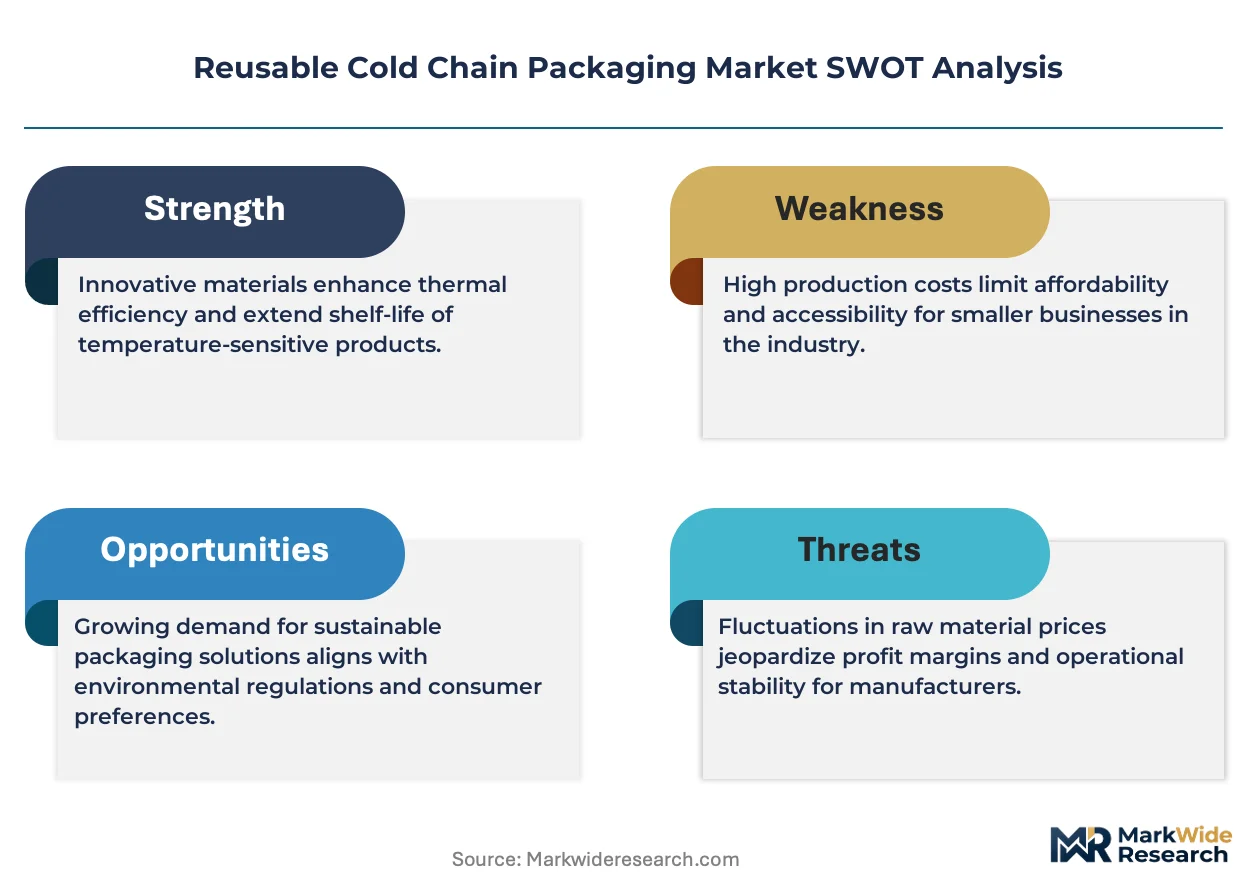
Overcapacity in Chinese polyurethane molding facilities is compressing export pricing for insulated container cores while tightening margins for European producers lacking captive chemical supply, forcing procurement teams to rebalance qualification costs against landed price advantages.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across pharmaceutical-grade reusable packaging, separating FDA-validated thermal shippers from standard food-logistics containers. Three-tier pricing stratifies across qualification-heavy premium, mid-grade standard, and economy levels for non-regulated segments. Cost compression in polyurethane cores is intensifying because isocyanate feedstock volatility feeds through molded component costs. Food distributors show highest price sensitivity, while vaccine logistics operators absorb premium pricing for EMA-compliant documentation bundles.
Supply Chain Analysis
Contract manufacturing concentration rests with Yangtze River Delta foam molders and German automotive-tier suppliers repurposing capacity for pharmaceutical-grade insulation. Raw material flows draw from Saudi petrochemical feedstocks for polyol, Belgian isocyanate producers, and domestic Chinese polypropylene extruders. Single-source vulnerability concentrates in vacuum-insulated panel silica core substrates, where legacy aerospace suppliers constrain scaling. Distribution runs through third-party logistics fleet operators charging per-trip thermal guarantees in consolidated pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reusable cold chain packaging market is reshaping as passive thermal protection displaces active refrigeration under EU chemical restrictions, with vacuum-insulated panel adoption compressing acceptable temperature excursion windows from hours to days.
For Market Incumbents: Pre-empt VIP-based shipper commoditization by anchoring long-term contracts through bundled qualification testing services that EMA inspection protocols mandate. Lock in polyurethane feedstock through backward integration or long-term offtake agreements before isocyanate volatility destabilizes tier-two competitors. Defend against Chinese molders scaling pharmaceutical-grade capacity by accelerating bio-based foam certification under REACH chemical restrictions. For New Entrants and Emerging Players: India's CDSCO-regulated vaccine distribution corridors offer underpenetrated procurement channels where WHO prequalification opens institutional tenders ahead of domestic qualification infrastructure maturation. Target Maharashtra's Mumbai-Pune pharmaceutical corridor with performance-based service contracts that transfer fleet ownership risk from biologics manufacturers to packaging operators. Lead with rapid turnaround protocol expertise rather than capital purchase models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among third-party logistics fleet operators charging per-trip thermal guarantees in route-dense pharmaceutical clusters like Germany and the Netherlands. Five-to-ten year viability favors platform integrators with captive chemical supply and embedded data logger integration capabilities. Watch for consolidation signals when polyurethane feedstock volatility triggers distressed asset availability among tier-two molded container producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Feedstock | Captive isocyanate supply insulates margins from petrochemical volatility affecting tier-two competitors. |
| WHO Prequalification Pathway Investment | CDSCO-aligned validation opens institutional procurement channels in India's expanding vaccine distribution networks. |
| Performance-Based Service Contract Rollout | Per-trip thermal guarantee models transfer qualification risk from biologics shippers to fleet operators in consolidated clusters. |
| Bio-Based Foam Certification Acceleration | REACH-compliant mycelium-derived insulation addresses ECHA substance evaluation protocols disqualifying petroleum-based formulations. |
| Embedded Data Logger Platform Integration | EMA inspection-ready traceability features differentiate compliant suppliers from commodity container providers. |
Research Methodology
Desk research of customs trade flows, ECHA substance registration databases, and pharmaceutical distribution tender records preceded structured interviews with cold chain logistics directors, thermal packaging procurement managers, regulatory affairs leads at vaccine distributors, and polyurethane plant operations heads. Primary fieldwork across German vaccine logistics hubs, Yangtze River Delta molding facilities, and Mumbai pharmaceutical corridors validated secondary indicators. Bottom-up container fleet sizing and top-down pharmaceutical shipment value analysis were triangulated against EMA good distribution practice inspection data.
Assumptions held regulatory enforcement intensity and polyurethane feedstock price volatility within historical ranges while varying biologics shipment consolidation rates and third-party logistics contract penetration across the projection horizon. Segmentation modeling incorporated product type, end-use vertical, material composition, and distribution channel dynamics. CAGRs were derived from regression analysis of installed base turnover rates against pharmaceutical cold storage investment flows. Forecast inputs included CDSCO regulatory expansion timelines and EU F-Gas Regulation phase-down schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese polyurethane molders or accelerated REACH chemical restrictions would shift outcomes beyond modeled ranges. Quarterly review of EMA inspection failure rates, isocyanate contract pricing, and WHO prequalification application volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Freezer Liner Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market