
 Reconditioned Packaging Market | 2026-2036
Reconditioned Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Reconditioned Packaging Market Analytics
Buyer concentration among beverage producers is shifting toward pooled container programs that prioritize reconditioned assets over virgin packaging. Greif Inc. leverages its North American drum reconditioning network to serve bulk chemical distributors. Mauser Packaging Solutions sustains vertical integration from collection through reconditioning to final quality certification. Schütz Container Systems anchors European demand through its IBC reconditioning footprint and closed-loop logistics.
Reconditioned packaging encompasses used containers, drums, and intermediate bulk containers that undergo cleaning, inspection, repair, and testing to restore functional integrity for repeated industrial use. The reconditioning process typically incorporates pressure testing, seam welding, and UN-certification renewal to meet hazardous material transport standards. Plastic containers dominate volume throughput due to standardized polypropylene and high-density polyethylene formulations that withstand multiple reconditioning cycles. Metal drums retain premium positioning in chemical and pharmaceutical end uses where UN-rated containment commands higher margin pools. Grade A quality classification captures the fastest expansion as pharmaceutical and cosmetics buyers tighten incoming inspection protocols.
The EPA governs hazardous waste container management under RCRASubtitle C, directly shaping reconditioning facility permitting and residue disposal requirements. FDA regulations for food-contact packaging impose strict cleaning validation protocols on reconditioned containers destined for beverage and food industry reuse. ISO 16106 standards for transport packaging provide the technical baseline that reconditioning operators must maintain to retain customer certification. Stakeholders must monitor how tightening state-level extended producer responsibility frameworks in California and New York reshape collection economics and reconditioning network placement.
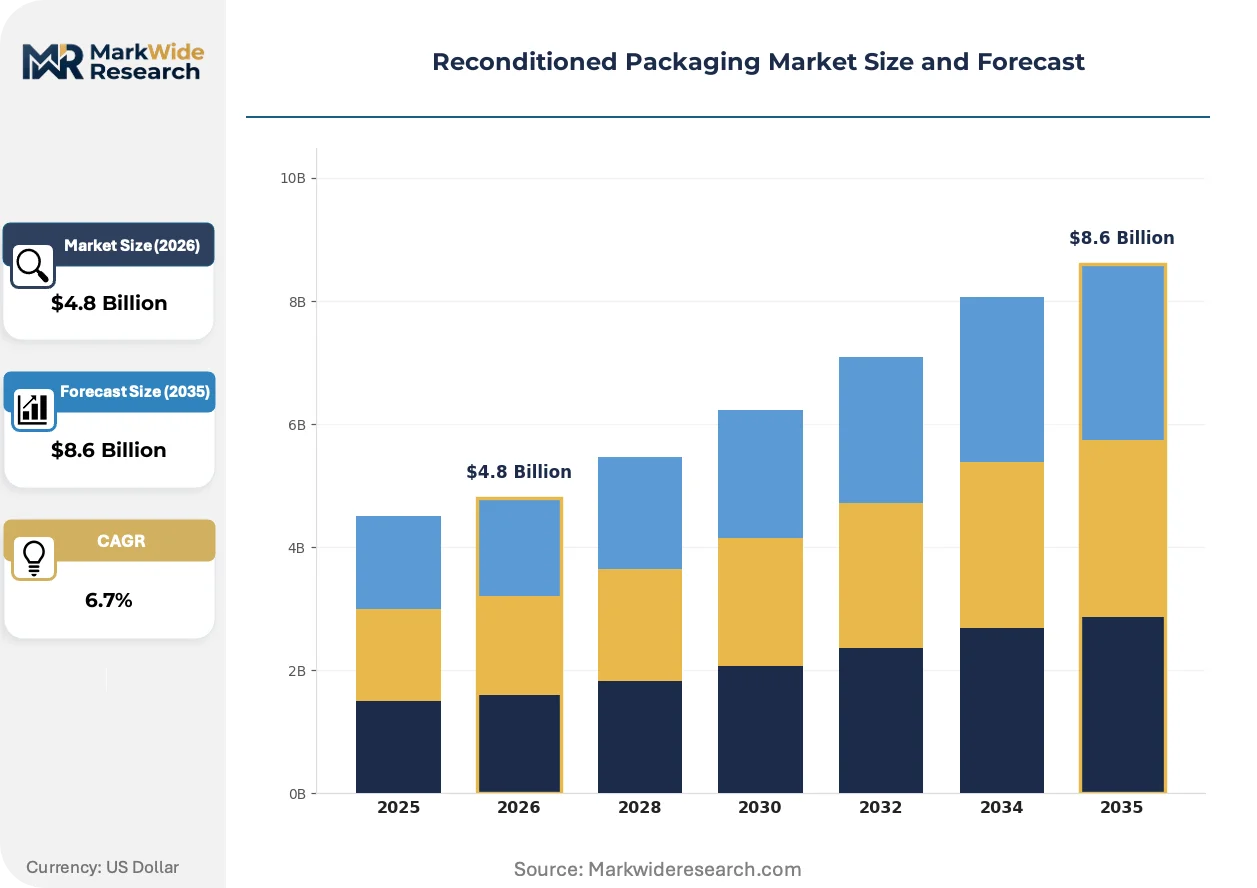
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing reuse timelines and forcing chemical, food, and automotive buyers to accelerate container return velocities, reshaping how reconditioning networks capture and redeploy assets.
Growth Catalysts
- Circularity mandates:The EU Packaging and Packaging Waste Regulation tightens reuse targets across member states, compelling industrial buyers to source reconditioned intermediate bulk containers rather than virgin alternatives.
- Cost pressure in food processing:Beverage and food manufacturers face margin compression that drives procurement toward pooled container programs with reconditioned asset pools.
- German industrial clustering:Chemical and automotive production concentration around Ludwigshafen and Stuttgart sustains high-volume return programs that feed reconditioning facilities.
Market Restraints
- Residue disposal costs:EPA RCRA Subtitle C hazardous waste rules impose escalating disposal fees on reconditioning facilities handling chemical containers, compressing margins on UN-rated drum processing.
- Input material volatility:Polypropylene pricing fluctuations directly affect reconditioning economics for plastic intermediate bulk containers, creating margin unpredictability.
- Substitution by single-use flexitanks:Bulk liquid shippers in non-hazardous segments increasingly bypass rigid container reconditioning entirely.
Strategic Opportunities
- Pharmaceutical-grade expansion:FDA cleaning validation protocols for food-contact reuse are migrating into cosmetic and pharmaceutical applications, opening premium Grade A certification demand.
- Closed-loop logistics integration:Reconditioning operators that embed tracking and reverse logistics software capture asset-return premiums from chemical distributors.
- California EPR frameworks:State-level extended producer responsibility legislation is reshaping collection economics and creating first-mover advantage for reconditioning network placement.
Industry Challenges
- UN-certification renewal timelines:Pressure testing and seam welding documentation requirements create bottlenecks that delay container redeployment.
- Skilled welder scarcity:Metal drum reconditioning facilities face recruitment gaps for certified pressure-vessel technicians capable of hazardous-material containment repair.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconditioned Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Glass Jars, Metal Drums, Cardboard Boxes End User: Food Industry, Beverage Producers, Pharmaceuticals, Cosmetics Application: Shipping, Storage, Retail Display, Waste Management Quality Grade: Grade A, Grade B, Grade C, Grade D |
| Companies Covered | Mauser Packaging Solutions, Greif Inc., Schütz Container Systems, BWAY Corporation, Snyder Industries, Hoyer Group, Berry Global Inc., Time Technoplast Limited, Brambles Limited (CHEP), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconditioned Packaging Market Evolving Landscape
Digital tracking systems and automated inspection technologies are compressing reconditioning cycle times while regulatory pressure on virgin plastic production intensifies asset-life extension strategies.
Blockchain-enabled container provenance tracking is decentralizing custody verification across multi-party supply chains. Chemical distributors in the Rhine-Ruhr corridor are piloting distributed ledger systems that eliminate redundant inspection handoffs. This architecture is decentralizing quality assurance from centralized certification bodies toward networked peer validation.
The EU Green Deal's packaging reuse targets are accelerating closed-loop service model adoption. Industrial buyers now contract for container availability rather than asset ownership, shifting balance sheet structures. Food and beverage manufacturers in France and Italy are restructuring procurement to prioritize reconditioned asset pools over virgin container purchases.
Buyer aggregation through pooled procurement platforms is consolidating demand-side leverage. Small and mid-sized chemical distributors are joining cooperative purchasing networks that negotiate standardized reconditioning service tiers. This concentration is most pronounced in Germany's Mittelstand manufacturing belt, where shared logistics infrastructure reduces per-unit reconditioning costs.
Reconditioned Packaging Market Segmentation
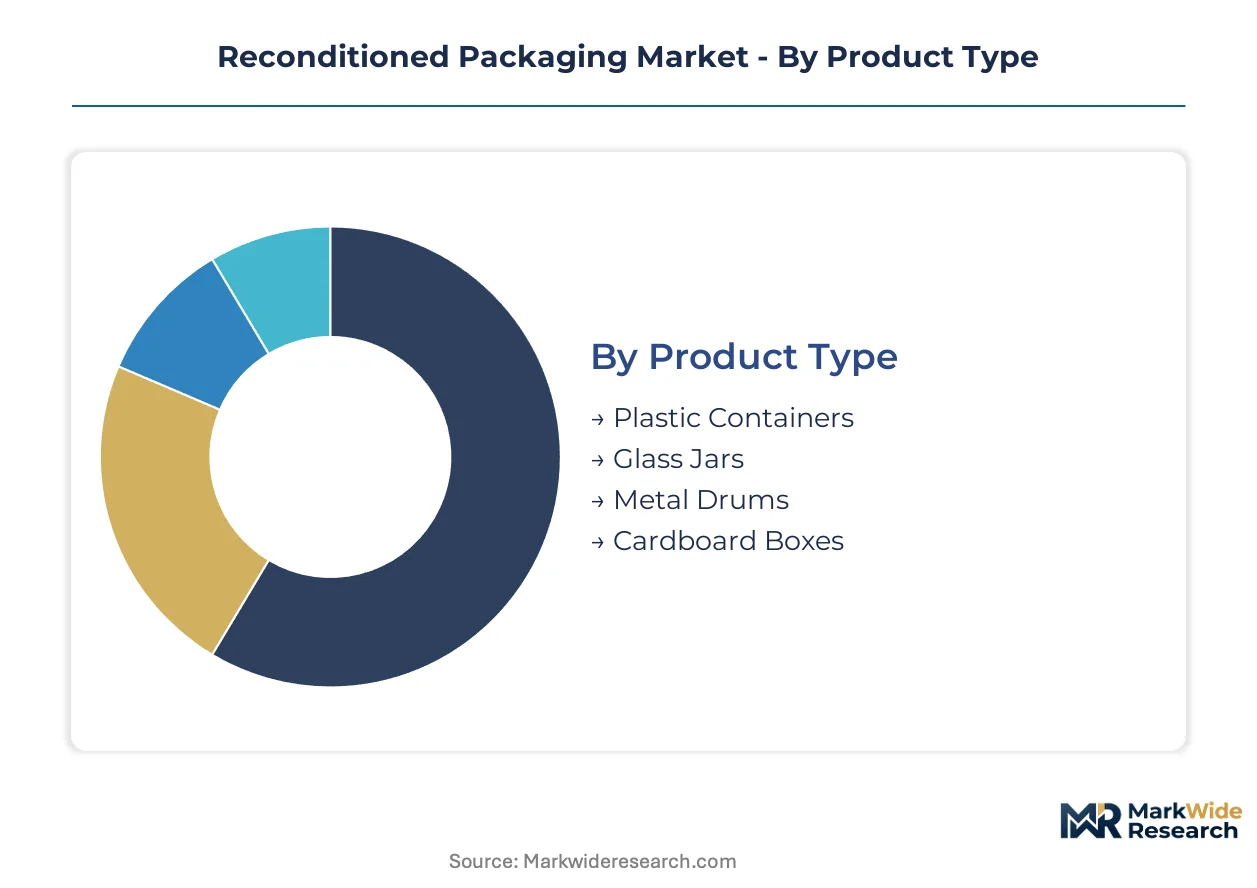
Segmentation in reconditioned packaging reveals how asset life cycles, regulatory thresholds, and end-use cleanliness standards partition demand. Each dimension governs facility capital allocation, certification burdens, and margin capture differently.
Product Type:
Standalone reconditioning dominates high-volume formats where dedicated facilities achieve scale, while embedded reconditioning applies to specialized containers integrated into proprietary logistics systems.
- Plastic Containers:Polypropylene and high-density polyethylene IBCs undergo standardized washing, pressure testing, and UN recertification cycles. Beverage producers in Germany and France drive procurement through pooled programs that prioritize reconditioned asset availability over virgin container purchases.
- Metal Drums:Carbon steel and stainless steel drums require seam welding, hydrostatic testing, and hazardous material containment validation. Chemical distributors in the Rhine-Ruhr corridor sustain the highest return velocities, though EPA RCRA Subtitle C residue disposal fees compress reconditioning margins.
- Glass Jars:Food-contact sterilization protocols limit reconditioning to non-hazardous applications with shorter reuse cycles.
- Cardboard Boxes:Limited reconditioning viability outside closed-loop retail logistics with controlled return streams.
Volume placements concentrate in plastic containers; the faster expansion belongs to metal drums as chemical sector circularity mandates tighten.
End User:
Cost tier segmentation separates premium-grade buyers with stringent incoming inspection protocols from economy-tier users accepting higher defect tolerance.
- Food Industry:FDA cleaning validation requirements govern reconditioned container acceptance for direct food contact. Pooled procurement platforms among mid-sized European processors are consolidating demand-side leverage.
- Beverage Producers:Carbonated and still beverage manufacturers face margin compression that accelerates shift toward reconditioned intermediate bulk container programs.
- Pharmaceuticals:Grade A certification demands dominate, with migration of FDA food-contact protocols into drug packaging applications.
- Cosmetics:Premium positioning aligns with Grade A quality classification as brands tighten supply chain sustainability credentials.
Food industry volume leads current placements; pharmaceuticals are climbing the fastest as cleaning validation standards migrate across sectors.
Application:
Application segmentation tracks functional deployment from single-move shipping through multi-cycle storage systems.
- Shipping:UN-rated container reconditioning serves hazardous material transport with mandatory pressure testing and documentation. Substitution by single-use flexitanks in non-hazardous bulk liquid segments constrains growth in certain corridors.
- Storage:Extended-use IBC reconditioning for chemical and automotive production clusters around Ludwigshafen and Stuttgart sustains high-volume return programs.
- Retail Display:Limited reconditioning applicability given aesthetic and branding requirements.
- Waste Management:Regulatory-driven container recovery for hazardous waste streams under EPA and EU frameworks.
Storage applications hold the largest installed base; shipping commands the steepest expansion trajectory as circularity mandates compress reuse timelines.
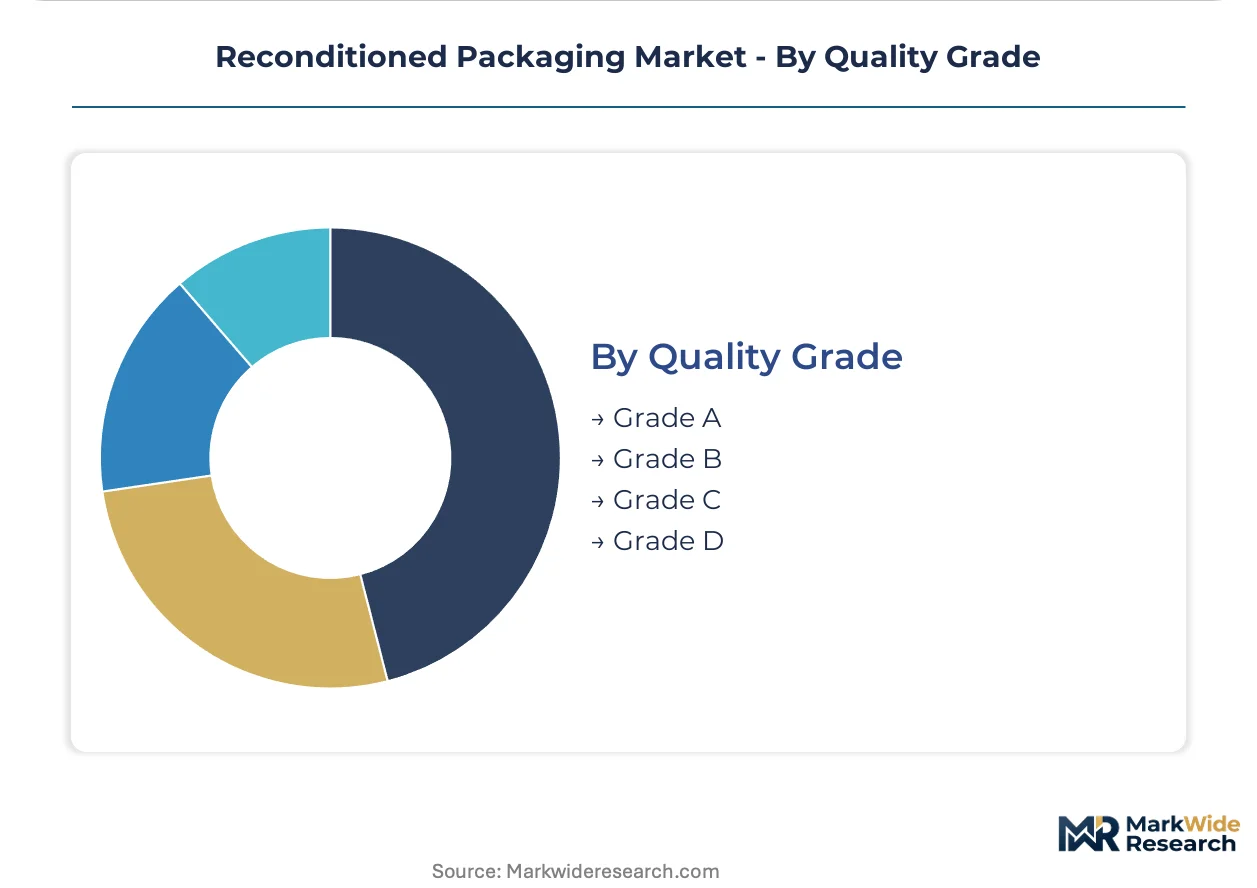
Quality Grade:
Grade stratification determines pricing differentiation and end-use eligibility across regulated industries.
- Grade A:Pharmaceutical and cosmetic buyers drive demand for containers meeting the tightest incoming inspection protocols, including full traceability documentation and validated cleaning records.
- Grade B:Industrial chemical and food processing applications with moderate contamination risk tolerance.
- Grade C:Non-hazardous material handling where functional integrity exceeds aesthetic or traceability requirements.
- Grade D:Limited reuse cycles for low-risk applications with minimal regulatory exposure.
Grade B retains the highest volume throughput; Grade A is gaining share fastest as premium end users tighten supplier qualification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates the highest reconditioned packaging demand through its chemical and automotive manufacturing density, while the United States and China follow with distinct regulatory and industrial drivers shaping network economics.
Germany
Automotive and chemical production clusters around Stuttgart and Ludwigshafen sustain the densest container return velocities in Europe. The EU Packaging and Packaging Waste Regulation accelerates reuse timelines, compelling BASF and Mercedes-Benz suppliers to prioritize reconditioned intermediate bulk container pools. Reconditioning facilities in North Rhine-Westphalia capture scale advantages through shared logistics infrastructure serving the Mittelstand manufacturing belt.
United States
Bulk chemical distributors along the Gulf Coast and Midwest food processors drive procurement of reconditioned drums and IBCs. EPA RCRA Subtitle C governs hazardous waste container management, shaping facility permitting and residue disposal economics that compress margins on UN-rated drum processing. Texas and Louisiana petrochemical corridors maintain the highest reconditioning facility density due to concentrated hazardous material transport demand.
China
Industrial packaging reuse expands through state-led circular economy pilots in the Yangtze River Delta and Pearl River Delta manufacturing zones. National standards under SAMR and MIIT establish technical baselines for container reconditioning quality. Chemical producers in Jiangsu and Zhejiang provinces are integrating closed-loop container programs to meet dual carbon goals and reduce virgin plastic procurement.
France
Food and beverage manufacturers in Île-de-France and Auvergne-Rhône-Alpes restructure procurement toward pooled reconditioned asset programs. The EU Green Deal's packaging reuse targets tighten compliance timelines for Danone and L'Oréal supply chains. Cosmetic brands in the Paris region are migrating FDA-derived cleaning validation protocols into supplier qualification standards for Grade A container certification.
India
Agrochemical and pharmaceutical packaging reuse gains traction in Maharashtra and Gujarat industrial corridors. BIS standards for transport packaging provide the technical framework that domestic reconditioning operators must meet to serve export-oriented pharmaceutical manufacturers. Time Technoplast and regional specialists in Pune and Ahmedabad are building collection networks to capture return velocities from growing bulk chemical distribution.
Reconditioned Packaging Market Competitive Landscape
North American producers anchor one tier; European specialists hold certification-intensive segments with tighter regulatory integration. The vendor base stratifies across three tiers: multinational packaging conglomerates with integrated reconditioning networks, regional specialists focused on single material categories, and logistics-embedded operators offering container pooling services. Strategic moves concentrate on backward integration into collection networks and technology licensing for automated inspection systems.
Among the scale-driven operators, Mauser Packaging Solutions exemplifies vertical control from collection through quality certification. Greif Inc. anchors North American drum reconditioning capacity serving bulk chemical distribution corridors. Schütz Container Systems occupies a position within European IBC reconditioning, leveraging closed-loop logistics integration to capture asset-return premiums from Rhine-Ruhr chemical clusters. These three represent distinct archetypes: full-service integration, regional scale concentration, and logistics-embedded pooling.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Greif Inc. |
| Schütz Container Systems |
| BWAY Corporation |
| Snyder Industries |
| Hoyer Group |
| Berry Global Inc. |
| Time Technoplast Limited |
| Brambles Limited (CHEP) |
| Others |
Value Network & Pricing Analysis
Residue disposal fees under EPA RCRA Subtitle C flow downstream through metal drum reconditioning tiers, compressing margins on UN-rated processing while plastic container economics track polypropylene spot volatility through pooled procurement contracts.
Pricing Analysis
Volume throughput concentrates in Grade B industrial chemical containers while margin capture concentrates in Grade A pharmaceutical-grade certification. Pricing stratifies across premium, standard, and economy tiers based on UN-certification renewal status and FDA cleaning validation documentation. Cost compression in metal drum reconditioning is intensifying because hazardous waste disposal fees escalate faster than container redeployment velocity. Small and mid-sized chemical distributors exhibit highest price sensitivity; pharmaceutical and cosmetic buyers demonstrate lowest sensitivity due to incoming inspection protocol rigidity.
Supply Chain Analysis
UN-certification and FDA cleaning validation gate facility participation, concentrating supply among operators with documented pressure-testing capabilities and validated sterilization protocols. Production gravity centers on Germany, the United States, and China, with chemical corridor clustering around Ludwigshafen, the Gulf Coast petrochemical belt, and the Yangtze River Delta. Raw material inputs draw from polypropylene resin markets, carbon steel sheet production, and high-density polyethylene formulations. Single-source vulnerability concentrates in certified pressure-vessel technician labor pools. Distribution runs through closed-loop logistics networks embedded within chemical distributor procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EPA residue disposal cost escalation forces sub-scale reconditioning facilities into exit or acquisition.
For Market Incumbents: Anticipate flexitank substitution in non-hazardous bulk liquid segments by embedding tracking software into closed-loop service contracts. Capture asset-return premiums through backward integration into collection networks serving Rhine-Ruhr chemical clusters. Counter margin compression with automated inspection technology licensing to reduce cycle-time bottlenecks. For New Entrants and Emerging Players: Launch via cooperative purchasing platforms serving Germany's Mittelstand manufacturing belt where shared logistics infrastructure reduces per-unit costs. Target pharmaceutical-grade reconditioning in France and Italy where FDA-derived cleaning validation protocols are migrating into cosmetic supplier qualification standards. Penetrate through Grade A certification investment rather than volume competition. For Investors and Strategic Acquirers: California EPR framework implementation is the leading indicator that state-level collection economics will reshape network placement viability. Five-to-ten year viability favors operators with captive supply of return-velocity contracts from automotive and chemical production clusters. Monitor EU Packaging and Packaging Waste Regulation enforcement variance across member states as the signal for asset-redeployment timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captures return-velocity premiums from BASF and Mercedes-Benz supplier tiers. |
| Automated Inspection Technology Deployment | Compresses UN-certification renewal timelines for Rhine-Ruhr chemical distributors. |
| Grade A Certification Investment | Opens pharmaceutical and cosmetic procurement channels with tightened protocols. |
| Closed-Loop Logistics Software Integration | Enables blockchain-enabled provenance tracking for multi-party custody verification. |
| Pooled Procurement Platform Participation | Consolidates demand-side leverage among mid-sized European food processors. |
Research Methodology
Trade association filings, customs and excise records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews involving reconditioning facility operators, chemical distributor procurement leads, FDA regulatory affairs specialists, and closed-loop logistics platform engineers. Bottom-up and top-down triangulation validated volume estimates against facility capacity utilization rates and return-velocity data from German automotive and chemical clusters.
Bottom-up modeling tracked product type, quality grade, end-use industry, and regional regulatory cluster across the analysis window. CAGRs were derived from segment-level growth rate reconciliation against macro industrial production indices. Forecast inputs incorporated EU Packaging and Packaging Waste Regulation compliance timeline assumptions and polypropylene price elasticity coefficients from packaging resin markets.
Regulatory enforcement variance, raw material price volatility, and substitution acceleration by single-use flexitanks are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in EPA RCRA Subtitle C residue disposal fee structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Global Recyclable Packaging Market