
 Refillable Packaging Market | 2026-2036
Refillable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Refillable Packaging Market Outlook
Food-grade certification tiers is bifurcating the competitive landscape as buyers separate commodity refillables from performance-validated formats. Amcor leverages its multilayer barrier film expertise to dominate high-oxygen-sensitivity applications such as edible oils and sauces. Schoeller Allibert Services BV anchors the industrial loop with its standardized foldable large containers, sustaining reuse cycles across automotive and chemical supply chains. Nefab Group specializes in engineered wooden refillable crates for heavy-machinery components, occupying a niche where metal fatigue risks exclude plastic alternatives.
Refillable packaging denotes containers engineered for multiple filling and distribution cycles, typically constructed with wall thicknesses exceeding single-use equivalents by 40-300% and incorporating threaded closures, gasket seals, or tamper-evident features to preserve product integrity across repeated handling. Its primary commercial purpose is to displace virgin material consumption in closed-loop or returnable supply chains while retaining brand-controlled primary packaging aesthetics at the point of sale. Glass bottles command the highest margin pools in personal care and premium food segments where tactile weight and chemical inertness justify elevated per-unit costs and reverse-logistics investment. Plastic pouches represent the fastest-expanding format as spouted stand-up designs with replaceable caps penetrate liquid household cleaners and condiments, though thin-film recycling complexity constrains circularity claims. Metal canisters retain mature demand in industrial lubricants and specialty chemicals where UN-rated stack strength and spark resistance override lightweighting priorities.
The European Chemicals Agency enforces REACH compliance for all surface coatings and additives in repeated-use food contact materials, while the EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that scale with packaging format reuse frequency. The US FDA maintains 21 CFR 177 substance clearance lists that constrain polymer selection for refillable food containers, creating a dual-track compliance burden for exporters serving both Atlantic markets. Stakeholders must monitor how emerging state-level extended producer responsibility laws in California and New York diverge from federal baseline requirements, as fragmentation threatens standardized return infrastructure investment.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing redesign timelines for single-use formats, forcing CPG manufacturers to engineer refillable alternatives with verified reuse-cycle durability before 2030 mandates activate.
Growth Catalysts
- Extended Producer Responsibility Mandates:EU member states now enforce packaging reuse quotas that scale with brand revenue, compelling food and beverage manufacturers to procure refillable formats or face material recovery fee escalations.
- Deposit-Return Infrastructure Density:Germany's retailer-led refill station networks create operational proof points that reduce adoption risk for neighboring markets, with dm-drogerie markt and REWE operating over 3,000 combined dispensing points.
- Barrier Film Advancement:Multilayer coextrusion technologies now achieve oxygen transmission rates below 0.1 cc/m²/day in polyethylene terephthalate formats, enabling refillable packaging for oxidation-sensitive edible oils and nut butters.
Market Restraints
- Reverse Logistics Cost Burden:Empty container collection, sanitization, and redistribution add 15-40% to total landed packaging costs compared to single-use alternatives, compressing margins in price-sensitive household cleaner segments.
- Polypropylene Feedstock Volatility:Propylene monomer supply disruptions in the US Gulf Coast and Northwestern Europe create input cost instability for injection-molded refillable containers with 2-4 month production lead times.
- Thin-Film Recycling Complexity:Spouted stand-up pouches with multi-material laminates face mechanical recycling incompatibility, limiting circularity claims and exposing brands to greenwashing liability under EU Green Claims Directive enforcement.
Strategic Opportunities
- Pharmaceutical Compliance Pathway:FDA 21 CFR 211 container closure system requirements for drug products remain underpenetrated by refillable formats, creating first-mover advantage for validated barrier systems in OTC liquid medications.
- Industrial Loop Standardization:Automotive battery cell manufacturers seek ISO 17840-compliant foldable large containers for cathode active material transport, replacing single-use fiber drums with tracked reusable assets.
- California SB 54 Implementation:The state's plastic pollution producer responsibility act mandates 30% source reduction by 2032, creating regulatory tailwind for refillable adoption in personal care and cleaning product categories.
Industry Challenges
- Sanitization Validation Timeline:FDA food contact notification reviews for novel refillable container designs average 180-270 days, delaying market entry for antimicrobial coating innovations.
- Legacy ERP Integration Friction:Container tracking via RFID and blockchain-enabled custody verification requires reconfiguration of SAP and Oracle inventory modules, stretching IT implementation cycles for mid-tier CPG brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refillable Packaging Market |
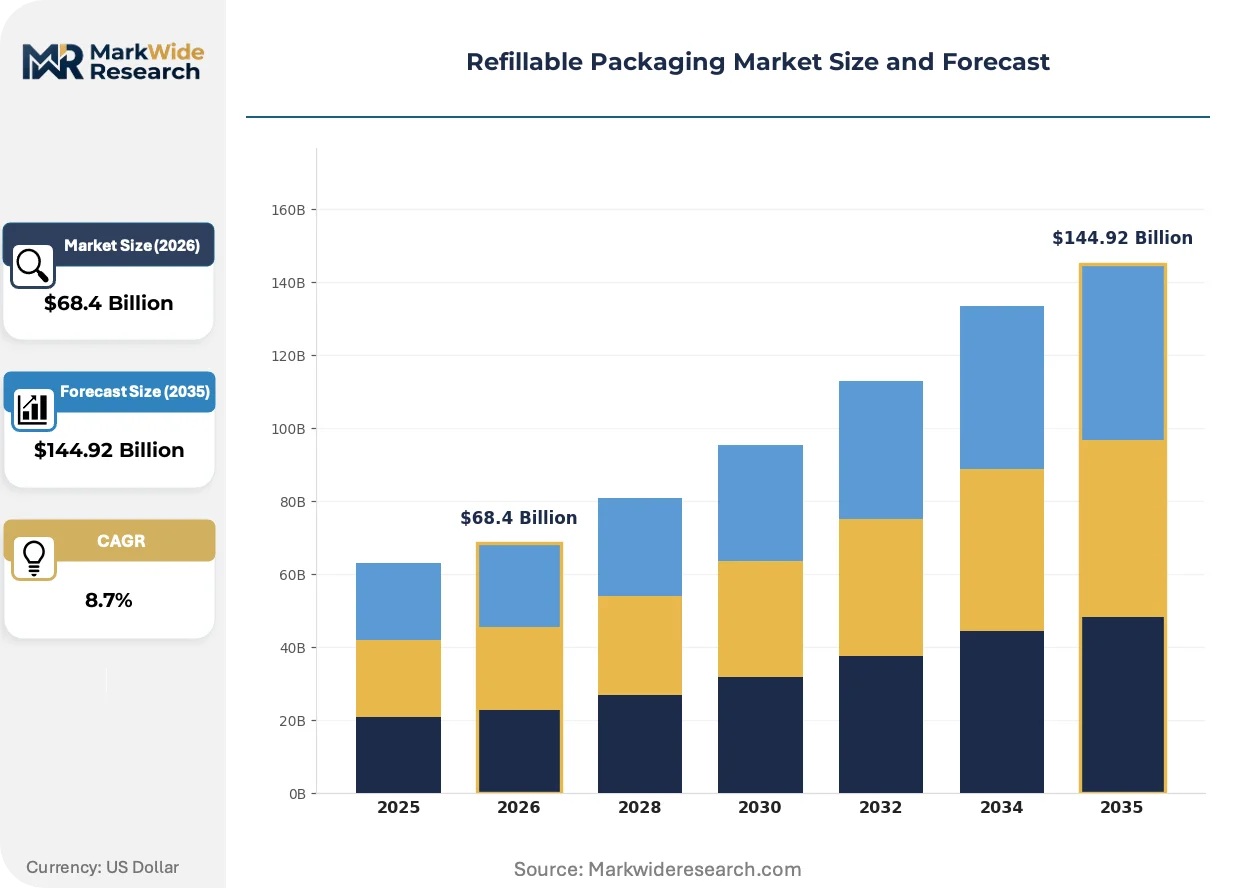
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Pouches, Jars, Canisters Material: Glass, Plastic, Metal, Paperboard End User: Food & Beverage, Personal Care, Household, Industrial Distribution Channel: Online, Retail, Direct, Wholesaler |
| Companies Covered | Amcor, IFCO Systems, Schoeller Allibert Services BV, Nefab Group, Greif Inc., International Paper, Smurfit Westrock, Orbis Corporation, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refillable Packaging Market Strategic Shifts
Material science breakthroughs and regulatory compliance automation are compressing the validation cycle for refillable formats, enabling faster scaling from pilot programs to regional deployment.
Smart closure systems with embedded NFC tags are bifurcating the authentication landscape. Premium personal care brands embed tamper-evident digital identifiers that verify refill authenticity and track consumption patterns. L'Oréal and Unilever pilot programs in France and the Netherlands demonstrate consumer willingness to register packaging for loyalty rewards, creating data assets that subsidize reverse logistics costs through targeted replenishment.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances in food contact materials are accelerating fluoropolymer replacement in high-barrier refillable formats. ECHA enforcement actions against non-compliant coatings have triggered reformulation investments across German and Italian packaging converters. The regulatory pressure concentrates impact on sauce and condiment segments where grease resistance previously depended on fluorinated barriers.
Retailer-owned refill infrastructure is displacing brand-controlled primary packaging at point of sale. Carrefour's bulk liquid dispensers in Belgium and Albert Heijn's packaging-free zones in the Netherlands remove brand billboard space, forcing CPG manufacturers to compete on formulation rather than shelf presence. This channel shift is most visible in household cleaning and personal hygiene categories where formulation differentiation remains limited.
Refillable Packaging Market Segmentation
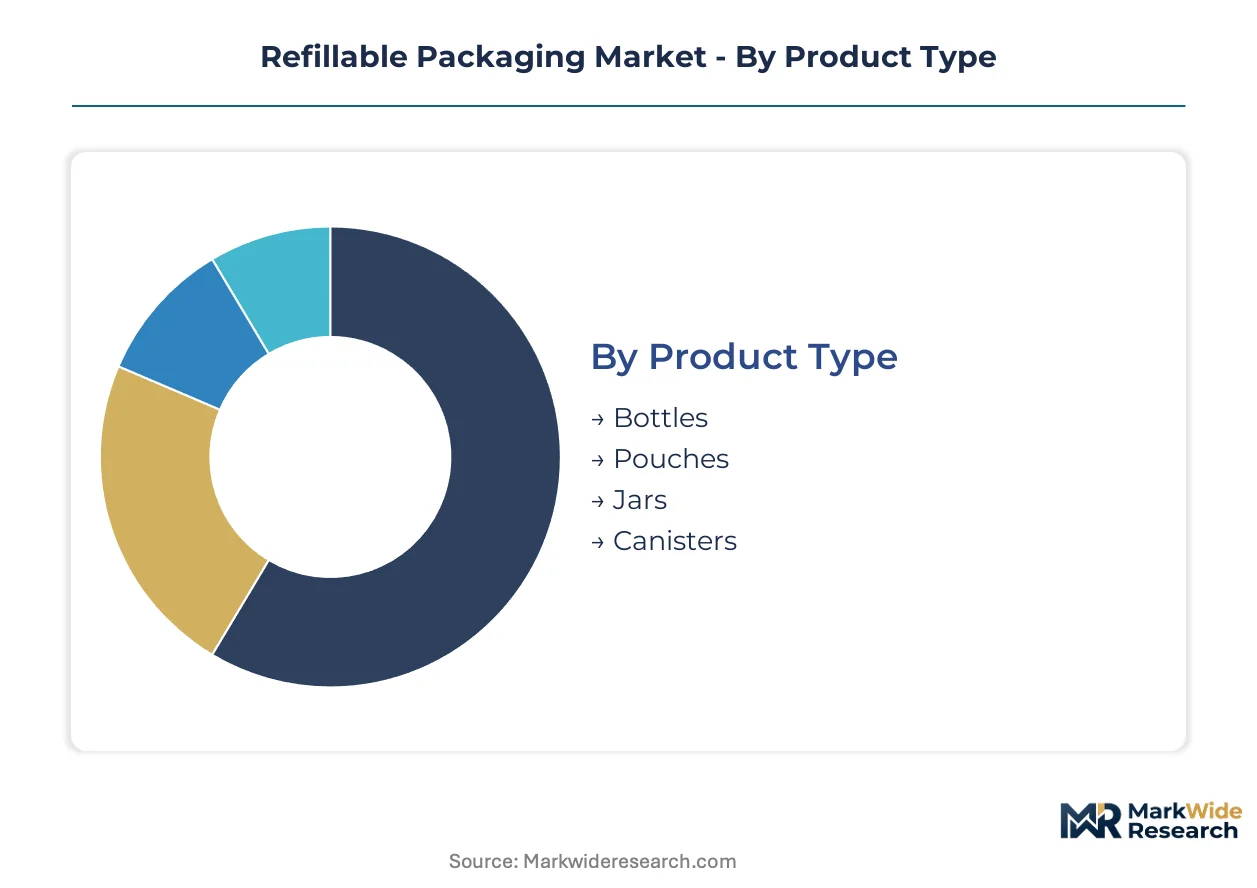
Refillable packaging procurement decisions diverge sharply across product formats and end-use applications. Material selection and distribution channel economics determine compliance feasibility and reverse-logistics viability for each segment configuration.
Product Type:
REACH Annex XVII and FDA 21 CFR 177 impose divergent testing burdens on each format's barrier coatings and closure systems, reshaping competitive positioning.
- Bottles:Glass and thick-walled PET constructions with threaded closures and gasket seals dominate oxygen-sensitive applications. Food-grade edible oils and premium sauces in Germany's dm-drogerie markt and REWE refill networks drive procurement concentration, though reverse-logistics density requirements limit expansion into sparse retail markets.
- Pouches:Spouted stand-up designs with replaceable caps penetrate liquid household cleaners and condiments through multilayer coextrusion achieving sub-0.1 cc/m²/day oxygen transmission. Thin-film recycling complexity under EU Green Claims Directive enforcement constrains circularity messaging for brands deploying this format.
- Jars:Wide-mouth configurations with tamper-evident lids serve viscous personal care formulations and nut butters. ECHA compliance documentation for repeated-use food contact coatings extends validation timelines.
- Canisters:UN-rated metal cylinders retain mature demand in industrial lubricants and specialty chemicals where spark resistance and stack strength override lightweighting priorities.
Bottles handle the majority of throughput; pouches are expanding most quickly on share.
Material:
Cost tier stratification separates commodity feedstocks from performance-validated alternatives with verified reuse-cycle durability.
- Glass:Highest margin pools in personal care and premium food segments where tactile weight and chemical inertness justify elevated per-unit costs and reverse-logistics investment. FDA 21 CFR 211 container closure requirements and ECHA REACH surface coating mandates create dual-track compliance burdens for Atlantic-market exporters.
- Plastic:Injection-molded polypropylene and PET formats with 40-300% wall thickness excess over single-use equivalents. US Gulf Coast and Northwestern European propylene monomer supply disruptions generate input cost instability for converters with 2-4 month production lead times.
- Metal:Stainless steel and aluminum canisters with fluoropolymer replacement underway following ECHA enforcement actions against per- and polyfluoroalkyl substances in food contact materials.
- Paperboard:Engineered fiber formats with moisture-resistant coatings for dry goods refill systems; limited reuse-cycle durability constrains application scope.
Plastic commands volume leadership; glass captures margin concentration.
End User:
Application-specific regulatory mandates and EPR fee structures determine procurement priority across customer categories.
- Food & Beverage:Largest procurement share as EU Packaging and Packaging Waste Regulation reuse quotas scale with brand revenue, forcing redesign of single-use formats before mandate activation. Extended producer responsibility fee escalations concentrate investment in Germany's densest adoption network.
- Personal Care:Premium segments embed NFC-enabled smart closures for tamper-evident authentication and loyalty program integration; L'Oréal and Unilever pilot programs in France and the Netherlands demonstrate consumer registration willingness.
- Household:Price-sensitive segments where 15-40% reverse-logistics cost premiums compress margins; retailer-owned refill infrastructure at Carrefour Belgium and Albert Heijn Netherlands displaces brand-controlled primary packaging.
- Industrial:ISO 17840-compliant foldable large containers for automotive battery cathode active material transport; Nefab Group engineered wooden crates serve heavy-machinery components where metal fatigue risks exclude plastic alternatives.
Food & Beverage anchors procurement volume; Personal Care climbs fastest on premiumization.
Distribution Channel:
Customer type and purchase scale determine tracking infrastructure requirements and custody verification protocols.
- Retail:Over 3,000 combined dispensing points at dm-drogerie markt and REWE in Germany create operational proof points reducing adoption risk for neighboring markets; RFID and blockchain-enabled custody verification requires SAP and Oracle inventory module reconfiguration.
- Online:Direct-to-consumer refill subscriptions with return-mail packaging; loyalty reward integration subsidizes reverse logistics costs through targeted replenishment data assets.
- Direct:Industrial loop arrangements with tracked reusable assets for automotive and chemical supply chains; standardized container pools sustain reuse cycles across multiple OEM suppliers.
- Wholesaler:Bulk dispensing systems for commercial food service and institutional cleaning operations; lower brand billboard exposure forces formulation-based competition.
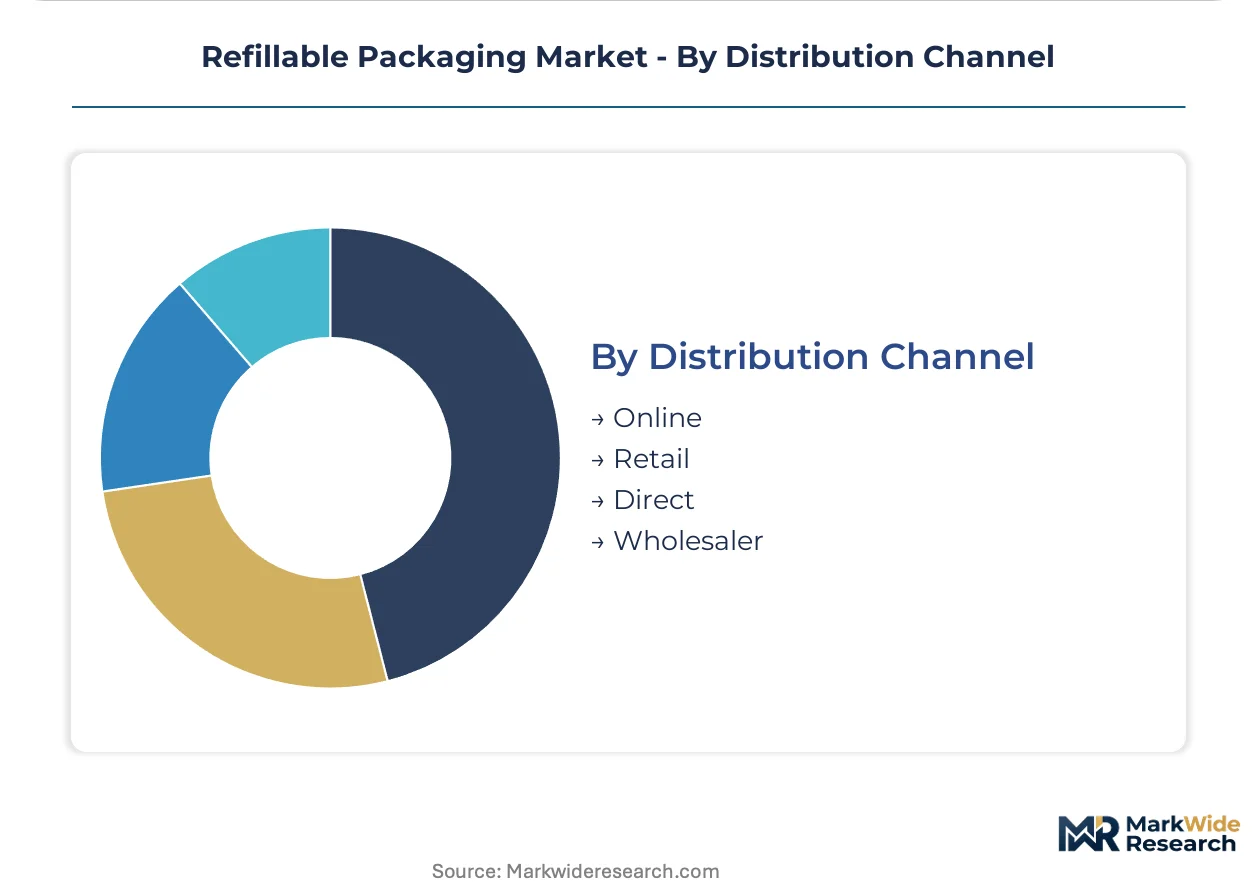
Retail dominates throughput; online gains share fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Germany tolerates substantial reverse-logistics premiums for refillable formats, while price-sensitive markets in Southern Europe and emerging economies resist cost premiums above single-use alternatives.
Germany
Retailer-led refill stations at dm-drogerie markt and REWE operate over 3,000 combined dispensing points, creating the densest adoption network globally. The EU Packaging and Packaging Waste Regulation reuse quotas scale with brand revenue, compelling domestic food manufacturers to procure validated refillable formats. Bavaria and North Rhine-Westphalia concentrate converter capacity for multilayer barrier films serving edible oil and sauce applications.
France
Premium personal care brands embed NFC-enabled smart closures for tamper-evident authentication and loyalty program integration. ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances in food contact materials accelerate fluoropolymer replacement in high-barrier formats. The Île-de-France region hosts reformulation investments by packaging converters responding to enforcement actions against non-compliant coatings.
United States
California SB 54 mandates 30% source reduction by 2032, creating regulatory tailwind for refillable adoption in personal care and cleaning categories. FDA 21 CFR 177 substance clearance lists constrain polymer selection for refillable food containers, creating dual-track compliance burdens for exporters. The Pacific Northwest and Northeast Corridor concentrate pilot programs for direct-to-consumer refill subscriptions with return-mail packaging.
Netherlands
Albert Heijn's packaging-free zones remove brand billboard space at point of sale, forcing CPG manufacturers to compete on formulation rather than shelf presence. The EU Green Claims Directive exposes brands to greenwashing liability for thin-film circularity claims. The Randstad region anchors retailer-owned refill infrastructure deployment across household cleaning and personal hygiene categories.
China
Automotive battery cell manufacturers seek ISO 17840-compliant foldable large containers for cathode active material transport, replacing single-use fiber drums. MIIT standards and GB regulations shape domestic refillable container specifications for industrial chemical applications. The Yangtze River Delta and Pearl River Delta concentrate manufacturing capacity for injection-molded polypropylene formats with extended reuse-cycle durability.
Refillable Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with multilayer barrier film specialists commanding premium tiers while standardized container pools compete on scale economics. The market exhibits tiered concentration: a narrow premium segment validated for oxygen-sensitive food applications, a broad mid-market of industrial loop operators, and fragmented regional converters serving price-sensitive household segments. Three archetypes dominate: integrated materials-science conglomerates with film expertise, industrial packaging specialists with tracked asset pools, and niche wooden-crate engineers for heavy-machinery applications. Competitive moves concentrate on barrier film advancement for oxidation-sensitive categories and RFID-enabled custody verification for closed-loop tracking.
Within the industrial loop tier, Schoeller Allibert Services BV and Orbis Corporation exemplify standardized foldable large container operators sustaining reuse cycles across automotive and chemical supply chains. Among diversified packaging conglomerates, Amcor occupies a position representing multilayer barrier film expertise for high-oxygen-sensitivity applications. Nefab Group anchors the niche tier of engineered wooden refillable crates where metal fatigue risks exclude plastic alternatives for heavy-machinery components.
| Leading Market Players |
|---|
| Amcor |
| IFCO Systems |
| Schoeller Allibert Services BV |
| Nefab Group |
| Greif Inc. |
| International Paper |
| Smurfit Westrock |
| Orbis Corporation |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
EU Packaging and Packaging Waste Regulation reuse quotas gate both supplier qualification and price differentiation simultaneously, forcing converters to validate extended reuse-cycle durability before accessing premium procurement tiers while brands face material recovery fee escalations that compress mid-market margins.
Pricing Analysis
Reverse logistics service contracts drive lifetime value in refillable packaging economics. Three-tier pricing structure across premium, standard, and economy levels separates food-grade certified multilayer barrier films from commodity injection-molded formats. Cost compression in standard-tier polypropylene containers is intensifying because US Gulf Coast propylene monomer supply disruptions feed input volatility. Household cleaning brands exhibit highest price sensitivity; pharmaceutical and premium food manufacturers accept substantial per-unit premiums for validated oxygen transmission performance.
Supply Chain Analysis
Bavaria and North Rhine-Westphalia converter clusters anchor European multilayer barrier film supply for oxidation-sensitive edible oil applications. Raw material flows draw from German chemical parks for specialty polymers, Italian coating specialists for fluoropolymer replacements, and Chinese injection molding capacity for standardized foldable containers. Single-source vulnerability concentrates in ECHA-compliant food contact coating formulations where REACH Annex XVII enforcement has triggered reformulation bottlenecks. Distribution runs through retailer-led refill station networks in Germany, with dm-drogerie markt and REWE operating the densest downstream infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refillable packaging demand tracks EU extended producer responsibility implementation cycles, with mandate activation timelines creating predictable procurement waves that favor prepared suppliers.
For Market Incumbents: Shield premium barrier film positions by deepening backward integration into specialty polymer compounding and accelerating FDA 21 CFR 177 dual-track compliance investments. Retailer-owned refill infrastructure at Carrefour Belgium and Albert Heijn Netherlands threatens brand-controlled primary packaging billboard space; secure exclusive formulation partnerships with high-volume dispensing operators to maintain shelf-equivalent visibility. For New Entrants and Emerging Players: Smart closure authentication services represent an undersupplied layer where L'Oréal and Unilever pilot programs demonstrate consumer willingness to register packaging for loyalty rewards. Pharmaceutical compliance pathways for FDA 21 CFR 211 container closure systems remain underpenetrated by refillable formats, offering first-mover advantage in OTC liquid medications with validated barrier systems. Target direct-to-consumer refill subscriptions in the US Pacific Northwest and Northeast Corridor, leveraging return-mail packaging with embedded NFC consumption tracking. For Investors and Strategic Acquirers: California SB 54's 2032 source reduction mandate reshapes the acquisition landscape by creating regulatory tailwind for refillable adoption in personal care and cleaning categories. Five-to-ten year viability favors industrial loop operators with ISO 17840-compliant tracked asset pools serving automotive battery cathode active material transport. Monitor ECHA enforcement action intensity against per- and polyfluoroalkyl substances in food contact materials as the signal for barrier coating reformulation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Film Certification Investment | ECHA REACH Annex XVII compliance for fluoropolymer replacement unlocks sauce and condiment segment access. |
| Retailer Refill Infrastructure Partnership | Exclusive dispensing agreements with dm-drogerie markt and REWE secure volume commitments in Germany's densest network. |
| RFID-Enabled Custody Verification | Blockchain-tracked container pools reduce reverse logistics cost burden through SAP and Oracle inventory module integration. |
| Pharmaceutical Validation Pathway | FDA 21 CFR 211 compliance for drug product container closure systems captures underpenetrated OTC liquid medication demand. |
| Fluoropolymer Replacement R&D | Grease-resistant coating reformulation responds to ECHA enforcement actions in German and Italian converter markets. |
Study Parameters
Desk research of EU regulatory filings, ECHA enforcement databases, and FDA food contact notification records preceded structured interviews with packaging converter technical directors, CPG brand sustainability officers, retailer category buyers, and industrial loop logistics coordinators. Primary fieldwork validated secondary data from customs trade records, SEC 10-K packaging segment disclosures, and national packaging waste registry statistics. Bottom-up volume modeling across material formats and end-use applications triangulated with top-down market sizing from producer revenue aggregates.
Variance decomposition across product type, material grade, end-use industry, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic demand drivers. Key forecast inputs included EU Packaging and Packaging Waste Regulation mandate implementation schedules, propylene monomer price volatility indices, and retailer refill station deployment trajectories.
Forecasts assume regulatory continuity in EU REACH and FDA 21 CFR regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as ECHA enforcement intensity and California SB 54 implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Refillable and Reusable Packaging Market