
 Recyclable Ovenable Trays Market | 2026-2036
Recyclable Ovenable Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Recyclable Ovenable Trays Market Analytics
Food-grade barrier specification upgrades are reorganizing competitive priorities across the Recyclable Ovenable Trays Market. Huhtamaki Oyj leverages its molded fiber expertise to anchor European retail supply chains. Sonoco Products Company sustains North American food service dominance through integrated paperboard operations. Amcor plc differentiates via high-temperature polymer laminations that compete with aluminum incumbents.
Recyclable ovenable trays are rigid containers engineered to withstand temperatures between 180°C and 220°C while maintaining structural integrity for direct-to-oven use, typically constructed from coated paperboard, anodized aluminum, or crystallized polyester designed for post-consumer recovery streams. Paper-based formats lead unit volumes in retail channels where curb-side recyclability drives purchase decisions, while aluminum retains margin concentration in premium food service and catering segments where thermal conductivity and repeated use cycles matter. Bioplastic variants represent the fastest-growing material category as brand owners seek petrochemical displacement, though polypropylene continues to dominate total production tonnage due to established reprocessing infrastructure.
EU REACH compliance and the FDA's food contact notification system govern material safety approvals, while the EU Green Deal's packaging waste targets directly mandate recyclability thresholds that reshape converter investment calendars. The EPA's emerging sustainable materials management framework signals analogous pressure in North American jurisdictions. Stakeholders must monitor evolving extended producer responsibility fee structures and sorting infrastructure compatibility standards to anticipate which material platforms achieve scale economics.
Market Dynamics
The EU Packaging and Packaging Waste Regulation mandates 70% material recovery by 2030, forcing converters to abandon multi-layer laminates for mono-material designs that sort cleanly in municipal streams.
Growth Catalysts
- Extended Producer Responsibility frameworks:Germany's Verpackungsgesetz imposes modulated fees based on recyclability scores, accelerating converter investment in fiber-based tray platforms.
- QSR sustainability mandates:Quick-service restaurant chains in the United States now specify oven-safe recyclable containers for hot-hold applications, displacing expanded polystyrene clamshells.
- Retail private-label programs:United Kingdom supermarket chains embed curb-side recyclability claims into own-brand ready-meal packaging specifications.
Market Restraints
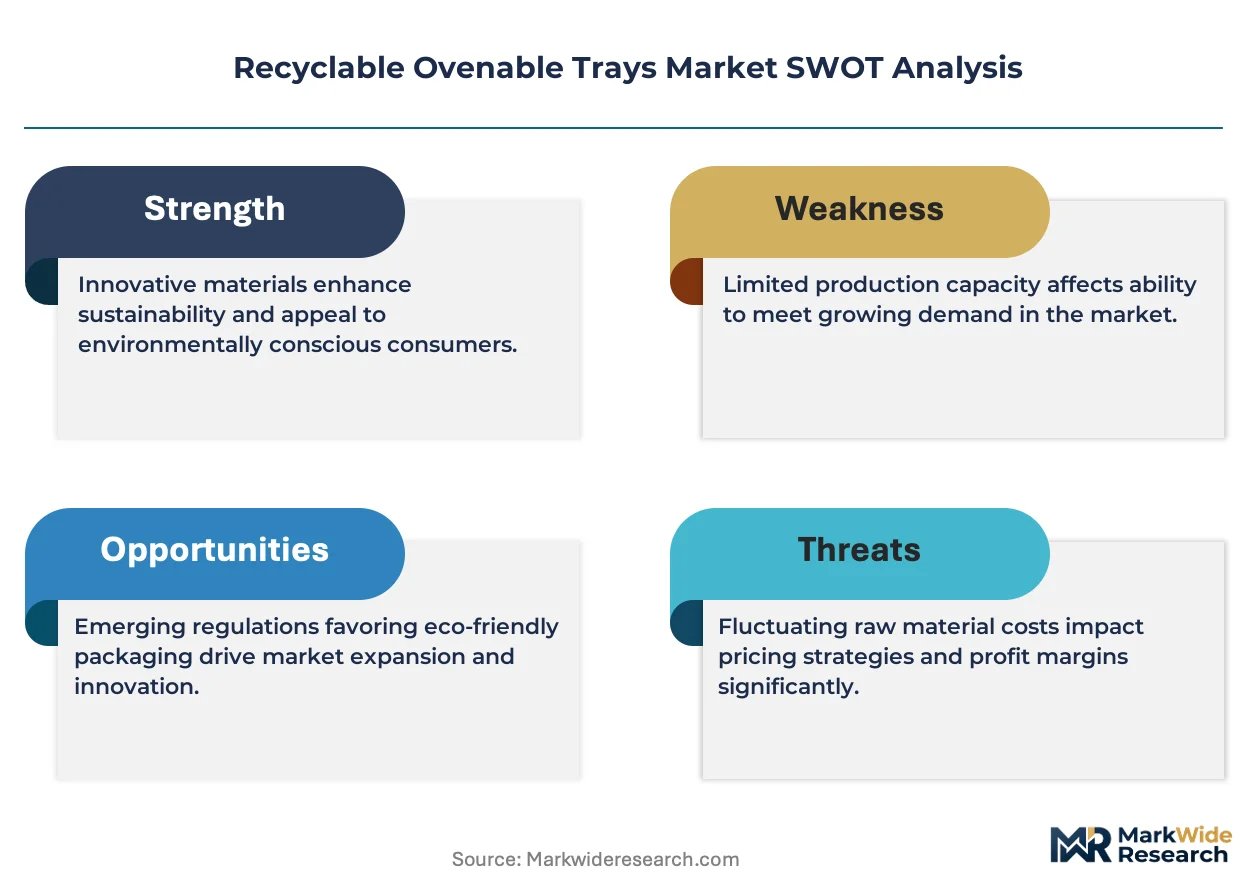
- Recycled pulp cost volatility:Post-consumer fiber prices fluctuate with municipal collection rates, compressing margins for molded fiber tray producers.
- Barrier coating supply concentration:Water-based and bio-based oxygen barrier chemistries concentrate among European specialty chemical suppliers, creating input dependency.
- Aluminum thermal performance:Anodized aluminum retains unmatched heat conductivity for repeated oven cycles, limiting paperboard penetration in catering segments.
Strategic Opportunities
- India food service modernization:Organized food retail and cloud kitchen expansion creates first-mover potential for ovenable fiber tray suppliers establishing local converting partnerships.
- Carbon border adjustment mechanisms:The EU CBAM creates competitive advantage for low-carbon-intensity packaging materials in export-oriented food processing.
- Smart packaging integration:Time-temperature indicators and QR-linked traceability converge with ovenable substrates to create premium positioned intelligent packaging.
Industry Challenges
- Food contact notification timelines:Novel barrier coatings face 12-18 month FDA review cycles, delaying product commercialization.
- Sorting infrastructure misalignment:Near-infrared detection systems at materials recovery facilities inconsistently recognize new bio-based polyester variants, causing downstream contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recyclable Ovenable Trays Market |
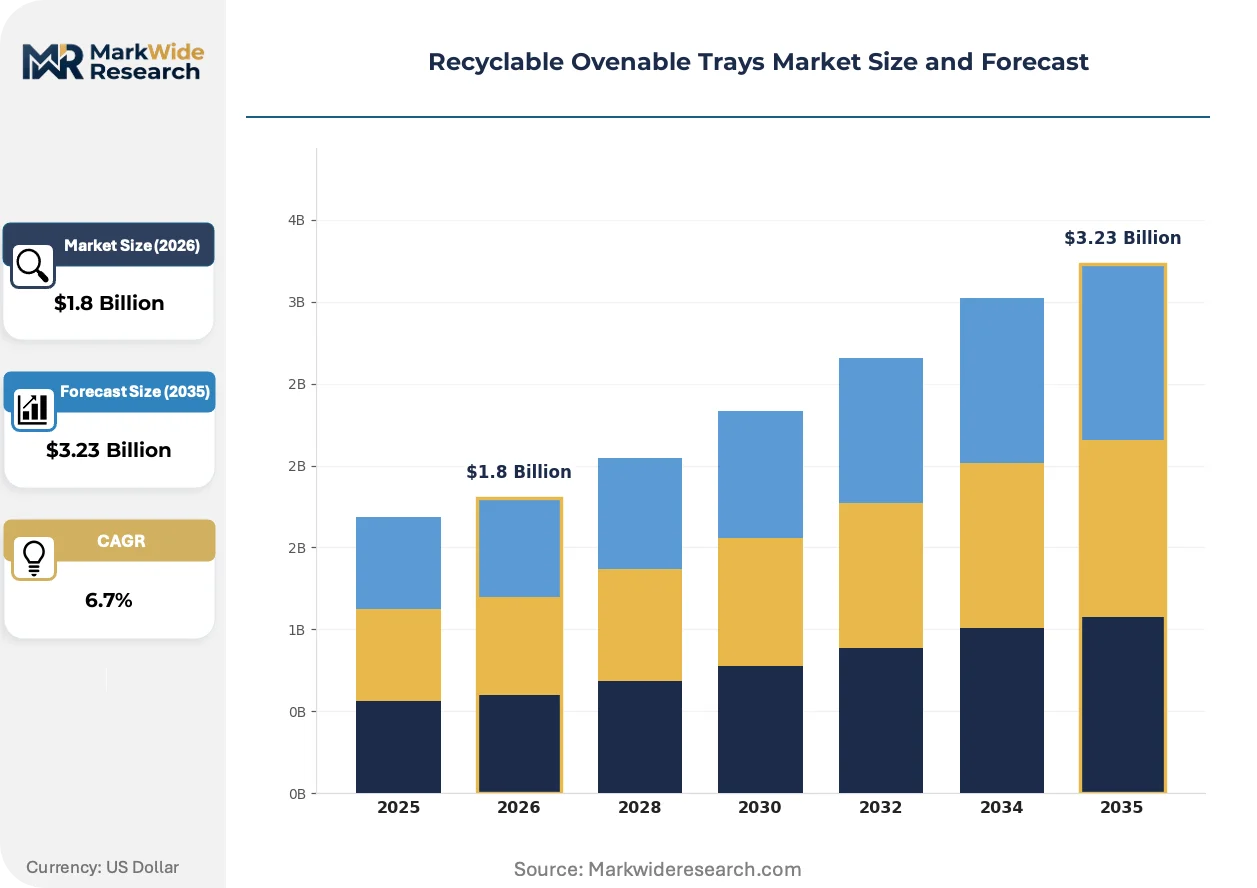
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Aluminum, Bioplastic, Polypropylene End User: Food Service, Retail, Catering, Food Processing Application: Ready-to-Eat Meals, Baking, Food Storage, Cooking Distribution Channel: Online, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Huhtamaki Oyj, Sonoco Products Company, Amcor plc, Pactiv Evergreen Inc., Sabert Corporation, Berry Global Inc., WestRock Company, Faerch Group, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recyclable Ovenable Trays Market Evolving Landscape
Material science advances and sorting infrastructure upgrades are redefining performance thresholds for ovenable packaging, separating converters who control substrate-barrier integration from those dependent on external film lamination.
Crystallized polyethylene terephthalate (CPET) tray production is bifurcating between legacy amorphous PET lines and next-generation direct-to-sheet crystallization systems. European ready-meal manufacturers are adopting the newer platform for its 220°C thermal ceiling and clean mono-material recovery profile. This technology compression is marginalizing converters still running multi-step thermoforming with imported sheet.
The EU Green Deal's packaging waste targets now explicitly mandate design-for-recycling criteria across all member states. Industrial consequence includes mandatory mono-material construction and standardized labeling that eliminates consumer sorting confusion. Premium chilled ready-meal segments in France and the Netherlands are responding fastest, eliminating black plastics and adopting detectable colorants.
Buyer specification protocols now require third-party recyclability certification prior to contract award, replacing informal supplier claims. United States retail procurement teams are embedding How2Recycle and APR design recognition into vendor scorecards. This verification-driven preference shift concentrates volume with converters who maintain in-house testing laboratories and pre-qualification documentation.
Recyclable Ovenable Trays Market Segmentation
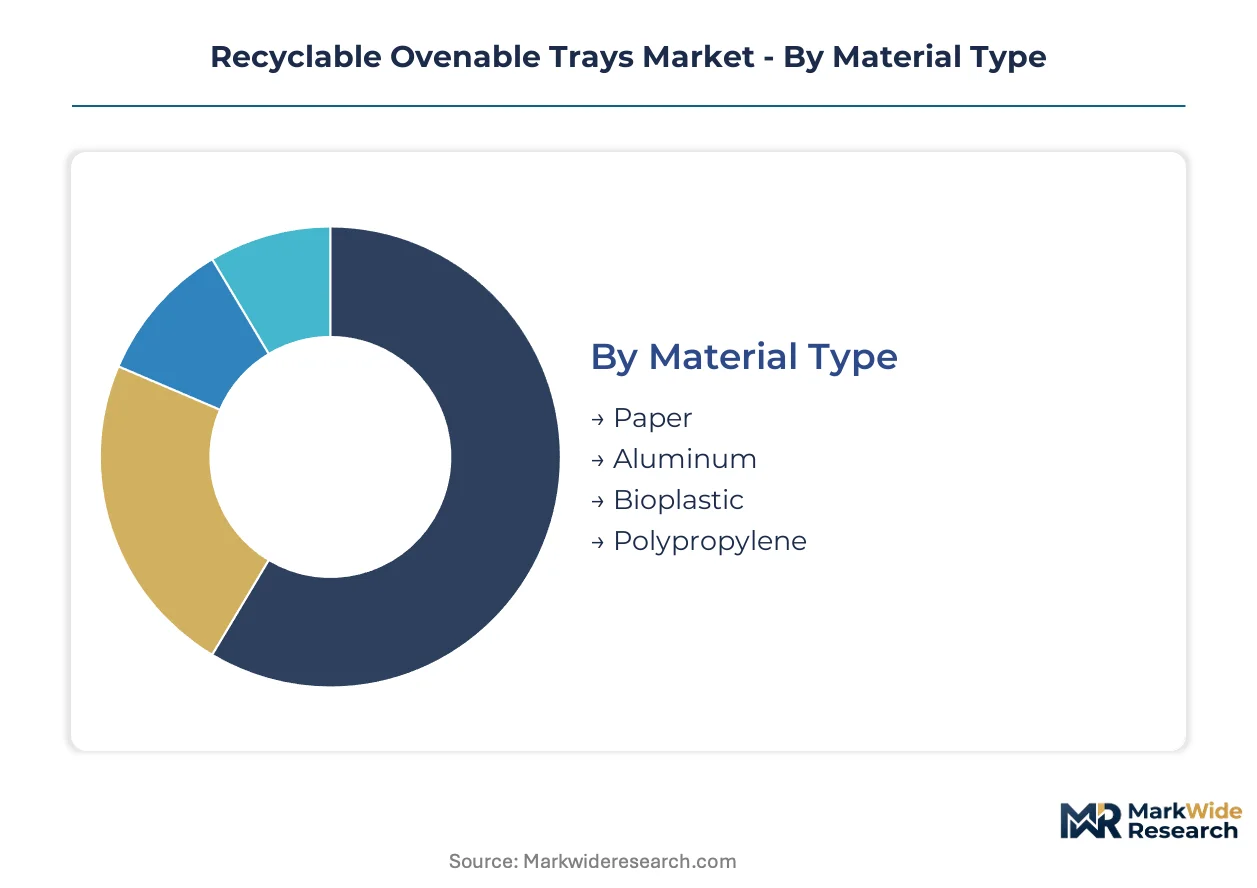
Material platform selection determines recyclability certification eligibility and thermal performance ceilings, creating divergent margin profiles across converter portfolios. End-user procurement protocols now mandate third-party recyclability verification prior to contract award, reshaping competitive positioning within each segment cluster.
Material Type:
Aluminum faces the most acute substitution pressure as fiber-based barriers close the thermal performance gap and EPR frameworks penalize high-carbon-intensity substrates.
- Paper:Coated paperboard and molded fiber constructions dominate retail ready-meal applications where curb-side recyclability drives consumer purchase decisions. United Kingdom supermarket chains specify fiber-based trays for private-label programs, though barrier coating supply concentration among European specialty chemical suppliers creates input dependency risks.
- Aluminum:Anodized aluminum retains unmatched thermal conductivity for repeated oven cycles above 200°C, anchoring premium catering and food service segments where durability matters. Germany's Verpackungsgesetz imposes modulated EPR fees based on recyclability scores, compressing aluminum's cost position against mono-material alternatives.
- Bioplastic:Crystallized PLA and bio-based polyester variants target petrochemical displacement in brand owner sustainability roadmaps.
- Polypropylene:Established reprocessing infrastructure and FDA food contact notification precedents sustain volume leadership in North American food service.
Polypropylene retains volume leadership; bioplastic holds the steepest expansion curve.
End User:
Procurement scale concentrates with institutional buyers who embed recyclability mandates into vendor scorecards, favoring converters with in-house testing laboratories.
- Food Service:Quick-service restaurant chains in the United States now specify oven-safe recyclable containers for hot-hold applications, displacing expanded polystyrene clamshells. Major operators require How2Recycle and APR design recognition prior to contract award.
- Retail:Supermarket private-label programs in France and the Netherlands are eliminating black plastics and adopting detectable colorants fastest, responding to EU Green Deal packaging waste targets. Third-party recyclability certification has replaced informal supplier claims in procurement protocols.
- Catering:Repeated use cycle requirements sustain aluminum penetration despite fiber-based substitution pressure.
- Food Processing:Export-oriented processors face EU CBAM competitive pressure favoring low-carbon-intensity packaging materials.
Food service commands procurement volume concentration; retail exhibits the most rapid specification upgrade velocity.
Application:
Temperature exposure duration and moisture content determine barrier coating requirements, segmenting converter technical capabilities.
- Ready-to-Eat Meals:Chilled and frozen ready-meal segments in France and the Netherlands are adopting CPET direct-to-sheet crystallization systems for 220°C thermal ceilings and clean mono-material recovery. This platform marginalizes converters running multi-step thermoforming with imported sheet.
- Baking:Sustained high-temperature exposure above 180°C favors aluminum and crystallized polyester where fiber-based barriers face performance ceilings.
- Food Storage:Lower thermal requirements enable broader fiber-based penetration in refrigerated applications.
- Cooking:Direct-to-oven use from frozen state demands substrate-barrier integration control that separates integrated converters from film-lamination dependent suppliers.
Ready-to-eat meals anchor revenue concentration; baking maintains the highest technical barrier to entry.
Distribution Channel:
Channel selection determines labeling standardization requirements and lot traceability obligations, with retail-facing channels imposing stricter verification protocols.
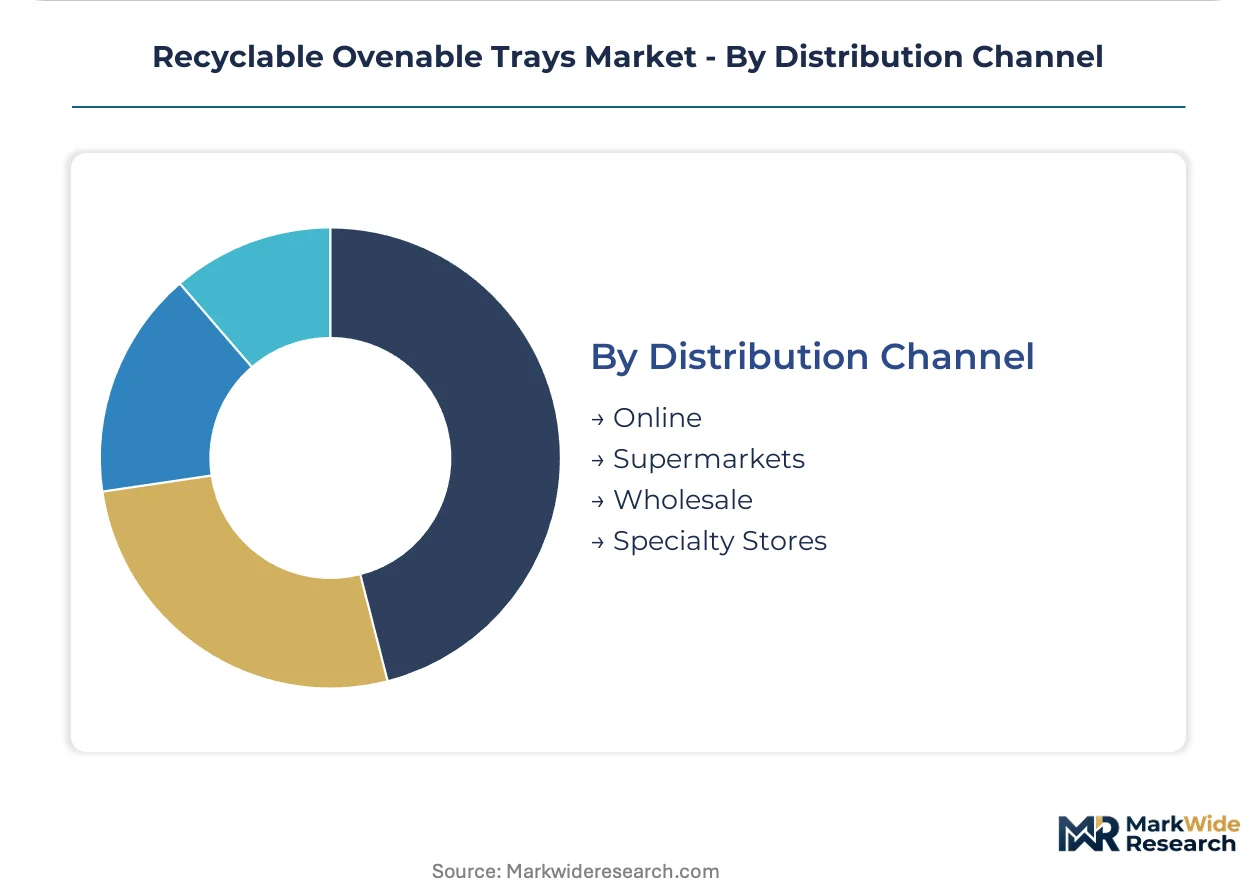
- Supermarkets:United Kingdom and German retail procurement teams embed How2Recycle and APR design recognition into vendor scorecards, concentrating volume with pre-qualified converters. Shelf placement contracts now require documented recyclability certification.
- Wholesale:Institutional supply to food service and catering segments prioritizes unit cost and thermal performance over curb-side recyclability claims.
- Online:E-commerce direct-to-consumer channels expose packaging to consumer scrutiny, amplifying sustainability claim verification requirements.
- Specialty Stores:Premium positioning in organic and gourmet segments creates niche demand for bio-based and compostable variants.
Supermarkets dominate procurement scale; online channels are expanding most quickly as direct-to-consumer meal kit subscriptions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, the United Kingdom, and the United States where EPR frameworks and retail procurement mandates create concentrated demand pull. These three markets account for the dominant share of investment in mono-material tray platforms and third-party recyclability certification infrastructure.
Germany
Retail private-label programs and QSR sustainability mandates drive specification upgrades across ready-meal packaging. The Verpackungsgesetz imposes modulated EPR fees based on recyclability scores, penalizing multi-layer laminates. Converting activity concentrates in North Rhine-Westphalia where integrated paperboard operations serve pan-European supply chains.
United Kingdom
Supermarket chains embed curb-side recyclability claims into own-brand procurement protocols, displacing black plastics with detectable colorants. The Environment Agency enforces packaging waste regulations aligned with EU Green Deal targets. Industrial capacity clusters in the Midlands and Greater London where molded fiber tray production scales for retail distribution.
United States
Quick-service restaurant chains specify oven-safe recyclable containers for hot-hold applications, replacing expanded polystyrene clamshells. The EPA's sustainable materials management framework signals tightening recyclability standards. Converting capacity concentrates in the Midwest and Southeast where integrated paperboard mills supply food service and retail channels.
France
Premium chilled ready-meal segments adopt CPET direct-to-sheet crystallization systems fastest, eliminating black plastics under EU packaging waste mandates. ANSM and environmental regulators enforce design-for-recycling criteria. Packaging innovation clusters in Île-de-France and Auvergne-Rhône-Alpes where converters develop high-temperature mono-material solutions.
India
Organized food retail and cloud kitchen expansion creates first-mover potential for ovenable fiber tray suppliers establishing local partnerships. FSSAI governs food contact safety while BIS standards address packaging material specifications. Industrial activity concentrates in Maharashtra and Karnataka where converting partnerships target food service modernization in Mumbai and Bangalore.
Recyclable Ovenable Trays Market Competitive Landscape
Concentration sits with integrated paperboard and packaging specialists who control substrate-barrier integration and maintain in-house recyclability testing laboratories. The competitive structure spans three tiers: multinational converters with global retail supply chain anchoring, regional specialists with EPR-optimized mono-material platforms, and emerging players targeting bioplastic displacement. Dominant competitive moves include strategic partnerships with specialty chemical suppliers for barrier coating access and capacity expansion in CPET direct-to-sheet crystallization systems.
Among Nordic and North American integrated packaging groups, Huhtamaki Oyj and Sonoco Products Company exemplify the substrate-control archetype, while Amcor plc occupies a position within the high-performance polymer lamination tier. These three companies represent contrasting strategic bets on material platforms—fiber-based molded construction, integrated paperboard operations, and crystallized polyester systems—each anchoring different thermal performance and recyclability certification profiles.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Sonoco Products Company |
| Amcor plc |
| Pactiv Evergreen Inc. |
| Sabert Corporation |
| Berry Global Inc. |
| WestRock Company |
| Faerch Group |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
Fiber-based barrier coatings displacing aluminum in ovenable tray construction simultaneously redraw supply geography toward Nordic pulp clusters and compress pricing premiums previously commanded by metal substrates. The EU Packaging and Packaging Waste Regulation amplifies this shift by penalizing high-carbon-intensity materials through modulated EPR fees, redirecting converter investment toward integrated paperboard operations.
Pricing Analysis
Germany's Verpackungsgesetz dictates the pricing tier structure across the recyclable ovenable trays market, with recyclability scores determining fee modulation and contract eligibility. Pricing stratifies across premium, standard, and economy tiers based on barrier performance certification and volume scale commitments. Cost compression in molded fiber platforms is intensifying because post-consumer pulp price volatility runs through European specialty chemical supply chains. Quick-service restaurant chains exhibit highest price sensitivity due to procurement scale pressures, while premium catering segments remain least sensitive given repeated-use thermal performance requirements.
Supply Chain Analysis
Inventory cycles for barrier-coated paperboard extend 8-12 weeks longer than aluminum sheet due to pulp conditioning and coating curing requirements. Raw material sourcing draws from Swedish and Finnish pulp mills, German specialty chemical suppliers for water-based oxygen barriers, and Norwegian crystallized PET resin operations. Single-source vulnerability concentrates in European barrier coating chemistries where three specialty chemical suppliers control food-grade formulations. Distribution runs through integrated converter-direct models for retail private-label programs and wholesale distributors for food service institutional supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recyclable ovenable trays market functions as a service-attach opportunity where third-party recyclability certification and compliance documentation subscriptions expand faster than substrate hardware sales. Recurring revenue from pre-qualification testing and regulatory filing support now anchors converter profitability.
For Market Incumbents: Shield market position by deepening backward integration into barrier coating formulation and expanding in-house testing laboratory capacity. Capture fiber-based substitution momentum through captive pulp supply agreements with Nordic mills. Defend against emerging bioplastic specialists by accelerating CPET direct-to-sheet crystallization capacity in Germany and France. For New Entrants and Emerging Players: Lead with India food service modernization partnerships targeting cloud kitchen tray supply in Mumbai and Bangalore. Penetrate the wholesale institutional channel where thermal performance specifications remain less stringent than retail certification requirements. Pursue joint-venture converting arrangements with established European barrier coating suppliers to bypass 12-18 month FDA food contact notification timelines. For Investors and Strategic Acquirers: EU Green Deal packaging waste targets reshaping the acquisition landscape toward converters with pre-qualified mono-material platforms and documented design-for-recycling capabilities. Long-term viability centers on substrate-barrier integration control rather than film-lamination dependency. Target acquisition archetype: regional specialists with EPR-optimized fiber tray operations and established How2Recycle certification relationships. Monitor EU CBAM implementation pace as inflection signal for low-carbon-intensity packaging material competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Coating | Reduces input dependency on European specialty chemical suppliers and compresses cost position. |
| CPET Direct-to-Sheet Crystallization Capacity | Secures 220°C thermal ceiling performance and clean mono-material recovery profile for ready-meal segments. |
| Third-Party Recyclability Certification | Unlocks United Kingdom and German supermarket private-label procurement where pre-qualification is mandatory. |
| India Local Converting Partnership | Captures cloud kitchen expansion in Mumbai and Bangalore ahead of organized food retail maturation. |
| Smart Packaging Integration | Converges time-temperature indicators with ovenable substrates for premium intelligent packaging positioning. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with packaging converters, retail procurement directors, and food service supply chain managers; and secondary validation through EU regulatory filings, EPA sustainable materials management disclosures, and trade customs records for pulp and resin flows. Bottom-up triangulation across converter capacity assessments and top-down demand modeling from ready-meal production volumes anchored value and volume estimates.
Across the projection horizon, the analytical framework modeled material platform substitution dynamics, end-user procurement protocol evolution, and regional EPR framework implementation pace. Segmentation dimensions included material type, thermal performance tier, recyclability certification status, and distribution channel structure. CAGRs derived from installed converting capacity expansion schedules cross-referenced against regulatory mandate compliance deadlines and buyer specification upgrade timelines.
Forecasts assume regulatory continuity in EU member state packaging waste regimes and United States EPA sustainable materials management frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Refillable and Reusable Packaging Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Reusable Food Wrap Market
Reusable Packaging
Reusable Water Bottle Market