
 Refillable and Reusable Packaging Market | 2026-2036
Refillable and Reusable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Refillable and Reusable Packaging Market Insights
Food-grade certification tiers is redrawing procurement priorities across the refillable and reusable packaging sector. DS Smith leverages its corrugated expertise to develop multi-trip transit packaging for grocery supply chains. Schoeller Allibert anchors European demand through its standardized plastic crate and pallet pooling systems. ORBIS Corporation dominates North American automotive and food manufacturing with its structural foam reusable containers.
Refillable and reusable packaging encompasses durable containers engineered for multiple use cycles, typically fabricated from high-density polyethylene, borosilicate glass, or anodized aluminum with minimum wall thickness specifications of 0.8-2.5 millimeters to withstand industrial washing protocols. Its primary commercial purpose centers on eliminating single-use material throughput while maintaining product integrity across beverage, personal care, and pharmaceutical distribution networks. Glass bottles command premium positioning in personal care due to chemical inertness and aesthetic differentiation, while plastic containers lead volume in food and beverage applications where lightweighting and drop resistance govern total cost of ownership. Metal formats sustain growth in household products where barrier properties against oxygen and ultraviolet degradation prove critical.
The EU Packaging and Packaging Waste Regulation imposes binding reuse quotas on beverage and transport packaging, compelling manufacturers to redesign for standardized return logistics. FDA food contact substance notifications govern refillable container materials in the United States, while EFSA safety assessments shape European material approvals. Stakeholders must monitor how California's SB 54 extended producer responsibility framework and Germany's VerpackG amendment interact with emerging refill infrastructure investments to determine capital allocation between material innovation and reverse logistics platform buildout.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles across beverage and transport packaging categories, forcing manufacturers to reengineer for standardized return logistics before reuse quotas take binding effect.
Growth Catalysts
- EU reuse mandates:Binding quotas on beverage and transport packaging under the EU Packaging and Packaging Waste Regulation are compelling manufacturers to redesign for circularity. Food and beverage brands across Germany, France, and the United Kingdom are scaling refill station networks in retail locations.
- Deposit-return infrastructure:Western European grocery retail is embedding bulk dispensing systems as standard fixtures. Supermarket chains in Scandinavia and the Netherlands are integrating automated refill stations into store layouts.
- HDPE durability advances:High-density polyethylene formulations achieving 50+ wash cycles are displacing single-use alternatives in food manufacturing. Minimum wall thickness specifications of 0.8-2.5 millimeters now withstand industrial washing protocols.
Market Restraints
- Reverse logistics capex intensity:Standardized crate and pallet pooling systems require substantial capital deployment for washing facilities and tracking infrastructure. The cost structure favors large-scale operators over mid-tier entrants.
- Food-grade certification timelines:EFSA safety assessments and FDA food contact substance notifications create extended approval cycles for novel materials. Certification delays compress product launch windows.
- Glass weight penalty:Borosilicate glass formats command premium positioning in personal care but impose transport cost disadvantages against lightweight plastic alternatives. The weight differential limits geographic expansion for glass-heavy portfolios.
Strategic Opportunities
- Pharmaceutical distribution networks:Chemical inertness requirements in pharmaceutical logistics create white space for anodized aluminum and glass formats with barrier properties against oxygen and ultraviolet degradation.
- California SB 54 alignment:Extended producer responsibility frameworks in the United States are creating regulatory tailwinds for refill infrastructure investments ahead of federal standardization.
- RFID-integrated tracking:Convergence of radio-frequency identification with blockchain verification is enabling asset-level traceability for multi-trip containers. Pooling operators are piloting smart crate systems.
Industry Challenges
- Integration complexity with legacy ERP:Reverse logistics platforms require reconfiguration of enterprise resource planning systems to manage return cycles. Food manufacturers face disruption to established inventory management workflows.
- Standardization delays across national schemes:Germany's VerpackG amendment operates on different technical specifications than French refill station protocols. Interoperability gaps fragment pooling network economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refillable and Reusable Packaging Market |
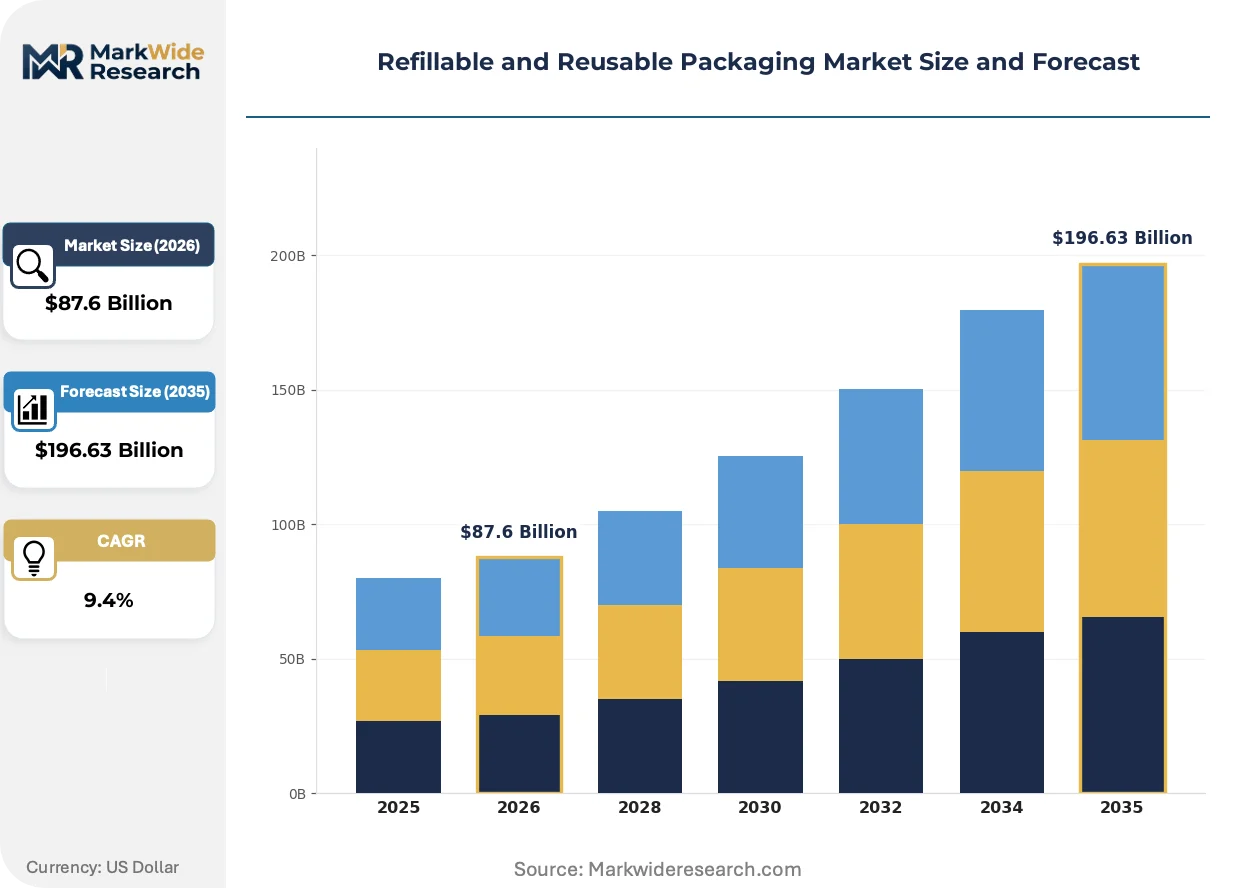
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Pouches, Tubs Material: Glass, Plastic, Metal, Wood End Use Industry: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | DS Smith, Menasha Corporation, Nefab Group, Schoeller Allibert, ORBIS Corporation, Amcor, IFCO Systems, Ball Corporation, TerraCycle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refillable and Reusable Packaging Market Trends and Innovations
Material science breakthroughs and regulatory compression are converging to reshape competitive positioning in refillable packaging, with durability standards and traceability requirements becoming primary design constraints.
Smart tracking hardware is miniaturizing. Embedded sensors in high-density polyethylene containers now monitor temperature exposure and wash cycle counts in real time. Beverage distributors in Germany and the Netherlands are deploying these units across refill station networks. The technology is miniaturizing cost barriers that previously limited asset-level monitoring to premium glass formats.
REACH substance restrictions are tightening material approvals for food contact applications. ECHA evaluations of per- and polyfluoroalkyl substances are forcing reformulation of barrier coatings in metal containers. Manufacturers serving household products segments are accelerating migration to silicone-based alternatives ahead of restriction deadlines.
Retail procurement patterns are fragmenting across channel types. Grocery chains are unbundling packaging procurement from product supply agreements, creating direct relationships with pooling operators. This shift is most visible in French and British supermarket networks, where refill station operators now contract separately from beverage brand owners.
Refillable and Reusable Packaging Market Segmentation
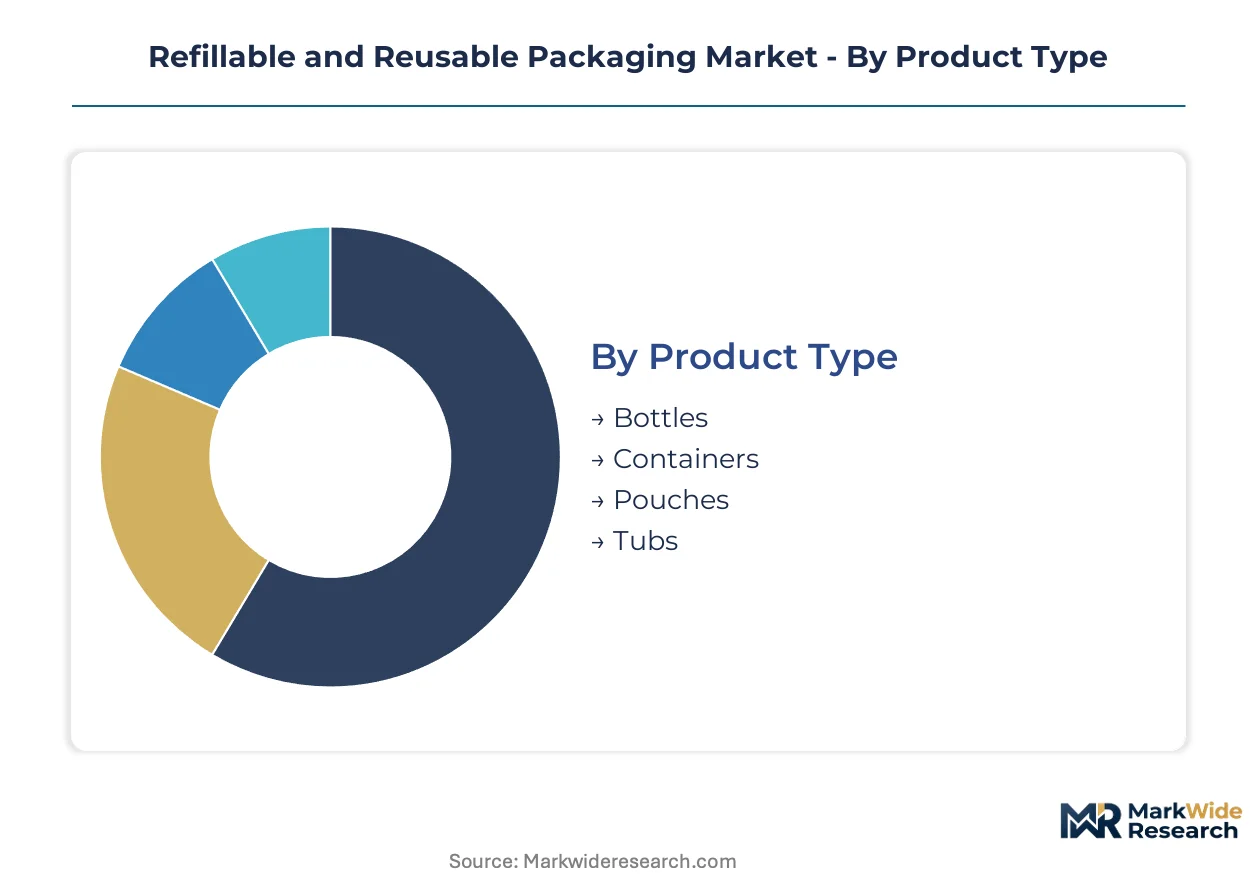
Refillable packaging procurement decisions diverge sharply across channel types, with grocery retail favoring standardized pooling formats while direct-to-consumer models prioritize aesthetic differentiation. Material specifications and wash-cycle durability requirements further fragment segment economics, creating distinct competitive arenas within each category.
Product Type:
Bottles flow predominantly through supermarket refill stations and direct sales channels, while containers and tubs concentrate in food manufacturing and industrial pooling networks. Pouch formats remain concentrated in online retail due to lightweight shipping economics.
- Bottles:Engineered from borosilicate glass or high-density polyethylene with 0.8-2.5 millimeter wall thickness to withstand 50+ industrial wash cycles. German and French beverage distributors are scaling standardized returnable bottle networks under EU reuse mandates, though glass weight penalties limit geographic expansion against plastic alternatives.
- Containers:Structural foam HDPE formats dominate automotive and food manufacturing applications through standardized crate pooling systems. ORBIS Corporation and Schoeller Allibert anchor demand through multi-trip transit packaging with embedded RFID tracking for asset-level traceability.
- Pouches:Flexible laminated constructions with silicone-based barrier coatings are displacing per- and polyfluoroalkyl substance formulations ahead of ECHA restriction deadlines.
- Tubs:Anodized aluminum and thick-walled plastic formats serve household products and personal care segments where chemical resistance governs material selection.
Bottles dominate installed base across retail refill infrastructure. Containers are where expansion concentrates as food manufacturers reconfigure supply chains for circularity.
Material:
Cost tiers stratify procurement patterns, with plastic commanding volume leadership through lightweighting advantages while glass and metal capture premium positioning through barrier properties and aesthetic differentiation.
- Glass:Borosilicate compositions command personal care applications due to chemical inertness and premium shelf presence. Transport cost disadvantages against plastic alternatives constrain expansion beyond urban refill station networks in Germany, France, and the United Kingdom.
- Plastic:HDPE formulations achieving extended wash-cycle durability are displacing single-use alternatives across food and beverage manufacturing. Minimum thickness specifications now standardize at 0.8-2.5 millimeters for industrial washing protocol compatibility.
- Metal:Anodized aluminum formats sustain growth in household products and pharmaceuticals where oxygen and ultraviolet barrier properties prove critical against REACH substance restrictions.
- Wood:Limited to specialty applications and artisanal retail segments with minimal standardization for industrial return logistics.
Plastic leads volume throughput across refill station networks. Glass is climbing the fastest in personal care direct-to-consumer channels.
End Use Industry:
Application requirements dictate material certification intensity, with pharmaceuticals demanding EFSA and FDA food contact approvals while household products navigate evolving REACH barrier coating regulations.
- Food & Beverage:Deposit-return systems and bulk dispensing infrastructure are becoming standard fixtures in Western European grocery retail, with Scandinavian and Dutch supermarket chains integrating automated refill stations.
- Personal Care:Premium glass bottle demand concentrates in direct sales and online retail channels where aesthetic differentiation commands price premiums.
- Household Products:Metal container demand is accelerating migration to silicone-based barrier coatings ahead of ECHA per- and polyfluoroalkyl substance restriction deadlines.
- Pharmaceuticals:Chemical inertness requirements create white space for anodized aluminum and specialized glass formats with oxygen and ultraviolet degradation protection.
Food and Beverage anchors installed base through standardized pooling networks. Pharmaceuticals represents the steepest expansion trajectory as distribution networks adopt circular packaging protocols.
Distribution Channel:
Customer type fragmentation is unbundling procurement relationships, with grocery chains contracting directly with pooling operators rather than beverage brand owners.
- Online Retail:Lightweight pouch formats and premium glass bottles dominate, with fulfillment economics favoring reduced shipping weights and aesthetic unboxing experiences.
- Supermarkets:Automated refill station deployment is scaling across German, French, and British networks, with standardized crate and pallet pooling systems requiring substantial capital deployment for washing facilities.
- Convenience Stores:Limited refill infrastructure penetration due to space constraints and reverse logistics complexity, concentrating instead on pre-filled returnable formats.
- Direct Sales:Personal care and premium household products leverage glass and metal formats for brand differentiation, bypassing standardized pooling economics.
Supermarkets dominate refill infrastructure deployment. Online Retail is gaining share fastest as direct-to-consumer circular models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Western European buyers absorb premium pricing for certified food-grade formats, while emerging market procurement prioritizes cost-optimized plastic alternatives with reduced wash-cycle specifications.
Germany
Deposit-return infrastructure density exceeds any European peer, with automated refill stations now standard in Rewe and Edeka locations. The VerpackG amendment mandates strict reuse quotas and tracking requirements for beverage distributors. Berlin and Hamburg anchor national pooling network expansion, where Schoeller Allibert operates standardized crate systems for grocery supply chains.
France
Retail procurement unbundling accelerates as Carrefour and Intermarché contract directly with refill station operators rather than brand owners. EFSA safety assessments govern material approvals for food contact applications, extending certification timelines for novel barrier coatings. The Île-de-France region concentrates pilot deployments of RFID-integrated tracking systems for asset-level traceability.
United Kingdom
Supermarket chains embed bulk dispensing infrastructure as competitive differentiation, with Tesco and Sainsbury's scaling refill station networks. Post-Brexit regulatory divergence from EU Packaging and Packaging Waste Regulation creates compliance complexity for cross-border pooling operators. London and the Southeast lead installed base density, though Northern England shows fastest network expansion rates.
United States
California SB 54 extended producer responsibility frameworks drive refill infrastructure investment ahead of potential federal standardization. FDA food contact substance notifications govern refillable container materials, creating approval bottlenecks for imported formats. The Pacific Northwest and Northeast Corridor concentrate early-adopter retail deployments, with Chicago and Austin emerging as secondary hubs.
Netherlands
Automated refill station penetration rates lead continental Europe, with Albert Heijn integrating dispensing systems into standard store layouts. REACH substance restrictions tighten material approvals, forcing reformulation of barrier coatings ahead of ECHA per- and polyfluoroalkyl substance deadlines. The Randstad urban corridor functions as testing ground for smart crate systems with embedded wash-cycle monitoring.
Refillable and Reusable Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes. The market exhibits tiered concentration, with large-scale pooling operators commanding standardized transit packaging segments while specialized fabricators capture premium niches through material differentiation. Three archetypes dominate: corrugated specialists leveraging fiber expertise for multi-trip applications, plastic crate pooling operators with reverse logistics platforms, and metal/glass premium format providers serving personal care and pharmaceutical channels. Competitive moves center on M&A for pooling network density and strategic partnerships for RFID-integrated tracking infrastructure.
Within the corrugated specialist tier, DS Smith represents integrated fiber-to-format capability. Schoeller Allibert and ORBIS Corporation exemplify divergent geographic anchoring strategies for plastic pooling systems. Among diversified packaging conglomerates, Amcor occupies a position spanning material science and refillable format development. These three players illustrate how scale, specialization, and geographic focus segment competitive positioning across the value chain.
| Leading Market Players |
|---|
| DS Smith |
| Menasha Corporation |
| Nefab Group |
| Schoeller Allibert |
| ORBIS Corporation |
| Amcor |
| IFCO Systems |
| Ball Corporation |
| TerraCycle |
| Others |
Pricing and Supply Chain Analysis
HDPE formulation substitution for borosilicate glass in beverage refill networks simultaneously concentrates supply geography around German and Dutch polymer processing hubs and compresses pricing economics through reduced transport cost penalties. This material shift reshapes procurement negotiations as pooling operators gain leverage over brand owners in standardized crate contracts.
Pricing Analysis
Wash-cycle service revenue tiers drive lifetime value for pooling operators, with contracts bundling container provision, industrial cleaning, and RFID tracking commanding premium positioning. Pricing stratifies across premium certified food-grade formats, standard multi-trip containers, and economy single-use alternatives based on EFSA certification status and volume commitment scale. Pricing pressure stems from reverse logistics capex intensity favoring large-scale operators over mid-tier entrants. Grocery retail chains exhibit highest price sensitivity due to unbundled procurement relationships, while pharmaceutical distributors absorb premiums for barrier-certified formats.
Supply Chain Analysis
Strategic stockpile preferences dominate resin procurement as HDPE suppliers buffer against REACH substance restriction uncertainty and ECHA evaluation timelines. Manufacturing concentrates in Germany, the Netherlands, and Belgium around automated refill station deployment corridors. Raw material dependencies center on high-density polyethylene resin, anodized aluminum sheet, and borosilicate glass tubing. Single-source vulnerability runs through specialized barrier coating formulations facing ECHA per- and polyfluoroalkyl substance deadlines. Distribution runs through standardized crate pooling networks with embedded RFID tracking infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward grocery retail chains as procurement unbundling fragments traditional brand-owner packaging contracts. Carrefour and Tesco now negotiate directly with pooling operators, consolidating demand concentration.
For Market Incumbents: Secure reverse logistics platform density through captive washing facility investments in the Randstad and Île-de-France corridors. Pooling operators must defend against mid-tier entrants by accelerating RFID-integrated tracking deployment ahead of interoperability standardization. Vertical integration into resin compounding insulates margin compression from REACH-driven reformulation cycles. For New Entrants and Emerging Players: EFSA fast-track certification for silicone-based barrier coatings opens white space in household products segments ahead of restriction deadlines. Pharmaceutical distribution networks present the most penetrable application, with chemical inertness requirements creating entry barriers that favor specialized fabricators over diversified incumbents. Target direct-to-consumer personal care channels with premium glass formats bypassing standardized pooling economics. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors pooling operators with installed washing infrastructure over material innovators. Long-term viability across the analysis window hinges on reverse logistics network density rather than patent-protected formulations. Acquisition targets should demonstrate captive relationships with German or French grocery retail chains. The signal to watch is VerpackG amendment enforcement intensity as inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Integrated Tracking Deployment | Enables asset-level traceability for multi-trip containers across German refill station networks. |
| Backward Integration into Resin Compounding | Insulates margin pressure from REACH-driven HDPE reformulation cycles and supply uncertainty. |
| EFSA Fast-Track Certification Investment | Accelerates market access for silicone-based barrier coatings ahead of ECHA restriction deadlines. |
| Retail Procurement Unbundling Partnership | Creates direct contractual relationships with Carrefour and Tesco separate from brand owners. |
| Pharmaceutical Distribution Network Entry | Captures premium positioning through anodized aluminum formats with oxygen barrier properties. |
Research Methodology
Cross-validation between executive interviews and customs trade data anchors the qualitative findings in observable shipment patterns. Primary fieldwork engaged packaging procurement directors at grocery retail chains, pooling operator logistics heads, EFSA regulatory affairs specialists, and HDPE resin procurement managers. Secondary sources included EU Packaging and Packaging Waste Regulation filings, ECHA substance restriction evaluations, SEC 10-K disclosures from listed packaging conglomerates, and trade data from German and Dutch polymer processing hubs. Bottom-up demand modeling triangulated against top-down market sizing from regulatory mandate implementation timelines.
Sensitivity analysis tested forecast robustness across alternative reuse quota enforcement scenarios and resin price volatility assumptions. The analytical framework segmented volume and value outputs across product type, material grade, end-use industry, and distribution channel dimensions throughout the projection horizon. CAGRs derived from logistic curve fitting to refill station deployment trajectories in Germany, France, and the United Kingdom. Industry-specific inputs incorporated EFSA certification timeline distributions and VerpackG amendment compliance cost estimates.
Decision-makers should treat outputs as directional under binding EU reuse quota assumptions; material deviation in national implementation timelines would warrant model refresh. Forecasts reflect documented assumptions about regulatory enforcement intensity and pooling network expansion rates. Revision becomes warranted when EFSA certification backlog crosses thresholds that compress product launch windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Reusable Food Wrap Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market