
 Greenwrap Market | 2026-2036
Greenwrap Market Size, Share, and Industry Trends Forecast 2026-2036
Greenwrap Market Foresight
Market Context
E-commerce fulfillment channels are reshaping how protective wrapping reaches end users, with bulk-to-breakpack logistics demanding lighter, curbside-recyclable solutions. Sealed Air leverages its inflated protective systems expertise to serve automated packing lines. Huhtamaki Oyj anchors European foodservice wrap supply through molded fiber and paper-based formats. Amcor competes globally with renewable barrier coatings that extend shelf life without laminated plastic layers.
Technical Definition and Segment Structure
Greenwrap denotes flexible packaging materials engineered from renewable, recyclable, or biodegradable substrates—typically kraft paper, regenerated cellulose, or starch-based films between 20-80 gsm—designed to replace conventional polyethylene stretch film and bubble wrap in protective and aesthetic applications. Biodegradable wraps dominate value pools due to premium pricing tied to marine-degradability certifications, while recycled paper wraps occupy volume leadership in corrugated dunnage and void fill. Food packaging applications are the fastest-growing segment as cold-chain shippers adopt compostable films to meet retailer sustainability scorecards.
Regulatory Environment
EPA guidelines on sustainable materials management and the EU Packaging and Packaging Waste Directive shape product specifications and market access thresholds on both sides of the Atlantic. BIS certification requirements in India and FDA food-contact substance notifications in the United States add compliance layers that favor pre-qualified suppliers with established regulatory dossiers. Stakeholders must monitor how extended producer responsibility fee structures evolve, since these mechanisms will determine margin allocation between material innovators and downstream converters.
Market Dynamics
Extended producer responsibility fee structures are redistributing margin pools between cellulose substrate innovators and downstream converters, forcing capacity commitments before regulatory thresholds crystallize.
Growth Catalysts
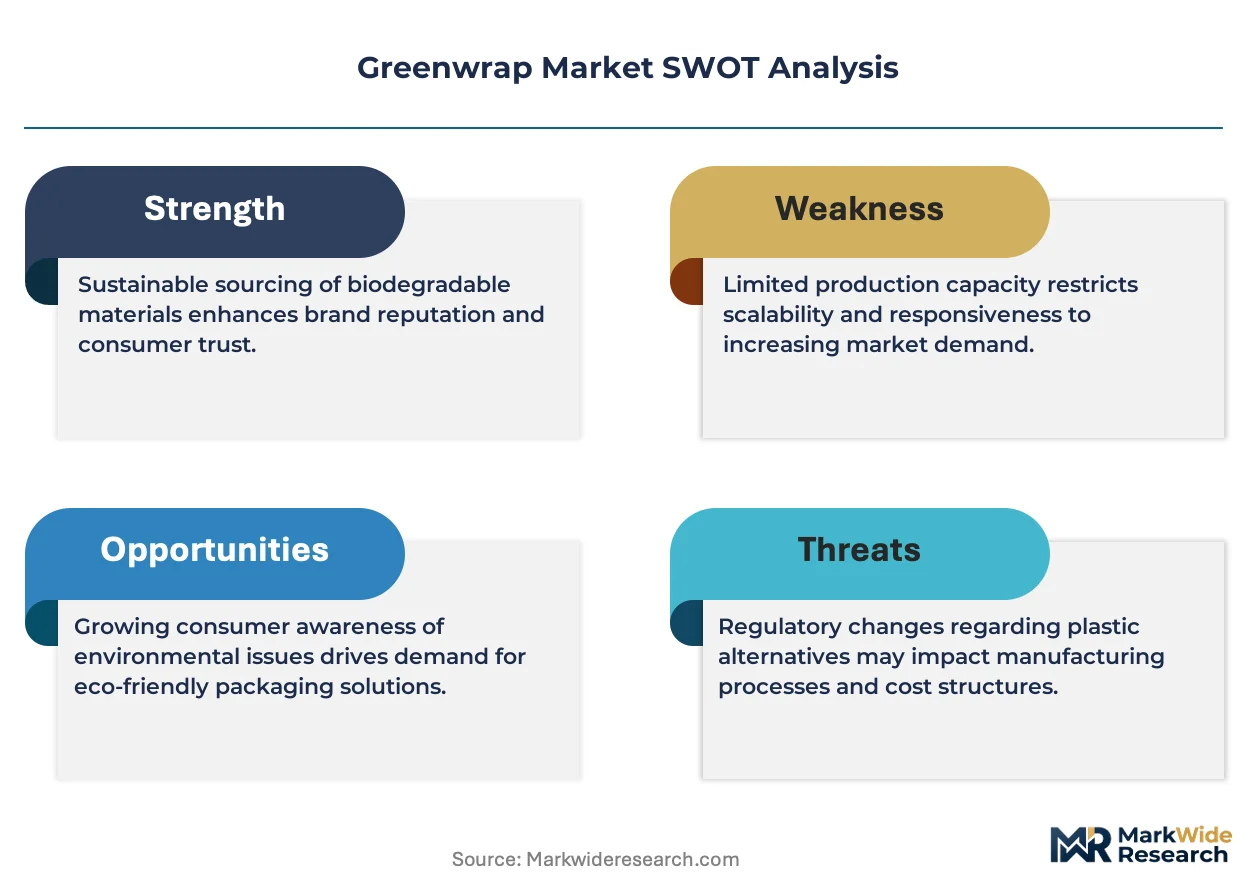
- EU Packaging and Packaging Waste Directive:Mandatory recyclability targets are compelling food retailers to replace laminated plastic films with compostable cellulose wraps ahead of 2030 compliance deadlines.
- Cold-chain logistics:Pharmaceutical shippers are adopting starch-based protective films to meet retailer sustainability scorecards without compromising temperature integrity.
- Kraft paper innovation:German packaging engineers have developed 40 gsm barrier-coated papers that match polyethylene puncture resistance at equivalent unit economics.
Market Restraints
- Pulp input volatility:Nordic softwood pulp contracts swing 15-30% quarterly, compressing converter margins on fixed-price annual supply agreements with retail chains.
- Barrier coating supply concentration:Bio-based moisture barriers rely on three European chemical specialists, creating single-source risk for shelf-life-critical food applications.
- Industrial composting infrastructure gaps:Home-compostable certifications exceed actual municipal processing capacity in most US metropolitan markets.
Strategic Opportunities
- Indian foodservice expansion:Quick-service restaurant chains under FSSAI plastic ban deadlines are sourcing molded fiber wraps from European converters unable to meet volume timelines.
- Automated packing line integration:E-commerce fulfillment centers are retrofitting legacy inflatable systems to handle paper-based void fill at 120 units per minute.
- REACH-compliant barrier coatings:ECHA authorization pathways for novel bio-polymers are accelerating 18-month certification cycles versus historical 36-month timelines.
Industry Challenges
- Material science talent scarcity:Formulation chemists with simultaneous expertise in paper substrate engineering and polymer barrier science command 40% salary premiums over packaging generalists.
- Multi-certification sequencing:FDA food-contact notifications, BIS quality marks, and marine-degradability validations require parallel track management with non-aligned documentation standards.
- Legacy equipment retrofit costs:Converters face $2-4 million per line to adapt heat-sealing infrastructure from polyethylene to cellulose film temperature profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenwrap Market |
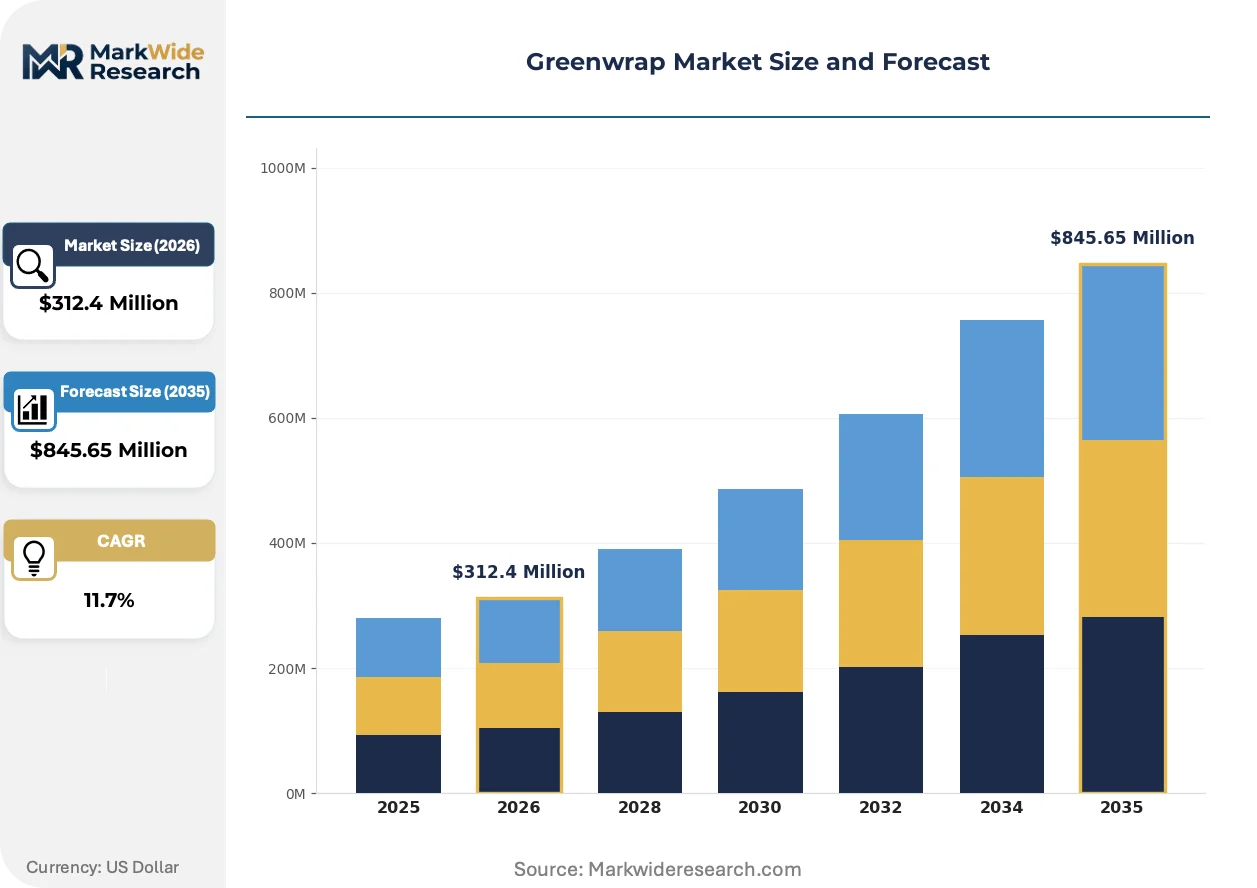
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Wraps, Compostable Films, Recycled Paper Wraps, Organic Materials Application: Food Packaging, Electronics Packaging, Gift Wrapping, Retail Packaging End User: Food Industry, Electronics Manufacturers, E-commerce, Retailers Material: Kraft Paper, Plant-Based Plastics, Cellulose, Starch-Based Materials |
| Companies Covered | Sealed Air, Ball Corporation, Amcor, Pactiv Evergreen, Huhtamaki Oyj, Smurfit Westrock, Tetra Pak, CCL Industries, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenwrap Market Shifts & Advancements
Digital substrate specification tools are compressing product development cycles from 18 months to 90 days, collapsing the traditional barrier between laboratory formulation and commercial scale-up.
Regenerated cellulose films with nano-fibrillated cellulose reinforcement are virtualizing the performance gap between petroleum-based stretch wrap and bio-based alternatives. Third-party logistics providers in the Netherlands are qualifying these substrates for automated pallet containment at throughput rates matching conventional films. The technology is virtualizing converter capital allocation decisions, diverting expansion budgets from polyethylene extrusion lines to cellulose regeneration capacity.
REACH authorization requirements for per- and polyfluoroalkyl substances are eliminating oil-based grease barriers from food-contact applications by 2026. European converters are reformulating with polysaccharide-lipid complexes that sacrifice some moisture resistance for regulatory certainty. Cold-chain dairy packaging in Germany and France is absorbing the highest compliance costs, passing through 8-12% price premiums to retail buyers.
Buyer consortiums at major retail chains are consolidating specification authority previously held by regional procurement teams. Centralized sustainability scorecards now mandate uniform greenwrap performance tiers across thousands of SKUs, displacing fragmented supplier relationships. This concentration is most visible in Nordic grocery retail, where three buying groups control 70% of fresh produce packaging decisions.
Greenwrap Market Segmentation
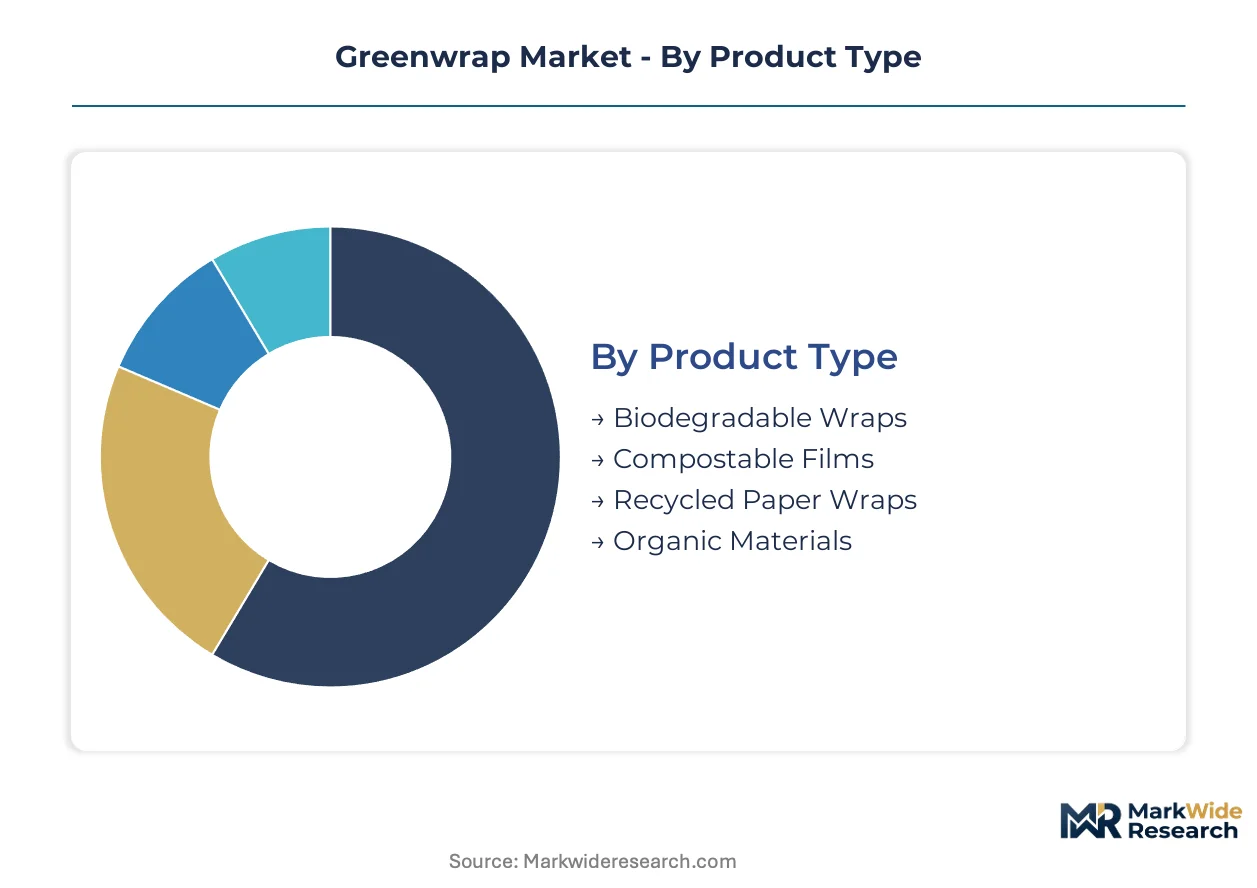
Greenwrap segmentation reveals how substrate chemistry, application requirements, and regulatory compliance intersect to create distinct value pools. Material composition determines performance ceilings and certification pathways, while end-use specifications dictate barrier properties and unit economics.
Product Type:
Use cases span protective dunnage, aesthetic presentation, and regulatory-compliant food contact, each demanding different degradation profiles and mechanical specifications.
- Biodegradable Wraps:Engineered from polylactic acid and polyhydroxyalkanoate blends, these materials achieve marine-degradability certifications that command price premiums in coastal logistics corridors. Cold-chain pharmaceutical shippers in the Netherlands specify these wraps to meet retailer sustainability scorecards without compromising temperature integrity during transit.
- Compostable Films:Starch-based substrates with polysaccharide-lipid barrier coatings serve food-contact applications where home-compostable certifications satisfy EU Packaging and Packaging Waste Directive targets. German dairy processors absorb compliance costs through 8-12% price premiums passed to retail buyers.
- Recycled Paper Wraps:Post-consumer kraft pulps occupy corrugated dunnage and void-fill volume leadership through cost parity with virgin alternatives.
- Organic Materials:Agricultural residue substrates including wheat straw and bagasse serve premium gift-wrapping segments seeking tactile differentiation.
The dominant share belongs to Recycled Paper Wraps, while Compostable Films is closing the gap fastest.
Application:
Application segmentation tracks how performance specifications diverge across temperature sensitivity, aesthetic requirements, and regulatory exposure.
- Food Packaging:Cold-chain integrity demands have driven starch-based protective film adoption as pharmaceutical and fresh-produce shippers replace laminated plastic layers. Nordic grocery retail buying groups now mandate uniform compostable wrap tiers across thousands of SKUs.
- Electronics Packaging:Anti-static cellulose wraps with nano-fibrillated reinforcement match polyethylene puncture resistance for automated packing lines at 120 units per minute throughput.
- Gift Wrapping:Aesthetic substrates prioritize printability and hand-feel over barrier performance, sourcing from European molded fiber specialists.
- Retail Packaging:Point-of-sale display wraps balance curb-side recyclability with brand visibility requirements.
Food Packaging holds the largest volume position, though Electronics Packaging is expanding most quickly through e-commerce fulfillment automation.
End User:
Procurement sophistication varies sharply across customer types, from centralized sustainability scorecards to fragmented specification authority.
- Food Industry:Quick-service restaurant chains under FSSAI plastic ban deadlines in India are sourcing molded fiber wraps from European converters unable to meet volume timelines, creating supply bottlenecks.
- Electronics Manufacturers:Original equipment manufacturers specify anti-static properties and clean-room compatibility for component protection during assembly and distribution.
- E-commerce:Fulfillment centers retrofit legacy inflatable systems to handle paper-based void fill, with automated packing line integration driving substrate qualification cycles.
- Retailers:Buyer consortiums at major chains have consolidated specification authority previously held by regional procurement teams.
Food Industry commands the deepest volume commitments, while E-commerce is gaining share fastest through logistics automation investments.
Material:
Material selection determines regulatory compliance pathways, barrier performance, and capital allocation across regeneration versus extrusion capacity.
- Kraft Paper:German packaging engineers have developed 40 gsm barrier-coated papers that match polyethylene puncture resistance at equivalent unit economics, diverting converter expansion budgets from polyethylene extrusion lines.
- Plant-Based Plastics:Polylactic acid and polyhydroxyalkanoate formulations serve applications requiring thermoformability and heat-seal compatibility with legacy equipment.
- Cellulose:Regenerated cellulose films with nano-fibrillated cellulose reinforcement are virtualizing the performance gap with petroleum-based stretch wrap, with third-party logistics providers in the Netherlands qualifying these for automated pallet containment.
- Starch-Based Materials:Potato and corn starch substrates provide home-compostable pathways where municipal processing infrastructure exists.
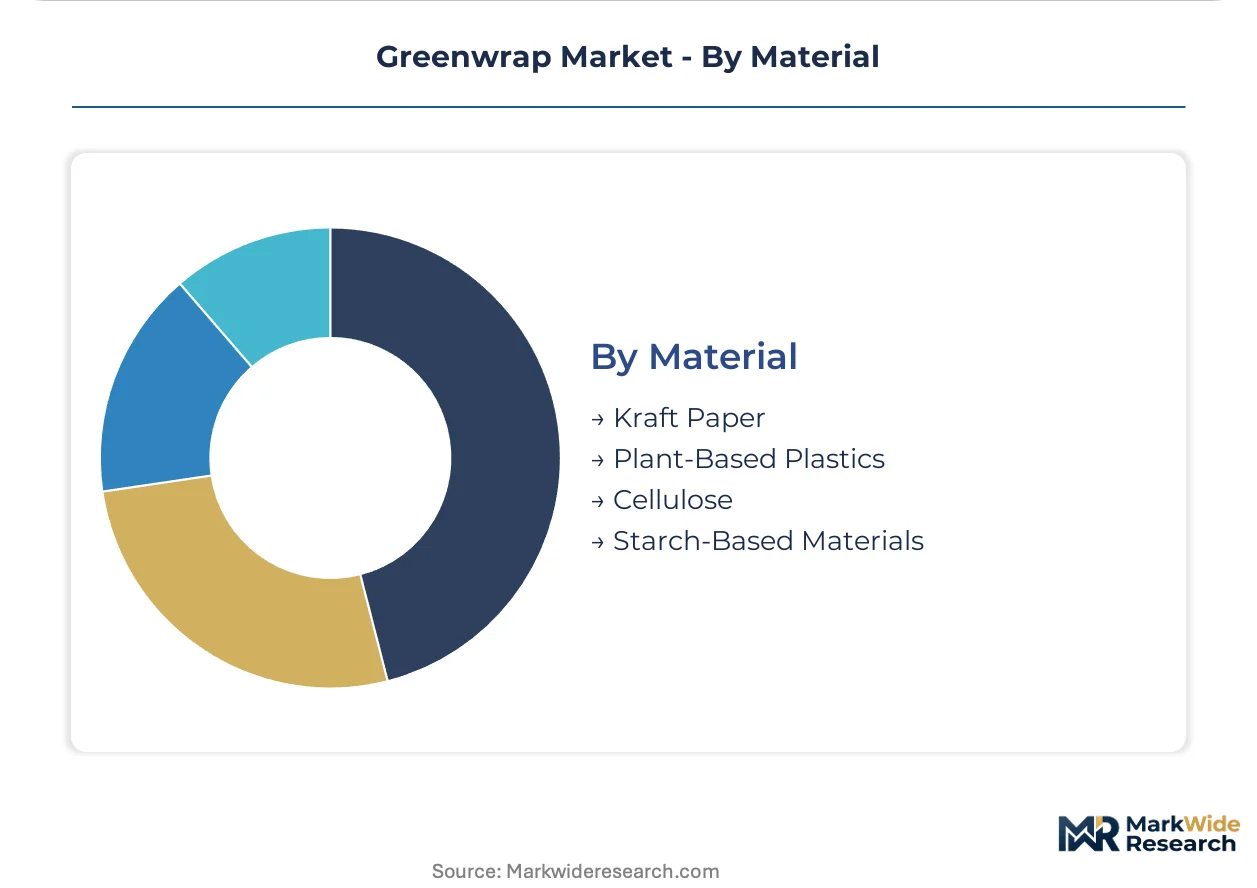
Kraft Paper retains the dominant position by volume, while Cellulose is climbing the fastest through regeneration capacity investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH authorization pathways anchor European demand, with ECHA compliance deadlines compressing material transition timelines. FDA food-contact notifications and EPA sustainable materials management guidelines shape North American specifications. BIS certification requirements in India and FSSAI plastic bans are accelerating procurement shifts across Asia-Pacific.
Germany
Quick-service restaurant chains under EU Packaging and Packaging Waste Directive deadlines are sourcing compostable cellulose wraps for cold-chain dairy applications. REACH-compliant barrier coatings from ECHA-authorized bio-polymer suppliers command 18-month certification cycles. Bavarian packaging engineers in the Munich-Stuttgart corridor have developed 40 gsm barrier-coated kraft papers matching polyethylene puncture resistance.
United States
E-commerce fulfillment centers are retrofitting automated packing lines to handle paper-based void fill at 120 units per minute throughput. EPA guidelines on sustainable materials management and FDA food-contact substance notifications favor pre-qualified suppliers with established regulatory dossiers. Industrial composting infrastructure gaps in most metropolitan markets exceed home-compostable certification capacity.
India
FSSAI plastic ban deadlines are driving quick-service restaurant chains to source molded fiber wraps from European converters unable to meet volume timelines. BIS certification requirements add compliance layers that favor established regulatory dossiers. Maharashtra and Gujarat industrial clusters are absorbing capacity expansion investments from domestic substrate converters.
Netherlands
Third-party logistics providers are qualifying regenerated cellulose films with nano-fibrillated reinforcement for automated pallet containment matching conventional film throughput. EU Green Deal implementation accelerates material transitions toward cellulose and starch-based substrates. Rotterdam-Amsterdam logistics corridors concentrate cold-chain pharmaceutical shipper demand for marine-degradable certifications.
France
Nordic grocery retail buying groups now mandate uniform compostable wrap tiers across thousands of SKUs, consolidating specification authority previously held by regional procurement teams. ECHA authorization pathways for novel bio-polymers are accelerating certification timelines. Paris-Lyon industrial basins absorb the highest compliance costs for cold-chain dairy packaging, passing 8-12% price premiums to retail buyers.
Greenwrap Market Competitive Landscape
Specialized substrate innovators and diversified packaging conglomerates split the market into distinct capability tiers. Concentration favors players with parallel regulatory dossiers across FDA, ECHA, and BIS jurisdictions. Three archetypes dominate: cellulose regeneration specialists with barrier-coating integration, molded fiber converters with foodservice scale, and multinational film suppliers with renewable coating portfolios. Competitive moves center on backward integration into pulp supply and technology licensing for automated line compatibility.
Among Nordic-based material science groups, Stora Enso exemplifies the cellulose regeneration archetype with integrated barrier-coating capabilities. Huhtamaki Oyj occupies a position within the molded fiber tier serving foodservice wrap demand. Sealed Air anchors the protective systems segment through inflated packaging expertise adapted for automated fulfillment lines. These three represent the strategic positioning spectrum from substrate innovation through downstream conversion.
| Leading Market Players |
|---|
| Sealed Air |
| Ball Corporation |
| Amcor |
| Pactiv Evergreen |
| Huhtamaki Oyj |
| Smurfit Westrock |
| Tetra Pak |
| CCL Industries |
| Stora Enso |
| Others |
Supply & Pricing Matrix
Overcapacity in Nordic softwood pulp regeneration is compressing converter margins and forcing tiered pricing discipline across fixed-price annual supply agreements with retail chains.
Pricing Analysis
Geographic price spreads of 15-30% separate German barrier-coated kraft from Indian molded fiber wraps. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale. Cost compression in standard-tier recycled paper is intensifying because pulp input volatility outpaces contract renegotiation cycles. Quick-service restaurant chains under FSSAI deadlines exhibit highest price sensitivity; cold-chain pharmaceutical shippers absorbing REACH compliance costs show lowest.
Supply Chain Analysis
Upstream Nordic softwood pulp contracts, Brazilian eucalyptus fiber, and Indian agricultural residue feedstock anchor raw material sourcing. Bio-based moisture barrier coatings draw from three European chemical specialists, creating single-source vulnerability for shelf-life-critical food applications. Distribution runs through converter-owned logistics networks serving automated packing line retrofits and direct retail chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greenwrap procurement is shifting toward subscription-style barrier-coating service agreements expanding faster than substrate hardware sales, as converters monetize certification maintenance and compliance updates.
For Market Incumbents: Harden pulp supply security through backward integration into Nordic regeneration capacity or long-term offtake with Brazilian eucalyptus plantations. Lock in ECHA-authorized bio-polymer supply before REACH authorization pathways compress further. Defend against specialty chemical single-source risk by dual-sourcing polysaccharide-lipid barrier formulations.
For New Entrants and Emerging Players: Build out molded fiber capacity in Maharashtra and Gujarat industrial clusters to capture Indian quick-service restaurant demand European converters cannot fulfill. Target e-commerce fulfillment center automation retrofit segments where paper-based void fill throughput requirements create qualification bottlenecks. Lead with automated packing line compatibility certifications rather than substrate performance alone.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cellulose regeneration specialists with integrated barrier-coating capabilities and multi-jurisdiction regulatory dossiers. Long-term viability favors archetypes with captive pulp supply and ECHA pre-authorization status. Watch for inflection when buyer consortiums at major retail chains consolidate specification authority previously held by regional procurement teams.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic softwood and Brazilian eucalyptus sourcing secures margin control against quarterly contract volatility. |
| REACH-Compliant Barrier Coating Certification | ECHA authorization pathways compress from historical timelines, rewarding pre-qualified bio-polymer suppliers. |
| Automated Packing Line Compatibility | E-commerce fulfillment centers at 120 units per minute throughput demand substrate-qualification partnerships. |
| Multi-Jurisdiction Regulatory Dossier Expansion | FDA food-contact notifications, BIS quality marks, and marine-degradability validations unlock geographic expansion. |
| Service-Attach Compliance Subscription | Retailer sustainability scorecard maintenance and certification update monetization outpaces hardware growth. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across substrate converters, barrier-coating formulators, retail chain procurement directors, and cold-chain logistics engineers. Primary interview insights triangulated against secondary sources including ECHA authorization databases, FSSAI regulatory filings, EU Packaging and Packaging Waste Directive implementation trackers, and Nordic pulp trade association capacity reports. Bottom-up volume modeling and top-down value reconciliation validated segment-level outputs.
Calibration anchored historical capacity utilization and pricing realization data against forward-projected regulatory deadline impacts across the analysis window. Segmentation dimensions modeled include material composition, application temperature sensitivity, end-user procurement sophistication, and regional compliance framework cluster. CAGRs derived from substrate adoption curves weighted by retailer mandate timelines and industrial composting infrastructure development trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cellulose regeneration specialists with captive pulp supply would shift outcomes beyond modeled ranges. Cross-checking against EU extended producer responsibility fee structure announcements and municipal composting capacity buildout timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Reusable Food Wrap Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Resealable Cans Market