
 North America and Europe Reusable Corrugated Boxes Market | 2026-2036
North America and Europe Reusable Corrugated Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Reusable Corrugated Boxes Market Analytics
E-commerce fulfillment is recalibrating box utilization patterns across both regions. DS Smith leverages its closed-loop recycling infrastructure to anchor European grocery and fast-moving consumer goods accounts. International Paper sustains manufacturing scale across the southeastern United States, while Orbis Corporation specializes in returnable plastic corrugated hybrids for automotive part sequencing.
Reusable corrugated boxes are multi-trip containers fabricated from fluted fiberboard or polymer-composite substrates, engineered for dimensional stability across fifty to one hundred use cycles through reinforced corners and interlocking closures. Their primary purpose is to eliminate single-use shipping material in closed-loop supply chains. Double-wall and foldable product types command expanding share in electronics and automotive applications where cube utilization and return logistics dominate total cost equations. Recycled fiber material grades attract investment as European sorting infrastructure and North American old corrugated container recovery rates tighten furnish quality standards.
The EPA's sustainable materials management framework and the EU Packaging and Packaging Waste Regulation shape design-for-recycling mandates and recycled content thresholds across both markets. Germany's national packaging regulator enforces strict return and recovery quotas that favor reusable formats in business-to-business channels. Stakeholders must monitor divergence between state-level extended producer responsibility enactments in the United States and harmonized EU rules when configuring cross-Atlantic fleet deployments and material certification strategies.
Market Dynamics
E-commerce fulfillment networks are compressing return logistics cycles across North America and Europe, forcing packaging specifications toward foldable formats that maximize cube density in reverse freight. The EU Packaging and Packaging Waste Regulation and emerging state-level extended producer responsibility frameworks in the United States are mandating material recovery investments that favor multi-trip containers over single-use alternatives.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:The regulation mandates strict recycled content thresholds and design-for-recycling standards that direct capital toward reusable fiberboard formats in business-to-business channels.
- Automotive part sequencing:Just-in-time assembly plants in Germany's supplier corridors and the Upper Midwest distribution belt are standardizing returnable container fleets to reduce packaging waste penalties and line-side storage requirements.
- Double-wall fiberboard engineering:Reinforced fluting structures now withstand fifty to one hundred use cycles without dimensional degradation, meeting electronics and pharmaceutical cold-chain integrity demands.
Market Restraints
- Old corrugated container furnish volatility:North American OCC recovery rate fluctuations and European sorting infrastructure bottlenecks create input cost instability for recycled fiber grades.
- Return logistics infrastructure gaps:Rural distribution nodes in the Upper Midwest and Eastern Europe lack consolidated backhaul networks, inflating per-trip container recovery costs.
- Polymer-composite substrate competition:Returnable plastic corrugated hybrids from specialized manufacturers threaten fiberboard share in high-moisture automotive and food processing environments.
Strategic Opportunities
- Poland and Czech Republic manufacturing clusters:Underpenetrated automotive supplier corridors in Central Europe present fleet deployment opportunities as OEMs relocate component sourcing from Western Europe.
- Pharmaceutical cold-chain validation:Temperature-controlled reusable boxes with integrated tracking sensors are capturing share from expanded polystyrene shippers in vaccine and biologics distribution.
- California and New York state EPR enactments:Emerging extended producer responsibility frameworks are creating compliance-driven demand for certified reusable formats in consumer goods fulfillment.
Industry Challenges
- Interoperability certification delays:Divergent state-level EPR reporting requirements in the United States and national packaging regulator quotas in Germany complicate cross-Atlantic fleet standardization.
- RFID and sensor integration complexity:Embedding track-and-trace electronics into fiberboard substrates without compromising crush resistance requires materials engineering capabilities scarce among mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Reusable Corrugated Boxes Market |
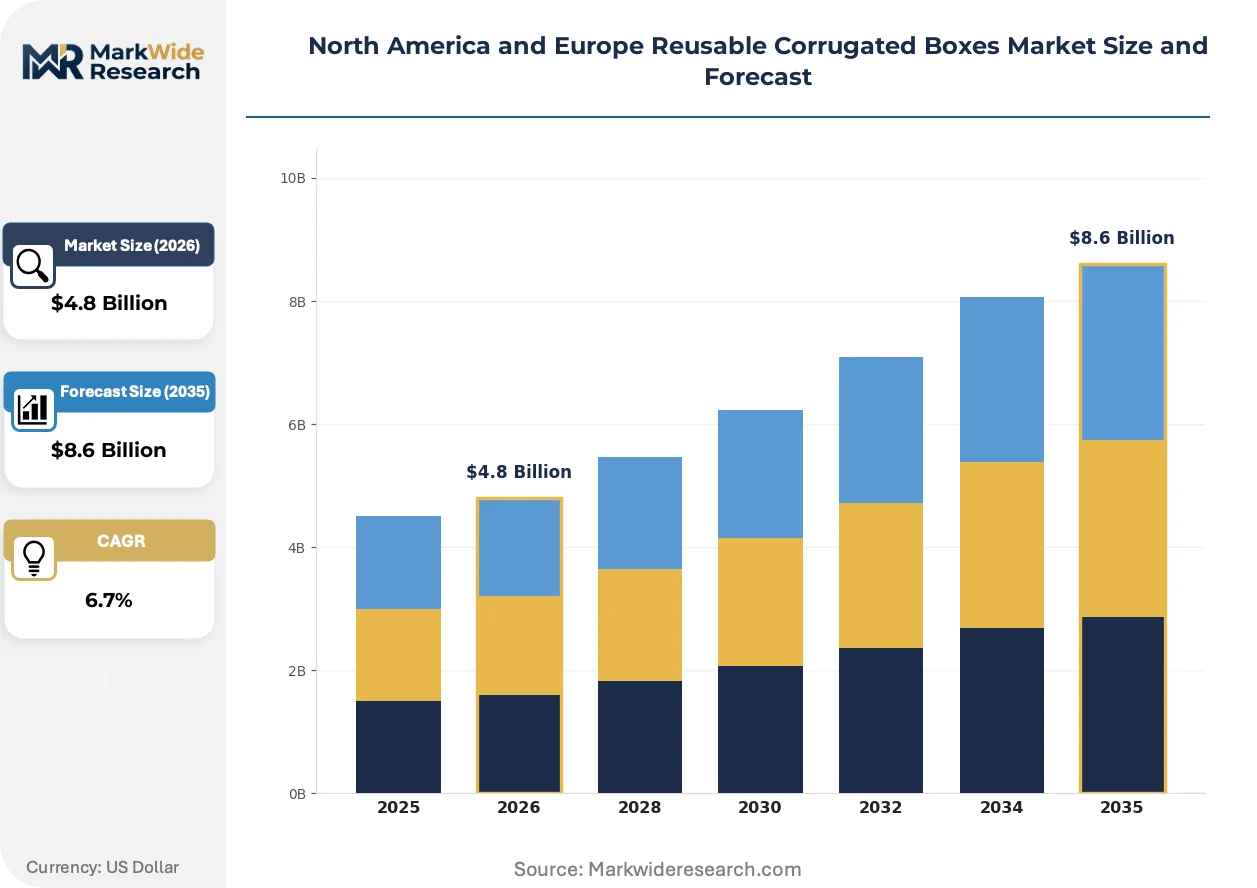
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall, Double-Wall, Triple-Wall, Foldable Application: Retail, Automotive, Electronics, Food & Beverage Material: Cardboard, Paperboard, Recycled Fiber, Plastic End User: Manufacturers, Wholesalers, Distributors, E-commerce |
| Companies Covered | Smurfit Westrock, International Paper, DS Smith, Packaging Corporation of America, Mondi, WestRock Company, Stora Enso, VPK Group NV, Orbis Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Reusable Corrugated Boxes Market Evolving Landscape
Active RFID integration and polymer-fiber hybrid substrates are compressing the technical gap between single-use shipping containers and durable returnable packaging. These innovations are redefining total cost of ownership calculations across automotive, electronics, and grocery fulfillment networks.
Polymer-composite corrugated substrates with embedded RFID tags are electrifying traceability standards in closed-loop supply chains. Tier-one automotive suppliers in Germany and Illinois are mandating real-time location tracking for component sequencing totes. The technology is compressing inventory reconciliation cycles from days to hours while reducing container loss rates.
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation are accelerating substitution of wax-coated fiberboard with recyclable water-resistant treatments. European grocery and fast-moving consumer goods accounts now specify fluorine-free oil and grease resistance for produce and meat packaging. German national packaging regulator enforcement is driving converters to reformulate coatings ahead of 2025 compliance deadlines.
Third-party logistics providers are consolidating container pooling services across the Upper Midwest and Benelux distribution corridors. Amazon and regional grocery cooperatives are outsourcing fleet management to specialized pooling operators rather than maintaining captive box inventories. The Netherlands and Wisconsin are emerging as hub locations where pooling density justifies dedicated reverse logistics infrastructure investment.
North America and Europe Reusable Corrugated Boxes Market Segmentation
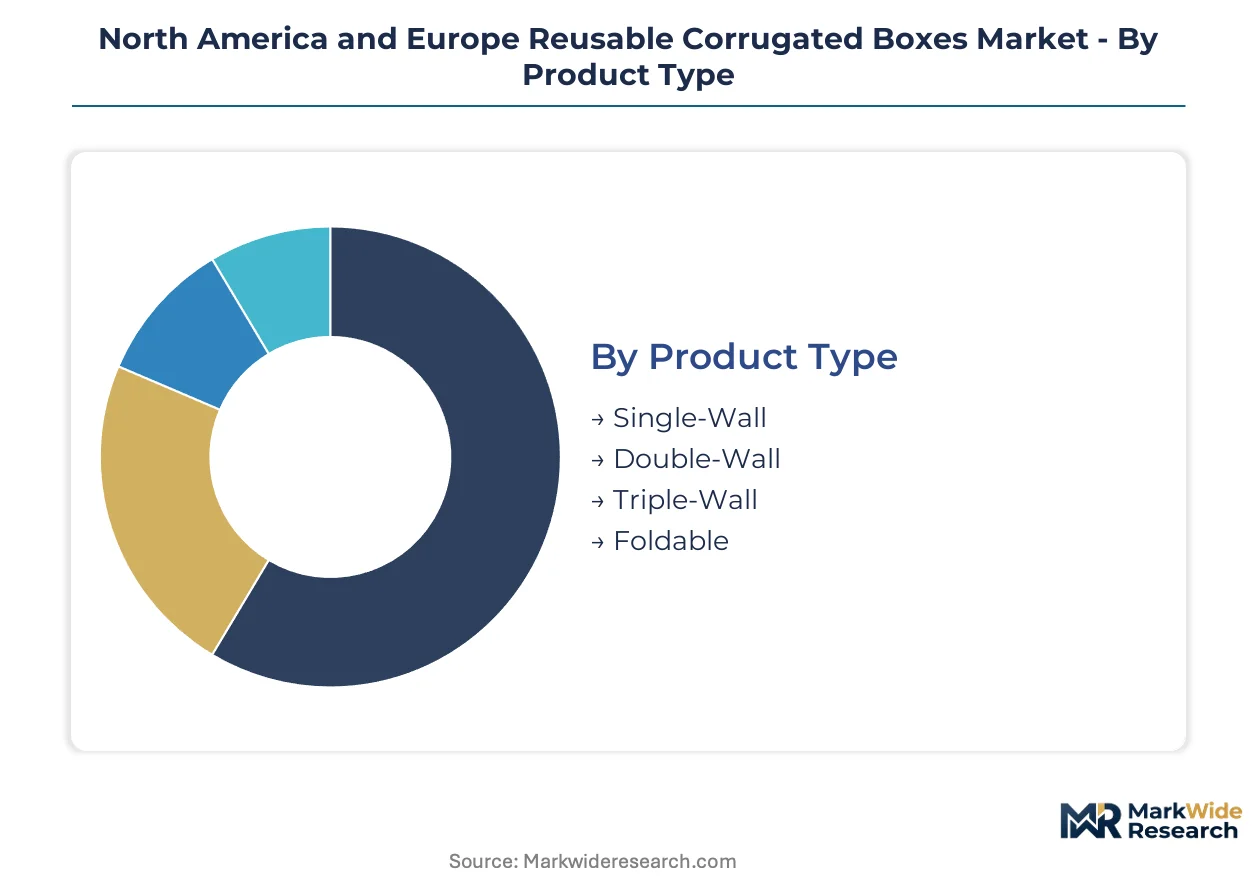
Reusable corrugated box specifications diverge sharply between high-velocity e-commerce channels and precision automotive sequencing. Material selection and wall construction directly determine cycle life, cube utilization, and compliance with EU Packaging and Packaging Waste Regulation thresholds across North American and European supply chains.
Product Type:
Double-wall and foldable formats command premium positioning against single-wall commodity alternatives, with volume concentration shifting toward automotive and electronics fulfillment networks.
- Double-Wall:Reinforced fluting structures withstand fifty to one hundred use cycles without dimensional degradation. Demand concentrates in Germany's automotive supplier corridors where just-in-time assembly plants mandate container integrity for component sequencing.
- Foldable:Collapsible designs maximize cube density in reverse freight operations. E-commerce fulfillment networks across the Upper Midwest distribution belt are standardizing these formats to compress return logistics cycles and reduce per-trip recovery costs.
- Single-Wall:Lightweight construction suits short-loop grocery and fast-moving consumer goods applications with lower durability requirements.
- Triple-Wall:Heavy-duty specification serves industrial equipment and export packaging where maximum stacking strength outweighs return freight efficiency.
Mature deployment sits with Single-Wall formats in established grocery channels. Newer deployment is concentrated in Foldable configurations as e-commerce reverse logistics infrastructure expands.
Application:
Automotive and electronics applications drive engineering investment, while retail and food processing segments lag in standardized reusable fleet adoption.
- Automotive:Returnable container fleets eliminate packaging waste penalties and reduce line-side storage requirements. OEM component sourcing shifts into Poland and Czech Republic manufacturing clusters are expanding addressable fleet deployment opportunities.
- Electronics:Cold-chain integrity demands and anti-static specifications favor polymer-fiber hybrid substrates with embedded RFID tracking. Tier-one suppliers in Illinois mandate real-time location tracking for high-value component totes.
- Retail:Third-party logistics pooling services are consolidating container management for regional grocery cooperatives across Benelux distribution corridors.
- Food & Beverage:REACH substance restrictions and fluorine-free coating mandates are accelerating substitution of wax-treated fiberboard with recyclable water-resistant treatments for produce and meat packaging.
Volume leadership belongs to Automotive sequencing applications. Steepest expansion trajectory is occurring in Electronics cold-chain validation as temperature-controlled reusable boxes capture share from expanded polystyrene shippers.
Material:
Recycled fiber grades attract capital investment as furnish quality standards tighten, while plastic corrugated hybrids threaten fiberboard share in moisture-exposed environments.
- Recycled Fiber:European sorting infrastructure investments and North American OCC recovery rate improvements are stabilizing input quality for multi-trip container production. EU Packaging and Packaging Waste Regulation recycled content thresholds direct converter capital toward this grade.
- Plastic:Polymer-composite substrates withstand high-moisture automotive and food processing environments where fiberboard degrades. Returnable plastic corrugated hybrids from specialized manufacturers are gaining share in sequencing totes and pharmaceutical distribution.
- Cardboard:Virgin fiber construction serves premium branding applications and pharmaceutical cold-chain where batch consistency and traceability documentation are mandatory.
- Paperboard:Lightweight specification dominates single-trip retail display and promotional packaging with limited reuse potential.
Regulatory compliance investment centers on Recycled Fiber reformulation. Premium performance requirements are elevating Plastic substrate specification in automotive and pharmaceutical verticals.
End User:
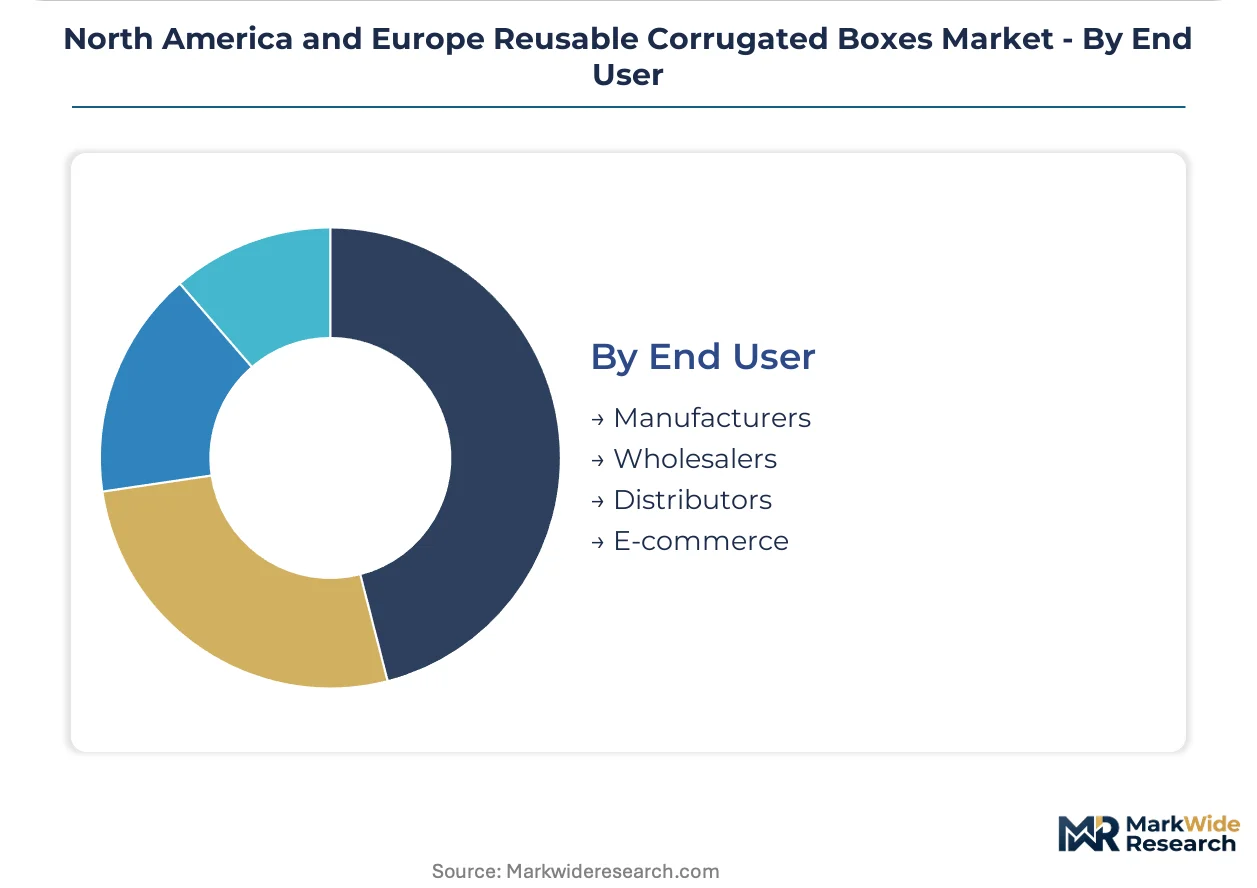
E-commerce platforms and manufacturers deploy divergent fleet strategies, with wholesalers and distributors occupying intermediate positions in container pooling networks.
- E-commerce:Amazon and regional grocery cooperatives are outsourcing fleet management to specialized pooling operators rather than maintaining captive box inventories. California and New York state EPR enactments are creating compliance-driven demand for certified reusable formats.
- Manufacturers:Captive container fleets dominate automotive and electronics production facilities with closed-loop supply chain control. Germany's national packaging regulator enforces strict return and recovery quotas that favor reusable formats in business-to-business channels.
- Distributors:Consolidated backhaul networks in the Netherlands and Wisconsin are emerging as hub locations where pooling density justifies dedicated reverse logistics infrastructure investment.
- Wholesalers:Intermediate positioning in supply chains limits direct fleet ownership, with container access typically arranged through third-party pooling agreements.
Standardized fleet ownership concentrates with Manufacturers in regulated European corridors. Outsourced pooling adoption is expanding fastest among E-commerce platforms seeking capital efficiency in volatile demand environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux distribution corridors and Germany's automotive supplier zones concentrate reusable corrugated box deployment through EU Green Deal tax incentives and circular economy investment credits.
Germany
Just-in-time assembly plants in Bavaria and Baden-Württemberg mandate container integrity for component sequencing. The national packaging regulator enforces strict return and recovery quotas that favor reusable formats in business-to-business channels. Stuttgart and Munich automotive clusters standardize returnable container fleets to reduce packaging waste penalties and line-side storage requirements.
United States
E-commerce fulfillment networks across Illinois and Wisconsin compress return logistics cycles toward foldable formats. Emerging state-level extended producer responsibility frameworks in California and New York create compliance-driven demand for certified reusable formats. The Upper Midwest distribution belt spanning Wisconsin and Illinois anchors third-party logistics pooling infrastructure investment.
Netherlands
Third-party logistics providers consolidate container pooling services across Rotterdam and Amsterdam distribution hubs. EU Packaging and Packaging Waste Regulation recycled content thresholds direct converter capital toward multi-trip container production. The Randstad region emerges as a hub location where pooling density justifies dedicated reverse logistics infrastructure.
Poland
OEM component sourcing shifts into Polish manufacturing clusters expand addressable fleet deployment opportunities. EU Green Deal circular economy funding supports packaging reuse infrastructure development. Warsaw and Krakow automotive supplier corridors present underpenetrated fleet deployment opportunities as production relocates from Western Europe.
United Kingdom
DS Smith leverages closed-loop recycling infrastructure to anchor grocery and fast-moving consumer goods accounts. Post-BREXIT regulatory divergence from EU packaging rules complicates cross-border fleet standardization. Midlands distribution centers and London fulfillment networks drive specification toward foldable formats that maximize cube density in reverse freight.
North America and Europe Reusable Corrugated Boxes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fiberboard converters dominating European grocery channels and polymer-composite fabricators capturing automotive sequencing accounts. The vendor base organizes around three archetypes: integrated paperboard producers with captive recycling infrastructure, specialized returnable packaging engineers, and third-party logistics pooling operators. M&A activity concentrates on recycling asset consolidation, while capacity expansion targets Central European automotive corridors.
Among integrated paperboard producers, Smurfit Westrock and International Paper exemplify scale-driven archetypes with closed-loop recycling infrastructure. DS Smith occupies a position within the European grocery and fast-moving consumer goods specialization tier. Orbis Corporation represents the polymer-composite hybrid segment serving automotive part sequencing requirements.
| Leading Market Players |
|---|
| Smurfit Westrock |
| International Paper |
| DS Smith |
| Packaging Corporation of America |
| Mondi |
| WestRock Company |
| Stora Enso |
| VPK Group NV |
| Orbis Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EU Packaging and Packaging Waste Regulation-compliant reusable formats and uncertified commodity alternatives manifests in both procurement premiums and supply chain consolidation patterns across Germany, the United States, and the Netherlands. Tier-one automotive suppliers and pooled e-commerce fleets command price premiums for validated multi-trip containers while spot-market buyers absorb OCC furnish volatility in single-wall segments.
Pricing Analysis
Lead-time compression commands measurable premiums in the German automotive corridor, where just-in-time assembly plants pay elevated rates for expedited double-wall container delivery against standard pooled fleet pricing. Three-tier pricing structure across premium certified, standard validated, and economy spot-market levels reflects EU recycled content thresholds and state-level EPR compliance burdens. Price differentiation centers on RFID-embedded traceability and fluorine-free coating certification. Cost compression in economy single-wall grades intensifies as North American OCC recovery fluctuations destabilize input costs. E-commerce pooling operators exhibit lowest price sensitivity due to capital-efficiency outsourcing models, while independent Midwest distributors face acute margin pressure from rural backhaul infrastructure gaps.
Supply Chain Analysis
Regional distribution centers in Wisconsin, Illinois, and the Netherlands anchor hub-and-spoke patterns for container pooling operators serving Amazon and grocery cooperative accounts. Manufacturing concentration rests on Germany, Poland, and the United States, with Polish automotive supplier corridors drawing fleet deployment investment from Western European relocation. Raw material sourcing draws from North American old corrugated container recovery streams, European sorting infrastructure outputs, and polymer-composite resin feedstocks. Single-source vulnerability concentrates in specialized RFID-embedded substrate fabrication capabilities scarce among mid-tier converters. Distribution runs through third-party logistics pooling networks rather than captive manufacturer inventories across Benelux and Upper Midwest corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America and Europe Reusable Corrugated Boxes Market functions as a cost-of-compliance arena where the EU Packaging and Packaging Waste Regulation erects barrier-to-entry moats favoring incumbents with validated certification infrastructure and closed-loop recycling assets.
For Market Incumbents:Hedge against polymer-composite substitution in high-moisture automotive sequencing by deepening captive supply of recyclable water-resistant fiberboard treatments ahead of REACH enforcement deadlines. Fortify position through backward integration into European sorting infrastructure and OCC recovery assets that stabilize furnish quality for multi-trip container production. Prioritize RFID-embedded substrate R&D partnerships to close the traceability gap with Orbis Corporation's hybrid offerings.
For New Entrants and Emerging Players:Enter via Poland and Czech Republic automotive supplier corridors where OEM component sourcing relocation has outpaced established fleet deployment. Target pharmaceutical cold-chain validation as the most penetrable vertical, where temperature-controlled reusable boxes with integrated sensors displace expanded polystyrene shippers lacking regulatory compliance pathways. Pursue white-label manufacturing partnerships with third-party logistics pooling operators in the Netherlands rather than direct fleet ownership models.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized returnable packaging engineers possessing EU certification infrastructure and automotive sequencing relationships, given accelerating EPR enactments in California and New York that will replicate European compliance burdens. Long-term viability favors acquisition targets with established pooling density in Wisconsin or Benelux hub locations where reverse logistics infrastructure investment has achieved critical mass. Monitor RFID integration yield rates at fiberboard converters as the inflection signal for materials engineering capability scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Infrastructure Acquisition | Captive OCC recovery assets in Germany and the Upper Midwest stabilize input costs for multi-trip production. |
| RFID-Embedded Substrate Development | Real-time tracking capabilities meet Tier 1 automotive supplier mandates in Stuttgart and Illinois corridors. |
| Central European Manufacturing Expansion | Poland and Czech Republic automotive clusters offer underpenetrated fleet deployment as OEM sourcing relocates. |
| Pharmaceutical Cold-Chain Certification | Temperature validation protocols capture share from expanded polystyrene in vaccine and biologics distribution. |
| Third-Party Pooling Partnership | Outsourced fleet management models reduce capital intensity for e-commerce platforms in volatile demand environments. |
Research Methodology
Independent corroboration across converter technical directors, third-party logistics pooling operators, automotive Tier 1 procurement leads, and EU national packaging regulators underwrites the qualitative findings in this study. Primary interviews with plant managers at Wisconsin and German manufacturing facilities, supply chain planners at e-commerce fulfillment networks, and regulatory affairs specialists tracking EPR enactments combined with secondary validation from EPA sustainable materials management disclosures, EU Packaging and Packaging Waste Regulation implementation documents, and North American OCC recovery rate databases. Bottom-up container fleet deployment estimates and top-down market size triangulation anchored the quantitative framework.
Rate-of-change decomposition across the projection horizon segmented volume and value trajectories by product type (double-wall, foldable, single-wall, triple-wall), application (automotive, electronics, retail, food and beverage), material substrate (recycled fiber, plastic corrugated, virgin cardboard), and end-user archetype (e-commerce platforms, manufacturers, distributors, wholesalers). CAGRs derived from regression analysis against automotive production forecasts, e-commerce fulfillment network expansion plans, and regulatory compliance timeline assumptions. Industry-specific inputs included just-in-time assembly plant container turnover rates and pharmaceutical cold-chain validation protocol adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt OCC furnish price spikes, accelerated state-level EPR divergence in the United States, or polymer-composite substrate breakthroughs in moisture-exposed environments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Global Recyclable Packaging Market