
 Resealable Cans Market | 2026-2036
Resealable Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Resealable Cans Market Outlook
Germany is tilting toward expanded resealable can production capacity as brand owners seek localized supply chains. Ball Corporation leverages its European beverage packaging infrastructure to sustain high-volume aluminum output. Crown Holdings anchors its position through deep specialization in premium beverage closures. Silgan Containers competes aggressively across multiple European markets with integrated metal-forming operations.
Resealable cans are cylindrical metal or hybrid containers featuring integrated mechanical closures that permit repeated opening and resealing without compromising internal pressure or product integrity, typically manufactured through drawn-and-ironed aluminum or steel processes with precision-molded polymer or metal lid mechanisms. Their primary commercial purpose is to extend consumption occasions for carbonated beverages, ready-to-drink coffee, and functional drinks while eliminating the need for separate transfer vessels. Aluminum dominates current production volumes due to its infinite recyclability and lightweight properties, while steel variants occupy niche positions in industrial and household applications where puncture resistance outweighs weight considerations. The Food & Beverage end-user segment generates the dominant margin pool, though Personal Care applications in aerosol-adjacent formats are expanding fastest among emerging categories.
REACH compliance through ECHA governs chemical safety in lid polymers and interior coatings, while the EU Green Deal's packaging waste targets directly accelerate substitution from single-use plastic bottles toward resealable metal formats. CE marking requirements under the EU Packaging and Packaging Waste Directive shape minimum recyclability thresholds that aluminum resealable cans routinely exceed. Stakeholders must monitor evolving Extended Producer Responsibility fee structures across EU member states to anticipate margin compression or competitive advantage from circular-economy-certified supply chains.
Market Dynamics
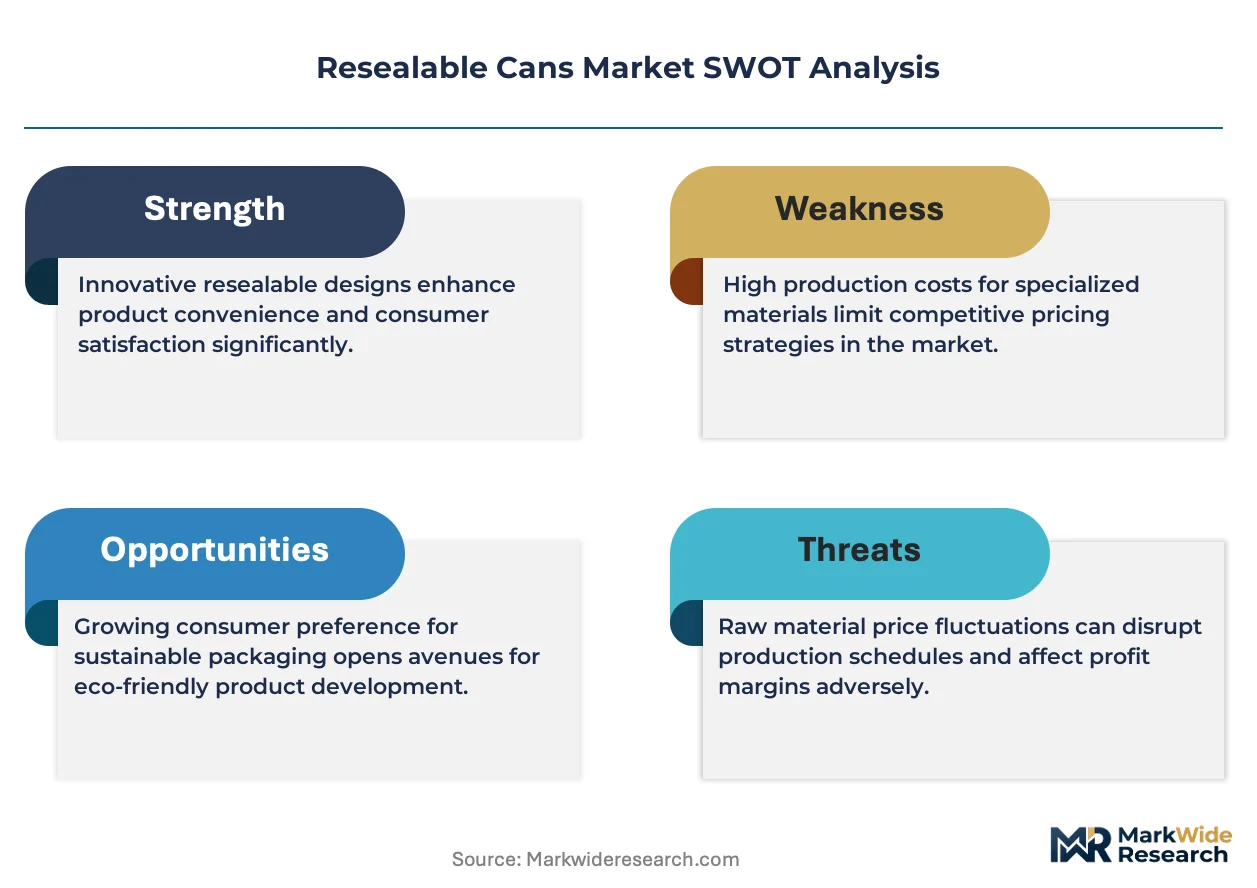
The EU Single-Use Plastics Directive is redirecting procurement toward aluminum resealable formats as beverage brands eliminate non-recyclable closures. This regulatory compression is forcing closure-system redesigns and localized supply chain investments across European manufacturing networks.
Growth Catalysts
- REACH compliance through ECHA:Chemical safety mandates for lid polymers accelerate substitution toward metal closure systems that bypass complex polymer registration requirements.
- On-the-go consumption patterns:Beverage brands are expanding resealable aluminum formats for mobile consumption occasions in Germany and the Netherlands.
- EU Green Deal packaging targets:Mandatory recyclability thresholds under the EU Packaging and Packaging Waste Directive position aluminum resealable cans above competing formats.
Market Restraints
- Aluminum input cost volatility:London Metal Exchange pricing fluctuations compress margins for drawn-and-ironed can body production.
- Closure mechanism supply concentration:Precision-molded polymer lid production clusters in specialized German and Austrian tooling facilities.
- Steel substitution in puncture-critical applications:Industrial aerosol-adjacent formats retain steel variants where damage resistance outweighs lightweighting benefits.
Strategic Opportunities
- Extended Producer Responsibility fee arbitrage:Circular-economy-certified supply chains in Germany command preferential EPR rates versus conventional packaging.
- Personal Care aerosol expansion:Functional spray formats for cosmetics and household products represent underpenetrated resealable metal applications.
- Ready-to-drink coffee segment growth:Premium beverage brands are adopting resealable cans for ambient coffee distribution in Dutch retail channels.
Industry Challenges
- Polymer-coating compliance timelines:REACH registration deadlines for interior can coatings compress product recertification windows.
- Precision tooling skill scarcity:Drawn-and-ironed aluminum forming and closure integration require specialized mechanical engineering expertise concentrated in aging European workforces.
- Legacy filling line retrofit costs:Existing beverage production infrastructure requires capital-intensive modification to handle resealable closure formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resealable Cans Market |
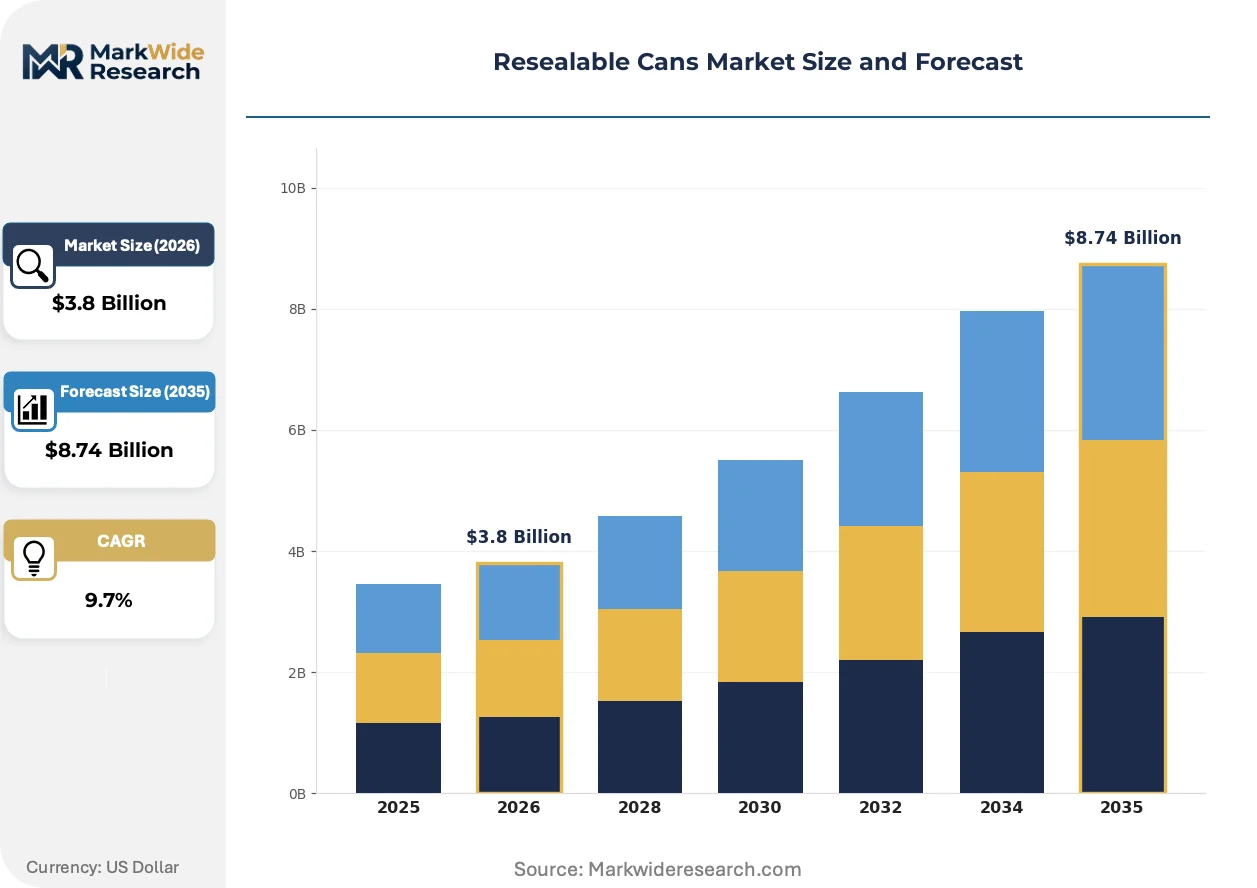
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Plastic, Biodegradable End User: Food & Beverage, Personal Care, Household Products, Automotive Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Wilkinson Containers Ltd, Allstate Can Corporation, Ball Corporation, Can2close GmbH, Silgan Containers, Ardagh Group, Xolution GmbH, Orora, Crown Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resealable Cans Market Strategic Shifts
Closure-system engineering is converging with sustainability certification requirements as brands compete on circular-economy credentials. Three developments are restructuring competitive positioning across European supply chains.
Integrated mechanical closure systems with precision-molded metal lid mechanisms are rendering obsolete separate transfer vessels for carbonated beverage consumption. Premium beverage brands in Germany are adopting these systems at accelerated pace. The technology is compressing single-use plastic bottle demand in on-the-go consumption channels.
CE marking requirements under the EU Packaging and Packaging Waste Directive are mandating minimum recyclability thresholds that aluminum formats routinely exceed. Industrial consequence includes accelerated substitution from polymer closures toward all-metal systems. The Food & Beverage segment is responding with supply chain reconfigurations toward EPR-optimized circular certification.
Consumption-pattern fragmentation is splitting demand between immediate consumption and extended-use occasions. Traditional single-serve cans face displacement from resealable formats in Dutch and German retail channels. This bifurcation is most visible in functional drink and ready-to-drink coffee verticals where portion control drives purchasing decisions.
Resealable Cans Market Segmentation
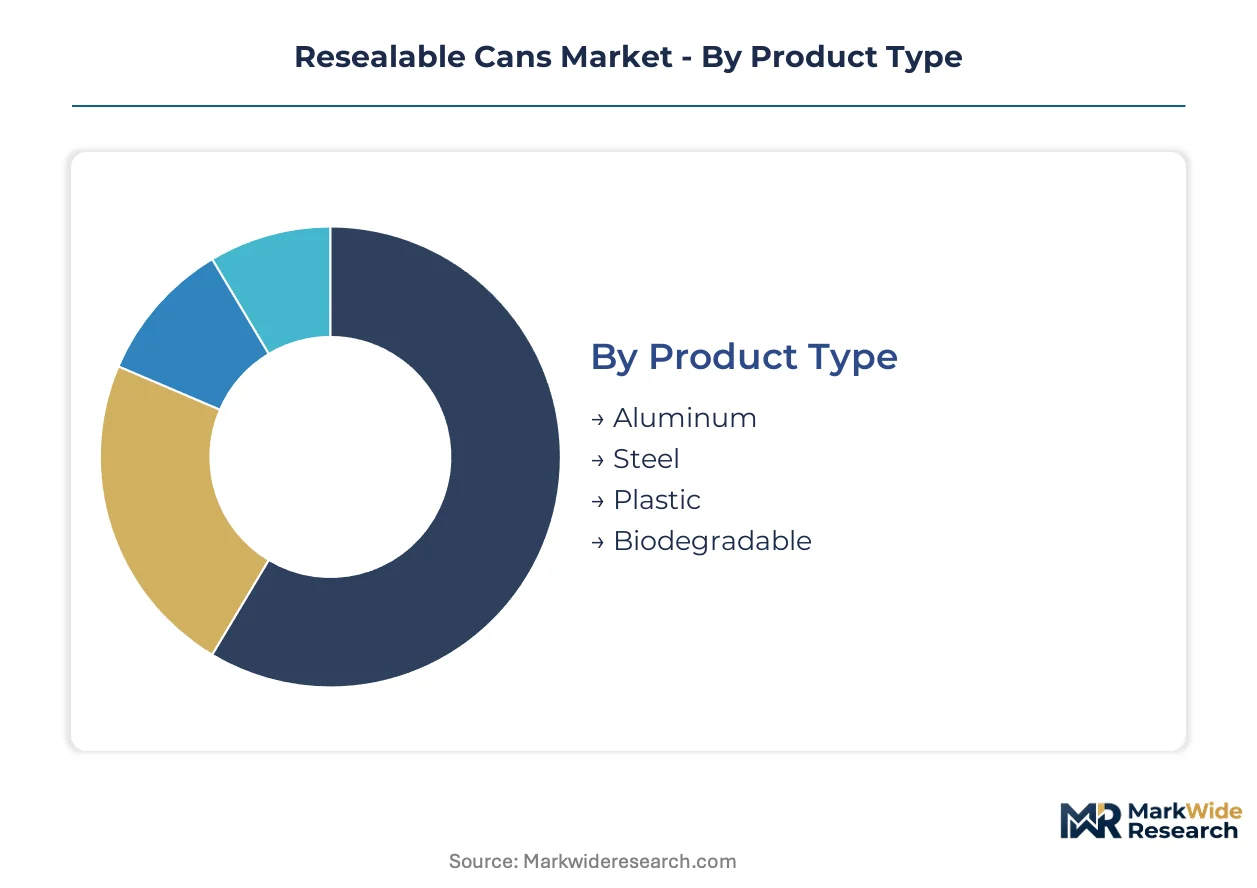
Resealable cans serve divergent performance requirements across material compositions, consumption occasions, and procurement channels. Segment boundaries reflect trade-offs between recyclability mandates, shelf-life engineering, and route-to-market economics that reshape supplier priorities.
Product Type:
Material composition determines weight profiles, barrier properties, and compliance pathways under EU packaging regulations.
- Aluminum:Drawn-and-ironed aluminum bodies paired with precision-molded metal closures deliver infinite recyclability and lightweight logistics. Beverage brands in Germany and the Netherlands prioritize aluminum formats to satisfy EU Green Deal targets and command preferential Extended Producer Responsibility rates.
- Steel:Tinplate or tin-free steel variants provide superior puncture resistance for industrial aerosol applications and household product formats. Demand concentrates in Central European manufacturing corridors where damage tolerance outweighs lightweighting priorities.
- Plastic:Polymer resealable containers occupy cost-sensitive beverage niches and temporary storage applications where metal economics prove prohibitive.
- Biodegradable:Emerging compostable formats target premium organic food brands seeking differentiation through end-of-life certification.
Aluminum commands the established base. The steepest expansion runs through biodegradable formats.
End User:
Application verticals split between high-volume beverage consumption and specialized industrial or personal care deployment.
- Food & Beverage:Carbonated drinks, ready-to-drink coffee, and functional beverages drive aluminum resealable can adoption. Dutch retail channels show particular density in ambient coffee distribution, while German brand owners localize supply chains to reduce closure-system lead times.
- Personal Care:Aerosol-adjacent spray formats for cosmetics and functional household products represent underpenetrated territory. REACH compliance through ECHA for lid polymers accelerates migration toward all-metal closure systems in this segment.
- Household Products:Cleaning agents and maintenance chemicals utilize steel variants where chemical compatibility and pressure retention matter.
- Automotive:Specialized lubricant and fluid containers serve professional garage networks through wholesale procurement channels.
Food & Beverage generates the dominant margin pool. Personal Care applications are climbing the fastest.
Capacity:
Volume tiers align with consumption occasion fragmentation between immediate single-serve and extended multi-occasion use.
- Small:Sub-250ml formats target premium functional drinks and sampler portions in Dutch convenience retail.
- Medium:Standard 330-500ml configurations dominate carbonated beverage and ready-to-drink coffee distribution across German supermarkets.
- Large:750ml-1L containers serve sharing occasions and family consumption in household product categories.
- Extra Large:Industrial-scale formats above 1L concentrate in automotive fluids and bulk household chemical procurement.
Medium capacity holds the volume anchor. Large formats are gaining share fastest in household product migration.
Distribution Channel:
Channel selection reflects buyer concentration, order fragmentation, and service-level requirements across end-user segments.
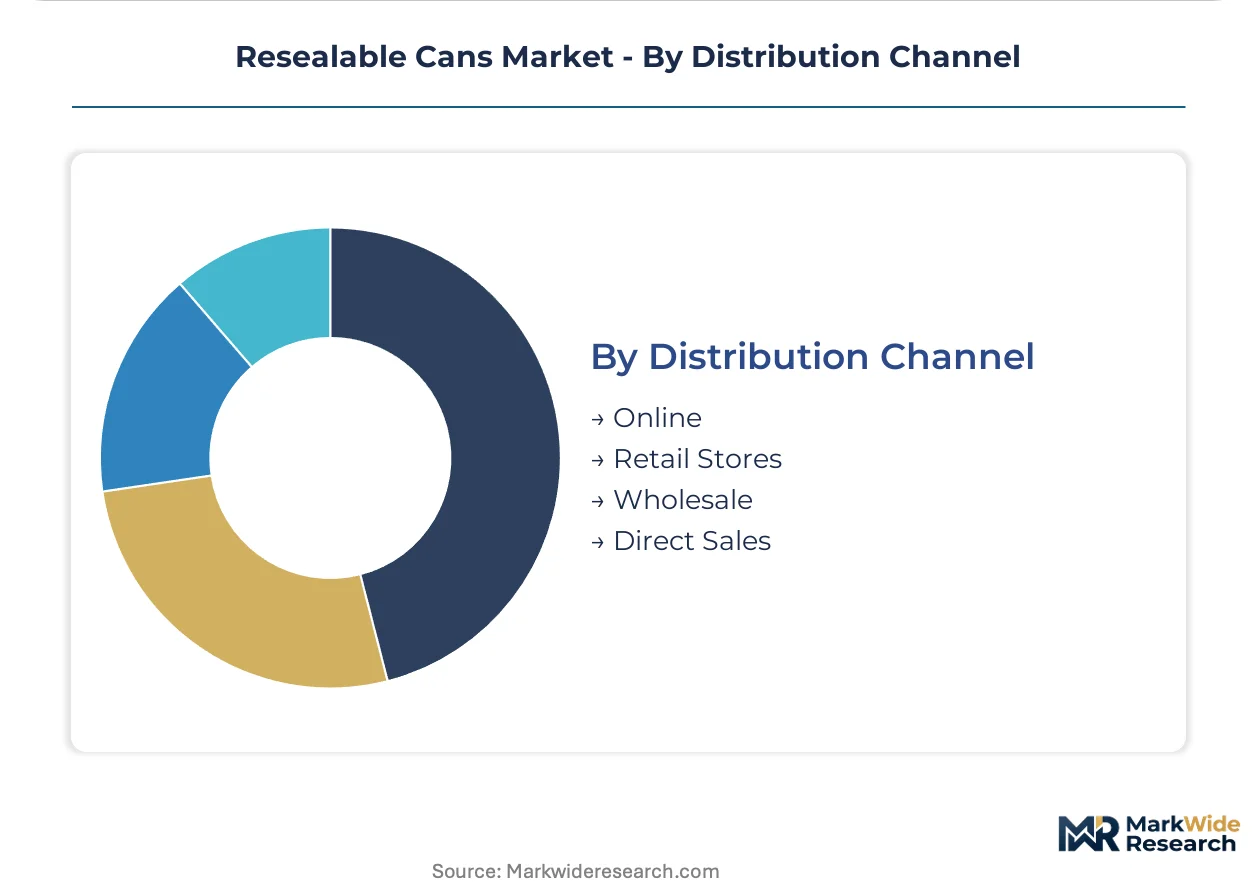
- Online:Direct-to-consumer and B2B platform sales accelerate for specialty beverage brands seeking subscription economics.
- Retail Stores:Supermarket and convenience networks in Germany and the Netherlands remain the primary offtake channel for Food & Beverage resealable cans.
- Wholesale:Industrial buyers in automotive and household products consolidate procurement through distributor networks serving professional end-users.
- Direct Sales:Large beverage brand owners contract directly with Ball Corporation, Crown Holdings, and Silgan Containers for captive supply arrangements.
Retail Stores maintain the incumbent position. Online channels are expanding most quickly in premium beverage verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance through ECHA anchors European resealable can demand as beverage brands eliminate non-recyclable closures. Germany and the Netherlands concentrate procurement gravity. Regulatory compression across EU member states accelerates substitution toward aluminum formats.
Germany
Brand owners localize supply chains to reduce closure-system lead times for carbonated beverages and functional drinks. Extended Producer Responsibility fee structures under the EU Packaging and Packaging Waste Directive reward circular-economy-certified supply chains with preferential rates. Bavaria and North Rhine-Westphalia host the densest manufacturing clusters for drawn-and-ironed aluminum forming.
Netherlands
Ambient ready-to-drink coffee distribution drives premium resealable can adoption in Dutch retail channels. CE marking requirements mandate minimum recyclability thresholds that aluminum formats routinely exceed. The Randstad region concentrates demand for medium-capacity configurations serving on-the-go consumption occasions.
United States
Beverage brands expand aluminum resealable formats for mobile consumption across convenience retail networks. FDA food contact regulations govern interior can coatings and lid polymer safety standards. The Pacific Northwest and Southeast manufacturing corridors anchor Ball Corporation and Crown Holdings production infrastructure.
China
Domestic beverage producers adopt resealable metal formats to satisfy SAMR packaging safety standards and dual carbon goals. GB standards for food contact materials shape interior coating compliance pathways. The Yangtze River Delta and Pearl River Delta concentrate precision-molded closure tooling capacity.
Japan
Premium beverage brands deploy resealable cans for portion-controlled functional drink distribution. METI circular economy roadmaps accelerate substitution from single-use plastic bottles toward infinitely recyclable aluminum. The Kanto region around Tokyo anchors demand for small-capacity formats in convenience retail.
Resealable Cans Market Competitive Environment
Integrated multinational suppliers and specialized closure-system engineers split the market into distinct capability tiers. Ball Corporation and Crown Holdings anchor the consolidated top tier through captive aluminum supply chains and high-volume beverage packaging infrastructure. Silgan Containers occupies a mid-tier position with integrated metal-forming operations across multiple European markets. Competitive moves concentrate on backward integration into precision tooling and geographic expansion toward EPR-optimized supply chains.
Among Germany-based specialists, Can2close GmbH and Xolution GmbH exemplify the closure-system engineering archetype focused on precision-molded lid mechanisms. Ball Corporation, Crown Holdings, and Silgan Containers represent the scale-driven multinational tier with integrated beverage packaging infrastructure spanning North America and Europe. Wilkinson Containers Ltd anchors UK-based fabrication capabilities for niche industrial applications.
| Leading Market Players |
|---|
| Wilkinson Containers Ltd |
| Allstate Can Corporation |
| Ball Corporation |
| Can2close GmbH |
| Silgan Containers |
| Ardagh Group |
| Xolution GmbH |
| Orora |
| Crown Holdings |
| Others |
Value Chain & Pricing Dynamics
Aluminum input cost volatility on the London Metal Exchange determines both pricing tier spreads and supply chain configuration across European resealable can production. This commodity exposure compresses margins for drawn-and-ironed can body manufacturers while forcing tiered sourcing strategies that separate premium certified supply from standard-grade procurement.
Pricing Analysis
German and Dutch markets exhibit the widest price spreads between circular-economy-certified and conventional resealable can tiers. Three-tier pricing structure across premium, standard, and economy levels reflects EPR rate differentials under the EU Packaging and Packaging Waste Directive. Cost compression in the economy tier is intensifying because aluminum scrap competition from Asian buyers elevates input costs. Small functional drink brands in Dutch convenience retail show highest price sensitivity, while premium beverage owners in Germany absorb certification premiums for preferential EPR treatment.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk for precision-molded closure tooling. Manufacturing concentrates in Germany, the Netherlands, and Austria for drawn-and-ironed aluminum forming and polymer lid production. The network draws from bauxite refining in Guinea and Australia, primary aluminum smelting in Iceland and Norway, and specialized polymer feedstocks from German chemical complexes. Single-source vulnerability clusters in Bavarian tooling facilities for precision-molded metal closures. Distribution runs through captive direct sales for large beverage brands and wholesale networks serving industrial aerosol applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resealable can incumbents face substitution pressure from fiber-based cartons and refillable glass systems as EU packaging waste targets tighten. Defense requires locking in circular-economy certification advantages before alternative formats capture EPR rate arbitrage.
For Market Incumbents: Entrench position through backward integration into precision-molded closure tooling to reduce dependency on Bavarian and Austrian single-source suppliers. Expand captive aluminum recycling capacity in North Rhine-Westphalia to secure scrap supply against Asian buyer competition. Prioritize REACH pre-registration for interior coating chemistries ahead of ECHA deadlines to eliminate recertification risk from polymer substitution threats. For New Entrants and Emerging Players: Pursue white-space opportunity in Personal Care aerosol-adjacent formats where REACH compliance accelerates migration toward all-metal closure systems. Target Dutch retail channels for ambient ready-to-drink coffee distribution where medium-capacity resealable cans remain underpenetrated against single-serve plastic bottles. Lead with sustainability certification as the go-to-market angle to command preferential EPR rates from launch. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized closure-system engineers with precision tooling capabilities over commodity can body manufacturers. Long-term viability hinges on circular-economy certification moats that survive through tightening EU Green Deal packaging targets. Watch for inflection in London Metal Exchange aluminum backwardation as the signal for margin compression timing across integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Closure Tooling | Captive supply of precision-molded lids reduces lead time exposure from Bavarian specialists. |
| Circular-Economy Certification Program | EPR-optimized supply chains in Germany command preferential rates versus conventional packaging. |
| Capacity Expansion in North Rhine-Westphalia | Localized aluminum forming reduces logistics costs for German beverage brand procurement. |
| REACH Pre-Registration Investment | Early ECHA compliance for interior coatings eliminates recertification windows against polymer substitution. |
| Joint Venture with Scrap Recyclers | Secure bauxite-aluminum loop access against Asian buyer competition for European scrap. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, EU Packaging and Packaging Waste Directive implementation reports, and London Metal Exchange pricing archives. Primary interviews engaged beverage packaging procurement directors at German and Dutch brand owners, plant managers at drawn-and-ironed aluminum facilities, and regulatory affairs leads specializing in REACH compliance. Secondary validation drew from SEC filings of listed packaging multinationals, customs trade data for aluminum can imports, and industry association circular-economy certification records. Bottom-up demand modeling triangulated against top-down market sizing across material composition and end-use segments.
Forecast inputs span aluminum price trajectory assumptions, EU Green Deal packaging waste target implementation schedules, and EPR fee structure evolution across member states. Segmentation dimensions include material type, end-use vertical, capacity tier, and distribution channel. CAGRs were derived from elasticity-adjusted volume projections tied to substitution rates from single-use plastics. Industry-specific forecast inputs incorporate REACH registration timeline compression for lid polymers and retrofit capital expenditure patterns for legacy filling lines.
Macroeconomic conditions sit as an overlay; deviation in London Metal Exchange aluminum pricing, EU EPR harmonization pace, or German industrial energy costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timing and substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Global Recyclable Packaging Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market