
 Cold Chain Packaging Pooling and Reverse Logistics Services Market | 2026-2036
Cold Chain Packaging Pooling and Reverse Logistics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Chain Packaging Pooling and Reverse Logistics Services Market Insights
Buyer concentration among large biopharmaceutical contract manufacturers is recalibrating procurement leverage across the cold chain packaging pooling and reverse logistics services ecosystem. CSafe leverages its vertically controlled fleet of active temperature-controlled containers to sustain direct relationships with top-ten pharma distributors. Envirotainer dominates intercontinental air freight lanes with its RKN e1 container system, while Cold Chain Technologies specializes in passive parcel shipper configurations for last-mile cell and gene therapy deliveries.
Cold chain packaging pooling and reverse logistics services encompass the cyclical management of temperature-validated shipping assets, including thermal qualification testing, return transit coordination, depot sanitization, and asset redeployment to origin points. Reusable containers typically incorporate vacuum-insulated panels with polyurethane foam cores and phase change material packs engineered to maintain two-to-eight-degree Celsius stability for ninety-six-plus hours. Packaging pooling captures the largest service revenue share due to capital intensity and asset tracking infrastructure requirements, while phase change materials represent the fastest-expanding packaging category as gel pack alternatives face regulatory pressure. Third-party logistics channels lead distribution channel volume by aggregating multi-client reverse logistics flows, though dedicated fleets retain margin premiums for high-value biologics with chain-of-custody demands.
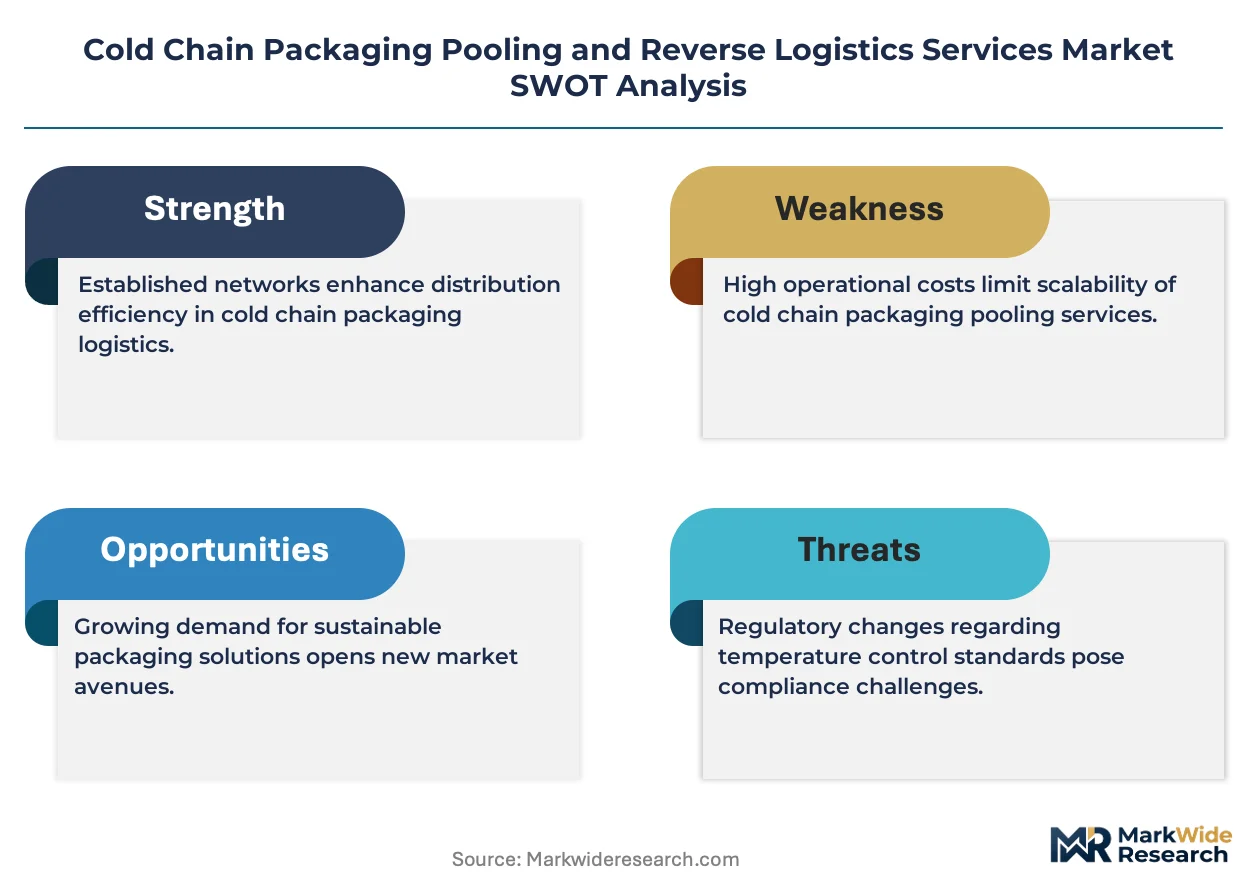
The EU GDP guidelines enforced by national medicines regulators, the US FDA's DSCSA serialization requirements, and IATA CEIV Pharma certification standards collectively elevate compliance costs and barrier thresholds for market entry. FDA inspectional observations on temperature excursion documentation directly trigger corrective action investments in pooling network traceability systems. Stakeholders must monitor evolving pharmacopoeial thermal packaging qualification standards and assess whether to build captive reverse logistics infrastructure or deepen reliance on specialized third-party pooling operators.
Market Dynamics
The EU F-Gas Regulation is compressing hydrofluorocarbon refrigerant availability and forcing shippers toward phase change material alternatives, restructuring asset depreciation cycles across pooling networks.
Growth Catalysts
- Cell and gene therapy expansion:Biopharmaceutical manufacturers require validated thermal packaging for personalized medicine shipments with sub-zero stability requirements, driving depot network densification.
- REACH chemical compliance:European chemical safety frameworks are restricting conventional insulation foams, accelerating vacuum-insulated panel adoption in reusable container fleets.
- Pharmaceutical manufacturing clustering:Dense production zones in Germany and Switzerland generate concentrated outbound shipment volumes that justify dedicated pooling infrastructure investment.
Market Restraints
- PCM raw material volatility:Paraffin and salt hydrate feedstock prices fluctuate with petroleum and mineral commodity markets, compressing phase change material supplier margins.
- Depot network concentration:Third-party pooling operators rely on a limited number of sanitization and refurbishment facilities near major air hubs, creating single-point vulnerability.
- Thermal duration limitations:Passive shipper configurations face hard physical ceilings on hold-time extension without active compressor systems, constraining ultra-long-haul lane viability.
Strategic Opportunities
- Indian biopharma export corridors:Contract manufacturing organizations in Hyderabad and Bangalore are scaling temperature-controlled exports to regulated markets, creating first-mover pooling network potential.
- Real-time visibility integration:IoT sensor telemetry is converging with blockchain custody records to create auditable chain-of-condition documentation for high-value biologics.
- US DSCSA serialization alignment:FDA track-and-trace mandates for pharmaceutical distribution are creating compliance service bundles that combine packaging pooling with serialization data management.
Industry Challenges
- Thermal qualification engineering scarcity:ISTA 7E and WHO PQS protocol expertise concentrates among a limited pool of testing laboratory personnel, extending new product validation timelines.
- Multi-modal handoff coordination:Air-to-road transfer points introduce temperature excursion risks that require redundant sensor coverage and standardized operating procedures across carrier networks.
- Legacy ERP integration:Asset tracking platforms must interface with shipper enterprise systems built on decades-old warehouse management architectures, delaying real-time fleet visibility deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Chain Packaging Pooling and Reverse Logistics Services Market |
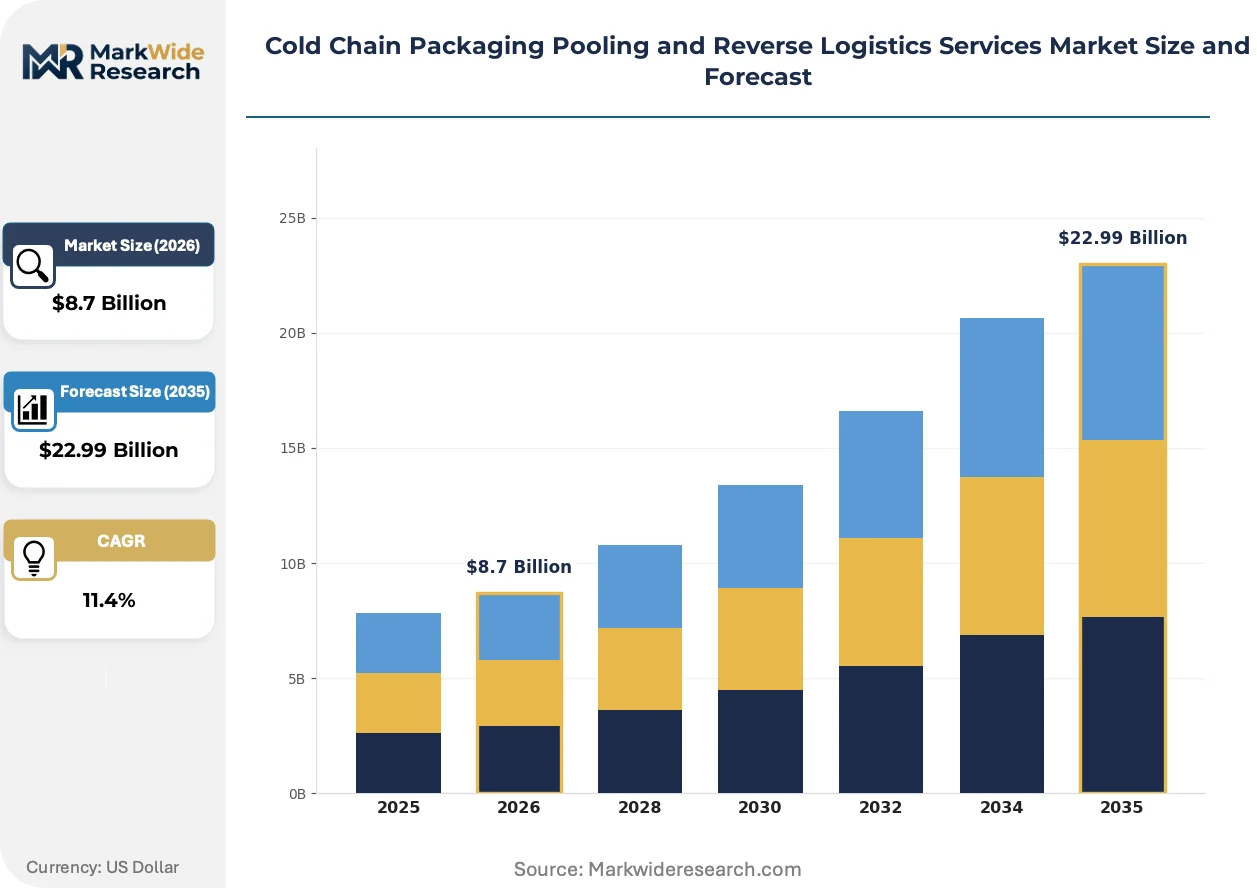
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Packaging Pooling, Reverse Logistics, Inventory Management, Transportation Management, Waste Disposal Packaging Type: Reusable Containers, Insulated Boxes, Gel Packs, Corrugated Boxes, Phase Change Materials End User Industry: Pharmaceuticals, Biotechnology, Food Processing, Chemical Manufacturing, Consumer Electronics Distribution Channel: Third-Party Logistics, Dedicated Fleets, Contract Carriers, Freight Forwarders, Courier Services |
| Companies Covered | Envirotainer, CSafe, Cold Chain Technologies, Peli BioThermal, SkyCell, Sonoco ThermoSafe, Sofrigam, Intelsius, UPS Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Chain Packaging Pooling and Reverse Logistics Services Market Trends and Innovations
Digital traceability infrastructure and material science advances are compressing validation cycles while expanding the addressable range of temperature-sensitive shipments beyond traditional cold chain lanes.
Phase change material formulations are converging with machine learning-driven thermal modeling to enable predictive stability assessment before physical lane qualification. Biopharmaceutical quality assurance teams are adopting these in-silico tools to reduce ISTA 7E testing iterations by half. The technology is converging with automated packaging configuration software that matches payload dimensions to optimal PCM mass and placement.
Europe's F-Gas Regulation mandates an eighty percent phasedown of hydrofluorocarbon refrigerants by 2030, eliminating a core input for gel pack manufacturing. Thermal packaging suppliers are reformulating around bio-based phase change materials with comparable latent heat properties. Air freight forwarders operating EU-originating lanes face the most immediate compliance pressure and are accelerating qualification of PCM alternatives.
Biopharmaceutical procurement teams are consolidating vendor relationships around full-service pooling operators who assume reverse logistics liability. Small and mid-sized drug developers are abandoning in-house thermal packaging management in favor of subscription-based asset access models. This vendor consolidation pattern is most pronounced in Germany and Switzerland, where GDP inspection intensity has elevated compliance failure costs beyond captive operation viability.
Cold Chain Packaging Pooling and Reverse Logistics Services Market Segmentation
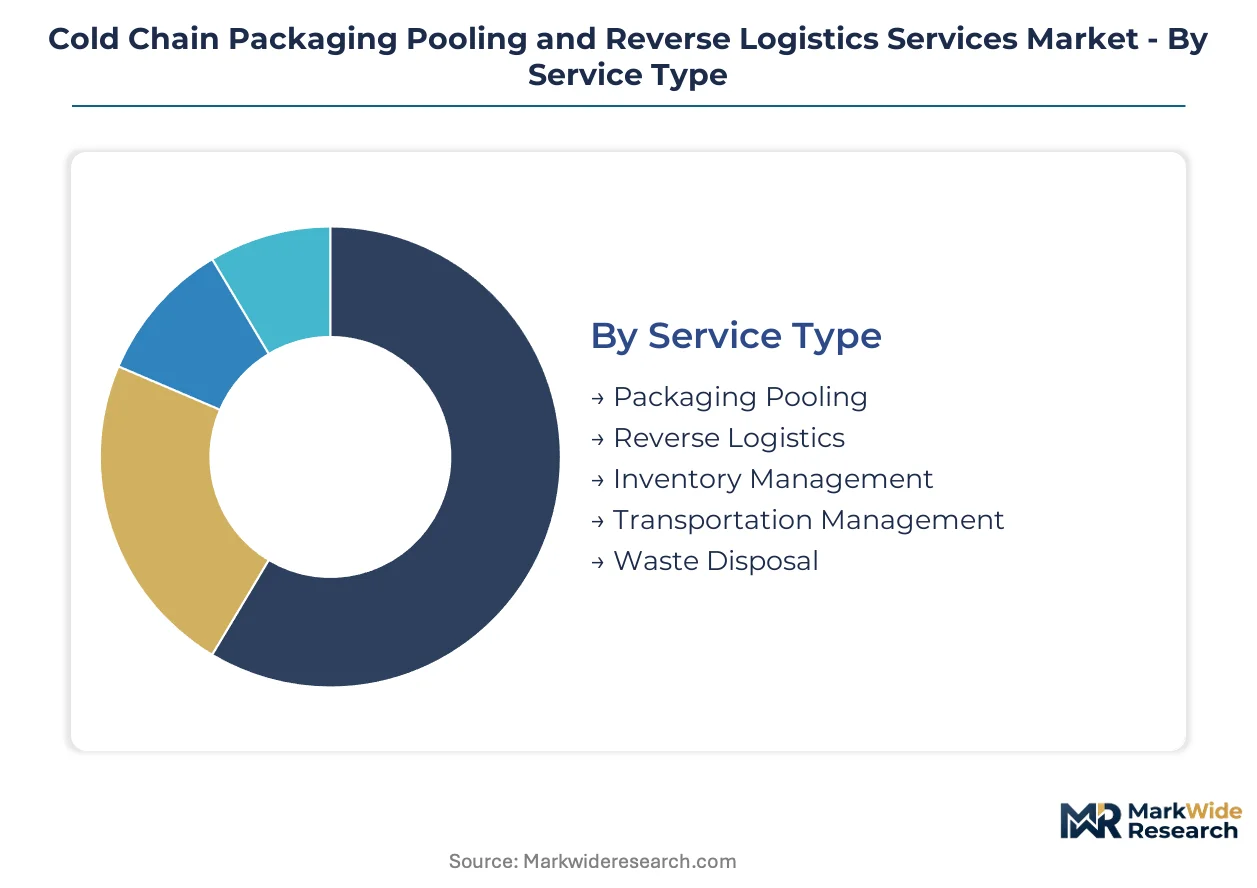
Cold chain packaging pooling and reverse logistics services fragment across service intensity, asset technology, and custody requirements. Procurement teams align vendor selection with shipment value density, regulatory exposure, and network reach constraints.
Service Type:
Capital intensity peaks in packaging pooling, where fleet ownership and depot infrastructure dominate upfront investment requirements.
- Packaging Pooling:Asset-heavy service involving thermal container ownership, qualification testing, and circular redeployment through sanitization depots. German pharmaceutical manufacturers sustain the densest pooling network investments due to EMA GDP inspection intensity and outbound biologics volume concentration.
- Reverse Logistics:Coordination of empty container return flows, customs documentation for cross-border asset movements, and damage assessment protocols. Demand concentrates among biotech contract manufacturers in Switzerland managing multi-site European distribution networks with strict chain-of-custody requirements.
- Inventory Management:Depot-based asset positioning and demand forecasting for pooled container availability.
- Transportation Management:Lane optimization and carrier selection for temperature-validated movements.
- Waste Disposal:Regulatory-compliant destruction of single-use thermal packaging and exhausted phase change materials.
Most installed capacity flows through Packaging Pooling. Expansion is steepest in Reverse Logistics.
Packaging Type:
Margin structure separates vacuum-insulated precision systems from commodity thermal protection, with material substitution reshaping supplier positioning.
- Reusable Containers:Vacuum-insulated panel systems with polyurethane foam cores engineered for ninety-six-plus hour temperature stability. Swiss biopharmaceutical exporters deploy these assets for intercontinental lane qualification under IATA CEIV Pharma standards.
- Phase Change Materials:Salt hydrate and paraffin formulations displacing hydrofluorocarbon gel packs under EU F-Gas Regulation phasedown mandates. REACH chemical compliance restrictions on conventional insulation foams are accelerating PCM adoption in German-manufactured container fleets.
- Insulated Boxes:Expanded polystyrene or polyurethane configurations for shorter-duration protection.
- Gel Packs:Hydrofluorocarbon-based refrigerants facing regulatory phaseout pressure.
- Corrugated Boxes:Single-use fiber-based outer shells for parcel shipment consolidation.
Reusable Containers retain the largest deployed base. Phase Change Materials are gaining share fastest.
End User Industry:
Compliance burden and shipment value density create sharp segmentation in procurement sophistication and service tier selection.
- Pharmaceuticals:Temperature-sensitive small-molecule drugs and vaccines requiring GDP-validated documentation. FDA DSCSA serialization mandates are forcing US distributors toward integrated pooling providers with track-and-trace data capabilities.
- Biotechnology:Cell and gene therapy shipments with sub-zero stability requirements and personalized medicine logistics complexity. Swiss and German clusters generate concentrated demand for validated thermal systems with redundant sensor coverage.
- Food Processing:Perishable shipment protection with shorter hold-time tolerances.
- Chemical Manufacturing:Hazardous material temperature control with dual regulatory compliance.
- Consumer Electronics:Battery shipment thermal management for air freight safety.
Pharmaceuticals command the deepest pooling infrastructure. Biotechnology shows the steepest expansion trajectory.
Distribution Channel:
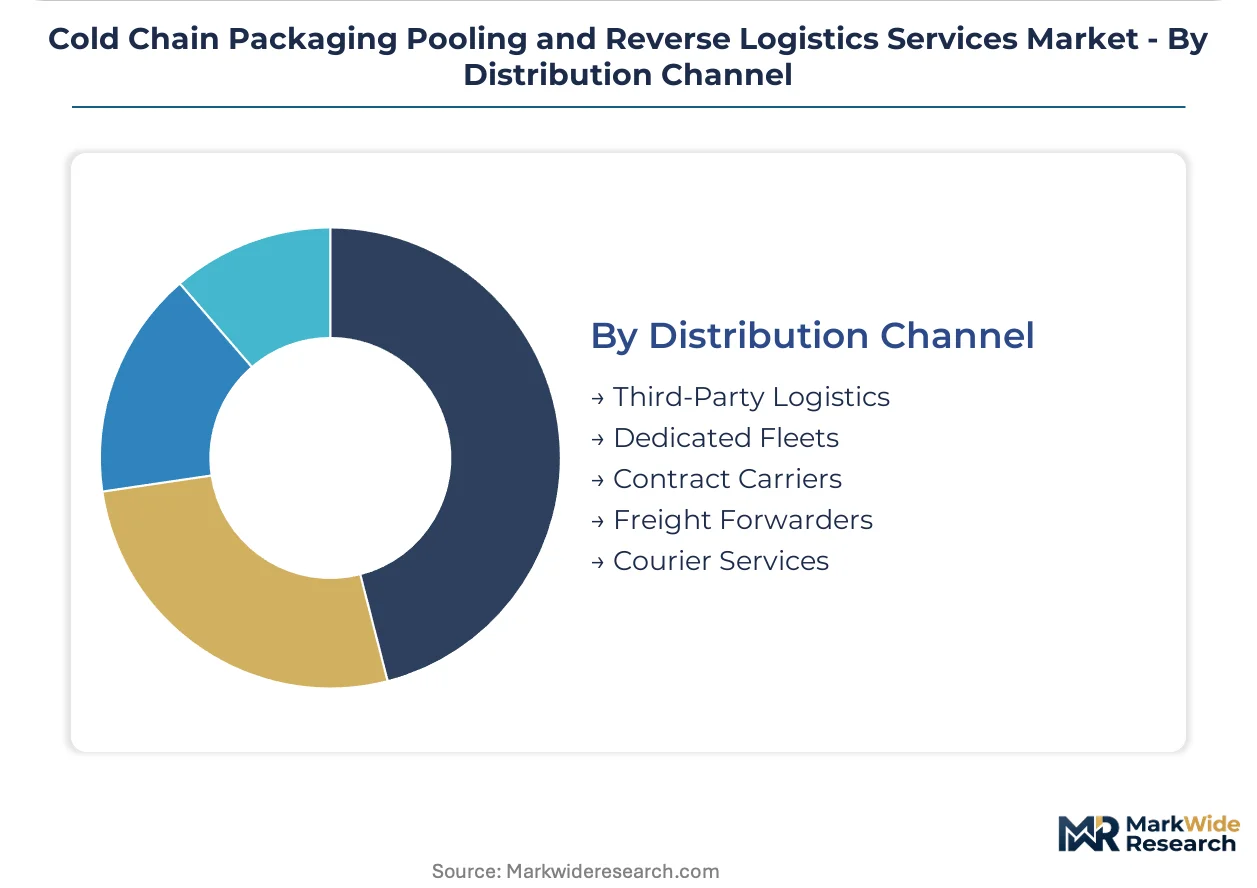
Custody liability and visibility requirements determine channel selection between aggregated third-party flows and dedicated asset control.
- Third-Party Logistics:Multi-client aggregation of reverse logistics volumes through shared depot networks and standardized sanitization protocols. Indian contract manufacturing organizations in Hyderabad and Bangalore are scaling temperature-controlled exports through 3PL pooling partnerships.
- Dedicated Fleets:Captive vehicle and container assets for high-value biologics with chain-of-custody documentation requirements. German GDP enforcement intensity has elevated dedicated fleet premiums for temperature excursion liability absorption.
- Contract Carriers:Long-term lane-specific capacity agreements with thermal performance guarantees.
- Freight Forwarders:Air freight consolidation with IATA CEIV Pharma certification requirements.
- Courier Services:Last-mile parcel delivery with passive shipper configurations.
Third-Party Logistics handles the largest volume share. Dedicated Fleets capture the highest margin tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany sustains deeper pooling network investments than the United States, while Indian contract manufacturers are accelerating temperature-controlled export corridor development.
Germany
EMA GDP inspection intensity and dense pharmaceutical manufacturing clusters sustain the highest pooling infrastructure density in Europe. The EU F-Gas Regulation mandates hydrofluorocarbon refrigerant phasedown, forcing depots toward phase change material alternatives. Bavaria and Baden-Württemberg host concentrated biologics production zones that justify dedicated sanitization facility investment.
United States
FDA DSCSA serialization requirements are integrating track-and-trace data capabilities with packaging pooling procurement decisions. The FDA's temperature excursion documentation standards trigger corrective action investments in network traceability systems. Greater Boston and the San Francisco Bay Area anchor cell and gene therapy logistics demand with sub-zero stability requirements.
Switzerland
Swissmedic enforcement elevates chain-of-custody documentation standards for intercontinental biopharmaceutical exports. REACH chemical compliance frameworks restrict conventional insulation foams, accelerating vacuum-insulated panel adoption in container fleets. Basel and Zurich generate concentrated demand for validated thermal systems with redundant sensor coverage.
India
Contract manufacturing organizations in Hyderabad and Bangalore are scaling temperature-controlled exports to regulated markets, creating first-mover pooling network potential. CDSCO alignment with ICH guidelines elevates thermal qualification protocol adherence for export-bound shipments. The Telangana and Karnataka clusters are attracting dedicated depot infrastructure investment from third-party logistics operators.
United Kingdom
Post-Brexit customs complexity increases reverse logistics documentation burden for cross-border container movements. MHRA retention of EU GDP guideline equivalence sustains compliance cost structures for pooling operators. The Golden Triangle logistics corridor between London, Birmingham, and Manchester concentrates pharmaceutical distribution infrastructure investment.
Cold Chain Packaging Pooling and Reverse Logistics Services Market Competitive Landscape
German and Swiss producers anchor one tier of precision-engineered container systems; United States-based specialists hold contract logistics integration capabilities. The market structures around three strategic archetypes: active temperature-controlled container manufacturers, passive shipper configuration specialists, and integrated third-party logistics operators. Consolidation pressure concentrates among pooling network operators seeking depot scale economies. Competitive moves center on geographic corridor expansion and real-time visibility technology partnerships.
Within the active container tier, Envirotainer and CSafe exemplify vertically controlled fleet operators sustaining direct pharmaceutical distributor relationships. Cold Chain Technologies occupies a position among passive configuration specialists focused on last-mile cell and gene therapy logistics. These three anchors represent divergent asset intensity models across the packaging pooling ecosystem.
| Leading Market Players |
|---|
| Envirotainer |
| CSafe |
| Cold Chain Technologies |
| Peli BioThermal |
| SkyCell |
| Sonoco ThermoSafe |
| Sofrigam |
| Intelsius |
| UPS Healthcare |
| Others |
Pricing and Supply Chain Analysis
ISTA 7E thermal qualification engineers concentrated in Germany and Switzerland command premium compensation that propagates through service pricing tiers, widening spreads between GDP-certified premium offerings and standard depot-based pooling contracts.
Pricing Analysis
Capacity additions in India are reshaping price floors for temperature-validated container leasing. Three-tier pricing structure across GDP-certified premium, CE-marked standard, and non-certified economy levels stratifies procurement options. Cost compression in standard-tier passive shippers is intensifying because REACH-compliant vacuum-insulated panel feedstock prices fluctuate with mineral commodity markets. Small biotech developers exhibit highest price sensitivity and migrate fastest toward subscription-based asset access models.
Supply Chain Analysis
Regional distribution centers near Frankfurt, Mumbai, and Singapore anchor hub-and-spoke patterns for container redeployment. Manufacturing of reusable thermal systems concentrates in Germany, Switzerland, and the United States. Phase change material production draws from paraffin feedstocks tied to petroleum markets and salt hydrate minerals sourced from Chilean and Chinese deposits. Single-source vulnerability permeates PCM formulation expertise concentrated among specialty chemical suppliers. Distribution runs through third-party logistics aggregators consolidating multi-client reverse logistics volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cold chain packaging pooling rests on automation-driven depot cost reduction and biopharmaceutical procurement consolidation toward full-service operators absorbing reverse logistics liability.
For Market Incumbents: Anticipate EU F-Gas Regulation compliance deadlines by accelerating phase change material qualification ahead of hydrofluorocarbon gel pack phaseout. Consolidate sanitization depot networks in Germany and Switzerland to capture scale economies against emerging Indian competitors. Vertical integration into IoT sensor telemetry partnerships secures real-time visibility differentiation.
For New Entrants and Emerging Players: Machine learning-driven thermal modeling tools offer technology-first wedge positioning against incumbent qualification laboratories. Target Hyderabad and Bangalore contract manufacturing corridors where CDSCO-aligned export growth outpaces dedicated depot infrastructure. Lead with automated packaging configuration software reducing ISTA 7E testing iterations.
For Investors and Strategic Acquirers: Third-party logistics operators with pharmaceutical verticals are the most active acquirer in this space, seeking pooling network scale. Five-to-ten year viability hinges on depot density in high-growth biopharma export corridors. Watch Indian CDSCO inspection intensity alignment with ICH guidelines as inflection signal for export corridor infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Depot Network Automation | Robotic sanitization systems reduce German GDP-compliant facility operating costs by half. |
| Phase Change Material Qualification | Bio-based PCM formulations secure EU F-Gas Regulation compliance ahead of 2030 mandates. |
| Real-Time Visibility Integration | IoT sensor convergence with blockchain custody records satisfies FDA DSCSA documentation requirements. |
| Indian Corridor Infrastructure | Hyderabad and Bangalore depot investments capture CDSCO-aligned export growth to regulated markets. |
| Subscription Service Model | Asset-access pricing absorbs reverse logistics liability for small biotech developers. |
Research Methodology
Multiple input streams — thermal packaging engineering directors, biopharmaceutical quality assurance leads, third-party logistics procurement officers, and phase change material R&D specialists — were reconciled against secondary validation from EMA GDP inspection records, FDA DSCSA guidance documents, IATA CEIV Pharma certification databases, and customs trade flows for temperature-controlled container movements. Bottom-up service revenue modeling and top-down pharmaceutical logistics spend allocation were triangulated.
Historical growth patterns were cross-referenced against panel input from depot operators and container manufacturers. Segmentation dimensions spanned service type, packaging technology, end-user industry, and distribution channel complexity. CAGRs were derived from installed base depreciation cycles and biopharmaceutical shipment volume projections. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and Indian CDSCO regulatory alignment trajectories.
The model holds under stable regulatory enforcement intensity; deviation in EMA GDP inspection frequency or CDSCO export certification timelines would shift capacity investment assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Freezer Liner Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Cold Storage Insulated Market