
 Disposable Paper Plates Market | 2026-2036
Disposable Paper Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Paper Plates Market Analysis
Barrier-coated molded fiber technology is rewriting how disposable paper plates achieve grease resistance without plastic lamination. Huhtamaki leverages its integrated pulp-to-converting footprint across the American Midwest to sustain cost leadership in heavy-duty plate production. Georgia-Pacific anchors North American supply through its captive bleached board mills, while Pactiv competes aggressively in the foodservice channel through direct distributor relationships and private-label scale.
Disposable paper plates are single-use foodservice items manufactured from wood pulp, sugarcane bagasse, or bamboo fiber, typically formed through wet-pressing or dry-molding processes and specified by basis weight, rim rigidity, and liquid holdout duration; they serve the commercial and consumer need for sanitary, portable meal presentation without washing infrastructure. Compostable plates lead material-based demand as municipal organic waste programs expand across the United States, with sugarcane bagasse variants commanding premium placement in California and Pacific Northwest markets. Online retailers represent the fastest-growing distribution channel, though wholesale distributors still occupy the dominant margin pool through contracted volume commitments with national restaurant chains.
The EPA regulates post-consumer fiber content claims under its Comprehensive Procurement Guidelines, while the FDA governs food-contact substance safety under 21 CFR, and ASTM International maintains D6400 and D6868 standards for compostability certification that shape product development priorities. State-level extended producer responsibility legislation in California and Oregon is forcing importers to document fiber sourcing and end-of-life pathways. Stakeholders must monitor how municipal composting infrastructure buildouts alter the economic case for certified compostable plates versus conventional coated alternatives.
Market Dynamics
Barrier-coated molded fiber technology is compressing the competitive set by eliminating plastic lamination without sacrificing grease resistance, forcing converters to retool wet-press lines or exit the heavy-duty segment entirely.
Growth Catalysts
- EPA Food Packaging Waste Guidelines:Federal pressure on quick-service restaurants to abandon plastic-coated tableware accelerates fiber-based procurement at scale.
- Sugarcane Bagasse Processing:Pulp mills in the American Southeast are expanding bagasse pulping capacity, lowering raw material logistics costs for regional converters.
- Off-Premise Dining Expansion:Drive-through and delivery program growth at national restaurant chains sustains bulk single-serve tableware demand.
Market Restraints
- Bleached Board Input Volatility:Kraft pulp price swings transmit directly to converter margins, compressing profitability during supply tightness.
- Municipal Composting Infrastructure Gaps:Uneven buildout of industrial composting facilities across the United States limits the addressable market for certified compostable plates.
- Polypropylene Substitution in Wet Applications:Plastic plates retain cost and performance advantages for high-moisture foods, capping fiber penetration in specific menu categories.
Strategic Opportunities
- California Extended Producer Responsibility Mandates:Documentation requirements for fiber sourcing and end-of-life pathways favor domestic converters with integrated supply chains.
- Online Retail Channel Expansion:Direct-to-consumer platforms enable private-label penetration beyond traditional foodservice distributor networks.
- Bamboo Fiber Convergence with Barrier Chemistry:Hybrid material formulations combining bamboo pulp with advanced coatings open premium positioning in Pacific Northwest markets.
Industry Challenges
- ASTM D6400 Certification Timelines:Third-party compostability testing creates 12-18 month product development cycles that delay market entry.
- Wet-Press Line Retooling Costs:Barrier-coated molded fiber production requires capital-intensive equipment upgrades that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Paper Plates Market |
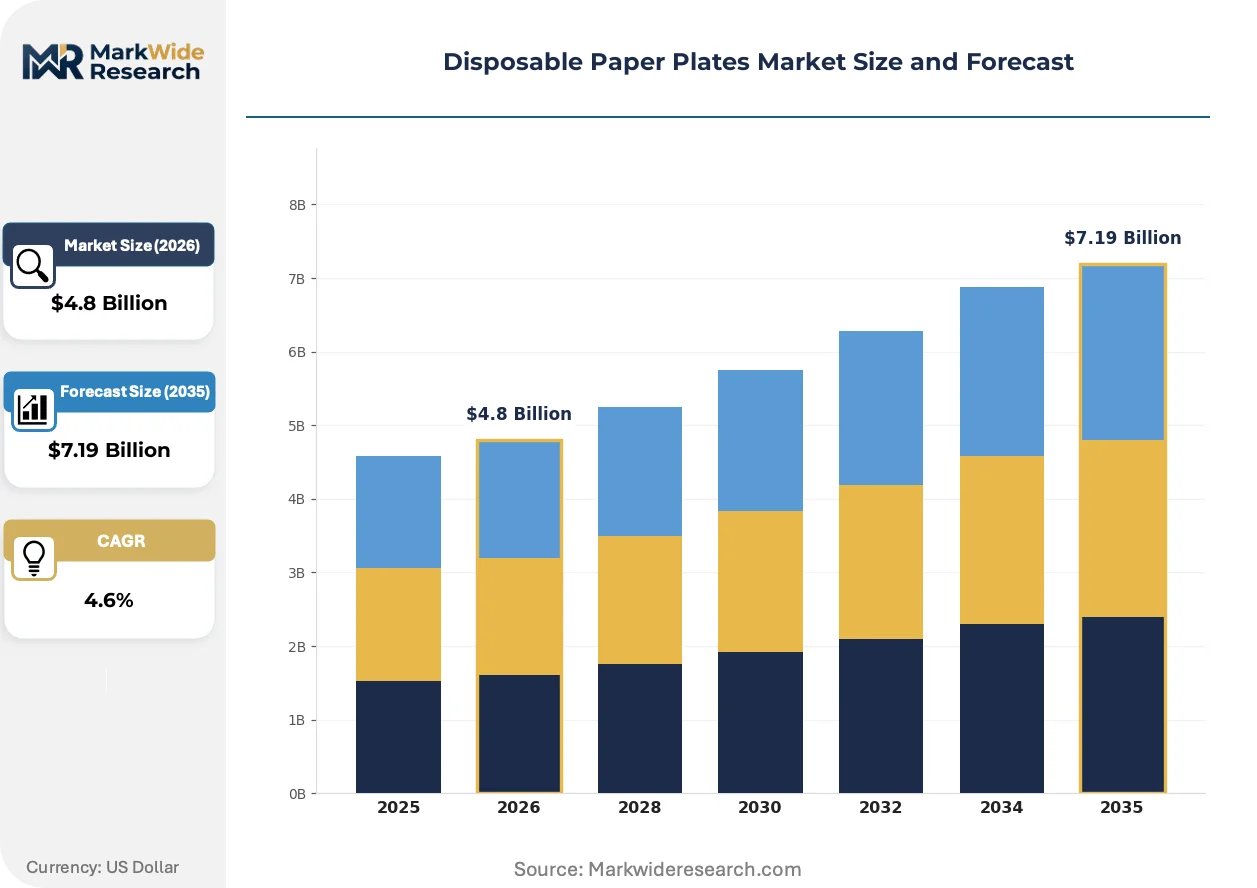
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Plates, Chinet Plates, Compostable Plates, Biodegradable Plates End User: Restaurants, Catering Services, Households, Food Trucks Material: Pulp, Sugarcane Bagasse, Bamboo, Recycled Paper Distribution Channel: Online Retailers, Wholesale Distributors, Grocery Stores, Supermarkets |
| Companies Covered | International Paper, Pactiv, Dart Container Corporation, Duni, Hotpack Group, Genpak, Huhtamaki, Poppies Europe, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Paper Plates Market Emerging Trajectories
Active innovation in the disposable paper plates market centers on material chemistry breakthroughs, regulatory compliance automation, and distribution channel restructuring that together redefine competitive advantage.
Barrier-coated molded fiber technology is rendering obsolete conventional polyethylene-laminated plates in quick-service applications. National restaurant chains are specifying these formulations in new supply contracts at accelerating pace. The shift compresses margins for converters lacking in-house coating capabilities or captive pulp supply.
California's extended producer responsibility legislation is forcing importers to deploy blockchain-tracked fiber sourcing documentation. The state's organic waste mandates now require proof of compostability certification for products sold into municipal procurement. Quick-service operators in Los Angeles and San Francisco are pre-qualifying suppliers based on documentation readiness rather than unit cost alone.
Foodservice distributors are unbundling volume commitments from exclusive supply arrangements as buyer concentration intensifies. National restaurant chains are consolidating procurement through direct manufacturer relationships, bypassing traditional wholesale intermediaries. The American Southeast exhibits this pattern most visibly, where pulp mill proximity enables converters to offer delivered pricing that matches distributor landed costs.
Disposable Paper Plates Market Segmentation
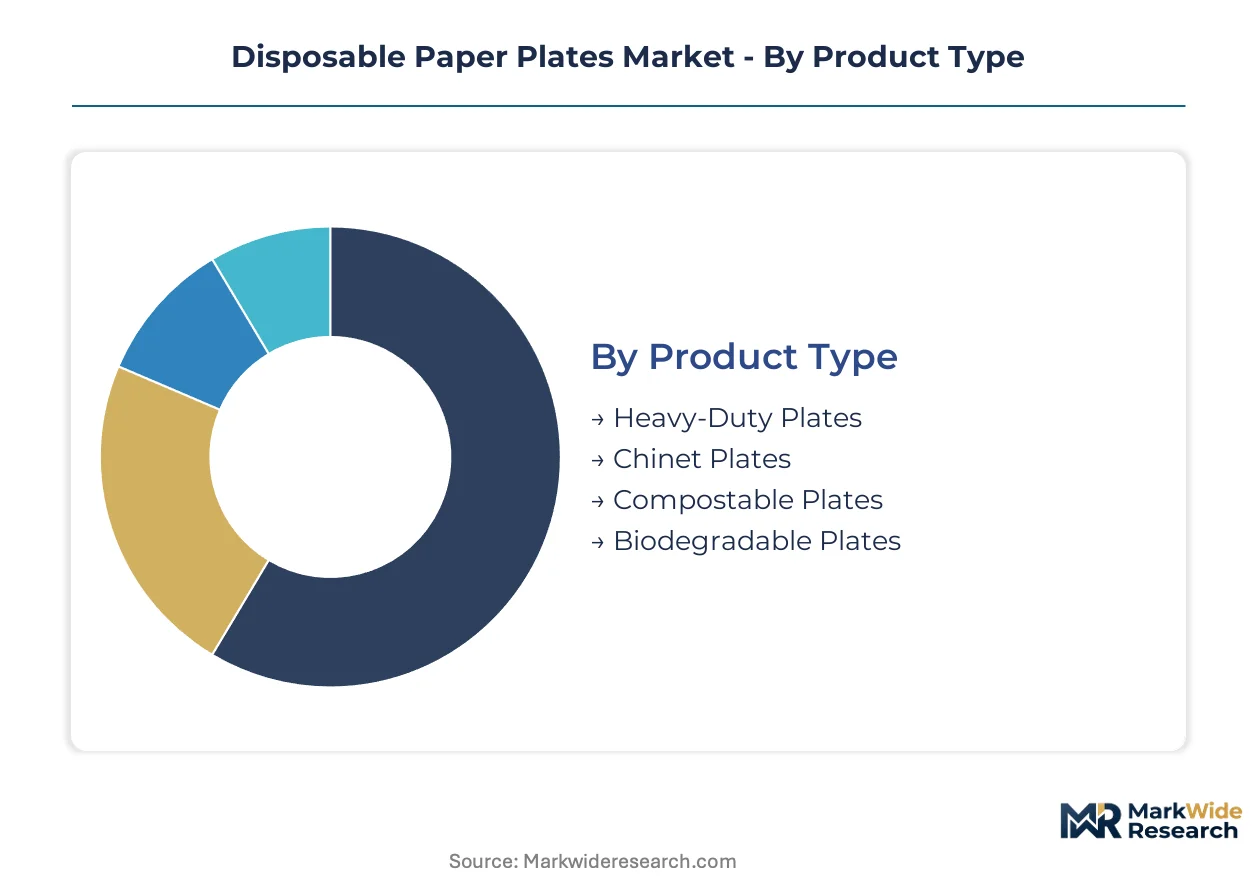
Segmentation in disposable paper plates reveals how procurement priorities diverge between cost-sensitive bulk buyers and sustainability-driven premium purchasers. Understanding these fault lines exposes where margin pools concentrate and which technology investments yield competitive separation.
Product Type:
Cost tier differentiation separates occasional-use consumers from commercial operators demanding structural integrity under hot, heavy loads.
- Heavy-Duty Plates:Multi-ply construction with enhanced rim rigidity supports loaded meals without sagging. Quick-service restaurants in the American Southeast specify these for drive-through programs where presentation quality affects brand perception.
- Compostable Plates:Certified fiber formulations meeting ASTM D6400 standards enable municipal organic waste program participation. California and Pacific Northwest markets require these for compliance with extended producer responsibility mandates, commanding price premiums over conventional alternatives.
- Chinet Plates:Molded fiber with distinctive rim styling targets upscale casual dining and catered events where aesthetics justify higher unit costs.
- Biodegradable Plates:Uncertified fiber variants lacking industrial composting certification serve price-conscious buyers seeking environmental positioning without documentation burden.
Heavy-Duty Plates commands the established base. The steepest expansion runs through Compostable Plates.
End User:
Application intensity determines volume predictability and contract structure, from erratic household purchasing to multi-year foodservice supply agreements.
- Restaurants:National chains negotiate direct manufacturer relationships with volume commitments spanning 12-36 months. Off-premise dining expansion sustains bulk procurement of single-serve tableware across quick-service and fast-casual formats.
- Households:Event-driven purchasing concentrates around holidays and summer outdoor dining seasons. Online retail platforms capture this demand through subscription and bulk-pack formats that reduce per-unit shipping costs.
- Catering Services:White-glove presentation requirements favor premium molded fiber with coating barriers that resist sauce penetration during transport.
- Food Trucks:Space-constrained operations prioritize stackability and lightweight logistics over premium specifications, accepting thinner-gauge alternatives.
Restaurants anchor volume concentration. Households are climbing the fastest as direct-to-consumer channels mature.
Material:
Supply geography and processing chemistry create divergent cost positions and sustainability credentials across fiber inputs.
- Sugarcane Bagasse:Agricultural residue from sugar processing requires less bleaching energy than wood pulp and carries stronger compostability narratives. Pulp mill proximity in Louisiana and Florida lowers logistics costs for regional converters serving Gulf Coast foodservice markets.
- Pulp:Bleached kraft from southeastern US mills remains the volume leader due to established supply chains and coating compatibility. Price volatility in softwood markets transmits directly to converter margins.
- Bamboo:Rapid-renewal grass fiber appeals to West Coast premium positioning but faces higher freight costs from Asian processing facilities.
- Recycled Paper:Post-consumer fiber content satisfies EPA Comprehensive Procurement Guidelines for federal contractors but introduces contamination risks affecting food-contact compliance.
Pulp holds the volume base. Sugarcane Bagasse shows the steepest expansion trajectory as composting infrastructure spreads.
Distribution Channel:
Customer type and purchase scale determine whether buyers route through intermediaries or establish direct manufacturer relationships.
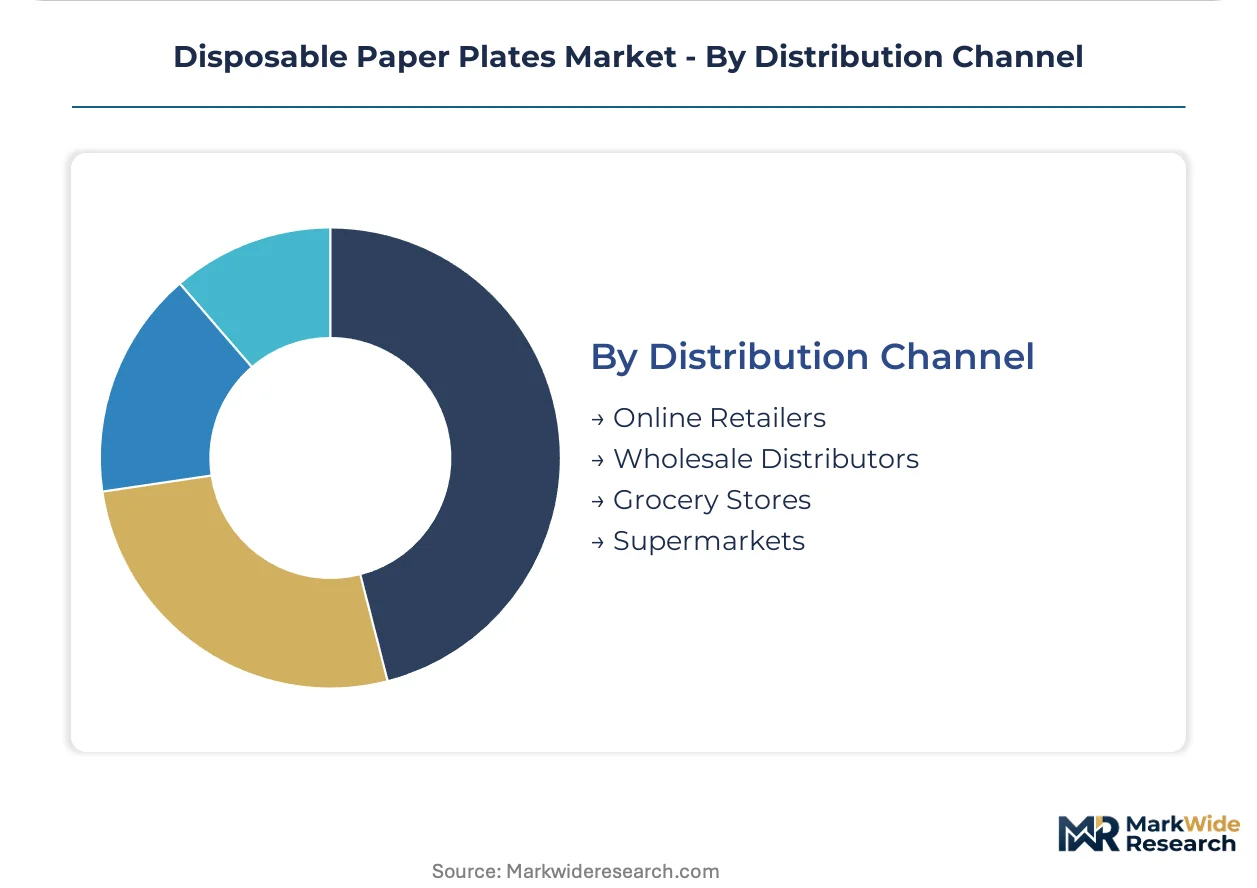
- Wholesale Distributors:Broadline foodservice distributors maintain contracted volume commitments with national restaurant chains, bundling paper plates with broader disposable tableware portfolios.
- Online Retailers:Direct-to-consumer platforms enable private-label penetration beyond traditional distributor territories, with fastest-growing share in household and small-catering segments.
- Grocery Stores:Seasonal promotional placement captures impulse purchasing for outdoor dining and holiday entertaining occasions.
- Supermarkets:Club-format bulk packaging serves small foodservice operators and large households with storage capacity for volume purchases.
Wholesale Distributors retain the established margin pool. Online Retailers are gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and municipal organic waste programs concentrate demand in specific geographies where pulp mill proximity, regulatory pressure, and composting infrastructure intersect. Buyer archetypes split between cost-driven bulk foodservice operators and compliance-focused institutional purchasers.
United States
Off-premise dining expansion at national restaurant chains sustains bulk procurement of single-serve tableware. The EPA's Comprehensive Procurement Guidelines pressure federal contractors toward post-consumer fiber content. Pulp mill concentration in the American Southeast lowers raw material logistics costs for regional converters serving Gulf Coast foodservice markets.
Germany
EU Green Deal packaging waste regulations accelerate fiber-based alternatives to plastic-coated tableware. ECHA guidance on food-contact substances shapes coating chemistry development priorities. Industrial converters in North Rhine-Westphalia leverage established paperboard supply chains to serve central European foodservice distributors.
China
Rapid urbanization and food delivery platform growth expand single-use tableware consumption in tier-one cities. SAMR food-contact safety standards govern domestic and export production. Yangtze River Delta manufacturing clusters concentrate molded fiber converting capacity for Asia-Pacific export markets.
India
Street food vendor formalization and quick-service restaurant expansion drive disposables demand in metropolitan areas. FSSAI food packaging safety regulations influence material selection for domestic consumption. Maharashtra and Gujarat house emerging molded fiber converting operations serving western India foodservice networks.
Brazil
Sugarcane bagasse availability from ethanol processing creates raw material cost advantages for regional converters. ANVISA food-contact regulations align with Mercosur technical standards. São Paulo state industrial parks concentrate pulp-to-converting operations serving South American foodservice distribution.
Disposable Paper Plates Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: integrated pulp-to-converting operators with captive fiber supply, specialty coating technology holders commanding premium positioning, and scale-driven distributors leveraging private-label volume. Dominant competitive moves include backward integration into pulp supply and direct procurement relationships that bypass traditional wholesale intermediaries.
Among North American integrated operators, Georgia-Pacific and International Paper exemplify the pulp-captive archetype with in-house bleached board supply. Huhtamaki occupies a specialist position in barrier-coated molded fiber technology. Pactiv represents the distributor-aligned scale player competing through foodservice channel relationships and private-label penetration.
| Leading Market Players |
|---|
| International Paper |
| Pactiv |
| Dart Container Corporation |
| Duni |
| Hotpack Group |
| Genpak |
| Huhtamaki |
| Poppies Europe |
| Georgia-Pacific |
| Others |
Supply Flow & Price Mechanics
Southeastern US pulp mill concentration anchors converter cost positions and dictates where margin pools accumulate downstream. Kraft pulp price volatility transmits directly to heavy-duty plate producers lacking captive fiber supply, while barrier-coated molded fiber specialists command premium positioning through in-house coating capabilities.
Pricing Analysis
Cost-plus contracts indexed to Random Lengths pulp futures dominate procurement between converters and national restaurant chains. Three-tier pricing structure across premium compostable, standard coated, and economy uncoated levels separates ASTM D6400-certified bagasse variants from bleached kraft alternatives. Pricing pressure stems from polypropylene substitution in wet applications where plastic retains performance advantages. Quick-service chains exhibit highest price sensitivity, while California institutional buyers prioritize documentation compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Georgia-Pacific's captive bleached board mills in the American Southeast and International Paper's integrated pulp-to-converting operations. Raw material dependencies center on softwood kraft pulp, sugarcane bagasse from Louisiana processing facilities, and proprietary barrier coating chemistries. Supply chain risk hinges on single-source vulnerability for advanced coating formulations imported from European specialty chemical suppliers. Distribution runs through broadline foodservice distributors, though direct manufacturer relationships are displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier coating technology licensing and compostability certification services represent faster-expanding recurring revenue layers than commodity plate production. Service-attach opportunities concentrate in compliance documentation and coating formulation supply.
For Market Incumbents: Insulate heavy-duty plate margins through backward integration into southeastern pulp supply and accelerated ASTM D6400 certification timelines. Polypropylene substitution in high-moisture applications threatens fiber penetration; proprietary barrier chemistry R&D is the essential defensive lever. For New Entrants and Emerging Players: Pursue online retail channel penetration with private-label compostable plates targeting Pacific Northwest household segments. California extended producer responsibility mandates create the most penetrable white-space for documentation-ready suppliers. Direct-to-consumer subscription models offer viable go-to-market angles outside distributor-controlled foodservice networks. For Investors and Strategic Acquirers: Capital is best deployed toward integrated pulp-to-converting operators with captive southeastern fiber supply and in-house coating capabilities. Long-term viability across the analysis window favors converters controlling upstream raw material access and downstream certification documentation. Monitor municipal composting infrastructure buildout rates as the critical inflection signal for certified compostable plate addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive kraft fiber access insulates Georgia-Pacific and International Paper from price volatility. |
| Barrier Coating Technology Licensing | Huhtamaki's proprietary formulations command premium positioning in quick-service procurement. |
| ASTM D6400 Certification Investment | California extended producer responsibility mandates require documentation for municipal procurement eligibility. |
| Direct-to-Consumer Channel Expansion | Online retail platforms enable private-label penetration beyond traditional foodservice distributor networks. |
| Sugarcane Bagasse Processing Capacity | Louisiana and Florida pulp mill proximity lowers logistics costs for Gulf Coast converters. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quick-service restaurant procurement directors, molded fiber plant managers, foodservice distributor category buyers, and EPA compliance officers. Secondary validation drew from FDA food-contact substance filings, ASTM International certification databases, SEC 10-K disclosures from integrated paperboard producers, and state-level extended producer responsibility legislation texts. Bottom-up volume estimates triangulated against top-down pulp consumption data.
Calibration against historical price elasticities and pulp-to-plate conversion yields anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product performance tier, material chemistry, end-use application intensity, and distribution channel structure. CAGRs were derived from regression analysis of procurement volume trends and capacity expansion announcements. Industry-specific forecast inputs incorporated municipal composting facility buildout timelines and quick-service off-premise dining program expansion rates.
Sensitivities concentrate around kraft pulp price volatility, polypropylene substitution thresholds, and uneven municipal composting infrastructure deployment. Forecasts reflect documented assumptions on regulatory enforcement consistency and coating technology adoption curves. Quarterly review of state-level extended producer responsibility implementation and pulp futures pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Converting Paper Market