
 Reusable Ice Packs Market | 2026-2036
Reusable Ice Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Ice Packs Market Outlook
Healthcare provider procurement is pivoting toward multi-use cold therapy systems that reduce per-treatment waste. YETI leverages its premium brand architecture to dominate high-performance outdoor and medical-adjacent channels. Rubbermaid sustains broad retail distribution across pharmacy and mass-merchant formats. Engel differentiates through heavy-duty rotomolded construction aimed at extended-duration cold chain applications.
Reusable ice packs are thermally engineered containers filled with gel, phase-change material, or insulated fluid, designed to maintain sub-ambient temperatures through repeated freeze-thaw cycles for therapeutic cooling, food preservation, or specimen transport. Fabrication methods include blow-molded plastic shells, welded PVC bladders, and silicone pouches with sealed gel matrices, with thermal performance measured in hours of sustained temperature retention. Gel packs lead volume due to conformability and cost efficiency in physical therapy settings, while rigid packs command margin pools in institutional healthcare where durability protocols dominate procurement criteria. Flexible packs represent the fastest-growing configuration as athletes and retail consumers prioritize portability and anatomical fit.
FDA medical device classifications shape product claims and labeling requirements for therapeutic cold applications, while EPA guidelines on PVC and plasticizer content constrain material selection for domestic manufacturers. REACH compliance in Europe restricts certain phthalate formulations, creating divergence in regional product portfolios. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that could mandate recycling infrastructure for polymer-based thermal products.
Market Dynamics
FDA medical device classifications for temperature-regulated therapeutic products are tightening compliance requirements, forcing manufacturers to revalidate gel formulations and labeling claims while healthcare procurement shifts toward multi-use cold therapy systems that reduce per-treatment waste.
Growth Catalysts
- Post-surgical cold therapy protocols:Healthcare providers are expanding evidence-based cryotherapy programs in orthopedic and sports medicine recovery, driving institutional procurement of reusable phase-change systems.
- REACH compliance divergence:European restrictions on phthalate formulations have triggered regional product portfolio specialization, creating competitive differentiation for compliant manufacturers.
- Home healthcare segment expansion:Aging populations and remote patient monitoring programs are accelerating replacement cycles for consumer-grade gel packs in the United States.
Market Restraints
- Petrochemical input volatility:Polymer shell materials and gel matrices face price instability tied to propylene and ethylene feedstock fluctuations.
- Extended producer responsibility mandates:Emerging state-level recycling infrastructure requirements for polymer-based thermal products threaten compliance cost escalation.
- Single-use instant cold pack substitution:Disposable chemical reaction packs retain cost advantage in emergency medical services and acute care settings.
Strategic Opportunities
- Athletic performance segment:Professional sports teams and collegiate programs represent underpenetrated demand for anatomically contoured flexible packs with compression integration.
- Cold chain specimen transport:Biopharmaceutical logistics providers seek extended-duration rotomolded solutions for temperature-sensitive diagnostic samples.
- EPA plasticizer guidelines:Anticipated domestic restrictions on PVC content create first-mover advantage for bio-based polymer innovators.
Industry Challenges
- FDA 510(k) clearance timelines:Medical device classification for therapeutic cold products extends certification cycles and elevates documentation burdens.
- Phase-change material formulation expertise:Scarcity of thermal engineers capable of optimizing latent heat capacity across freeze-thaw cycles constrains R&D velocity.
- Legacy hospital supply chain integration:New reusable systems face friction against entrenched group purchasing organization contracts and vendor credentialing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Ice Packs Market |
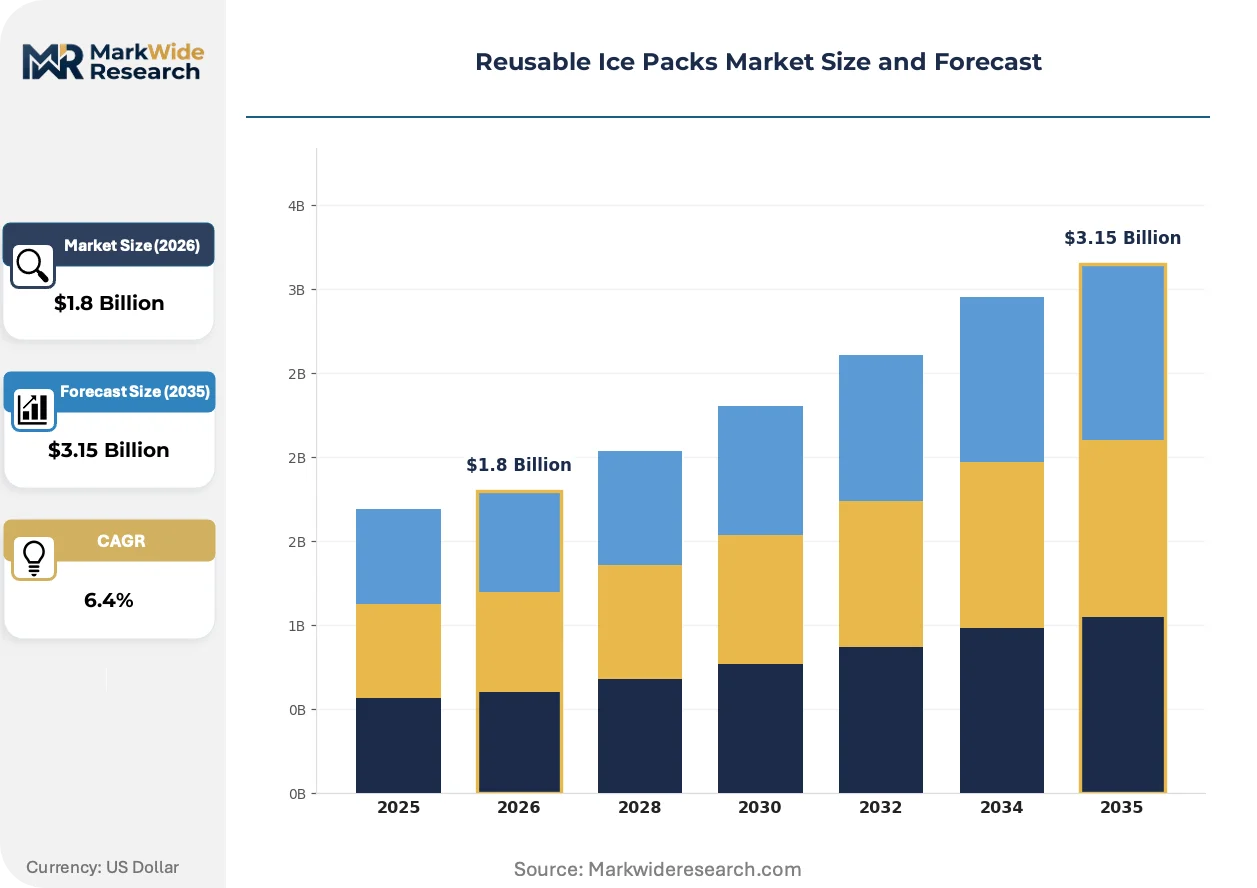
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packs, Gel Packs, Rigid Packs, Cold Compress Target Audience: Athletes, Healthcare Providers, Physical Therapists, Retail Consumers Material: Plastic, PVC, Silicone, Fabric Use Case: Sports Therapy, Injury Recovery, Pain Relief, First Aid |
| Companies Covered | Rubbermaid, Igloo, Engel, Fit & Fresh, FlexiFreeze, Techni Ice, Cooler Shock, NatraCure, YETI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Ice Packs Market Strategic Shifts
Material science advances and regulatory pressure are converging to reshape thermal retention engineering, with manufacturers racing to develop bio-based alternatives that satisfy both performance benchmarks and evolving chemical safety mandates.
Phase-change material technology is absorbing market share from traditional gel formulations in high-performance medical and outdoor applications. Hospital procurement departments and expedition equipment suppliers are adopting salt-hydrate and paraffin-based systems at accelerating rates. This transition is absorbing margin from commodity gel pack producers while rewarding thermal engineering specialists with premium positioning.
REACH restrictions on phthalate plasticizers in Europe have forced reformulation of PVC bladder components across the regional supply base. Manufacturers serving EU markets now maintain parallel product lines with bio-based elastomer substitutes. Medical device producers targeting European hospital systems face the steepest adaptation costs and longest validation timelines.
Direct-to-consumer subscription models for replacement ice pack inventories are disrupting traditional pharmacy and mass-merchant distribution. Athletic trainers and physical therapy clinics now source anatomical packs through specialized orthopedic supply platforms rather than general medical distributors. This channel migration is most pronounced in the United States, where sports medicine spending concentrates in metropolitan outpatient networks.
Reusable Ice Packs Market Segmentation
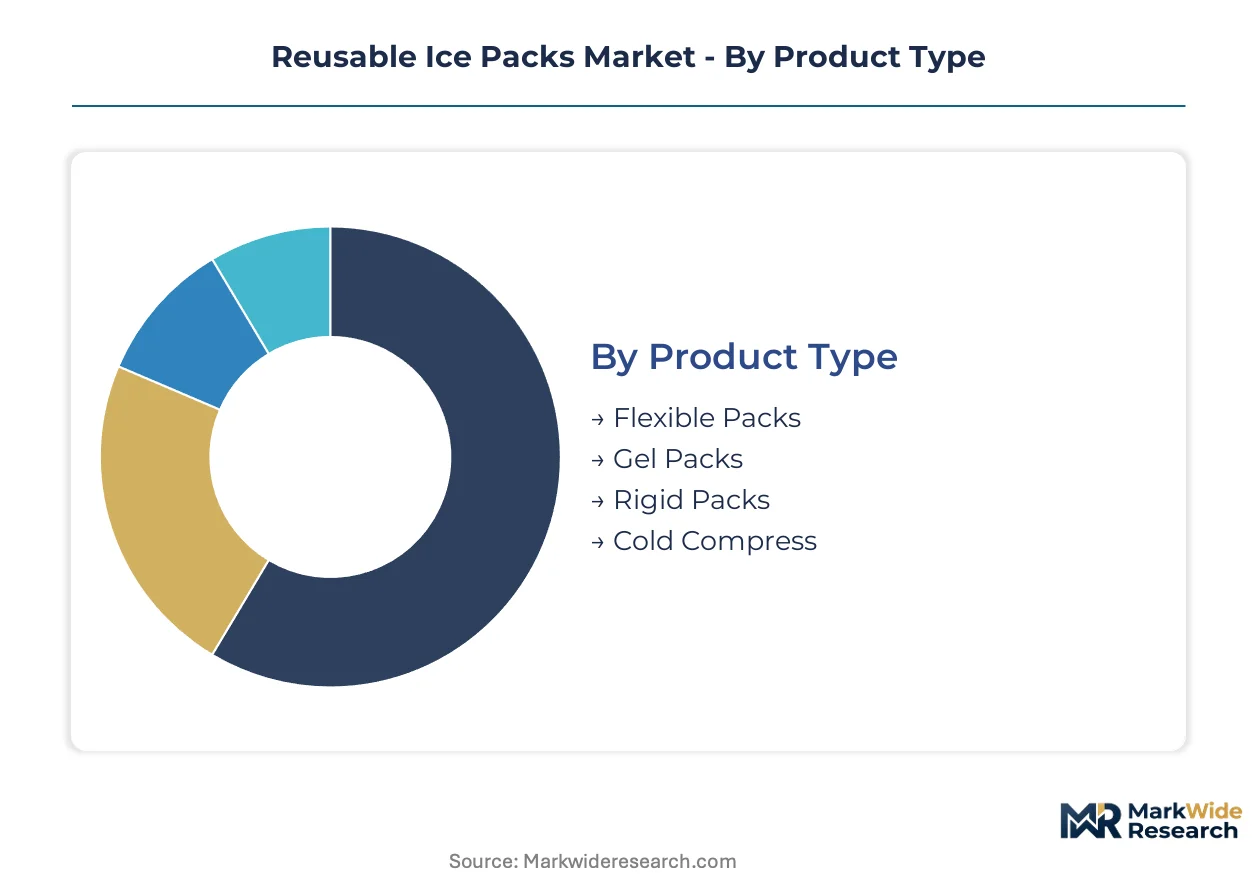
Reusable ice pack procurement splits between standalone consumer purchases and embedded systems within cold chain logistics and institutional therapy protocols. Material selection and pack rigidity determine integration depth across healthcare, athletic, and retail channels.
Product Type:
Gel packs and flexible configurations dominate standalone therapeutic applications, while rigid systems embed into institutional cold chain infrastructure.
- Gel Packs:Polymer matrices with aqueous gel solutions provide conformable cold delivery for 20-40 minute therapeutic windows. Demand concentrates in United States physical therapy clinics where post-surgical protocols mandate repeated freeze-thaw cycles. PVC bladder construction faces EPA plasticizer scrutiny.
- Flexible Packs:Fabric-encased phase-change materials contour to anatomical joints and muscle groups. Athletes and collegiate sports programs in Texas and California drive replacement cycles for compression-integrated designs. REACH-compliant bio-based elastomers command price premiums.
- Rigid Packs:Blow-molded HDPE shells with insulated cores serve institutional healthcare and biopharmaceutical transport.
- Cold Compress:Pre-fabricated wraps with integrated gel sections target home healthcare and emergency first aid kits.
Gel packs lead volumes today; flexible packs are gaining share fastest.
Target Audience:
Procurement authority separates institutional buyers with validation requirements from price-sensitive retail consumers.
- Healthcare Providers:Hospital systems and outpatient surgery centers source FDA-validated phase-change systems through group purchasing organizations. Medicare reimbursement protocols for cryotherapy drive specification rigor.
- Physical Therapists:Independent practices and franchise networks in Florida and Arizona prioritize anatomical fit and compression compatibility for ACL and rotator cuff rehabilitation protocols.
- Athletes:Professional sports teams and NCAA programs represent concentrated demand for rapid-recovery cold immersion systems.
- Retail Consumers:Pharmacy and mass-merchant channels serve home inventory replacement for minor injury management.
Healthcare providers anchor procurement value; athletes represent the steepest expansion trajectory.
Material:
Polymer chemistry determines thermal retention performance and regulatory compliance pathways across domestic and export markets.
- Plastic:HDPE and polypropylene shells dominate blow-molded rigid pack production for institutional durability requirements.
- PVC:Welded bladder construction offers cost-efficient gel containment but faces EPA and REACH restrictions on phthalate plasticizers. European hospital procurement now excludes non-compliant formulations.
- Silicone:Medical-grade elastomer pouches withstand autoclave sterilization and extreme temperature cycling. Biopharmaceutical logistics providers in Massachusetts and North Carolina specify silicone for diagnostic specimen transport.
- Fabric:Nylon and neoprene outer layers enable compression integration and moisture wicking for athletic applications.
Plastic leads installed base; silicone is climbing the fastest on biopharma cold chain demand.
Use Case:
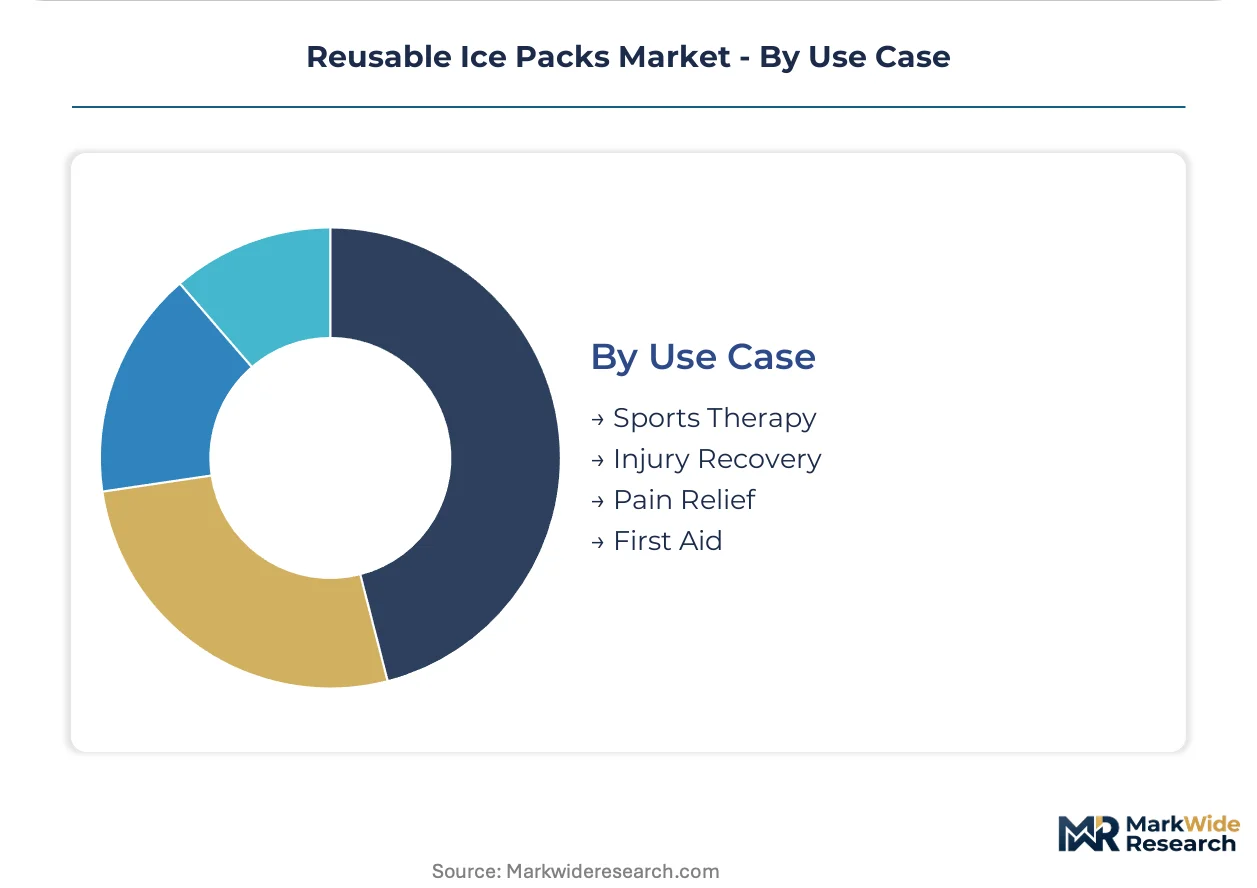
Clinical evidence requirements separate reimbursable medical applications from discretionary consumer purchases.
- Injury Recovery:Post-surgical orthopedic protocols in hospital systems mandate reusable cold therapy for edema reduction and pain management. FDA 510(k) clearance distinguishes reimbursable from non-reimbursable systems.
- Sports Therapy:Professional training rooms and collegiate athletic departments prioritize rapid temperature recovery and anatomical coverage for in-season injury management.
- Pain Relief:Chronic condition management in home healthcare settings drives retail pharmacy distribution for arthritis and neuropathy patients.
- First Aid:Emergency medical services and workplace safety programs specify instant-activation alternatives, constraining reusable pack penetration.
Injury recovery commands procurement value; sports therapy is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with lower compliance costs for polymer processing, creating divergence between REACH-regulated European supply chains and EPA-monitored domestic fabrication. This regulatory arbitrage accelerates capacity expansion in Southeast Asia while tightening material traceability requirements for cross-border shipments.
United States
Post-surgical cryotherapy protocols in Texas and Florida outpatient centers drive institutional procurement of FDA-validated phase-change systems. EPA scrutiny of PVC plasticizer content forces domestic reformulation toward bio-based elastomers. Massachusetts biopharmaceutical clusters specify silicone-based transport solutions for diagnostic specimen cold chains.
Germany
REACH restrictions on phthalate formulations have triggered parallel product line maintenance for EU hospital procurement. ECHA compliance costs elevate price positioning for compliant manufacturers serving Bavarian and North Rhine-Westphalian healthcare networks. Stuttgart-area thermal engineering specialists concentrate phase-change material R&D for premium medical applications.
China
Guangdong and Zhejiang provinces host blow-molded HDPE fabrication for export-oriented rigid pack production. NMPA alignment with international medical device standards accelerates domestic certification for therapeutic cold products. Yangtze River Delta manufacturers supply silicone pouch components to Japanese and South Korean biopharma logistics providers.
Japan
PMDA medical device classifications for temperature-regulated therapeutic products extend validation timelines for imported systems. METI industrial standards on polymer recyclability shape domestic procurement criteria for hospital cold therapy equipment. Osaka-based sports medicine clinics drive demand for anatomically contoured flexible packs with compression integration.
Australia
TGA therapeutic goods regulations mandate local stability testing for phase-change materials used in clinical settings. Queensland and New South Wales mining operations sustain demand for heavy-duty rotomolded solutions in remote-site medical facilities. Sydney-headquartered biopharmaceutical distributors specify extended-duration cold chain systems for temperature-sensitive diagnostic exports.
Reusable Ice Packs Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers balance medical-grade validation costs against consumer retail margin pressure. The vendor base separates into three tiers: premium thermal engineering specialists, mass-market polymer fabricators, and private-label contract manufacturers serving pharmacy chains. Strategic archetypes include FDA-focused medical device producers, outdoor recreation brand extenders, and cold chain logistics integrators. M&A activity concentrates on phase-change material technology acquisitions, while geographic expansion targets Southeast Asian polymer processing clusters.
Within the premium thermal engineering tier, YETI and Engel exemplify divergent positioning strategies. YETI leverages its outdoor recreation brand architecture to capture medical-adjacent channels where performance credentials transfer across use cases. Engel anchors the heavy-duty institutional segment through rotomolded construction expertise. Rubbermaid occupies a position bridging mass-merchant retail distribution with institutional durability requirements, representing the scale-driven archetype that sustains volume leadership across pharmacy and healthcare supply networks.
| Leading Market Players |
|---|
| Rubbermaid |
| Igloo |
| Engel |
| Fit & Fresh |
| FlexiFreeze |
| Techni Ice |
| Cooler Shock |
| NatraCure |
| YETI |
| Others |
Value Chain & Pricing Dynamics
Propylene and ethylene feedstock volatility cascades through polymer shell manufacturing into tiered pricing for gel-based and phase-change systems, with FDA-validated medical grades commanding premiums over consumer retail configurations.
Pricing Analysis
Distributor margin compression in mass-merchant channels intensifies as direct-to-consumer orthopedic platforms bypass traditional pharmacy networks. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) certification status and thermal retention duration specifications. Cost compression in consumer-grade gel packs stems from private-label contract manufacturing expansion. Retail consumers exhibit highest price sensitivity, while hospital systems purchasing through group purchasing organizations prioritize validation documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong and Zhejiang province manufacturers for blow-molded HDPE shell production. Raw material dependencies encompass propylene derivatives, phase-change salt-hydrate formulations, and medical-grade silicone elastomers. Tariff exposure on Chinese polymer processing threatens margin stability for US distributors. Distribution runs through group purchasing organizations for institutional healthcare, direct-to-consumer platforms for athletic segments, and mass-merchant retail for home inventory replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by durable replacement cycles in post-surgical cold therapy protocols and expanding home healthcare segments.
For Market Incumbents: Anchor market position through backward integration into phase-change material formulation capabilities and captive supply of REACH-compliant bio-based elastomers. Defend against single-use instant cold pack substitution by embedding reusable systems into hospital vendor credentialing protocols and GPO contract structures. Prioritize FDA 510(k) clearance maintenance for therapeutic cold claims to sustain reimbursement eligibility.
For New Entrants and Emerging Players: Collegiate athletic departments represent an underserved buyer archetype with concentrated procurement authority and limited incumbent penetration. White-space targets include anatomically contoured flexible packs with compression integration for Texas and California sports medicine networks, and extended-duration rotomolded solutions for biopharmaceutical specimen transport. Go-to-market execution should leverage specialized orthopedic supply platforms rather than general medical distributors.
For Investors and Strategic Acquirers: Consolidation pressure builds where phase-change material formulation expertise concentrates among thermal engineering specialists with limited scale. Long-term viability favors medical-grade validated producers with durable hospital supply chain relationships over commodity consumer fabricators. Acquisition targets should demonstrate FDA clearance portfolios and established GPO contracts. The signal to watch is EPA plasticizer guideline finalization, which would accelerate bio-based polymer substitution and reward compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phase-Change Material Production | Captures margin from thermal engineering specialists and secures formulation IP. |
| FDA 510(k) Clearance Investment | Unlocks Medicare reimbursement pathways for post-surgical cryotherapy protocols. |
| REACH-Compliant Bio-Based Elastomer Transition | Preserves European hospital access as ECHA restrictions tighten on phthalate alternatives. |
| Direct-to-Consumer Platform Development | Bypasses distributor margin compression in mass-merchant pharmacy channels. |
| Hospital System Partnership Expansion | Entrenches reusable systems against single-use substitution in group purchasing contracts. |
Study Parameters
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records; and customs trade data on polymer imports — were reconciled through bottom-up and top-down triangulation.
Historical shipment patterns were cross-referenced against panel input from thermal engineering specialists and cold chain logistics providers to model volume trajectories across the projection horizon. Segmentation dimensions encompassed product rigidity, material chemistry, target buyer archetype, and clinical application. CAGRs were derived from installed base replacement cycles and protocol expansion rates. Industry-specific forecast inputs included FDA clearance timelines and REACH compliance adaptation costs.
Underlying measurement precision varies by segment; institutional healthcare procurement carries tighter precision than fragmented retail consumer channels. Forecasts reflect assumptions on regulatory timeline adherence and polymer feedstock stability. Specific risk factors encompass EPA plasticizer guideline acceleration and state-level extended producer responsibility mandate implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Curbside Recyclable Packaging Market