
 Qatar ICT Market | 2026-2036
Qatar ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar ICT Market Analytics
Enterprise-grade infrastructure specifications are rotating toward sovereign cloud and edge-ready architectures across Qatar's public sector procurement pipelines. Ooredoo Q.P.S.C. leverages its domestic fiber backbone and submarine cable landing rights to anchor government and carrier-neutral data center contracts. Cisco Systems Inc. competes on secure networking portfolios tailored to Qatar's critical infrastructure operators, while Huawei Technologies Co., Ltd. extends its position in 5G base station deployment and smart city IoT layers under framework agreements with municipal authorities.
Information and communications technology in Qatar encompasses the design, deployment, and operation of digital infrastructure spanning cloud platforms, enterprise software, telecommunications networks, and cybersecurity systems, typically engineered to Tier III or Tier IV data center reliability standards with sub-10 millisecond latency targets for financial services workloads. Its primary commercial purpose is to enable economic diversification beyond hydrocarbons by digitizing trade logistics, government services, and knowledge-based industries. Cloud Computing dominates current procurement volumes as ministries and QatarEnergy affiliates retire legacy on-premises estates, while AI segments capture disproportionate R&D investment through Qatar Foundation's applied research partnerships. Managed Services margins exceed those in pure hardware resale, with system integration contracts for hybrid cloud deployments representing the fastest-growing revenue pool as enterprises navigate multi-vendor environments.
The National Cyber Security Agency enforces data residency and encryption standards that shape vendor qualification criteria for public sector tenders, while Qatar Central Bank's operational risk guidelines mandate business continuity architectures for financial institutions. TRAI-equivalent spectrum and licensing frameworks govern telecommunications infrastructure deployment timelines and competitive access terms. Stakeholders must monitor how forthcoming national AI governance frameworks and data protection regulations alter liability structures for cloud service providers operating in the domestic market.
Market Dynamics
Qatar's ICT sector operates under sovereign cloud mandates from the National Cyber Security Agency that are compressing procurement timelines and disqualifying non-compliant vendors from public tenders.
Growth Catalysts
- Qatar National Vision 2030:Government digitization targets are accelerating enterprise software deployment across ministries and state-owned entities, creating sustained demand for integrated platforms.
- Data Residency Requirements:The National Cyber Security Agency's encryption and localization standards are compelling financial institutions to rebuild infrastructure on domestic cloud estates.
- Lusail Smart City Development:The Doha district's data center clusters and AI R&D labs are anchoring national capacity and attracting specialized system integration contracts.
Market Restraints
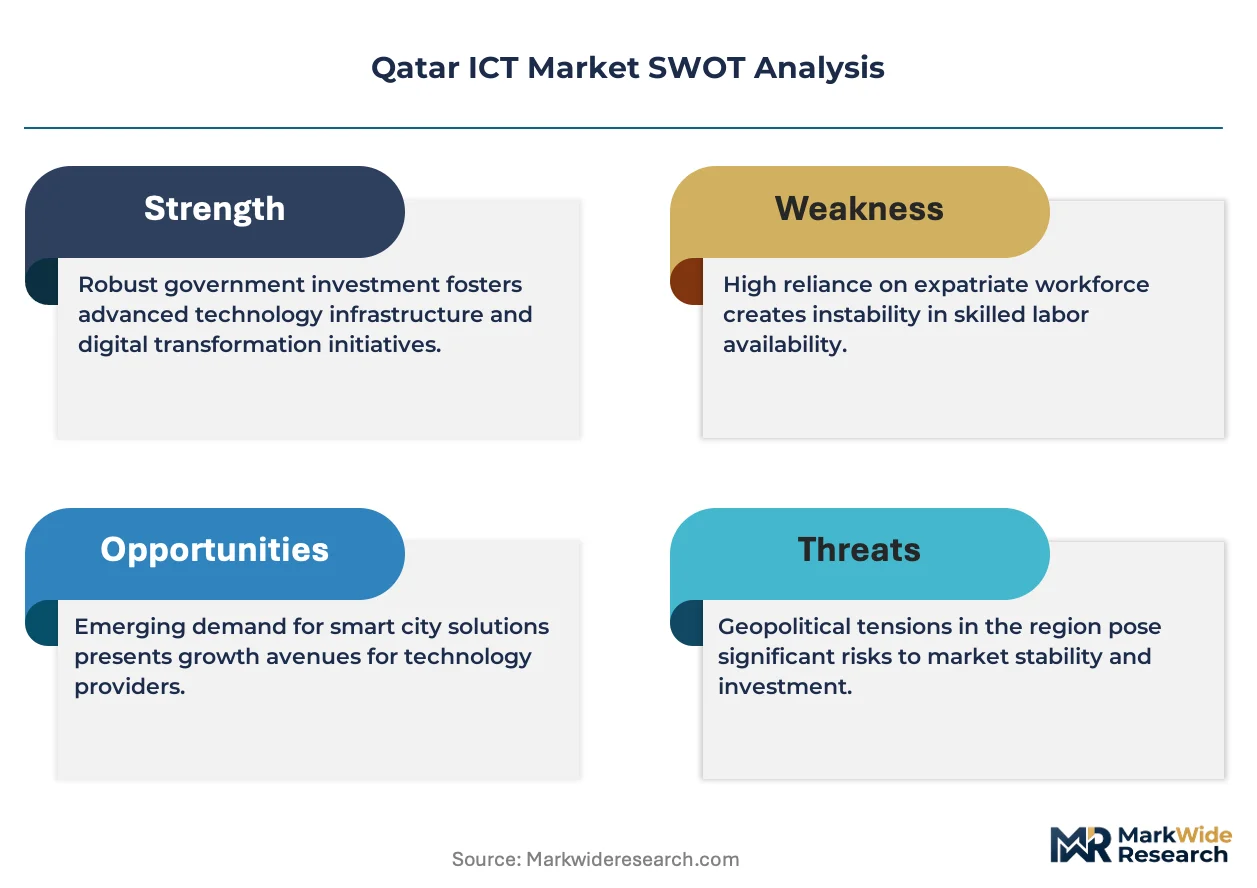
- Specialized Talent Scarcity:Domestic supply of cybersecurity architects and cloud engineers remains insufficient relative to project pipelines, inflating implementation costs.
- Vendor Concentration Risk:Submarine cable landing rights and fiber backbone ownership concentrate in limited carrier infrastructure, creating single-point-of-failure exposure.
- Legacy System Inertia:Hydrocarbon sector operators retain decades-old operational technology stacks that resist seamless cloud migration without operational disruption.
Strategic Opportunities
- Edge Computing Convergence:Integration of 5G base station infrastructure with distributed data centers enables sub-10 millisecond financial services workloads at Qatar Science & Technology Park.
- Managed Services Expansion:Hybrid cloud complexity is driving demand for outcome-based operational contracts that bundle monitoring, security, and optimization.
- AI Governance Frameworks:Forthcoming national regulations on algorithmic accountability will create first-mover advantages for compliant domestic service providers.
Industry Challenges
- Certification Timeline Compression:Qatar Central Bank's operational risk guidelines mandate accelerated business continuity architecture deployment that outpaces vendor qualification cycles.
- Multi-Vendor Integration Complexity:Enterprises navigating hybrid environments face interoperability failures between legacy on-premises systems and sovereign cloud platforms.
- Cybersecurity Skills Pipeline:Universities and technical institutes lack capacity to graduate sufficient network security specialists for financial and energy sector demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar ICT Market |
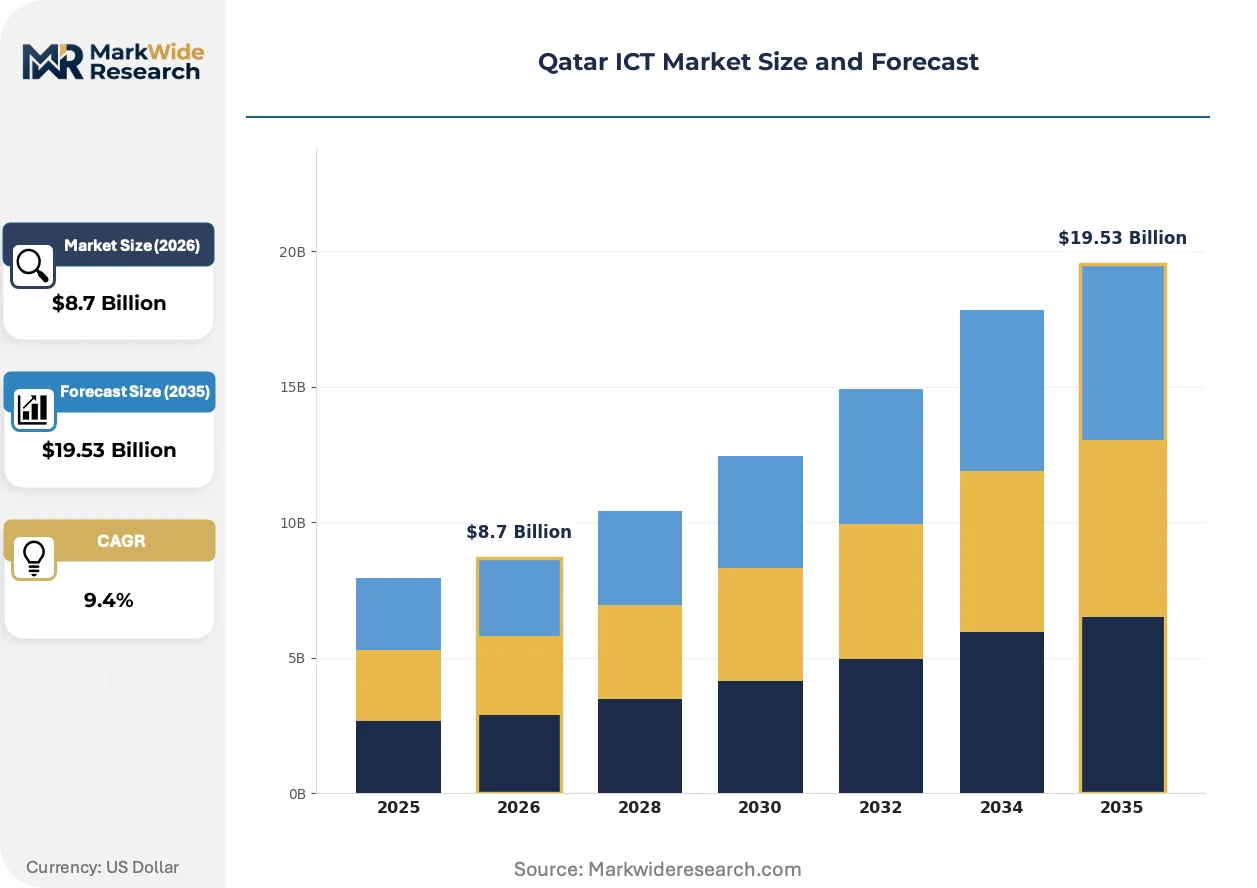
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Big Data, IoT, AI Service Type: Managed Services, Consulting, System Integration, Support Services Deployment: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud End User: SMEs, Large Enterprises, Government, Educational Institutions |
| Companies Covered | Amazon Web Services, Cisco Systems Inc., Ooredoo Q.P.S.C., SAP SE, Huawei Technologies Co., Ltd., Vodafone Qatar P.Q.S.C., Oracle Corporation, Infosys Limited, Microsoft Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar ICT Market Evolving Landscape
Sovereign cloud architectures are displacing conventional multi-tenant models as the default specification for Qatar's public sector procurement, with compliance now preceding performance in vendor evaluation criteria.
Hyperscale edge infrastructure is displacing centralized data center reliance among domestic banks and energy firms. QatarEnergy affiliates and Qatar Central Bank-regulated institutions are deploying micro data centers at branch and field locations to satisfy latency requirements. This topology is displacing traditional hub-and-spoke network designs that previously routed all traffic through Doha core facilities.
The National Cyber Security Agency's evolving data residency framework is mandating encryption standards that exceed baseline international certifications. Financial institutions must re-architect storage and processing workflows to satisfy these specifications. Domestic cloud service providers are responding by building dedicated government-community zones with hardware root-of-trust capabilities.
Enterprise buyers are consolidating vendor relationships to reduce operational complexity in multi-cloud environments. Qatar's largest state-owned entities are moving from best-of-breed point solutions to integrated platform contracts with single accountability. This concentration is most visible in the Lusail district, where smart city operators have awarded framework agreements spanning network, compute, and security layers to qualified system integrators.
Qatar ICT Market Segmentation
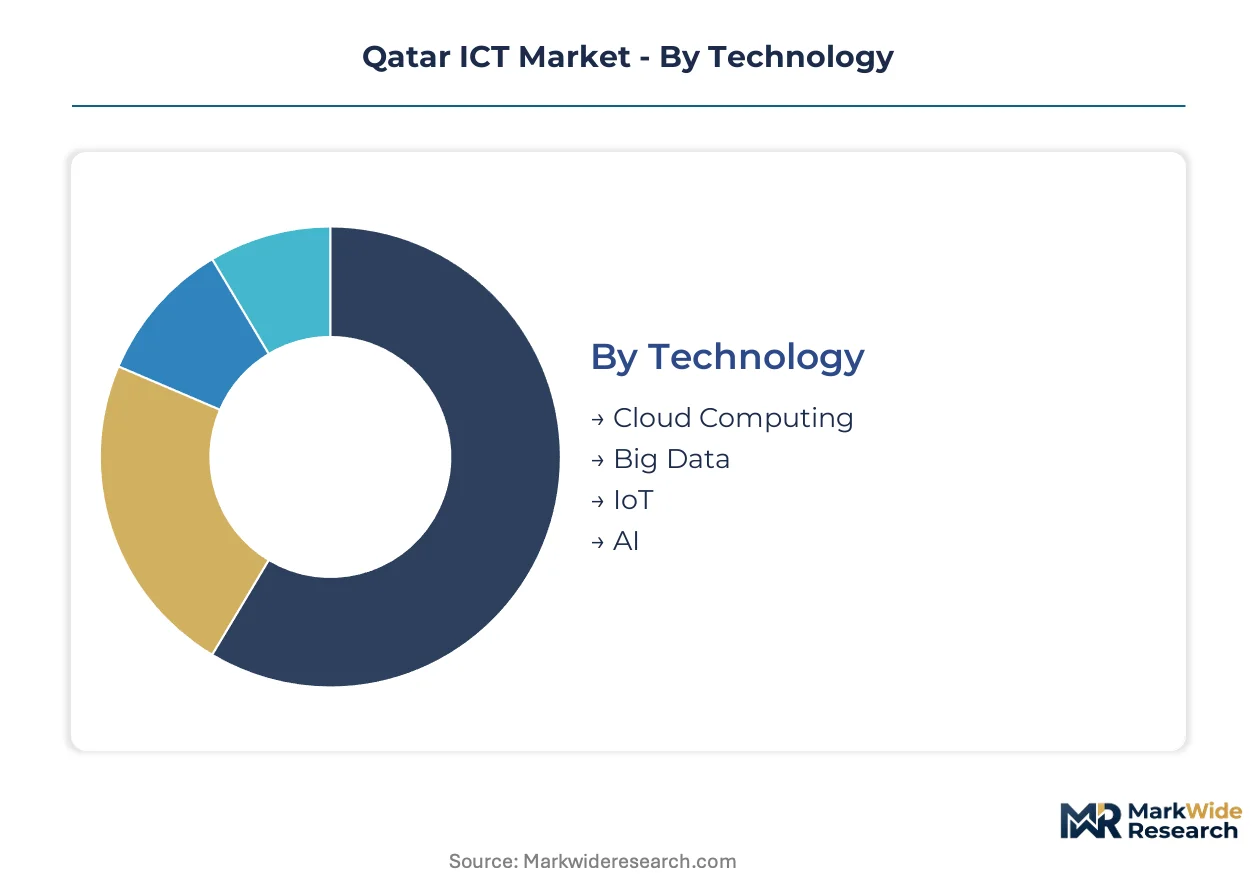
Qatar's ICT procurement patterns diverge sharply across technology maturity and buyer sophistication, with sovereign compliance requirements filtering vendor eligibility before commercial evaluation begins. Segment boundaries are hardening as the National Cyber Security Agency's data residency mandates reshape deployment architectures and service delivery models.
Technology:
Domestic demand concentrates in infrastructure layers that satisfy regulatory localization, while AI R&D partnerships at Qatar Science & Technology Park drive experimental adoption without immediate procurement scale.
- Cloud Computing:Sovereign cloud architectures with hardware root-of-trust capabilities anchor public sector tenders. QatarEnergy affiliates and ministry IT estates are retiring legacy on-premises infrastructure under National Cyber Security Agency migration timelines.
- AI:Applied research through Qatar Foundation partnerships consumes disproportionate investment relative to commercial deployment. Algorithmic accountability frameworks under development will determine vendor qualification criteria.
- Big Data:Analytics platforms process hydrocarbon sector operational data and financial services transaction flows. Latency requirements for real-time processing constrain architecture choices.
- IoT:Smart city sensor networks in Lusail district and industrial monitoring systems at Ras Laffan anchor deployment volume. 5G base station integration enables edge-ready connectivity.
Cloud Computing holds the largest share; momentum sits with AI as governance frameworks mature.
Service Type:
Margin structures favor recurring operational contracts over one-time implementation fees, with outcome-based pricing gaining traction among cost-conscious state-owned entities.
- Managed Services:Bundled monitoring, security, and optimization contracts capture premium pricing from hybrid cloud complexity. Qatar Central Bank-regulated institutions demand 24/7 operational accountability.
- System Integration:Multi-vendor interoperability projects for sovereign cloud migrations represent the steepest expansion trajectory. Implementation timelines compress under accelerated procurement mandates.
- Consulting:Advisory engagements focus on regulatory compliance architecture and business continuity planning. Cybersecurity skills scarcity inflates day rates.
- Support Services:Hardware maintenance and break-fix contracts retain steady demand from legacy estate operators. Tiered service level agreements align with criticality classifications.
System Integration commands the highest project values; recurring revenue expansion favors Managed Services.
Deployment:
Security certification tiers now precede performance benchmarks in vendor scoring, with air-gapped environments mandatory for specific government workloads.
- Private Cloud:Dedicated government-community zones with domestic data center residency satisfy National Cyber Security Agency encryption standards. QatarEnergy and Qatar Central Bank institutions mandate this architecture.
- Hybrid Cloud:Workload portability between on-premises estates and sovereign cloud platforms dominates enterprise planning. Interoperability failures between legacy and modern systems constrain adoption speed.
- Public Cloud:Limited to non-sensitive workloads without data residency constraints. International hyperscalers compete through local partnership structures.
- On-Premises:Declining footprint persists in hydrocarbon sector operational technology stacks resistant to cloud migration. Decades-old systems require custom integration approaches.
Private Cloud anchors regulated sector procurement; Hybrid Cloud gains share fastest among diversified enterprises.
End User:
Budget scale and compliance stringency segment buyer behavior, with centralized procurement frameworks consolidating vendor relationships across related entities.
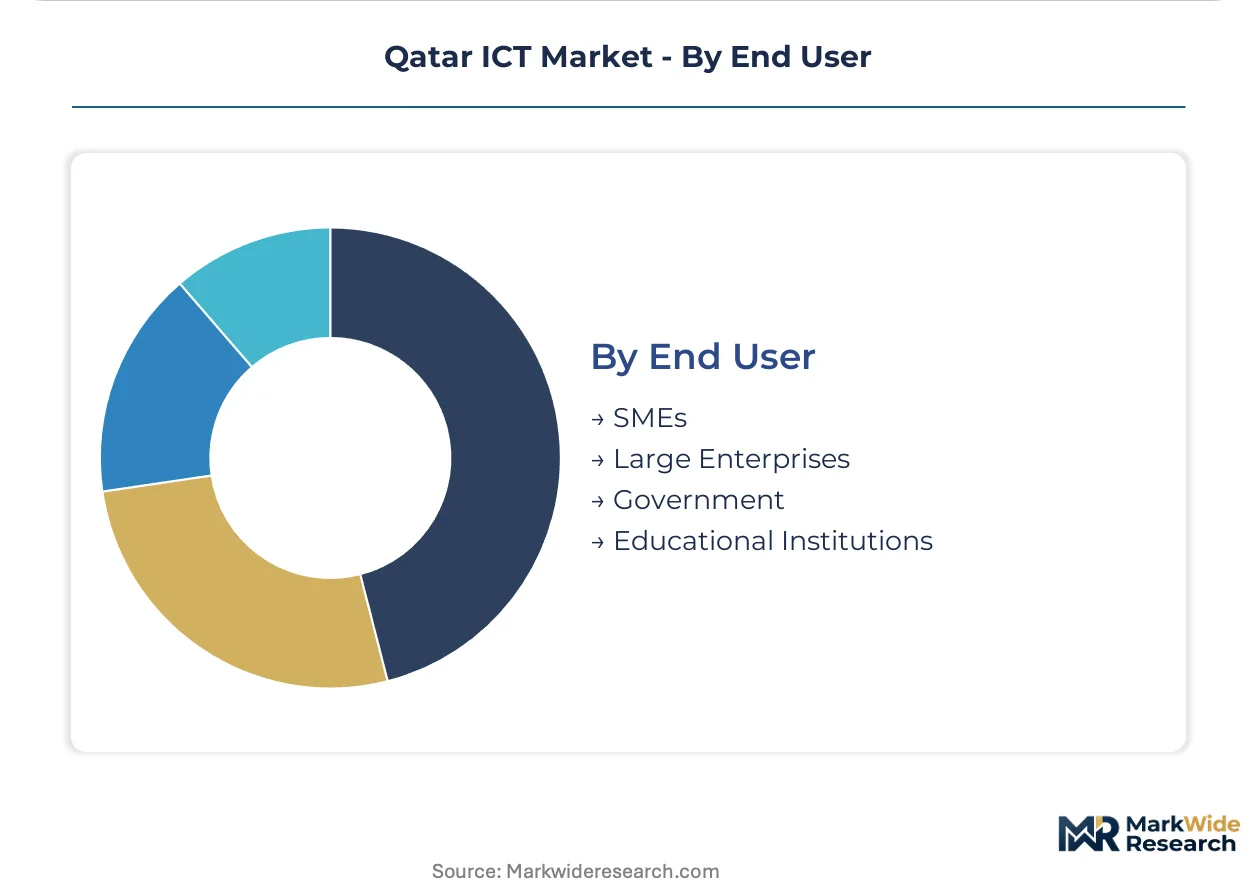
- Government:Ministry digitization targets under Qatar National Vision 2030 drive integrated platform tenders. Framework agreements span network, compute, and security layers to reduce operational complexity.
- Large Enterprises:QatarEnergy affiliates and financial institutions navigate multi-vendor environments with dedicated procurement functions. Business continuity architectures mandate redundant infrastructure.
- SMEs:Limited in-house technical capacity drives preference for packaged cloud solutions with embedded support. Price sensitivity constrains customization scope.
- Educational Institutions:Qatar Foundation entities and technical institutes anchor demand for research computing and student-facing platforms. AI lab partnerships create specialized requirements.
Government represents the deepest procurement pipeline; Large Enterprises show fastest contract value growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center capacity and submarine cable landing rights concentrate in Doha and its immediate metropolitan periphery, with Lusail smart city and Qatar Science & Technology Park anchoring national infrastructure investment.
Doha Metropolitan Area
Ministry digitization targets and QatarEnergy cloud migration mandates drive enterprise software procurement at scale. The National Cyber Security Agency enforces data residency standards that disqualify non-compliant vendors from public tenders. West Bay and the Diplomatic Area host carrier-neutral data center clusters serving financial institutions.
Lusail Smart City
Integrated platform contracts span network, compute, and security layers for municipal operators and real estate developers. Framework agreements with the Ministry of Transport and Communications accelerate smart city sensor deployment. The Entertainment City and Marina districts anchor edge computing infrastructure for sub-10 millisecond latency workloads.
Qatar Science & Technology Park
AI R&D partnerships with Qatar Foundation entities consume disproportionate investment relative to commercial deployment. Applied research labs collaborate with international hyperscalers on sovereign cloud architectures. The Education City corridor concentrates cybersecurity skills development programs addressing domestic talent scarcity.
Ras Laffan Industrial City
Hydrocarbon sector operators navigate legacy operational technology stacks resistant to seamless cloud migration. QatarEnergy affiliates mandate Tier III or Tier IV data center reliability standards for critical infrastructure. Industrial IoT monitoring systems at LNG facilities drive specialized system integration demand.
Al Wakrah and Southern Corridor
Logistics digitization for Hamad Port trade flows creates demand for trade finance platforms and customs automation. The Qatar Free Zones Authority incentivizes technology sector establishment through regulatory sandbox provisions. Mesaieed industrial area operators pilot private 5G networks for field operations connectivity.
Qatar ICT Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with international hyperscalers competing on cloud platform breadth against domestic carriers owning critical fiber and submarine cable infrastructure. The vendor base separates into three strategic tiers: sovereign-compliant system integrators, global platform providers operating through local partnerships, and specialized cybersecurity consultancies. Competitive moves concentrate on framework agreement capture for multi-year government contracts and strategic partnerships to satisfy data residency mandates.
Within the domestic carrier tier, Ooredoo Q.P.S.C. anchors infrastructure ownership through fiber backbone and landing rights. Among international platform providers, Microsoft Corporation and Amazon Web Services exemplify hyperscale cloud archetypes operating via local partnership structures to meet National Cyber Security Agency requirements. Cisco Systems Inc. represents the secure networking specialist archetype targeting critical infrastructure operators.
| Leading Market Players |
|---|
| Amazon Web Services |
| Cisco Systems Inc. |
| Ooredoo Q.P.S.C. |
| SAP SE |
| Huawei Technologies Co., Ltd. |
| Vodafone Qatar P.Q.S.C. |
| Oracle Corporation |
| Infosys Limited |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
Sovereign cloud mandates from Qatar's National Cyber Security Agency are displacing conventional multi-tenant hosting contracts, compressing procurement timelines while elevating compliance-certified domestic providers above price-competitive international hyperscalers in public sector tenders.
Pricing Analysis
The National Cyber Security Agency's data residency and encryption standards dictate the pricing tier structure across Qatar's ICT procurement landscape. Three-tier pricing separates sovereign-certified private cloud deployments from hybrid architectures and non-compliant public cloud alternatives. Price differentiation centers on certification grade and embedded security hardware rather than raw compute performance. Pricing pressure stems from compressed vendor qualification cycles that force accelerated compliance investment before revenue recognition. SMEs exhibit highest price sensitivity, while QatarEnergy affiliates and Qatar Central Bank-regulated institutions prioritize operational accountability over unit cost.
Supply Chain Analysis
Hardware lead times for Tier III and Tier IV data center equipment now stretch 18-24 weeks, constraining deployment velocity for Lusail smart city and Qatar Science & Technology Park projects. Supply concentrates in China, Taiwan, and South Korea for server-grade semiconductors and networking silicon. Component dependencies include specialized encryption hardware, liquid cooling systems, and fiber-optic transmission gear. Single-source vulnerability runs through submarine cable landing rights controlled by Ooredoo Q.P.S.C. and Vodafone Qatar P.Q.S.C. Distribution runs through carrier-neutral data center operators and system integrators holding framework agreements with the Ministry of Transport and Communications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's ICT sector is experiencing high-growth disruption as sovereign cloud mandates from the National Cyber Security Agency restructure competitive access and procurement economics.
For Market Incumbents: Compound defensive positioning through exclusive framework agreement capture with QatarEnergy and ministry procurement functions. Deepen sovereign cloud certification portfolios ahead of forthcoming AI governance frameworks. Acquire specialized cybersecurity talent through Qatar Foundation research partnerships to address domestic skills scarcity threatening implementation timelines.
For New Entrants and Emerging Players: Anchor in managed services and system integration white space where hybrid cloud complexity outpaces incumbent operational capacity. Target SME segment with packaged sovereign-compliant solutions embedding compliance overhead into standardized pricing. Pursue partnership structures with domestic carriers to satisfy data residency requirements without infrastructure ownership.
For Investors and Strategic Acquirers: Capital is best deployed toward sovereign-certified system integrators with established Qatar Central Bank and QatarEnergy relationships. Long-term viability hinges on compliance architecture depth rather than platform breadth. Watch for National Cyber Security Agency AI governance framework publication as signal for algorithmic accountability service demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Qualifies vendors for QatarEnergy and ministry procurement under National Cyber Security Agency mandates. |
| Edge Infrastructure Deployment | Enables sub-10 millisecond financial services workloads at Lusail Entertainment City and Marina districts. |
| Cybersecurity Talent Acquisition | Addresses implementation cost inflation from domestic cloud engineer and security architect scarcity. |
| AI Governance Compliance | Positions service providers for first-mover advantage under forthcoming national algorithmic accountability regulations. |
| Framework Agreement Consolidation | Reduces operational complexity for smart city operators through single-accountability platform contracts. |
Research Methodology
A spread of perspectives from cloud architects at QatarEnergy affiliates, procurement officers at Qatar Central Bank-regulated institutions, system integration specialists, National Cyber Security Agency policy leads, and Qatar Foundation research directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from listed technology vendors, hyperscaler capex disclosures, and Qatar government procurement registry data. Bottom-up project pipeline enumeration triangulated against top-down ICT spending forecasts from ministry budget disclosures.
Segmentation dimensions modeled include technology layer, service type, deployment architecture, and end-user category across the analysis window. Value projections reflect installed base depreciation schedules, cloud migration velocity assumptions, and sovereign compliance premium capture. CAGRs were derived from weighted average of historical procurement patterns and policy-mandated acceleration timelines. Industry-specific inputs include Qatar National Vision 2030 digitization targets and National Cyber Security Agency migration deadlines.
Material uncertainties — regulatory framework evolution, hydrocarbon sector capital allocation shifts, and submarine cable infrastructure disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
OSS/BSS Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Weather Information Technologies Market
Digital Solutions
Computer Aided Design (CAD) Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
AI Marketing Tool Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
IPTV Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Brazil Digital Twin Market