
 Global Tracking As a Service Market | 2026-2036
Global Tracking As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tracking As a Service Market Foresight
Subscription-based fleet telemetry is recalibrating what logistics buyers procure, shifting capital expenditure into recurring operational contracts. Zebra Technologies Corp. leverages its barcode-to-cloud integration to anchor enterprise warehouse tracking deployments. Trimble Inc. specializes in construction and agriculture sensor fusion, dominating field equipment monitoring across North American job sites. Geotab Inc. extends its open-platform API strategy to compete on third-party application compatibility rather than hardware margins alone.
Tracking as a Service denotes the delivery of location-aware monitoring capabilities through cloud-hosted platforms, combining GPS receivers, cellular modems, and edge analytics to stream positional and behavioral data without on-premise infrastructure ownership. The primary commercial purpose centers on converting fixed asset costs into variable operational expenditures while enabling real-time decision automation. Fleet Management services lead current revenue pools due to fuel optimization mandates and driver safety compliance, while Bluetooth Low Energy deployments within Inventory Control represent the fastest-expanding technology layer as retailers pursue sub-meter warehouse positioning. Cellular Networks sustain the dominant connectivity share, though Satellite-Based tracking captures margin concentration in remote agriculture and maritime applications where terrestrial coverage fails.
The United States EPA and NHTSA jointly shape demand through emissions monitoring and electronic logging device mandates that compel transport operators into certified telemetry subscriptions. Europe's GDPR and EU AI Act constrain how location data is processed, forcing providers to architect edge-anonymization and consent-management layers into platform design. Stakeholders must monitor evolving cross-border data sovereignty requirements as fleet operators internationalize and regulators fragment cloud residency rules.
Market Dynamics
Subscription telemetry is compressing fleet capital cycles as EPA emissions mandates in the United States and EU Green Deal logistics rules force operators off hardware ownership toward metered service contracts.
Growth Catalysts
- EPA Phase 3 Standards:United States transport operators face mandatory emissions monitoring that converts compliance spending into recurring telemetry subscriptions rather than capital equipment.
- Warehouse Robotics Integration:Bluetooth Low Energy positioning systems enable sub-meter inventory tracking as automated fulfillment centers demand real-time coordinate precision.
- Germany:KBA mandates on commercial fleet visibility under EU Green Deal compliance timelines accelerate real-time cargo monitoring adoption among logistics providers.
Market Restraints
- Cellular Modem Supply Concentration:Qualcomm and MediaTek dominate baseband chip fabrication, exposing platform providers to single-source vulnerability and input cost volatility.
- GDPR Edge-Processing Requirements:EU data residency rules force expensive local compute deployment, fragmenting cloud economics and raising operational friction.
- Satellite Connectivity Substitution:Starlink and Kuiper low-earth orbit networks threaten terrestrial cellular margins in remote agriculture and maritime segments.
Strategic Opportunities
- India:BIS certification pathways for IoT devices remain underpenetrated as domestic logistics digitization accelerates under PLI scheme incentives.
- Sensor Fusion Convergence:LiDAR and ultra-wideband integration with GPS is creating precision agriculture applications that command premium service tiers.
- Outcome-Based Insurance Models:Telematics data feeds enable usage-based underwriting that transforms fleet risk management from indemnity to prevention.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for edge analytics outpaces supply as automotive and logistics sectors compete for identical skill profiles.
- Legacy Fleet Integration:CAN bus protocol fragmentation across equipment vintages complicates retrofit telemetry deployment and extends implementation timelines.
- Cross-Border Data Sovereignty:Conflicting cloud residency requirements between United States CLOUD Act provisions and EU GDPR localization create architectural compliance complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tracking As a Service Market |
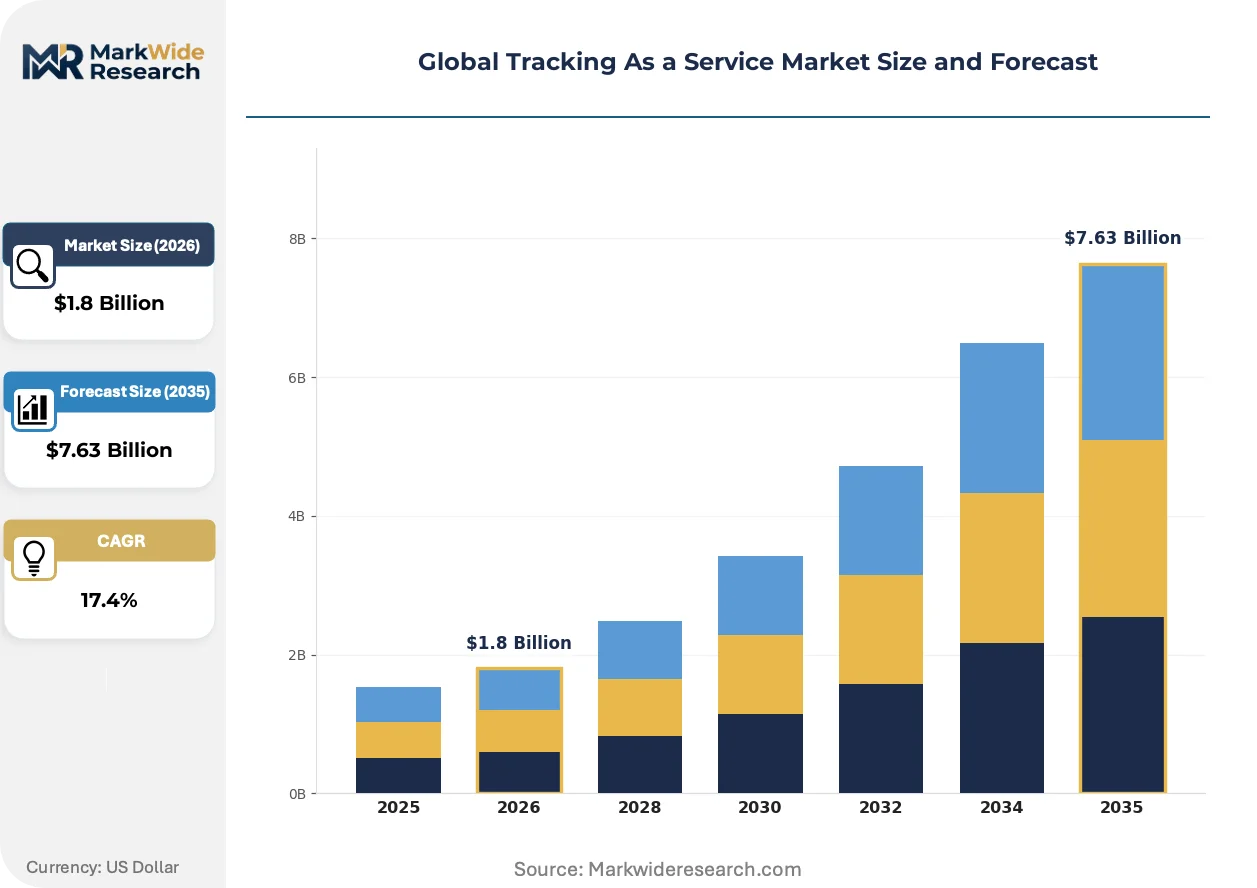
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.63 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fleet Management, Asset Tracking, Personal Tracking, Wildlife Tracking, Inventory Control Technology: GPS, RFID, Cellular Networks, Satellite-Based, Bluetooth Low Energy, Wi-Fi Application: Logistics, Construction Sites, Security Surveillance, Agriculture Monitoring, Field Services Customer Type: Transport Operators, Equipment Lessors, Event Organizers, Supply Chain Firms, Emergency Responders |
| Companies Covered | Zebra Technologies Corp., Trimble Inc., AT&T Inc., Verizon Communications, Motorola Solutions, Infor Inc., Geotab Inc., Rockwell Automation Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tracking As a Service Market Shifts & Advancements
Edge computing architectures are redistributing analytics workloads from centralized clouds toward vehicle-mounted processors, compressing latency and reshaping platform economics across fleet deployments.
Ultra-wideband positioning is decentralizing warehouse location intelligence by enabling centimeter-grade asset triangulation without infrastructure-heavy camera systems. Retail fulfillment operators in the United States and Germany are piloting battery-beacon networks that slash installation costs versus RFID ceiling grids. This topology shift is compressing the addressable market for traditional barcode-centric tracking hardware.
The EU AI Act's risk classification framework is forcing telemetry providers to embed algorithmic transparency layers into driver behavior scoring systems. European fleet operators must now maintain explainable decision trails for automated safety interventions. Germany's logistics sector faces the steepest compliance burden as KBA integrates these standards into commercial licensing audits.
Buyers are unbundling hardware from service contracts, demanding Bring Your Own Device compatibility that commoditizes modem margins and shifts value toward API extensibility. Fleet managers in the United States now procure tracking platforms through software marketplaces rather than direct OEM relationships. This channel migration is visible most acutely among mid-size logistics aggregators consolidating multi-vendor visibility through single-pane dashboards.
Global Tracking As a Service Market Segmentation
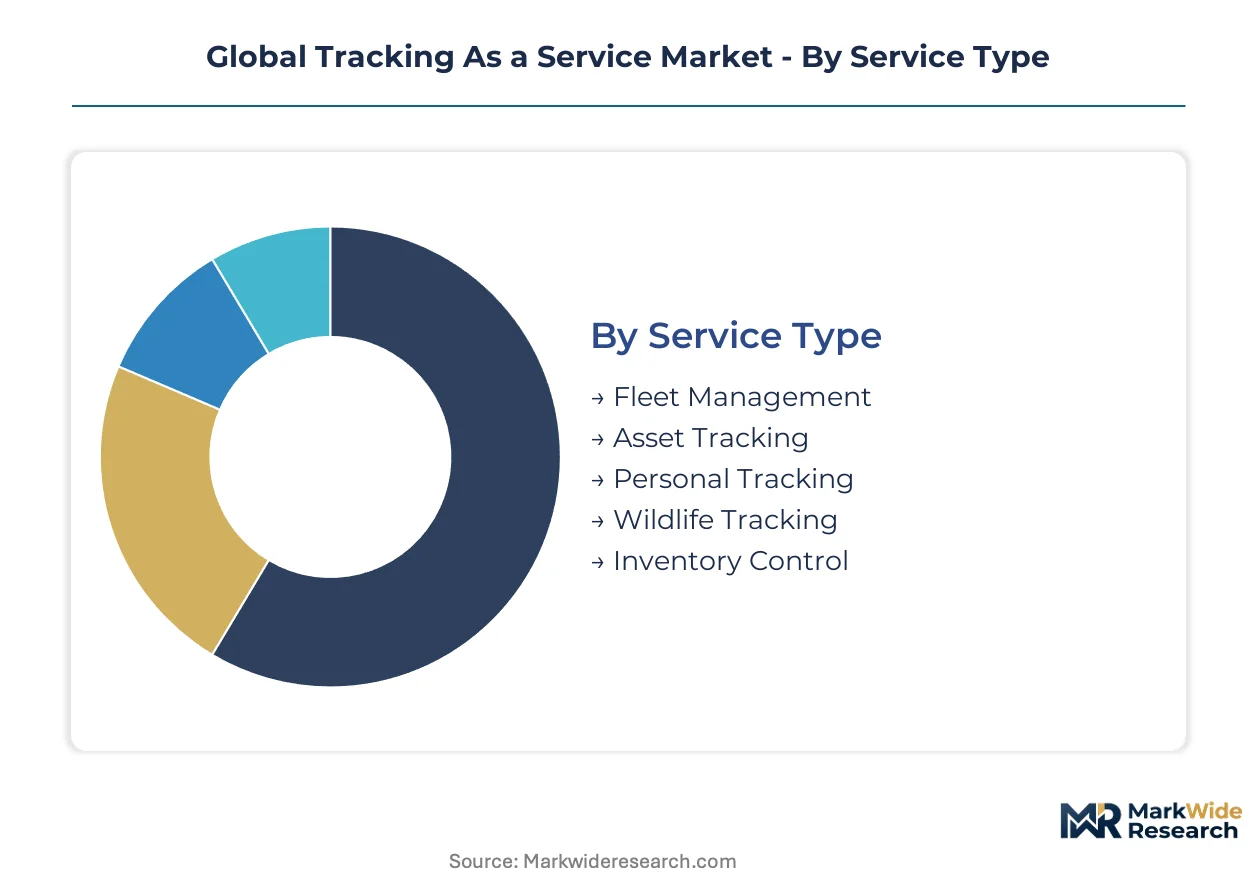
Tracking as a Service platforms segment across four dimensions that determine procurement economics and deployment architecture. Service type defines the core value proposition, while technology selection locks in connectivity cost structures and coverage constraints. Application context shapes regulatory exposure, and customer type dictates contract duration and integration complexity.
Service Type:
Supply concentrates in fleet telemetry as EPA mandates and EU Green Deal compliance convert capital expenditure into metered subscriptions.
- Fleet Management:Combines GPS receivers with cellular modems to stream vehicle location, fuel consumption, and driver behavior data. Demand concentrates among United States transport operators facing NHTSA electronic logging device mandates and EPA Phase 3 emissions monitoring requirements.
- Inventory Control:Deploys Bluetooth Low Energy beacons and ultra-wideband tags for sub-meter warehouse positioning without infrastructure-heavy camera systems. German logistics providers and United States retail fulfillment operators drive adoption as automated storage demands real-time coordinate precision.
- Asset Tracking:Monitors non-powered equipment through solar-assisted GPS units with multi-year battery life. Construction and agriculture lessors dominate procurement.
- Personal Tracking:Delivers consumer-grade location services through smartphone-integrated wearable devices. Elder care and lone worker safety applications anchor commercial demand.
- Wildlife Tracking:Satellite-collared biologgers transmit migration patterns and habitat utilization data. Research institutions and conservation agencies fund deployments.
Today's leader: Fleet Management. Tomorrow's challenger: Inventory Control.
Technology:
Cost tiers separate premium satellite connectivity from mass-market cellular deployments, with emerging short-range protocols compressing installation economics in controlled environments.
- Cellular Networks:LTE-M and NB-IoT modems dominate commercial fleet deployments through carrier-agnostic roaming agreements. Platform providers face Qualcomm and MediaTek baseband concentration risk.
- Satellite-Based:Iridium and Orbcomm constellations command premium pricing in maritime, agriculture, and remote infrastructure monitoring where terrestrial coverage fails. Starlink and Kuiper low-earth orbit networks threaten margin compression.
- Bluetooth Low Energy:Battery beacons enable centimeter-grade asset triangulation without RFID ceiling grids. Retail fulfillment pilots in Germany and the United States validate topology economics.
- GPS:Multi-constellation receivers integrating Galileo, GLONASS, and BeiDou enhance urban canyon accuracy. Standard inclusion in all service tiers.
- RFID:Passive and active radio-frequency identification persists in legacy warehouse management systems. Transitioning toward BLE substitution in greenfield deployments.
- Wi-Fi:Indoor positioning through access point triangulation serves campus and facility-scale deployments. Enterprise IT integration requirements limit standalone adoption.
Cellular Networks anchor current revenue. Bluetooth Low Energy gains share fastest in warehouse robotics integration.
Application:
Volume concentrates in logistics as freight digitization mandates real-time cargo visibility across multimodal networks.
- Logistics:End-to-end shipment monitoring through container-mounted telematics and trailer sensors. German KBA mandates and United States EPA rules compel subscription adoption among fleet operators.
- Agriculture Monitoring:Precision farming applications fuse GPS guidance with yield mapping and soil sensing. Remote field locations drive satellite connectivity preference.
- Construction Sites:Equipment utilization tracking and geofenced theft prevention for high-value machinery. Trimble dominates North American job site deployments.
- Field Services:Workforce dispatch optimization and proof-of-service documentation through mobile technician tracking. Service level agreement enforcement drives procurement.
- Security Surveillance:Perimeter monitoring and personnel safety applications in critical infrastructure protection. GDPR and EU AI Act constrain facial recognition integration.
Logistics commands current spend. Agriculture Monitoring climbs fastest on sensor fusion premium tier expansion.
Customer Type:
Margin profiles diverge sharply between long-term equipment lessor contracts and transactional event-based deployments.
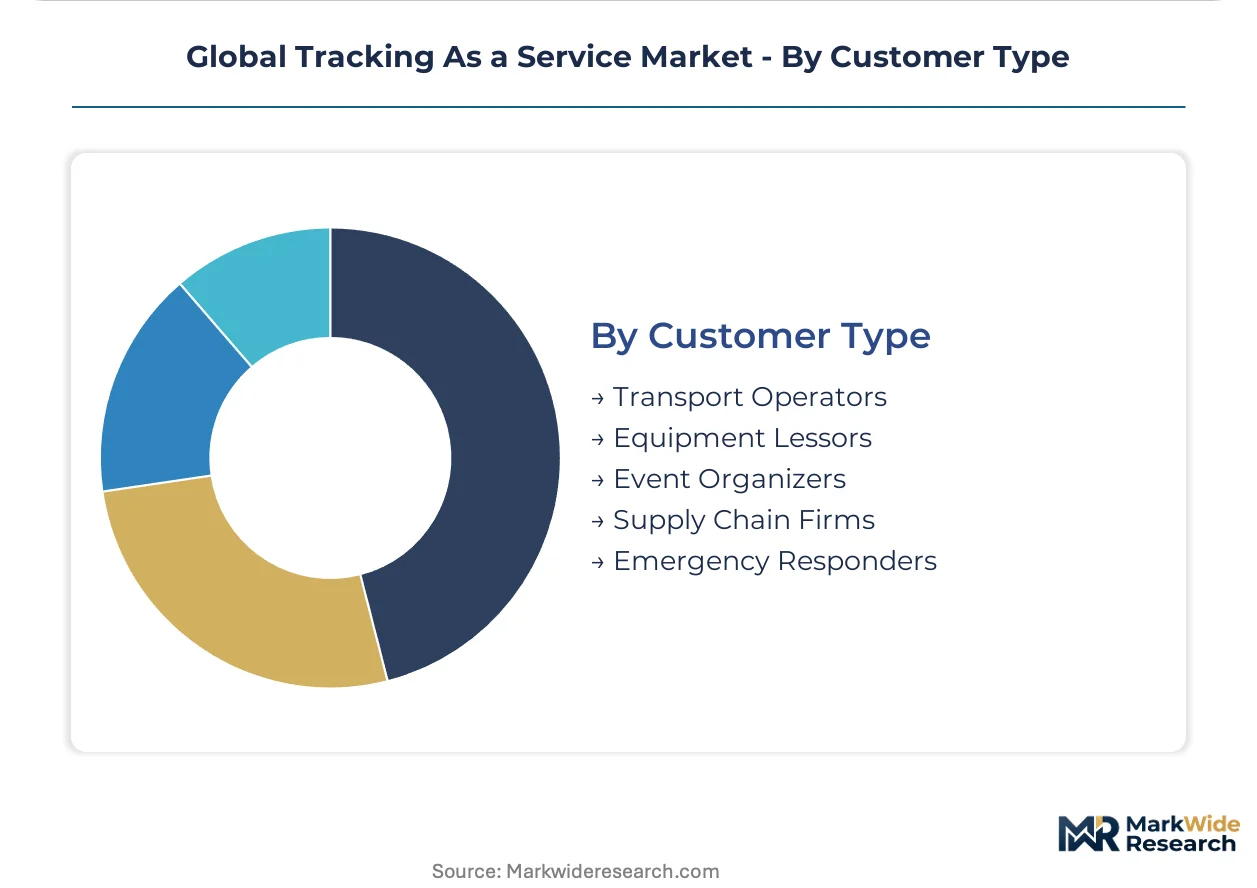
- Transport Operators:Long-haul trucking and last-mile delivery fleets under mandatory telemetry compliance. United States and Germany anchor contract value.
- Supply Chain Firms:Third-party logistics providers consolidating multi-vendor visibility through single-pane dashboards. API extensibility determines platform selection.
- Equipment Lessors:Construction and agriculture machinery rental companies monetizing utilization data. Outcome-based insurance models transform risk management.
- Emergency Responders:Public safety agencies requiring mission-critical location services with failover redundancy. Budget cycles extend procurement timelines.
- Event Organizers:Temporary workforce and asset tracking for festivals, sporting events, and exhibitions. Short-duration contracts compress customer lifetime value.
Transport Operators dominate contract value. Supply Chain Firms expand fastest through platform consolidation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's logistics sector commands stricter real-time cargo mandates than the United States, yet both markets dwarf India's emerging digitization wave in absolute contract value.
United States
EPA Phase 3 emissions standards and NHTSA electronic logging device rules compel long-haul operators into certified telemetry subscriptions. Fleet managers in the Midwest and Southeast consolidate multi-vendor visibility through single-pane dashboards. California's CARB regulations extend beyond federal baselines, accelerating zero-emission fleet tracking adoption in Los Angeles and Long Beach port corridors.
Germany
KBA commercial fleet visibility mandates under EU Green Deal compliance timelines drive real-time cargo monitoring adoption. Logistics providers in the Rhine-Ruhr and Hamburg port clusters demand sub-meter positioning precision for automated fulfillment. Berlin-Brandenburg's startup density spurs BLE beacon innovation for warehouse robotics integration.
India
PLI scheme incentives accelerate domestic logistics digitization as BIS certification pathways for IoT devices remain underpenetrated. Maharashtra and Gujarat's manufacturing belts anchor fleet operator demand for subscription-based asset monitoring. The Delhi-Mumbai Industrial Corridor drives construction equipment tracking procurement among infrastructure lessors.
China
Dual carbon goals and MIIT smart logistics directives reshape fleet procurement toward emissions-linked telemetry services. Yangtze River Delta logistics aggregators demand API-extensible platforms for multi-modal cargo visibility. Shenzhen's hardware ecosystem supplies cost-optimized modems compressing platform provider margins.
United Kingdom
DVSA compliance deadlines and urban low-emission zone expansion force transport operators into real-time vehicle monitoring. Midlands distribution hubs and London's last-mile delivery networks drive BLE warehouse positioning adoption. Post-Brexit customs complexity increases demand for cross-border shipment visibility among freight forwarders.
Global Tracking As a Service Market Competitive Landscape
Top-tier vendors anchor enterprise fleet telemetry, while mid-tier specialists compete on vertical-specific sensor fusion. The vendor base stratifies across three tiers: diversified technology conglomerates with barcode-to-cloud integration, pure-play telematics platforms with open API architectures, and industrial automation specialists with construction-agriculture field equipment dominance. Competitive moves center on strategic partnerships with cellular carriers and backward integration into edge computing hardware.
Within the diversified technology tier, Zebra Technologies Corp. and Honeywell International Inc. exemplify barcode-centric hardware vendors extending into cloud-hosted tracking services. Geotab Inc. occupies a position among pure-play telematics specialists competing through third-party application compatibility rather than captive modem margins. Trimble Inc. anchors the industrial specialization vector with field equipment monitoring expertise across North American job sites.
| Leading Market Players |
|---|
| Zebra Technologies Corp. |
| Trimble Inc. |
| AT&T Inc. |
| Verizon Communications |
| Motorola Solutions |
| Infor Inc. |
| Geotab Inc. |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
Cellular modem baseband chips from Qualcomm and MediaTek flow through Shenzhen assembly hubs into tiered subscription offerings, with hardware commoditization compressing margins at the economy tier while API extensibility commands premium pricing among supply chain firms consolidating multi-vendor visibility.
Pricing Analysis
Capacity additions in China's Shenzhen hardware ecosystem are reshaping price floors for cellular-enabled tracking devices, forcing platform providers toward software-centric revenue models. Three-tier pricing structure across premium, standard, and economy levels separates API-extensible fleet management suites from basic GPS-only subscriptions. Cost compression in the economy tier intensifies because Shenzhen modem suppliers compete on volume scale. Supply chain firms show least price sensitivity as they prioritize single-pane dashboard consolidation, while event organizers exhibit highest sensitivity due to short-duration contract economics.
Supply Chain Analysis
Freight costs from Taiwan semiconductor foundries and Shenzhen assembly clusters determine landed hardware economics for North American and European platform providers. Manufacturing concentrates in China, Taiwan, and Vietnam, with final assembly drawing from Malaysian electronics zones. Component sourcing rests on Qualcomm baseband processors, lithium battery cells, and multi-constellation GPS receivers. Single-source vulnerability in cellular modem fabrication creates supply chain risk. Distribution runs through carrier-direct channels and software marketplaces rather than traditional OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Tracking As a Service Market functions as a geographic-arbitrage play where India's underpenetrated BIS certification pathways offer cost-advantaged manufacturing against EU GDPR compliance burdens that inflate European platform operating costs.
For Market Incumbents: Acquire edge computing hardware capabilities to offset cellular modem margin erosion from Shenzhen cost competition. Defensive consolidation should prioritize backward integration into LiDAR and ultra-wideband sensor fusion for precision agriculture premium tiers. Starlink and Kuiper low-earth orbit networks threaten terrestrial cellular margins in remote segments, demanding satellite connectivity partnerships as counterpositioning. For New Entrants and Emerging Players: The premium-to-economy price-point gap in warehouse robotics integration offers white-space entry through Bluetooth Low Energy beacon networks. Target India's domestic logistics digitization under PLI scheme incentives as the most penetrable geography. Outcome-based insurance models for equipment lessors provide a differentiated go-to-market angle bypassing saturated fleet management competition. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware engineering talent scarcity fragments development capacity across automotive and logistics competitors. Long-term viability centers on platforms with captive API ecosystems and carrier-agnostic roaming agreements. Acquisition target archetype: pure-play telematics specialists with open-platform architectures. Watch Starlink maritime and agriculture penetration rates as inflection indicators for terrestrial cellular margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Integration | LiDAR and ultra-wideband convergence with GPS commands premium agriculture service tiers. |
| API Marketplace Expansion | Open-platform architectures attract third-party developers away from captive modem ecosystems. |
| Carrier Partnership Deepening | Roaming agreements with Verizon and AT&T secure connectivity coverage for cross-border fleets. |
| Edge Computing Deployment | Vehicle-mounted processors reduce latency for real-time driver behavior scoring under EU AI Act. |
| Satellite Connectivity Diversification | Iridium and Orbcomm partnerships defend margin concentration in remote agriculture and maritime. |
Research Methodology
Direct dialogue with fleet operations directors, telematics platform engineers, cellular carrier procurement leads, and logistics compliance officers grounded qualitative insights in operational reality. Secondary validation drew from NHTSA ELD mandate filings, EPA Phase 3 regulatory dockets, EU AI Act implementation guidance, and BIS certification pathway documentation. Bottom-up and top-down triangulation reconciled equipment shipment data with subscription revenue disclosures across the analysis window.
Bottom-up modeling built from individual country fleet penetration rates and service tier adoption curves, while top-down approaches cross-checked against logistics sector telemetry spending aggregates. Segmentation dimensions spanned service type, connectivity technology, application context, and customer archetype, with additional modeling of regulatory compliance intensity across jurisdictions. CAGRs derived from logistic curve fitting to subscription conversion patterns and hardware replacement cycles. Forecast inputs incorporated EPA enforcement timelines and EU Green Deal logistics rule implementation schedules.
Caveats apply where Starlink maritime coverage expansion or Qualcomm baseband supply disruption could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and cellular carrier roaming agreement stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Business As a Service Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
Data Governance Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Location As a Service Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Enterprise Mobility Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Component (Document) Content Management System Market