
 Fraud Detection Software Market | 2026-2036
Fraud Detection Software Market Size, Share, and Industry Trends Forecast 2026-2036
Fraud Detection Software Market Insights
Multi-source procurement of fraud detection capabilities is broadening as financial institutions reduce dependence on single-vendor stacks. Fiserv leverages its integrated payments ecosystem to embed risk scoring at the transaction layer. Feedzai specializes in machine-learning models tailored for real-time payment flows. IBM anchors enterprise-scale deployments with hybrid cloud infrastructure that spans on-premises and distributed environments.
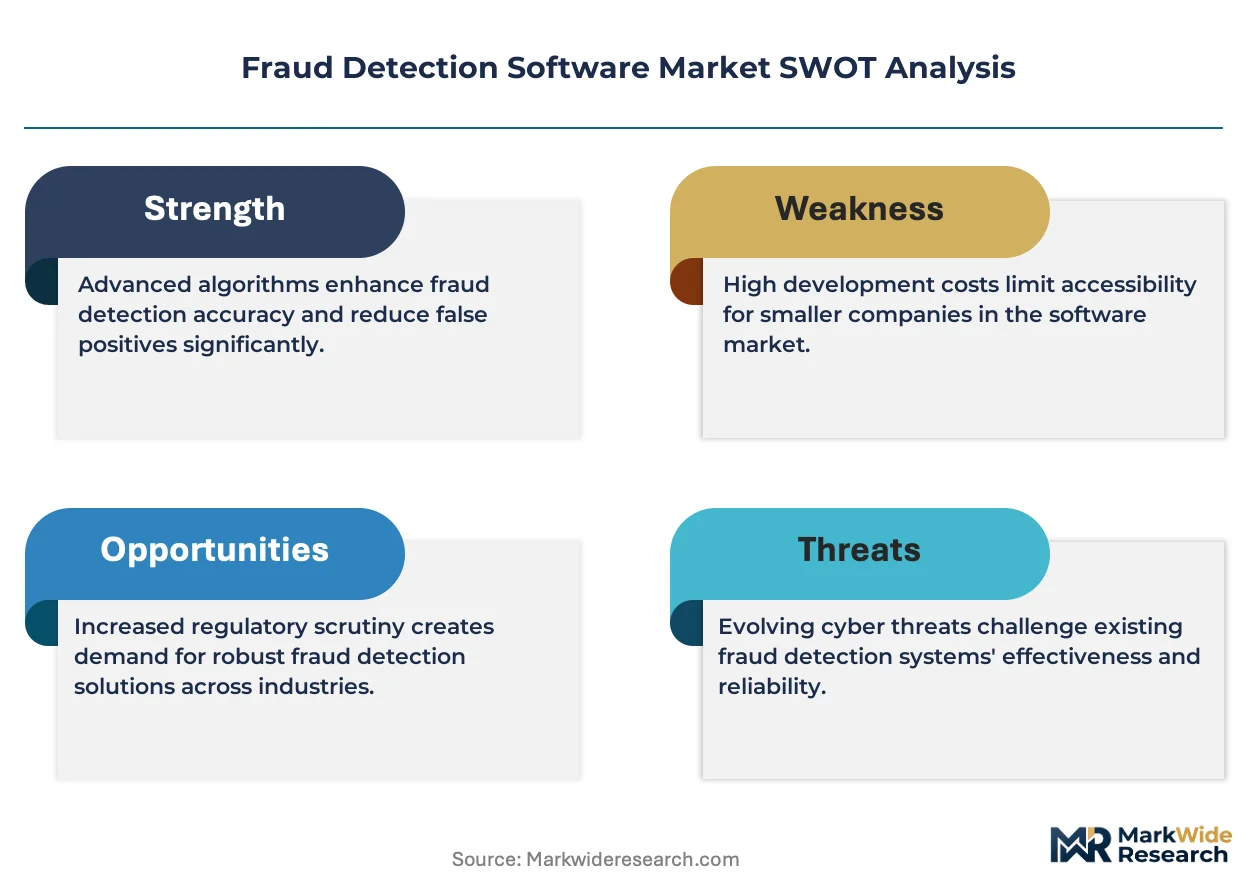
Fraud detection software encompasses algorithmic systems that analyze transactional data streams, behavioral biometrics, and identity signals to flag anomalous activity for intervention or blocking. These platforms process sub-second latency requirements, typically operating below 100 milliseconds per scoring decision to avoid checkout friction in high-velocity payment environments. Cloud-based deployment leads solution architecture as banks prioritize elastic compute for seasonal transaction spikes, while behavioral analytics and identity verification represent the fastest-expanding solution offerings as synthetic identity attacks proliferate. Transaction monitoring retains the largest installed base among use cases, though e-commerce fraud detection commands premium pricing due to merchant liability exposure.
The Federal Reserve's FedNow service guidelines and the EU's Digital Operational Resilience Act (DORA) impose real-time fraud prevention standards on payment infrastructure operators. The SEC's cybersecurity disclosure rules and state-level biometric privacy statutes in Illinois and Texas shape data handling requirements for behavioral analytics vendors. Stakeholders must weigh explainability mandates against model performance trade-offs as regulators intensify scrutiny of black-box scoring systems.
Market Dynamics
Real-time payment infrastructure expansion is compressing decision windows for fraud detection platforms, forcing algorithmic architectures toward sub-100 millisecond latency thresholds while explainability mandates from financial regulators add computational overhead.
Growth Catalysts
- FedNow service deployment:The Federal Reserve's instant payment rails mandate continuous transaction monitoring, driving United States banks toward embedded risk-scoring architectures.
- Behavioral biometrics adoption:Device fingerprinting and keystroke dynamics are displacing static authentication factors in e-commerce checkout flows.
- EU AI Act explainability requirements:European financial institutions must deploy interpretable machine-learning models for credit and fraud decisions, accelerating procurement of white-box scoring platforms.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for deep-learning fraud models depend on NVIDIA data-center chip availability, with pricing swings constraining mid-tier vendor R&D budgets.
- Cloud infrastructure concentration:Amazon Web Services, Microsoft Azure, and Google Cloud dominate elastic compute provisioning for transaction spikes, creating single-point-of-failure exposure for real-time scoring pipelines.
- Model drift maintenance burden:Synthetic identity attack patterns mutate faster than quarterly model retraining cycles, degrading detection accuracy between updates.
Strategic Opportunities
- Open banking API monetization:United Kingdom and Brazil regulatory frameworks mandate account data sharing, enabling fraud vendors to enrich scoring models with cash-flow visibility beyond transaction histories.
- Cross-channel identity graph convergence:Linking mobile device signals with browser sessions and call-center interactions is compressing false-positive rates for omnichannel merchants.
- Biometric privacy statute fragmentation:Illinois BIPA and Texas CUBI create compliance complexity that specialized legal-technology bundles can capture as premium service tiers.
Industry Challenges
- Adversarial machine-learning expertise scarcity:Defending against generative-AI-powered synthetic document attacks requires rare dual competencies in fraud pattern recognition and deep-learning architecture hardening.
- Core banking integration timelines:Legacy COBOL-based transaction engines at major United States banks impose 18-24 month certification cycles for new fraud detection modules, delaying revenue recognition for vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fraud Detection Software Market |
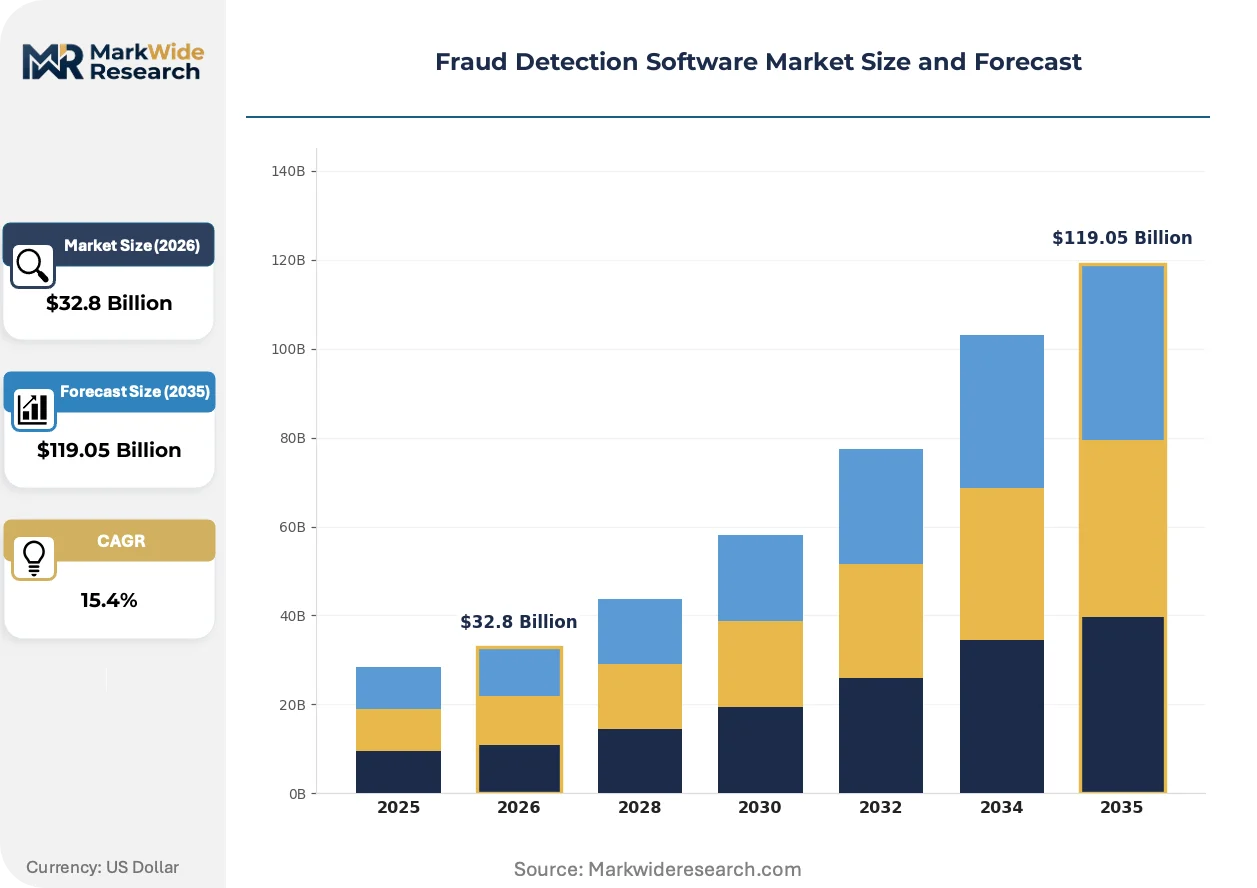
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $119.05 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge, API Integration Solution Offering: Transaction Monitoring, Identity Verification, Behavioral Analytics, Risk Scoring, Anomaly Detection Use Case: Payment Fraud, Insurance Claims Fraud, E-Commerce Fraud, Telecom Fraud, Identity Theft, Money Laundering End User: Banks, Insurance Firms, E-Commerce Merchants, Telecom Operators, Payment Gateways |
| Companies Covered | Fiserv, LexisNexis Risk Solutions, TransUnion, FIS Global, Experian, Feedzai, FICO, IBM, SAS Institute, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fraud Detection Software Market Trends and Innovations
Algorithmic decision architectures are converging with regulatory transparency mandates, compressing the trade-off space between model performance and explainability while distributed computing patterns reshape deployment economics.
Graph neural networks for identity resolution are consolidating disparate data silos into unified entity profiles. Large United States payment processors and digital-native banks are deploying these architectures for real-time link analysis across mule-account networks. The technology is consolidating vendor competitive positions around data integration depth rather than algorithmic sophistication alone.
The EU Digital Operational Resilience Act imposes strict incident-reporting timelines and third-party risk-management obligations on financial infrastructure operators. European banks must now maintain contractual audit rights over cloud-hosted fraud detection providers, shifting procurement toward vendors with EU-sovereign data residency options. Payment service providers in Germany and France are responding by negotiating dedicated instance deployments with hyperscale cloud operators.
Merchant liability exposure is compressing fraud tolerance thresholds for e-commerce platforms. Subscription-box retailers and digital-goods merchants are unbundling fraud protection from payment gateway contracts, procuring specialized scoring directly from machine-learning vendors. This pattern is most visible in the United States, where chargeback rates above 1% trigger card-network monitoring programs that threaten merchant account continuity.
Fraud Detection Software Market Segmentation
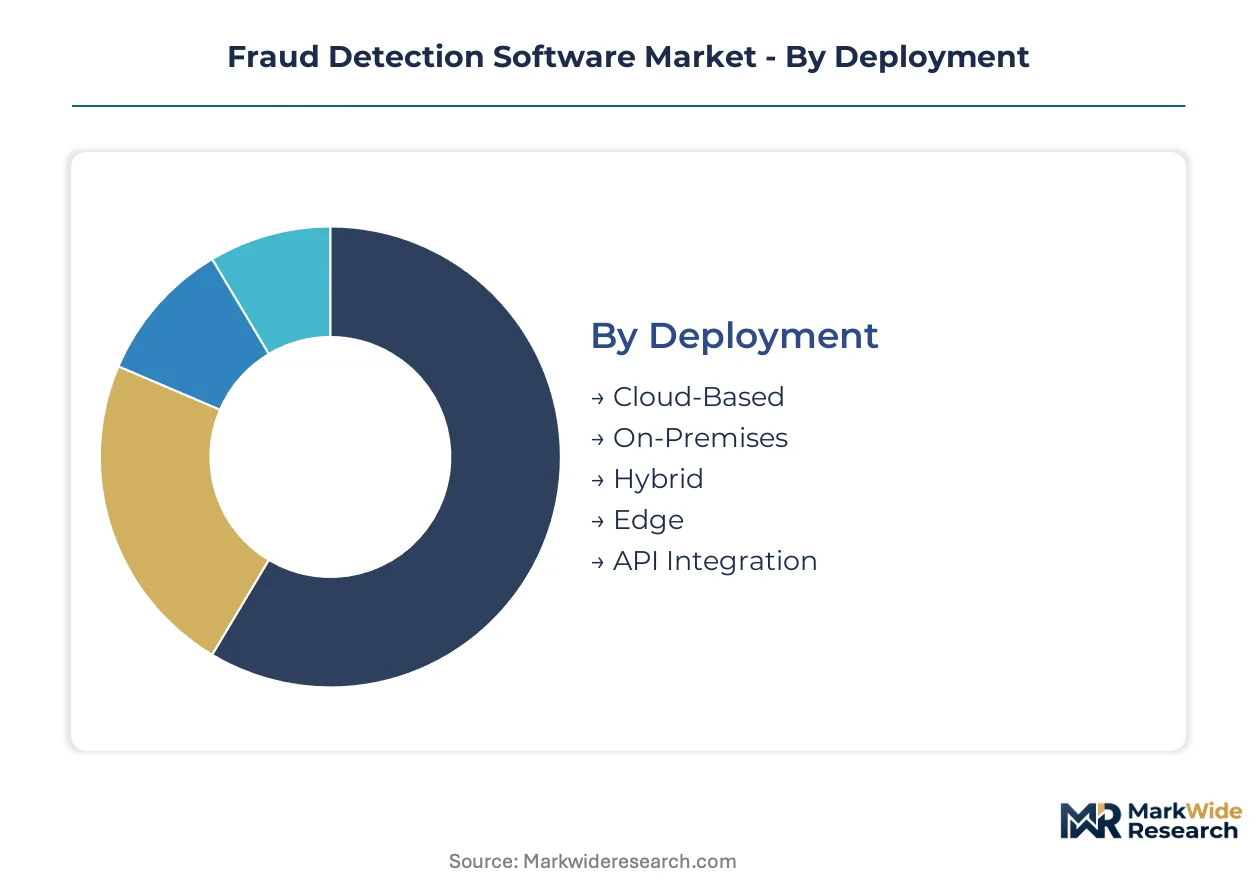
Segmentation in fraud detection software reveals how infrastructure choices, solution architectures, and industry-specific threat models create distinct procurement patterns. Deployment modality and solution type determine latency budgets and explainability requirements. End-user verticals impose divergent regulatory compliance burdens and integration timelines.
Deployment:
Cloud-native architectures dominate procurement for institutions prioritizing elastic transaction throughput and seasonal scaling.
- Cloud-Based:Hyperscale infrastructure delivers sub-100 millisecond scoring latency with automatic scaling for holiday transaction spikes. United States payment processors favor multi-region deployments to satisfy FedNow availability requirements while minimizing failover risk.
- On-Premises:Dedicated hardware installations serve institutions with sovereign data mandates or legacy core banking dependencies. German and French banks under DORA negotiate dedicated cloud instances that approximate on-premises control.
- Hybrid:Split architectures route real-time scoring through cloud edge nodes while retaining sensitive model training on private infrastructure.
- Edge:Distributed inference at point-of-sale terminals or mobile devices reduces round-trip latency for in-store and remote commerce.
- API Integration:Embedded risk-scoring modules plug directly into payment gateway workflows without standalone platform procurement.
Mature deployment sits with Cloud-Based configurations among digital-native banks. Newer deployment is concentrated in Edge architectures for omnichannel retail networks.
Solution Offering:
Functional modules compete for budget allocation based on attack vector prevalence and regulatory visibility requirements.
- Transaction Monitoring:Real-time analysis of payment flows against velocity thresholds and mule-account patterns. Banking institutions in the United States deploy these systems to satisfy FedNow continuous monitoring mandates.
- Identity Verification:Document authentication and biometric matching against government databases. E-commerce merchants procuring directly from machine-learning vendors drive fastest expansion as synthetic identity attacks proliferate.
- Behavioral Analytics:Keystroke dynamics, device fingerprinting, and session behavior profiling displace static passwords.
- Risk Scoring:Composite probability calculations combining multiple signal streams into actionable thresholds.
- Anomaly Detection:Unsupervised pattern recognition flagging deviations from established behavioral baselines.
Transaction Monitoring commands the largest installed base among incumbent banks. Identity Verification represents the fastest-growing trajectory as merchants unbundle fraud protection from gateway contracts.
Use Case:
Threat-specific applications command pricing premiums proportional to liability exposure and regulatory scrutiny intensity.
- Payment Fraud:Authorization-time blocking of stolen credentials and card-not-present abuse. United States card networks impose monitoring programs when merchant chargeback rates exceed 1%, compressing tolerance thresholds.
- E-Commerce Fraud:Checkout-flow protection for digital goods and subscription services where physical delivery verification is absent.
- Insurance Claims Fraud:Pattern analysis across repair estimates, medical billing, and claimant history for property and casualty carriers.
- Telecom Fraud:Subscription abuse, SIM swap detection, and international revenue share fraud prevention.
- Identity Theft:Account takeover prevention through device and behavioral signal correlation.
- Money Laundering:Suspicious activity reporting workflows integrating with correspondent banking compliance.
Payment Fraud solutions anchor vendor revenue through banking procurement cycles. E-Commerce Fraud applications are climbing the fastest as merchant liability frameworks tighten.
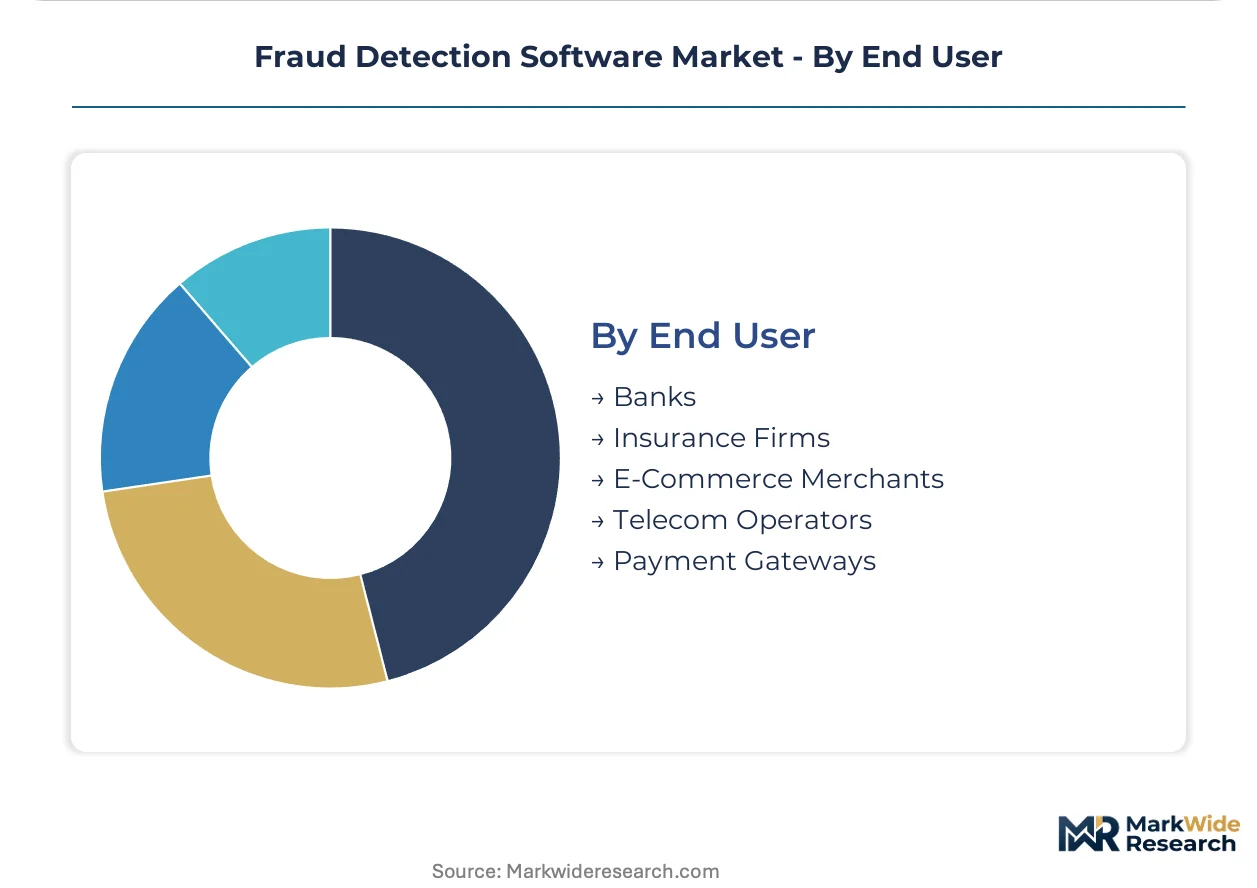
End User:
Vertical-specific compliance mandates and integration complexity create divergent vendor selection criteria and contract structures.
- Banks:Core system integration demands dominate procurement, with 18-24 month certification cycles for COBOL-based transaction engines at major United States institutions. FedNow and DORA compliance accelerate real-time architecture investments.
- Payment Gateways:Embedded risk-scoring as a competitive differentiator drives vertical integration into proprietary fraud stacks.
- Insurance Firms:Claims workflow integration and regulator reporting requirements shape solution specifications.
- E-Commerce Merchants:Direct procurement from specialized vendors bypasses gateway bundles as chargeback exposure intensifies.
- Telecom Operators:Subscriber lifecycle management integration with SIM provisioning and billing systems.
Banks maintain the longest solution tenure and highest switching costs. E-Commerce Merchants demonstrate the steepest expansion trajectory in direct vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States banking institutions and payment processors concentrate procurement of real-time fraud detection systems, with regulatory mandates across multiple jurisdictions accelerating vendor selection timelines. Geographic demand patterns reflect divergent compliance frameworks and infrastructure maturity levels.
United States
FedNow instant payment rails and SEC cybersecurity disclosure rules compress deployment windows for sub-100 millisecond scoring architectures. Large payment processors in New York and Chicago negotiate multi-region cloud deployments to satisfy availability requirements. Digital-native banks in San Francisco and Seattle procure directly from machine-learning vendors to bypass legacy core banking dependencies.
Germany
DORA mandates strict third-party risk-management obligations and contractual audit rights over cloud-hosted providers. Frankfurt-based banking consortia negotiate dedicated EU-sovereign data residency instances with hyperscale operators. Bavarian payment service providers deploy hybrid architectures routing real-time scoring through edge nodes while retaining sensitive model training on private infrastructure.
United Kingdom
Open banking API frameworks mandate account data sharing, enabling scoring model enrichment with cash-flow visibility beyond transaction histories. London fintech clusters procure behavioral analytics modules to address synthetic identity attack proliferation. Regulatory pressure from the Financial Conduct Authority accelerates explainable model procurement timelines.
France
CNIL guidance on biometric data handling shapes behavioral analytics vendor selection criteria for Paris-based retail banks. The EU AI Act drives procurement of interpretable machine-learning platforms for credit and fraud decisions. Lyon and Marseille payment processors concentrate on cross-channel identity graph convergence linking mobile signals with browser sessions.
Brazil
Central bank open banking regulations create data-sharing obligations that fraud vendors leverage for model enrichment. São Paulo digital payment platforms unbundle fraud protection from gateway contracts as merchant liability exposure intensifies. Rio de Janeiro insurance carriers deploy claims pattern analysis across repair estimates and medical billing workflows.
Fraud Detection Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors position for FedNow and DORA compliance mandates. The vendor base stratifies across three tiers: integrated payments ecosystems, specialized machine-learning platforms, and enterprise-scale hybrid cloud providers. Two archetypes define competitive positioning — embedded risk-scoring specialists and explainable model platforms — while M&A activity and geographic expansion represent the dominant competitive moves.
Within the integrated payments tier, Fiserv anchors embedded risk-scoring at the transaction layer. Feedzai occupies a position exemplifying real-time payment flow specialization. IBM represents enterprise-scale hybrid cloud deployment across on-premises and distributed environments. These three entities collectively illustrate how competitive positioning converges around data integration depth rather than algorithmic sophistication alone.
| Leading Market Players |
|---|
| Fiserv |
| LexisNexis Risk Solutions |
| TransUnion |
| FIS Global |
| Experian |
| Feedzai |
| FICO |
| IBM |
| SAS Institute |
| Others |
Pricing and Supply Chain Analysis
GPU compute costs for deep-learning model training cascade through SaaS subscription tiers, compressing margins for mid-tier vendors while hyperscale cloud providers absorb volatility through volume commitments from United States payment processors.
Pricing Analysis
Volume-based SaaS tiers separate enterprise deployments with dedicated model training infrastructure from mid-market per-transaction scoring and entry-level API bundles with shared inference clusters. Price differentiation hinges on explainability certification grade and FedNow compliance audit rights, with European institutions paying premiums for EU-sovereign data residency. Pricing pressure stems from NVIDIA data-center chip availability constraints, forcing mid-tier vendors toward CPU-based architectures. E-commerce merchants demonstrate highest price sensitivity due to thin digital-goods margins, while Tier 1 banks accept premium positioning for sub-100 millisecond latency guarantees.
Supply Chain Analysis
Regional distribution centers for edge inference hardware concentrate in Germany, Singapore, and the United States to satisfy DORA availability mandates and FedNow failover requirements. The supply chain draws from Taiwan for GPU fabrication, South Korea for high-bandwidth memory modules, and Ireland for EU data-sovereign cloud infrastructure. Single-source vulnerability sits with NVIDIA's dominant position in training accelerators, exposing vendors to allocation rationing during supply crunches. Distribution runs through hyperscale cloud marketplaces and direct OEM relationships with banking infrastructure consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adversarial machine-learning expertise scarcity props pricing for qualified engineering teams, constraining vendor expansion velocity and sustaining incumbent margins despite competitive pressure from cloud-native entrants.
For Market Incumbents: To counter generative-AI-powered synthetic document attacks, anchor defensive positioning through backward integration into behavioral biometrics data streams and captive development of white-box model architectures that satisfy EU AI Act explainability mandates without performance degradation. For New Entrants and Emerging Players: EU AI Act in Europe opens a window for interpretable machine-learning platforms that bypass black-box regulatory barriers, with German and French payment service providers representing the most penetrable buyer segment for dedicated instance deployments with contractual audit rights. For Investors and Strategic Acquirers: FedNow service deployment acceleration is the leading indicator that real-time scoring infrastructure demand will sustain elevated valuations, positioning acquisition targets with sub-100 millisecond latency architectures and existing banking certifications as the preferred archetype for portfolio exposure across the medium-term horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding risk scoring at the transaction layer reduces checkout friction for FedNow compliance. |
| Geographic Expansion | EU-sovereign data residency instances capture DORA-mandated procurement from Frankfurt banking consortia. |
| Strategic Partnership | Hyperscale cloud alliances secure GPU allocation priority for deep-learning model training workloads. |
| Acquisition of Specialist Firm | Behavioral biometrics targets compress false-positive rates for omnichannel merchant deployments. |
| Product Launch | White-box scoring platforms address EU AI Act interpretability requirements without latency penalties. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across CTOs at digital-native banks, fraud operations leads at payment processors, regulatory compliance officers, and machine-learning platform engineers. SEC cybersecurity disclosures, FedNow service guidelines, EU AI Act implementation documents, and cloud infrastructure capex reports supplied quantitative anchors. Bottom-up transaction volume estimates triangulated against top-down banking IT spend allocations.
Granularity-level modeling deployed deployment modality, solution type, end-user vertical, and regional regulatory cluster as primary segmentation dimensions across the analysis window. CAGRs derived from curve-fitting historical procurement cycles against regulatory mandate effective dates, with synthetic identity attack frequency and chargeback rate thresholds as industry-specific demand drivers.
Caveats apply where adversarial machine-learning capability gaps or core banking integration timeline slippage could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Mobile Security Market
Security Software
Identity and Access Management (IAM) Market
Security Software
Disk Encryption Software Market
Security Software
Internet Filter Software Market
Security Software
Global Anti-Spam Software Market
Security Software
Secure Web Gateway Market
Security Software
Devsecops Market
Security Software
Single Sign-On Market
Security Software
Global Secure Mobile Communications Software Market
Security Software
Hardware Encryption Market
Security Software
Identity Governance and Administration Market
Security Software
Messaging Security Market
Security Software
Global Background Check Software Market
Security Software
Sound Masking Systems Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Data Masking Technology Market