
 Chile ICT Market | 2026-2036
Chile ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Chile ICT Market Outlook
A shortage of cloud architects and AI specialists is reorganizing how technology vendors allocate resources across Chile. Microsoft Corporation leverages its Azure training partnerships with Chilean universities to build local deployment capacity. Entel S.A. anchors the telecommunications backbone through its nationwide fiber expansion. Huawei Technologies competes aggressively in 5G infrastructure tenders despite geopolitical scrutiny.
Information and communications technology in Chile encompasses digital infrastructure, software platforms, and data services operating across fixed and wireless networks with latency thresholds below 20 milliseconds for enterprise-grade applications. The primary purpose centers on enabling real-time transaction processing, remote operations, and predictive analytics for resource-intensive industries. Cloud Computing services capture the dominant margin pool as enterprises migrate legacy workloads, while Cybersecurity demand accelerates fastest among Banking and Retail verticals facing escalating threat environments. Artificial Intelligence applications within Data Analytics are gaining traction as mining and logistics operators pursue operational optimization.
Subtel, Chile's telecommunications regulator, enforces spectrum allocation and net-neutrality frameworks that directly shape infrastructure investment timelines and service pricing structures. The National AI Strategy coordinates standards-setting across public agencies, creating compliance obligations for government contractors. BIS-aligned technical standards for data-center equipment imports add certification layers for hardware suppliers. Stakeholders must monitor how forthcoming spectrum auctions and cross-border data-flow regulations reshape competitive positioning in enterprise segments.
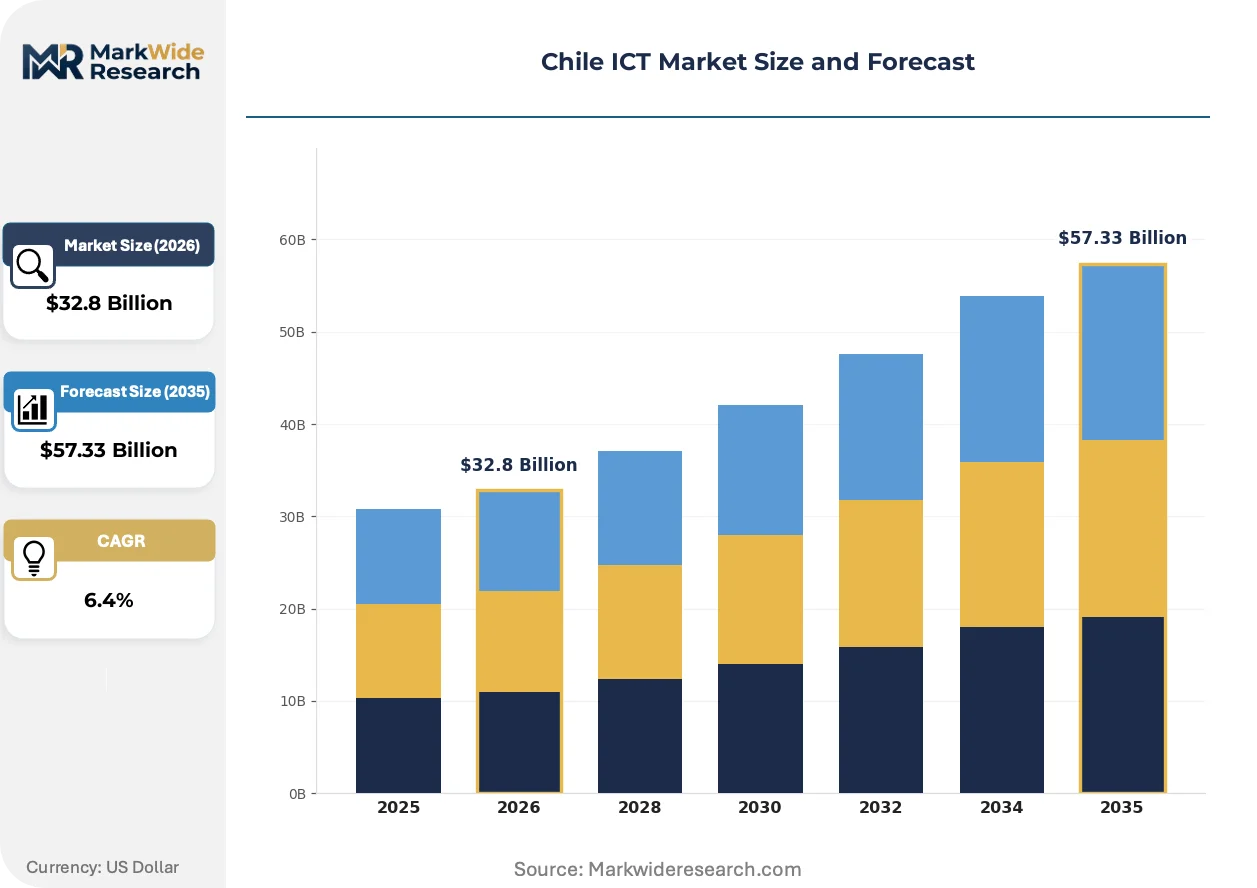
Market Dynamics
Chilean mining conglomerates are accelerating digital transformation investments, creating concentrated demand for low-latency edge computing infrastructure across the Atacama Desert operations belt. This industrial pull is reorganizing how technology vendors allocate technical resources and certification efforts toward resource extraction corridors.
Growth Catalysts
- Subtel spectrum frameworks:The regulator's 5G auction timelines and net-neutrality enforcement are compressing infrastructure deployment cycles for mobile network operators serving enterprise zones.
- Mining operational technology:Autonomous haulage systems and predictive maintenance platforms are generating sustained procurement of private wireless networks and industrial IoT sensors.
- Santiago technology corridor concentration:Data center clustering in Quilicura and Cerrillos municipalities is attracting hyperscale cloud providers to establish local availability zones.
Market Restraints
- Specialized labor scarcity:Cloud architecture and machine learning engineering talent shortages are inflating implementation timelines for enterprise digitalization programs.
- Hardware import certification:BIS-aligned technical standards for data center equipment are adding compliance layers and customs clearance friction for server and networking gear.
- Copper price volatility:Mining sector IT budgets correlate with commodity cycles, creating demand unpredictability for technology vendors dependent on extractive industry procurement.
Strategic Opportunities
- Antofagasta region underpenetration:Remote mining installations outside metropolitan fiber routes present white space for satellite-backhauled edge computing deployments.
- National AI Strategy compliance:Government contractor obligations for algorithmic transparency standards are creating mandatory upgrade cycles for public sector IT systems.
- Cybersecurity-5G convergence:Integration of zero-trust architectures with private cellular networks offers differentiated positioning for systems integrators serving critical infrastructure operators.
Industry Challenges
- Legacy system integration complexity:Mining operators' decades-old SCADA environments resist seamless cloud migration, requiring costly middleware development and operational downtime.
- Cross-border data flow uncertainty:Pending regulations on information localization are forcing architecture redesigns for multinational enterprises with regional shared services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile ICT Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Computing, Cybersecurity, Data Analytics, Software Development Industry Vertical: Telecommunications, Banking, Retail, Education Technology: 5G, Artificial Intelligence, IoT, Blockchain End User: SMEs, Large Enterprises, Government, Non-Profits |
| Companies Covered | IBM, Huawei Technologies, Microsoft Corporation, Telefónica Chile, Entel S.A., Amazon Web Services, Oracle, Cisco Systems, Google, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile ICT Market Strategic Shifts
Edge computing infrastructure is migrating from pilot deployments to production scale across Chile's northern mining districts, compressing the historical dominance of centralized cloud architectures. This shift reflects pressure for sub-20 millisecond latency in autonomous equipment control and real-time ore processing optimization.
Private 5G networks are displacing Wi-Fi and legacy LTE installations at open-pit copper operations. Antofagasta Minerals and Codelco are deploying dedicated spectrum slices for autonomous truck fleets and drone-based surveying. This infrastructure is displacing traditional leased-line connectivity models and forcing telecommunications vendors to restructure enterprise service portfolios around spectrum-as-a-service offerings.
Subtel's forthcoming mmWave spectrum allocations are tightening equipment certification timelines for base station suppliers. The regulator's technical mandates for rural coverage obligations are redirecting infrastructure investment toward underserved provinces outside Santiago. Mining operators in the Tarapacá region face accelerated compliance deadlines for transitioning emergency communications systems to 5G-native architectures.
Enterprise procurement of information technology is consolidating through framework agreements with systems integrators rather than direct vendor relationships. Chilean retail and banking verticals are unbundling hardware acquisition from managed services, shifting risk to outsourcing partners. This pattern is most pronounced in Santiago's financial district, where Banco de Chile and Banco Santander Chile have restructured supplier panels around outcome-based performance metrics.
Chile ICT Market Segmentation
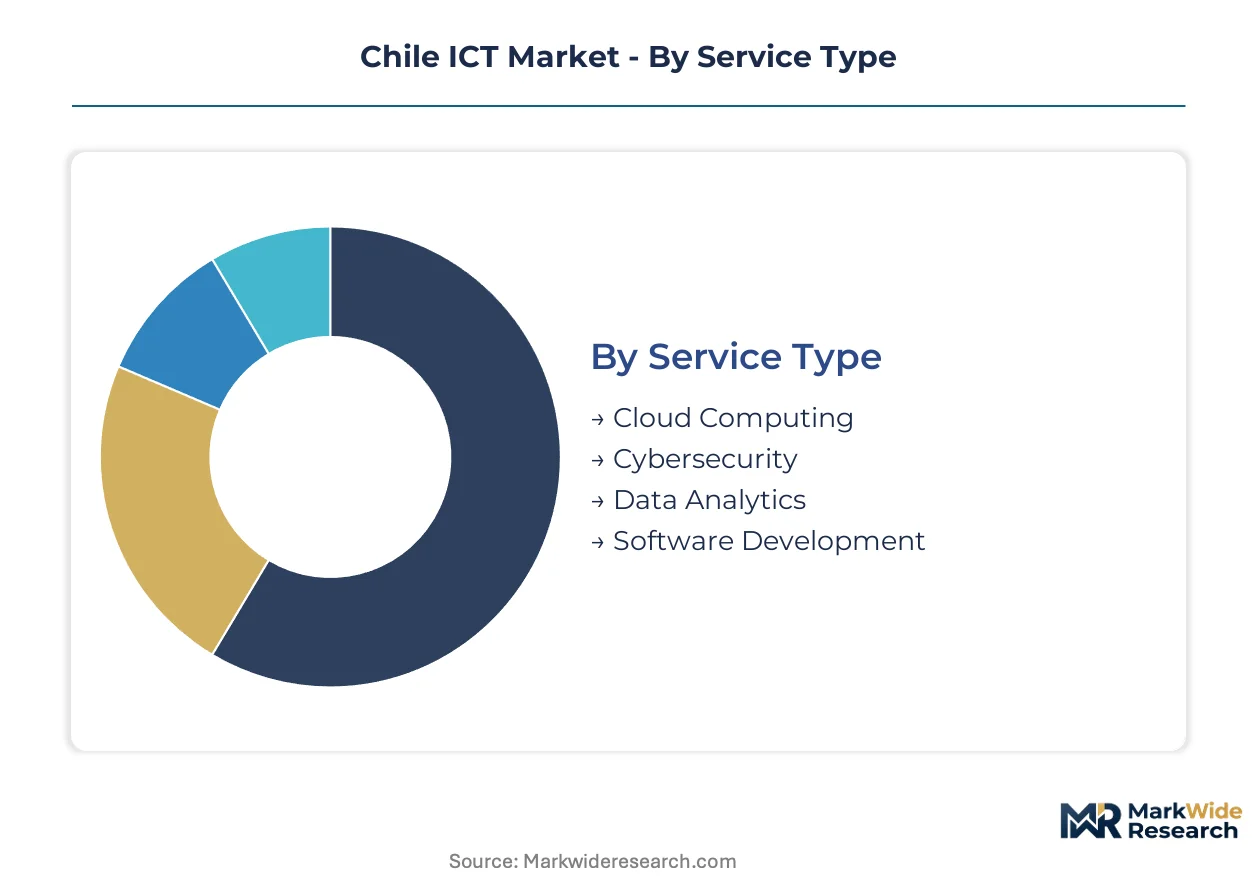
Chile's ICT market fragments across service delivery models, industry absorption patterns, and infrastructure maturity levels. Mining operators in Antofagasta and financial institutions in Santiago deploy fundamentally different technology stacks despite sharing common regulatory frameworks. Understanding these segment boundaries clarifies where vendor specialization yields competitive advantage.
Service Type:
Domestic demand concentrates in services supporting resource extraction and public sector modernization, while export-oriented segments remain limited given Chile's net importer position in specialized software.
- Cloud Computing:Hyperscale infrastructure services span public, private, and hybrid deployment models with latency requirements below 20 milliseconds for enterprise applications. Mining conglomerates in the Atacama Desert drive demand for edge-integrated cloud architectures as autonomous haulage systems expand. This segment captures the dominant margin pool as legacy workload migration accelerates.
- Cybersecurity:Threat detection, identity management, and zero-trust architecture implementations protect critical infrastructure across banking and retail verticals facing escalating attack surfaces. Banco de Chile and Banco Santander Chile have restructured procurement around outcome-based security metrics. Regulatory pressure from Subtel's net-neutrality enforcement and cross-border data flow rules intensifies compliance spending.
- Data Analytics:Predictive modeling platforms process operational data for mining optimization and logistics planning.
- Software Development:Custom application engineering serves public sector digitalization and enterprise system integration requirements.
Cloud Computing holds the largest share; momentum sits with Cybersecurity as threat environments escalate.
Industry Vertical:
Technology absorption rates correlate with capital intensity and regulatory exposure, creating divergent procurement cycles across Chile's economy.
- Telecommunications:Network infrastructure operators deploy 5G, fiber, and satellite systems under Subtel spectrum frameworks. Entel S.A. anchors nationwide backbone expansion while Huawei Technologies competes aggressively in infrastructure tenders despite geopolitical scrutiny. Rural coverage obligations redirect investment toward underserved provinces outside metropolitan Santiago.
- Banking:Financial institutions in Santiago's technology corridor pursue real-time transaction processing and algorithmic compliance systems. The National AI Strategy creates mandatory upgrade cycles for government contractors while BIS-aligned technical standards add certification layers for hardware imports. Retail and corporate banking verticals unbundle hardware acquisition from managed services.
- Retail:Omnichannel platforms and supply chain visibility tools dominate enterprise procurement.
- Education:Public sector institutions implement connectivity and learning management systems under government digitalization programs.
Telecommunications absorbs the greatest infrastructure investment; Banking climbs fastest on regulatory compliance mandates.
Technology:
Deployment maturity spans production-scale infrastructure to pilot-phase applications, with mining and logistics operators driving adoption of latency-sensitive systems.
- 5G:Private cellular networks displace Wi-Fi and legacy LTE at open-pit copper operations across the Tarapacá region. Antofagasta Minerals and Codelco deploy dedicated spectrum slices for autonomous truck fleets and drone-based surveying. Subtel's mmWave allocations tighten equipment certification timelines for base station suppliers.
- Artificial Intelligence:Machine learning platforms optimize ore processing and predictive maintenance in resource extraction corridors. Algorithmic transparency standards under the National AI Strategy create compliance obligations for public sector contractors. Cloud architecture and AI specialist shortages inflate implementation timelines across enterprise programs.
- IoT:Industrial sensor networks monitor equipment health and environmental conditions in remote installations.
- Blockchain:Distributed ledger applications pilot in supply chain traceability and trade finance documentation.
5G commands the heaviest infrastructure commitment; Artificial Intelligence expands most quickly on operational optimization demand.
End User:
Procurement scale and risk tolerance divide the market between centralized enterprise buyers and fragmented smaller accounts.
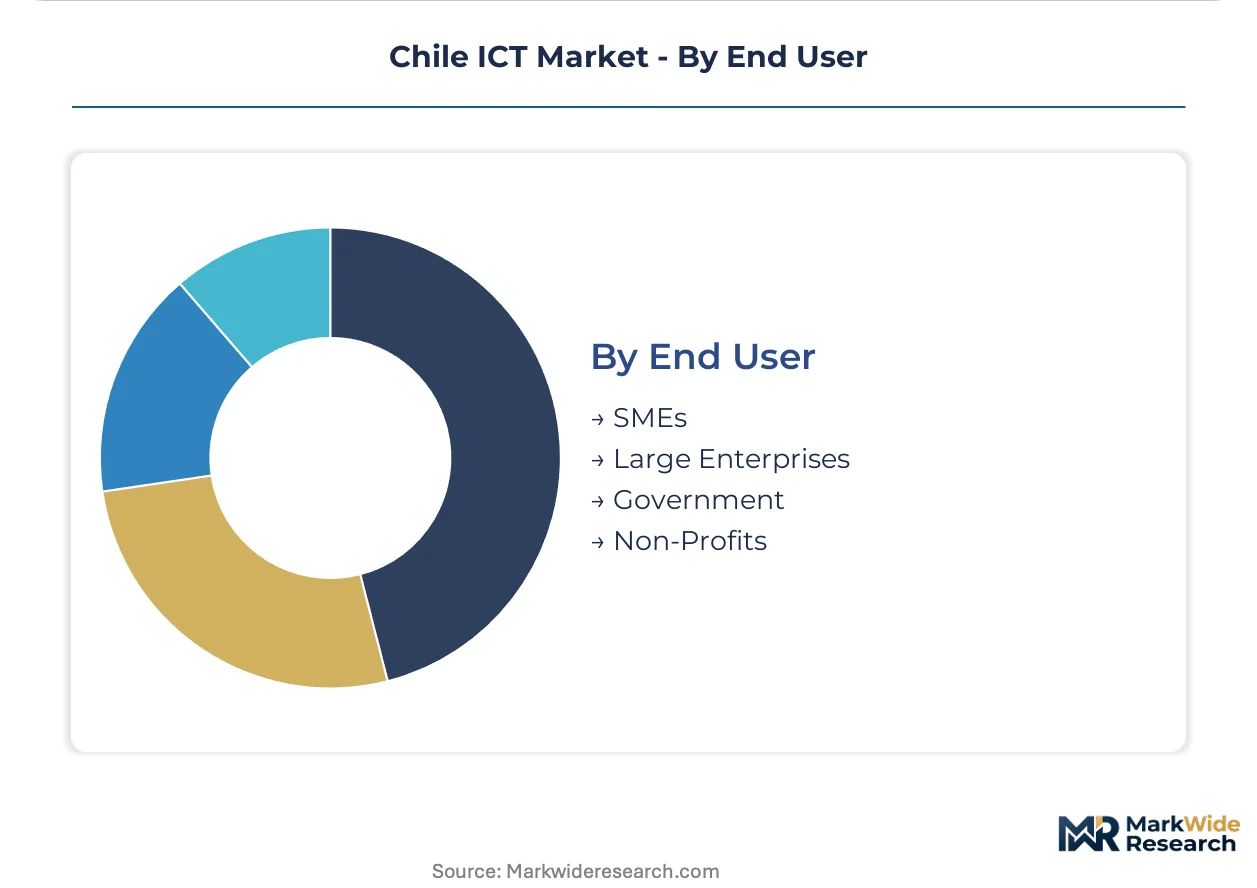
- SMEs:Mid-sized enterprises adopt cloud-native productivity suites and managed security services through systems integrator framework agreements. Santiago's technology corridor concentrates demand while remote regions face connectivity constraints. Subscription pricing models reduce upfront capital requirements.
- Large Enterprises:Mining conglomerates and financial institutions operate dedicated procurement functions with outcome-based performance metrics. Copper price volatility creates demand unpredictability for technology vendors dependent on extractive industry spending. Legacy SCADA environments resist seamless cloud migration, requiring costly middleware development.
- Government:Public agencies implement National AI Strategy compliance systems and emergency communications modernization.
- Non-Profits:Social sector organizations access subsidized connectivity and basic productivity tools through government programs.
Large Enterprises dominate absolute spending; SMEs gain share fastest as managed service models reduce adoption barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Santiago commands premium pricing power over Antofagasta for enterprise-grade connectivity, reflecting fiber density asymmetries between metropolitan and mining corridor deployments. Subtel's rural coverage obligations redirect infrastructure investment toward underserved provinces, compressing historical concentration in the capital region.
Santiago Metropolitan Region
Hyperscale cloud providers establish local availability zones in Quilicura and Cerrillos municipalities, attracted by data center clustering and sub-20 millisecond latency guarantees. The National AI Strategy mandates algorithmic transparency standards for government contractors headquartered in the capital. Banco de Chile and Banco Santander Chile restructure supplier panels around outcome-based performance metrics in the financial district.
Antofagasta Region
Autonomous haulage systems and predictive maintenance platforms generate sustained procurement of private wireless networks across open-pit copper operations. Subtel's mmWave spectrum allocations tighten equipment certification timelines for base station suppliers serving the mining belt. Codelco and Antofagasta Minerals deploy dedicated 5G spectrum slices for autonomous truck fleets in the Atacama Desert operations corridor.
Valparaíso Region
Port logistics operators pursue real-time cargo tracking and supply chain visibility tools through framework agreements with systems integrators. The government's digitalization programs channel connectivity subsidies toward public sector institutions in regional centers. Viña del Mar and Valparaíso city clusters attract managed security services for mid-sized enterprises adopting cloud-native productivity suites.
Biobío Region
Manufacturing and forestry verticals drive demand for industrial IoT sensors and edge computing infrastructure outside mining-dominated northern zones. Subtel's net-neutrality enforcement shapes service pricing structures for regional telecommunications operators. Concepción's technology corridor concentrates SME adoption of subscription-based productivity and security services.
Chile ICT Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure across Chile's ICT market. Hyperscale cloud providers and global infrastructure vendors occupy distinct positioning from regional telecommunications operators and local systems integrators. The market fragments across three strategic archetypes: global platform owners, national backbone operators, and specialized compliance integrators. Dominant competitive moves include hyperscale availability zone establishment and strategic training partnerships with Chilean universities to address cloud architecture talent scarcity.
Among global platform owners, Microsoft Corporation exemplifies technology leadership through Azure training partnerships that build local deployment capacity. Entel S.A. anchors the national backbone operator tier through nationwide fiber expansion serving enterprise zones. Huawei Technologies occupies a contested position in infrastructure tenders, representing cost-competitive 5G equipment supply despite geopolitical scrutiny affecting procurement decisions.
| Leading Market Players |
|---|
| IBM |
| Huawei Technologies |
| Microsoft Corporation |
| Telefónica Chile |
| Entel S.A. |
| Amazon Web Services |
| Oracle |
| Cisco Systems |
| Others |
Value Chain & Pricing Dynamics
BIS-aligned technical standards for data center equipment imports gate both supply qualification and price differentiation simultaneously in Chile's ICT market. Hardware vendors face certification layers that compress margins on entry-tier server shipments while hyperscale cloud providers absorb compliance costs through volume procurement frameworks.
Pricing Analysis
Santiago commands a 15-20% premium over Antofagasta for equivalent enterprise-grade connectivity packages. Three-tier pricing structure across premium, standard, and economy levels stratifies by latency guarantee and redundancy architecture. Cost compression in the economy tier is intensifying because Entel S.A. and Telefónica Chile compete aggressively for SME framework agreements. Mining conglomerates in the Atacama Desert show least price sensitivity due to operational technology uptime requirements.
Supply Chain Analysis
Port congestion at Valparaíso and San Antonio elevates inbound logistics costs for networking gear originating from China, Taiwan, and the United States. Chilean data center operators draw from server assemblies in Mexico and Brazil to circumvent Asia-Pacific container bottlenecks. Single-source vulnerability concentrates in 5G base station chipsets from Taiwanese foundries. Distribution runs through Santiago-based systems integrators with satellite stocking points in Antofagasta and Concepción.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's ICT market sits in early-cycle expansion as mining operational technology adoption accelerates private 5G network deployment. The National AI Strategy mandates algorithmic transparency standards that force government contractor upgrade cycles.
For Market Incumbents: Shield core enterprise relationships in Santiago's financial district through Azure training partnerships that address cloud architect scarcity. Entel S.A. should deepen fiber backbone density in Quilicura and Cerrillos municipalities before hyperscale availability zone saturation. Certification investment in BIS-aligned data center equipment standards preserves procurement eligibility for public sector frameworks.
For New Entrants and Emerging Players: Differentiate on satellite-backhauled edge computing for remote mining installations in Tarapacá and Antofagasta regions outside metropolitan fiber routes. The most penetrable segment sits with mid-sized mining contractors lacking dedicated spectrum engineering teams. A channel partnership model with established systems integrators accelerates framework agreement access without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across private 5G infrastructure deployment as Subtel's mmWave allocations tighten equipment certification timelines. Long-term viability favors vertically integrated specialists controlling both spectrum engineering and managed security service delivery. The signal to watch is copper price recovery trajectory as mining IT budgets correlate with commodity cycle positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Azure Training Partnership Expansion | Microsoft Corporation builds local deployment capacity addressing cloud architect scarcity in Santiago universities. |
| Private 5G Network Deployment | Codelco and Antofagasta Minerals displace Wi-Fi with dedicated spectrum slices for autonomous haulage systems. |
| Hyperscale Availability Zone Establishment | Amazon Web Services and Google establish Quilicura and Cerrillos presence for sub-20 millisecond latency guarantees. |
| Fiber Backbone Densification | Entel S.A. redirects investment toward underserved provinces under Subtel rural coverage obligations. |
| Zero-Trust Architecture Integration | Banco de Chile and Banco Santander Chile restructure procurement around outcome-based security performance metrics. |
Study Parameters
Initial hypotheses were tested against primary input from cloud platform engineers, mining operational technology directors, Subtel regulatory affairs specialists, and systems integrator account executives and refined through secondary validation. Sources included SEC filings from hyperscale providers, Subtel spectrum auction documentation, Entel S.A. infrastructure capex disclosures, and Chilean customs import records for data center equipment. Bottom-up service revenue aggregation and top-down ICT spending intensity ratios were triangulated against National AI Strategy implementation timelines.
Variance decomposition across the projection horizon isolates segment-specific growth contributions from cloud computing, cybersecurity, data analytics, and software development. Deployment model, organization size, vertical industry, and regional infrastructure maturity dimensions structure the analytical framework. CAGRs derive from logistic diffusion curves fitted to enterprise cloud migration patterns and mining autonomous system adoption rates. Copper price volatility scenarios and Subtel spectrum auction schedules feed sensitivity analysis.
Decision-makers should treat outputs as directional under base assumptions of sustained mining capital expenditure and Subtel regulatory continuity; material deviation would warrant model refresh. Cross-border data flow regulation uncertainty and specialized labor scarcity represent primary forecast revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
System Integration Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
AI In Packaging Design Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Multicarrier Parcel Management Solutions Software Market
Digital Solutions
Czech Republic ICT Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Agriculture Software Market
Digital Solutions
Canada ICT Market
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
Global Content Moderation Solutions Market
Digital Solutions
Self Service Technology Market