
 India Engineering Research and Development (ER&D) Services Market | 2026-2036
India Engineering Research and Development (ER&D) Services Market Size, Share, and Industry Trends Forecast 2026-2036
India Engineering Research and Development (ER&D) Services Market Insights
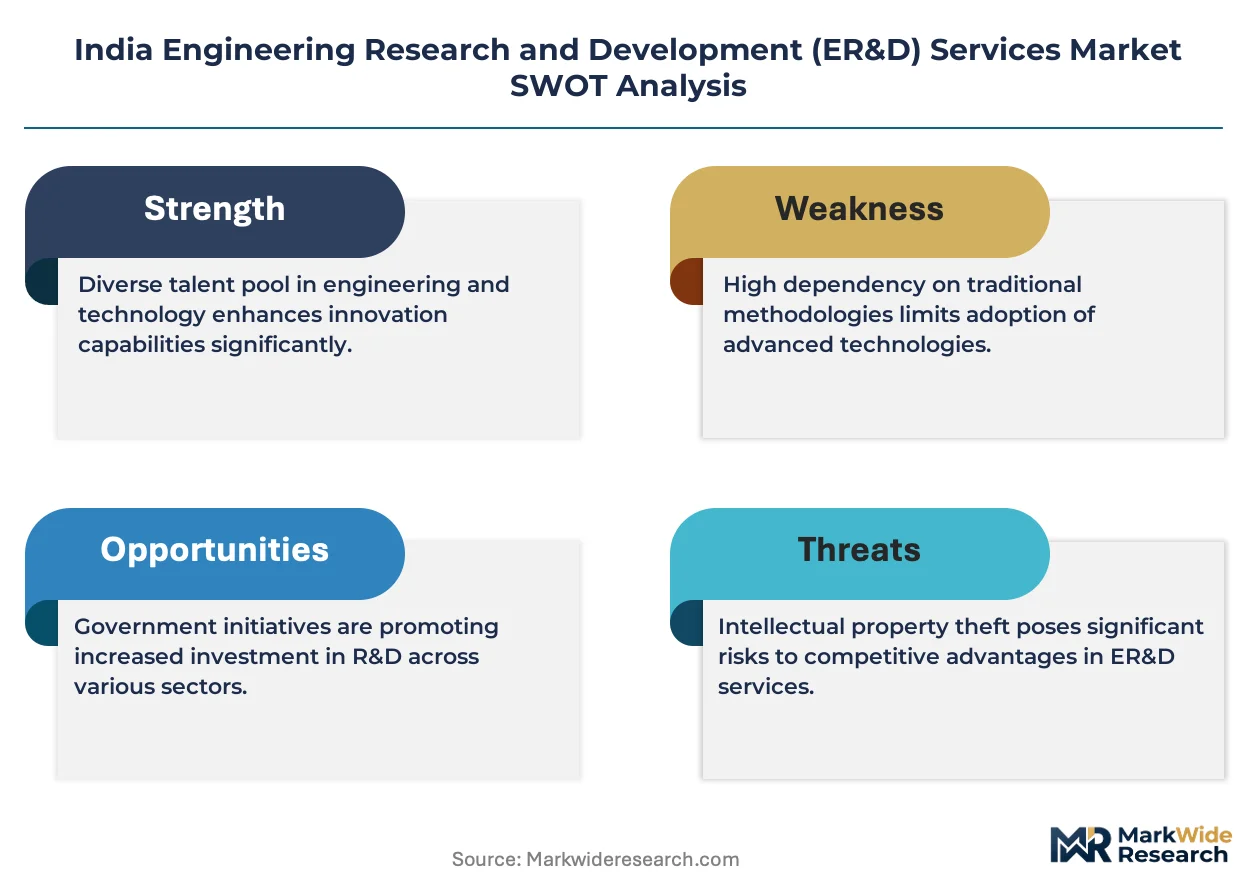
India's embedded systems talent pool is collapsing under the weight of surging demand from automotive and aerospace programs, forcing ER&D service providers to recalibrate hiring pipelines and compensation structures. HCL sustains one of the largest automotive engineering benches in the country, with dedicated powertrain and chassis development centers in Chennai and Pune. Tata Technologies dominates physical prototyping and testing services for commercial vehicle OEMs, leveraging its heritage manufacturing relationships. L&T Technology Services anchors high-margin simulation-led engagements for industrial machinery clients, differentiating through deep domain expertise in computational fluid dynamics and structural analysis.
Engineering Research and Development (ER&D) services encompass the outsourced design, prototyping, testing, and systems integration of hardware and software components across industrial products, typically executed through CAD-based modeling, finite element analysis, embedded firmware development, and validation against functional safety standards such as ISO 26262. These services enable OEMs to compress product development cycles, reduce fixed R&D overhead, and access specialized competencies without building captive engineering organizations. Design services and embedded systems represent the most mature revenue streams, with margin pools shifting toward IoT solutions and simulation software as clients demand digital-thread continuity from concept through production. Prototyping retains structural importance as a gateway to larger testing and consulting engagements, while healthcare and consumer electronics verticals are expanding fastest among industry verticals as regulatory complexity and miniaturization requirements intensify.
BIS standards for electronics and automotive components, CDSCO medical device regulations, and the PLI scheme administered by MeitY and DPIIT collectively shape market access, product qualification requirements, and the geographic distribution of ER&D investments across Indian states. Compliance with these frameworks determines which service providers can participate in government-linked programs and which end-user segments remain accessible. Stakeholders must monitor how the proposed Indian Semiconductor Mission and evolving data localization norms for embedded systems firmware will redraw competitive boundaries between domestic specialists and multinational captive centers.
Market Dynamics
The PLI scheme for automotive and auto components is channeling public capital into domestic R&D infrastructure, compressing the timeline for captive center establishment and forcing ER&D service providers to defend engineering bench depth in Bengaluru, Pune, and Hyderabad.
Growth Catalysts
- Automotive electrification mandates:Embedded systems development for electric powertrains is absorbing engineering capacity across tier-1 suppliers and OEM captive centers, pulling talent from conventional ICE programs into high-voltage architecture and battery management systems.
- BIS standards harmonization:Electronics and automotive component qualification requirements are creating predictable compliance pathways, enabling domestic ER&D providers to bid for government-linked programs previously reserved for multinational engineering houses.
- Hyderabad cluster maturation:The city's aerospace and defense engineering ecosystem is cross-pollinating into commercial automotive and industrial machinery verticals, expanding the addressable talent pool beyond traditional software services.
Market Restraints
- Silicon wafer import dependency:Prototype fabrication for embedded systems remains tethered to East Asian foundry capacity, exposing domestic ER&D schedules to shipping delays and customs processing bottlenecks at Indian ports.
- Specialized simulation software licensing:Computational fluid dynamics and multi-physics modeling tools from US and European vendors carry dollar-denominated annual fees that compress margins on fixed-price engineering engagements.
- ISO 26262 functional safety certification scarcity:The shallow pool of certified hardware and software safety engineers constrains expansion into autonomous driving and ADAS program work for European and North American OEMs.
Strategic Opportunities
- Medical device ER&D under CDSCO:Regulatory complexity for Class C and Class D devices is deterring generalist IT services firms, creating margin-rich white space for engineering specialists with biocompatibility testing and sterilization validation capabilities.
- Digital thread convergence:IoT platform integration with CAD-based modeling is enabling service providers to capture recurring software revenue alongside traditional hardware engineering fees, embedding annuity streams into project-based relationships.
- Tamil Nadu industrial corridor:State-level electronics manufacturing incentives are attracting component suppliers needing localized validation and testing support, extending ER&D serviceable addressable market beyond established Bengaluru-Pune-Hyderabad clusters.
Industry Challenges
- Power electronics skill scarcity:The intersection of embedded firmware development and high-voltage circuit design remains thinly staffed, forcing ER&D providers to train internally or poach from semiconductor firms at premium compensation multiples.
- Physical prototyping capex intensity:Wind tunnel testing, environmental chambers, and electromagnetic compatibility labs require capital commitments that strain mid-tier service providers competing against Tata Technologies' heritage manufacturing relationships.
- Legacy toolchain integration friction:Client-mandated migration from on-premise CAD servers to cloud-native collaborative platforms is disrupting established engineering workflows and requiring parallel support for hybrid infrastructure during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Engineering Research and Development (ER&D) Services Market |
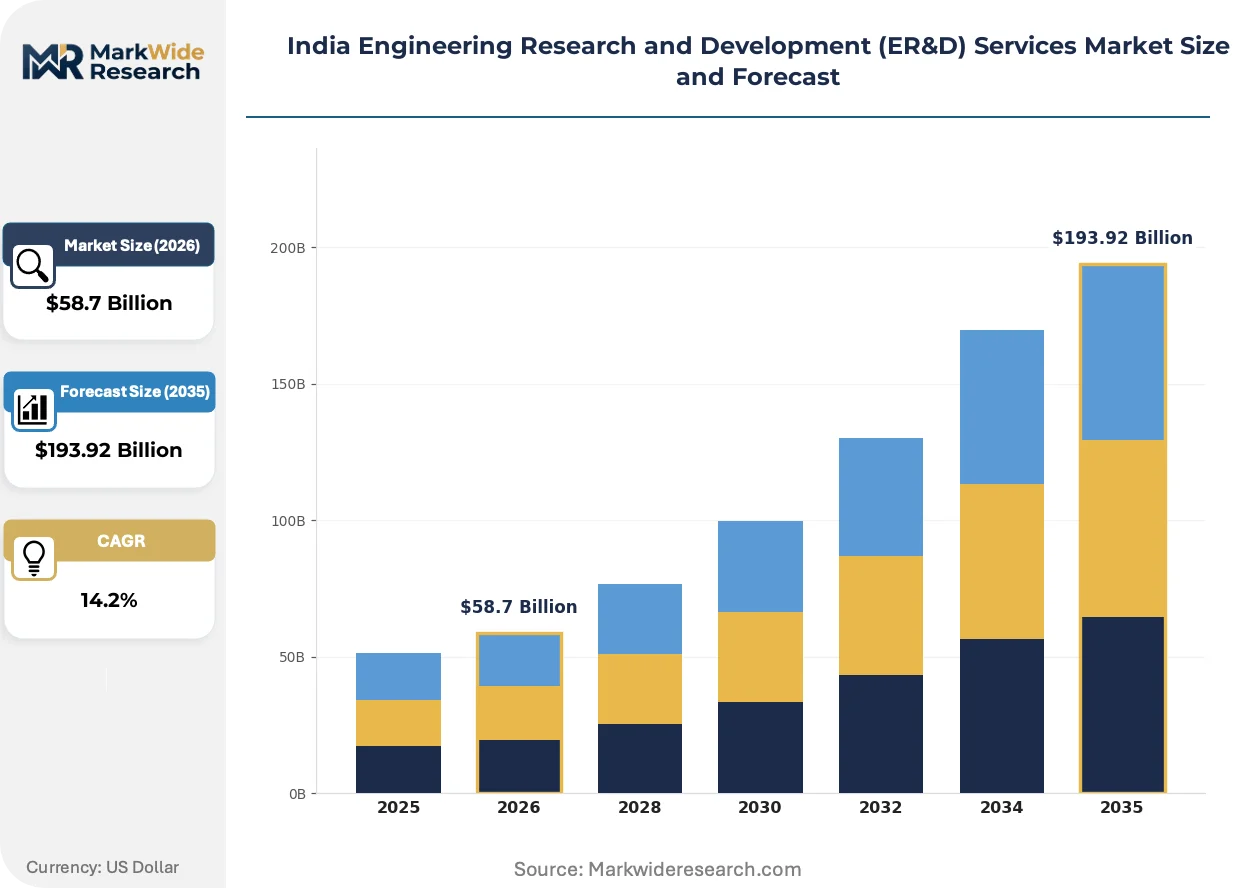
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $193.92 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Services, Prototyping, Testing Services, Consulting Services Industry Vertical: Aerospace, Automotive, Consumer Electronics, Healthcare Technology: MCAD, Simulation Software, Embedded Systems, IoT Solutions End User: OEMs, Tier-1 Suppliers, Startups, Government Agencies |
| Companies Covered | HCL, Infosys, L&T Technology Services, Tata Technologies, Wipro, Tata Consultancy Services, Cyient, Mahindra Engineering Services, Tech Mahindra, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Engineering Research and Development (ER&D) Services Market Trends and Innovations
Engineering service delivery is fragmenting across digital-native and physical-dominant capabilities, with client procurement patterns favoring providers who can bridge simulation-led design and hardware validation without handoff friction.
Model-based systems engineering is bifurcating the ER&D competitive landscape. The methodology integrates requirements management, architectural modeling, and verification into unified digital environments. Automotive OEMs in India are adopting MBSE at pace for electric vehicle platform development, displacing document-centric design reviews. This technology is compressing the traditional boundary between concept engineering and detailed design phases, forcing service providers to retrain mechanical engineers in SysML and requirements traceability tools.
CDSCO's tightening medical device clinical evaluation requirements are extending validation timelines for diagnostic imaging and patient monitoring equipment. The regulation mandates local adverse event reporting infrastructure and post-market surveillance systems that domestic ER&D providers must build to serve multinational healthcare OEMs. Cardiovascular device and IVD segments are most affected, with engineering teams restructuring quality management systems to accommodate notified body audit schedules.
Fixed-price engineering contracts are giving way to gain-sharing arrangements tied to product commercialization milestones. Industrial machinery OEMs in Gujarat and Maharashtra are piloting outcome-linked fee structures that align ER&D provider compensation with field performance metrics rather than delivery checkpoints. This shift is most visible in agricultural equipment and construction machinery verticals, where seasonal demand volatility makes traditional time-and-material engagements unpalatable to capital-constrained manufacturers.
India Engineering Research and Development (ER&D) Services Market Segmentation
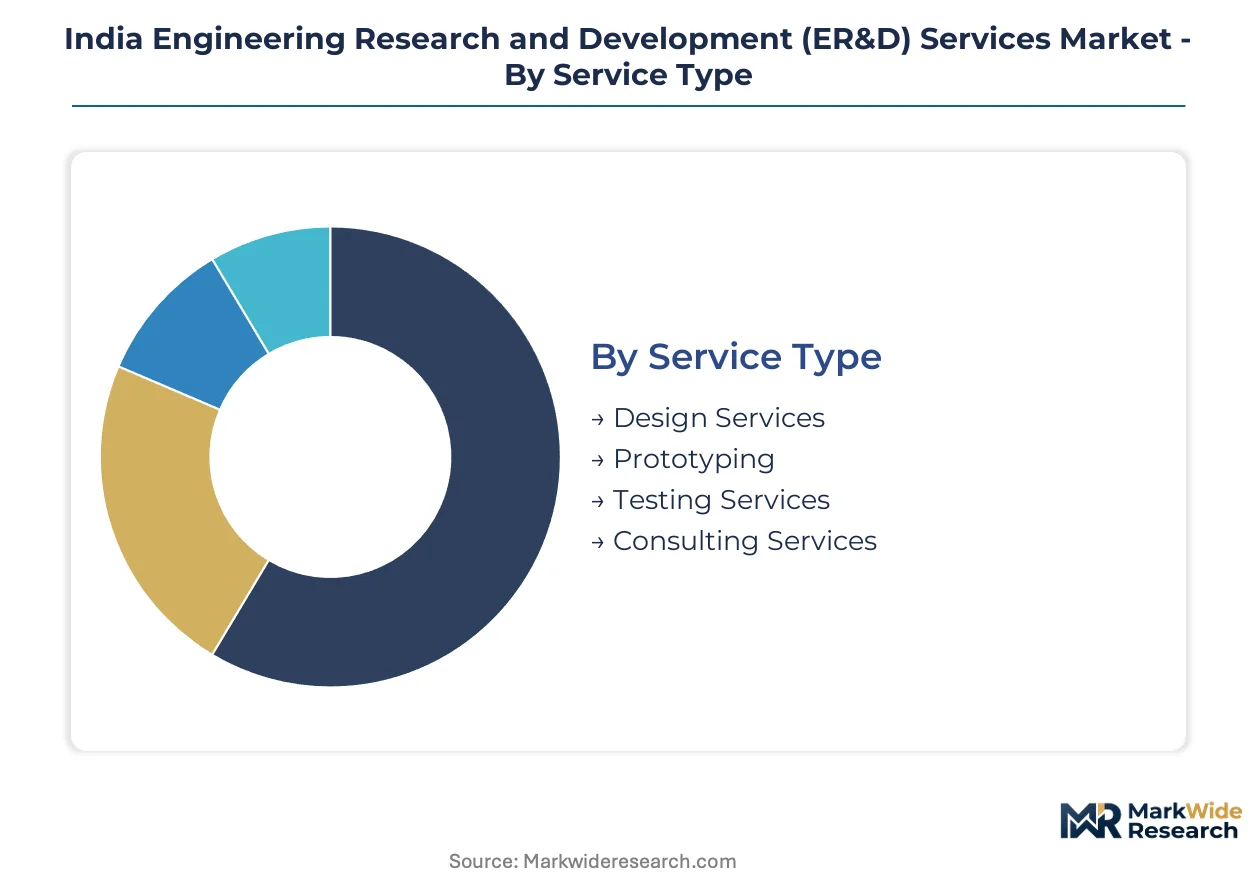
Segmentation in India's ER&D services market reveals how engineering capabilities align with procurement channels. Service providers configure delivery models differently for automotive OEMs versus healthcare startups, while technology choices determine margin structures and talent requirements.
Service Type:
Channel mix varies sharply across service categories, with design and prototyping flowing through direct enterprise sales while testing services route through certification body partnerships.
- Design Services:CAD-based modeling and finite element analysis form the technical core, with automotive electrification programs in Pune and Chennai absorbing substantial bench capacity. OEM captive centers compete directly with outsourced providers for mechanical and electrical design talent.
- Prototyping:Physical model fabrication bridges digital design and validation phases, requiring capital-intensive wind tunnels and environmental chambers that favor established players with heritage manufacturing relationships.
- Testing Services:Functional safety validation against BIS and ISO 26262 standards, concentrated among tier-1 suppliers seeking pre-certification support.
- Consulting Services:Systems engineering and regulatory navigation for CDSCO medical device submissions and PLI scheme compliance.
By volume, Design Services leads. By growth pace, Testing Services is climbing fastest as certification requirements tighten.
Industry Vertical:
Cost tier stratification separates capital-intensive aerospace programs from high-volume automotive engagements and margin-rich healthcare contracts.
- Automotive:Embedded systems development for electric powertrains dominates capacity allocation, with Bengaluru and Hyderabad engineering clusters feeding both OEM captive centers and tier-1 supplier programs. PLI scheme incentives are compressing timelines for domestic R&D infrastructure buildout.
- Healthcare:Class C and Class D medical device engineering under CDSCO jurisdiction commands premium pricing due to biocompatibility testing and sterilization validation requirements that deter generalist competitors.
- Aerospace:Defense and commercial aviation programs leverage Hyderabad's cross-pollinated engineering ecosystem for structural analysis and avionics development.
- Consumer Electronics:Miniaturization and IoT integration drives demand for compact embedded firmware solutions, with Tamil Nadu electronics manufacturing incentives extending addressable market beyond traditional clusters.
Automotive captures the largest revenue share. Healthcare is expanding most quickly as regulatory complexity deepens moats around specialized providers.
Technology:
Customer type determines technology adoption patterns, with OEMs standardizing on MCAD and simulation suites while startups prioritize IoT platform integration.
- Embedded Systems:Firmware development for automotive ECUs, battery management systems, and industrial controllers constitutes the most mature revenue stream. High-voltage power electronics skill scarcity is forcing providers to train internally or poach from semiconductor firms.
- Simulation Software:Computational fluid dynamics and multi-physics modeling anchor high-margin engagements for industrial machinery clients, though dollar-denominated licensing fees compress margins on fixed-price contracts.
- MCAD:Mechanical computer-aided design remains foundational across all verticals, with cloud-native platform migrations disrupting established engineering workflows.
- IoT Solutions:Platform integration with CAD-based modeling enables recurring software revenue alongside traditional hardware engineering fees.
Embedded Systems holds the deepest bench penetration. IoT Solutions is gaining share fastest as digital-thread requirements intensify.
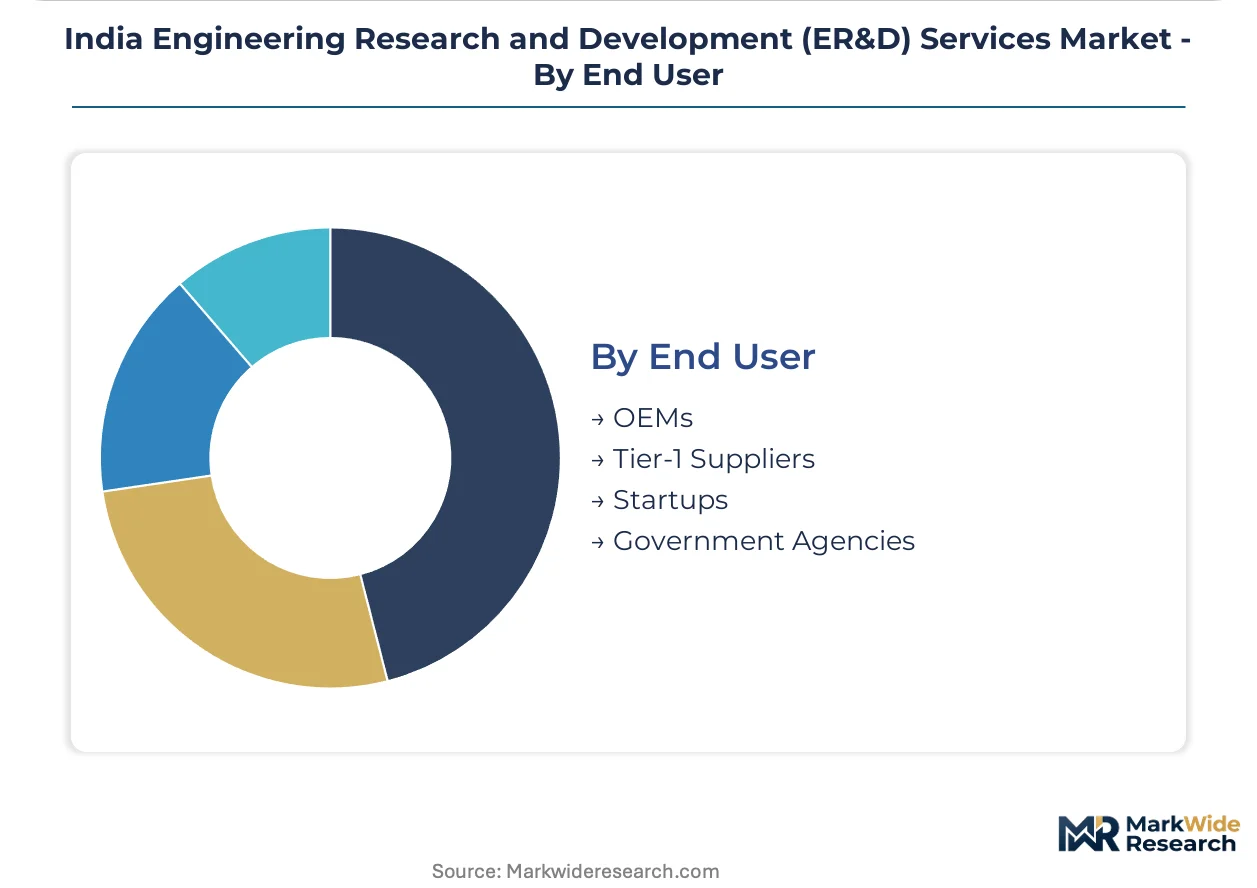
End User:
Supply concentration shapes competitive dynamics, with OEMs and tier-1 suppliers commanding dedicated engineering benches while startups and government agencies access services through project-based procurement.
- OEMs:Original equipment manufacturers in automotive and industrial machinery verticals drive the largest contract values, with gain-sharing arrangements tied to product commercialization milestones displacing fixed-price structures.
- Tier-1 Suppliers:Component manufacturers seeking pre-certification testing and embedded systems integration support, concentrated in Tamil Nadu and Maharashtra industrial corridors.
- Startups:Early-stage hardware ventures accessing outsourced engineering to avoid captive organization buildup, particularly in medical device and consumer electronics segments.
- Government Agencies:Defense and public infrastructure programs requiring BIS-compliant component qualification and localized validation support.
OEMs anchor volume concentration. Startups are expanding most quickly as venture-funded hardware ventures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's ER&D services consumption concentrates in automotive-heavy western states, while southern clusters specialize in aerospace and medical device engineering, creating distinct capability geographies that shape procurement patterns.
Maharashtra
Pune and Mumbai anchor automotive embedded systems development for electric powertrains, with tier-1 suppliers clustering around Chakan and Talegaon industrial belts. The state's MIDC electronics manufacturing incentives channel investment into validation and testing infrastructure. PLI scheme disbursements for auto components are accelerating captive center buildouts in Pimpri-Chinchwad.
Karnataka
Bengaluru's engineering talent density sustains the deepest bench for semiconductor-adjacent firmware development and simulation software. BIS standards harmonization for electronics components enables domestic providers to bid for government-linked programs previously reserved for multinational houses. The Electronics City and Whitefield corridors concentrate IoT platform integration work for industrial machinery OEMs.
Tamil Nadu
Chennai's heritage manufacturing relationships support physical prototyping and testing services for commercial vehicle programs. State-level electronics manufacturing incentives under the Tamil Nadu Industrial Policy attract component suppliers needing localized validation support. Sriperumbudur and Oragadam industrial corridors extend the addressable market beyond traditional Bengaluru-Pune-Hyderabad clusters.
Telangana
Hyderabad's aerospace and defense engineering ecosystem cross-pollinates into commercial automotive and industrial machinery verticals. The city's DRDO and ISRO legacy creates a talent pool for structural analysis and avionics development. Genome Valley's medical device manufacturing base generates demand for CDSCO-compliant ER&D services in diagnostic equipment.
Gujarat
Sanand and Vadodara industrial corridors host automotive OEMs piloting gain-sharing arrangements tied to product commercialization milestones. The state's semiconductor policy complements central PLI schemes for electronics manufacturing. Dholera Special Investment Region is attracting component suppliers requiring embedded systems integration support for industrial automation.
India Engineering Research and Development (ER&D) Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated engineering bench depth in automotive and aerospace verticals coexisting with fragmented medical device and consumer electronics specialists. The market structure reflects heritage manufacturing relationships versus software-native delivery models. Two archetypes dominate: diversified conglomerate-affiliated providers with captive fabrication access, and pure-play engineering specialists with simulation-led differentiation. Competitive moves center on talent poaching from semiconductor firms and cloud-native platform migrations to capture recurring software revenue.
Within the integrated tier, HCL, Tata Technologies, and L&T Technology Services exemplify divergent positioning strategies. HCL occupies a scale-driven position across embedded systems and powertrain development. Tata Technologies anchors physical prototyping relationships through heritage manufacturing linkages. L&T Technology Services represents simulation-led differentiation in industrial machinery verticals. These three structures illustrate how conglomerate affiliation, manufacturing lineage, and domain specialization create distinct competitive vectors in a market where ISO 26262 certification scarcity constrains expansion into autonomous driving programs.
| Leading Market Players |
|---|
| HCL |
| Infosys |
| L&T Technology Services |
| Tata Technologies |
| Wipro |
| Tata Consultancy Services |
| Cyient |
| Mahindra Engineering Services |
| Tech Mahindra |
| Others |
Pricing and Supply Chain Analysis
Project-based engineering contracts with embedded software licensing clauses lock in multi-year supply access for dollar-denominated simulation tools while capping price visibility for domestic ER&D providers serving BIS-compliant automotive programs. This structure forces margin compression when rupee depreciation accelerates against US and European vendor currencies.
Pricing Analysis
Fixed-price engineering engagements dominate automotive and industrial machinery verticals, though gain-sharing arrangements tied to product commercialization milestones are displacing traditional structures in Gujarat and Maharashtra. Price differentiation rests on ISO 26262 certification tier and volume scale, with uncertified generalist providers facing steeper discount pressure than functional safety specialists. Cost compression in simulation-led design services is intensifying because dollar-denominated software licensing fees consume margin on fixed-price contracts. Tier-1 suppliers exhibit highest price sensitivity due to OEM cost-down mandates, while medical device OEMs under CDSCO jurisdiction show lowest sensitivity given biocompatibility testing requirements that deter generalist competitors.
Supply Chain Analysis
Silicon wafer fabrication capacity in Taiwan, South Korea, and China constitutes the critical chokepoint for prototype development schedules in India's embedded systems segment. Domestic ER&D providers draw from East Asian foundry output for microcontroller units, power semiconductors, and battery management integrated circuits, with logistics concentrated through Singapore and Hong Kong transshipment hubs. Single-source vulnerability in advanced node fabrication exposes programs to shipping delays and customs processing bottlenecks at Indian ports. Distribution runs through direct enterprise sales for design services and certification body partnerships for testing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM captive center expansion under PLI scheme incentives threatens to substitute outsourced ER&D capacity with in-house engineering benches, forcing service providers to defend positioning through irreplaceable specialization.
For Market Incumbents: Compound defensive moats by deepening ISO 26262 certification density and securing backward integration into physical prototyping infrastructure. The threat of OEM captive center buildout demands preemptive investment in high-voltage power electronics talent pipelines that resist internalization. Certification scarcity in functional safety engineering represents the priority lever for margin defense against conglomerate-affiliated competitors with fabrication access. For New Entrants and Emerging Players: Anchor in CDSCO-regulated Class C and Class D medical device engineering, where biocompatibility testing and sterilization validation requirements deter generalist IT services firms. Tamil Nadu's electronics manufacturing incentives extend addressable market beyond saturated Bengaluru-Pune-Hyderabad clusters. A regulatory-navigation-first go-to-market angle, pairing quality management system restructuring with clinical evaluation support, unlocks multinational healthcare OEM relationships. For Investors and Strategic Acquirers: Capital is best deployed toward simulation-led specialists with captive computational fluid dynamics and multi-physics modeling capabilities, as digital-thread convergence compresses hardware-software boundaries. Long-term viability across the projection horizon hinges on recurring software revenue attachment rates from IoT platform integration. The signal to watch is cloud-native CAD migration velocity, which indicates which providers can capture annuity streams alongside project-based engineering fees.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Certification Investment | Functional safety accreditation unlocks autonomous driving and ADAS program work for European OEMs. |
| Cloud-Native CAD Platform Migration | Digital-thread continuity from concept through production embeds recurring software revenue into hardware relationships. |
| High-Voltage Power Electronics Talent Acquisition | Poaching from semiconductor firms addresses skill scarcity constraining electric powertrain program expansion. |
| CDSCO Compliance Infrastructure Buildout | Local adverse event reporting capability qualifies providers for Class C and Class D medical device engineering. |
| Tamil Nadu Industrial Corridor Expansion | State-level electronics manufacturing incentives attract component suppliers needing localized validation support. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement leads, ER&D service provider delivery heads, and CDSCO regulatory consultants, then refined through secondary validation against BIS certification databases, PLI scheme disbursement records, SEC filings from listed engineering services firms, and semiconductor import trade data. Bottom-up project pipeline analysis across Bengaluru, Pune, Hyderabad, Chennai, and Tamil Nadu industrial corridors was triangulated with top-down market sizing from automotive production forecasts and medical device registration trends.
Variance decomposition across service type, industry vertical, technology stack, and end-user archetype anchored the analytical framework throughout the forecast period. CAGRs were derived from segment-level engineering bench growth rates, PLI scheme incentive trajectories, and embedded systems talent supply elasticity. Industry-specific inputs included electric vehicle platform development timelines, CDSCO regulatory pathway maturation, and cloud-native CAD adoption curves among industrial machinery OEMs.
Material uncertainties — PLI scheme continuation decisions, rupee-dollar volatility impacts on software licensing costs, and foundry capacity allocation shocks from geopolitical disruption — sit outside the modeled envelope. Forecasts reflect assumptions about certification pipeline throughput and talent migration patterns between semiconductor and ER&D sectors. Practitioners should keep alternative scenarios live as BIS standards harmonization pace and data localization norms for embedded firmware evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Morocco ICT Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Global Freelance Platforms Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Digital Signage Services Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Restaurant POS Terminals Market