
 Web Content Management Market | 2026-2036
Web Content Management Market Size, Share, and Industry Trends Forecast 2026-2036
Web Content Management Market Analysis
Subscription-based software-defined content delivery is recalibrating vendor economics away from perpetual licenses toward recurring revenue pools. Adobe Experience Manager leverages deep creative-cloud integration to anchor enterprise accounts with bundled asset workflows. Contentful competes through API-first architecture that extends developer adoption across JAMstack environments. Sitecore specializes in commerce-content convergence, occupying mid-market retailers seeking unified customer data layers.
Web content management systems are software platforms that enable creation, storage, retrieval, and publishing of digital assets through structured repositories, templated rendering engines, and role-based access controls serving omnichannel distribution. Their primary commercial purpose is to decouple content production from presentation logic, allowing non-technical users to manage structured data while developers control frontend delivery frameworks. Cloud-based deployment leads the deployment model dimension as enterprises abandon capital-intensive on-premises infrastructure for elastic consumption models. The healthcare vertical within industry vertical segmentation generates concentrated margin pools due to HIPAA-mandated audit trails and patient-data isolation requirements that command premium pricing. Video content type exhibits the fastest structural expansion as bandwidth costs decline and streaming-first engagement models displace static page architectures.
FDA oversight of healthcare content accuracy and EU GDPR data-localization mandates jointly shape product roadmaps for vendors serving regulated European and North American buyers. The EU AI Act introduces additional compliance burdens for automated content personalization engines, forcing platform providers to embed transparency documentation and human-review checkpoints. Stakeholders must monitor how content provenance standards evolve under emerging regulatory frameworks to avoid retrofitting costs that erode SaaS margin structures.
Market Dynamics
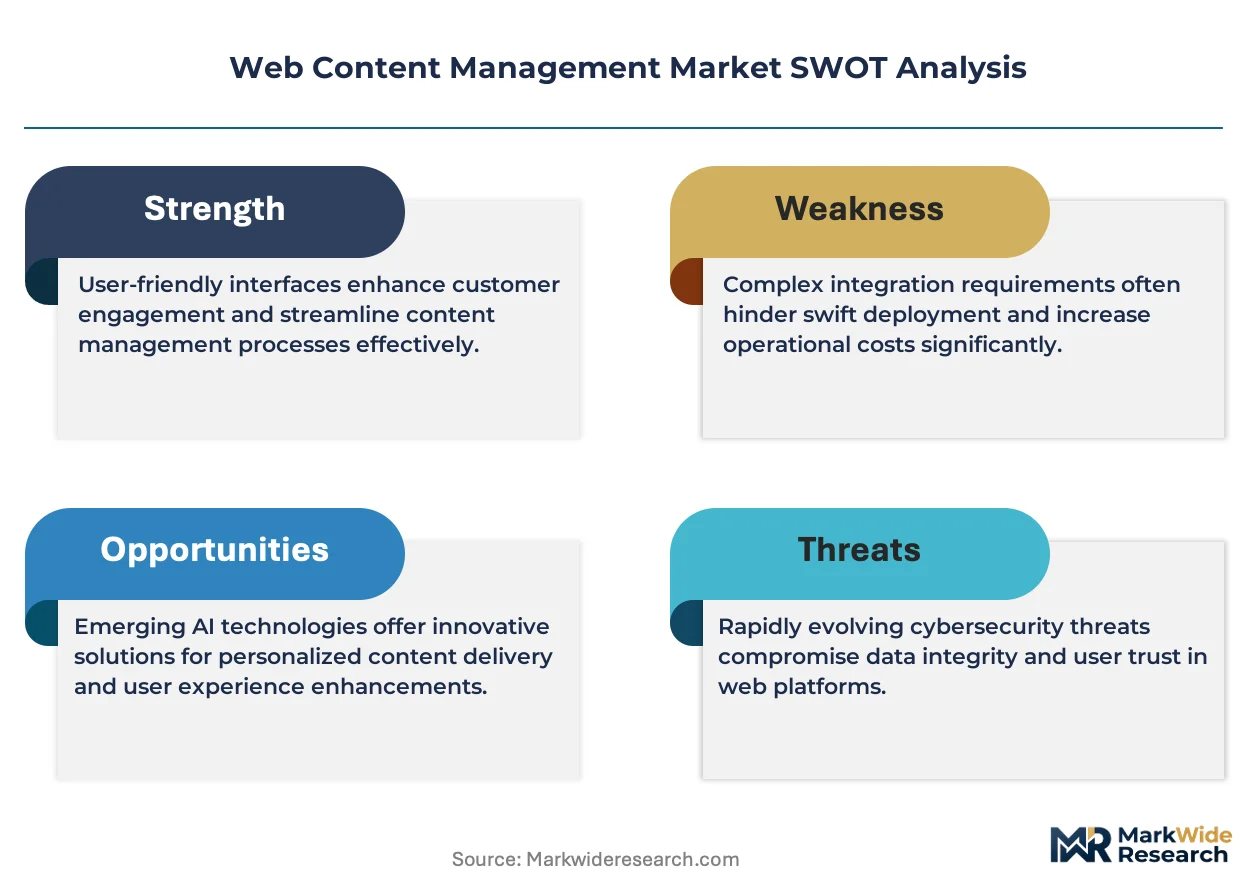
Headless CMS architectures are fragmenting the traditional monolithic stack, forcing vendors to unbundle content repositories from presentation layers as enterprises demand API-first delivery across emerging channels.
Growth Catalysts
- EU AI Act compliance mandates:Automated content personalization engines now require embedded transparency documentation and human-review checkpoints, creating upgrade cycles across European publishing workflows.
- Healthcare HIPAA audit trails:Patient-data isolation requirements and mandated audit capabilities command premium pricing from vendors serving hospitals and pharmaceutical distributors.
- Video streaming bandwidth economics:Declining delivery costs enable streaming-first engagement models that displace static page architectures across media and retail verticals.
Market Restraints
- GDPR data-localization infrastructure costs:European buyers face capital requirements for sovereign cloud deployments that fragment vendor margin pools across national boundaries.
- Legacy system integration friction:Decades-old enterprise content repositories resist API abstraction, extending implementation timelines and inflating professional services dependencies.
- Substitution by low-code page builders:Mid-market buyers increasingly bypass full CMS procurement for lightweight composable tools that sacrifice governance for deployment speed.
Strategic Opportunities
- German automotive content consolidation:Industrial brands are unifying fragmented supplier portals and technical documentation stacks onto single platforms, creating concentrated contract values.
- JAMstack developer ecosystem expansion:Static site generators and edge deployment networks are converging with headless CMS backends to capture front-end build workflows.
- CSRD sustainability reporting integration:The EU Corporate Sustainability Reporting Directive mandates structured ESG disclosure formats that content platforms can monetize through specialized compliance modules.
Industry Challenges
- API governance skill scarcity:Enterprises lack architects capable of orchestrating multi-vendor content services, creating bottlenecks in composable stack deployments.
- Content provenance standardization delays:Emerging frameworks for tracking AI-generated and human-authored material remain unsettled, forcing vendors to overbuild flexibility into editorial workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Web Content Management Market |
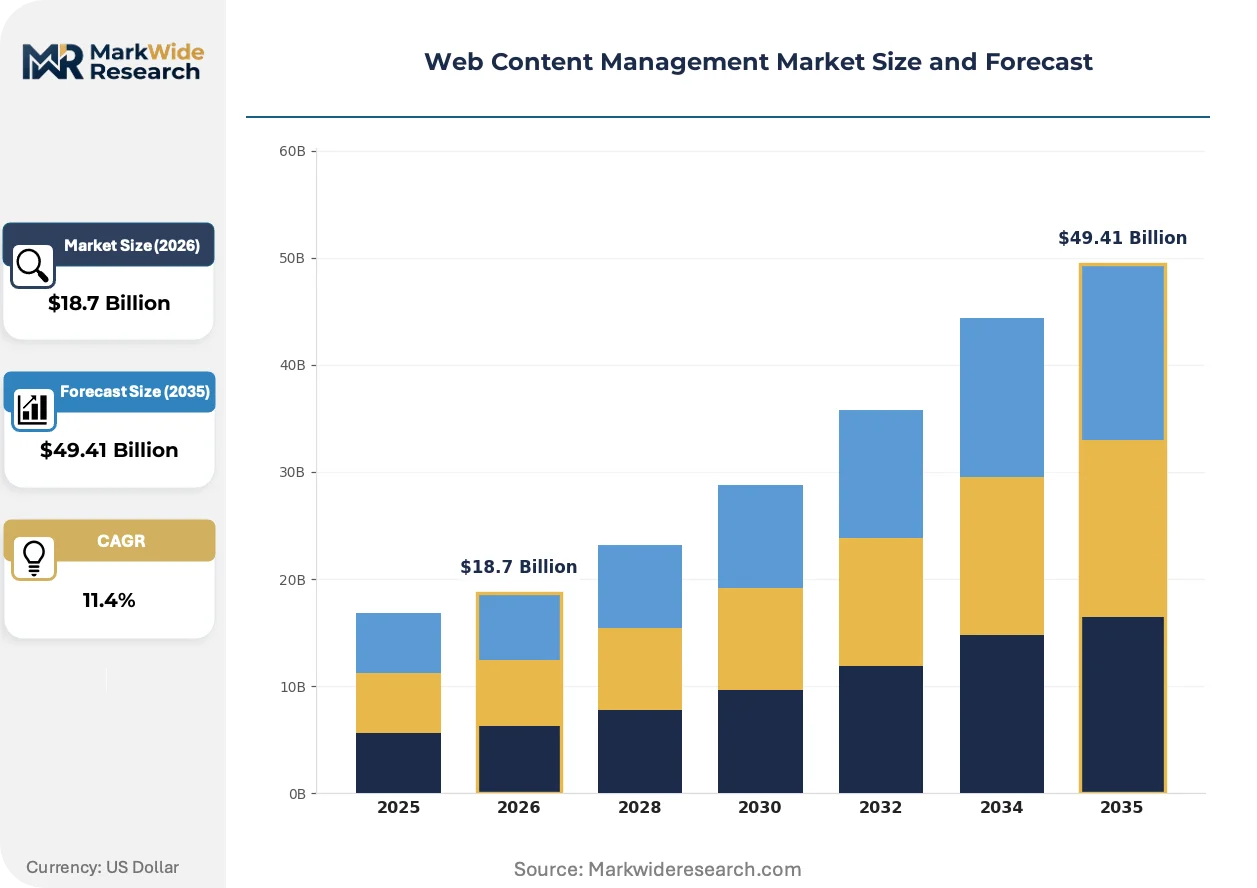
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS Industry Vertical: Healthcare, Education, Retail, Government Content Type: Text, Video, Images, Audio User Type: Marketers, Developers, Designers, Administrators |
| Companies Covered | Optimizely, Sanity, Adobe Experience Manager, WordPress VIP, Drupal, Sitecore, Contentstack, Kentico Xperience, Contentful, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Web Content Management Market Emerging Trajectories
Generative AI is penetrating editorial workflows at uneven speeds across verticals, with regulated industries deploying guardrails while media publishers accelerate automated production pipelines.
Composable architecture is absorbing monolithic CMS functionality into discrete API services. Mid-market retailers are adopting modular content primitives faster than Fortune 500 enterprises locked into multi-year platform contracts. This absorption is compressing vendor switching costs and elevating developer experience as the primary procurement criterion.
The EU AI Act's transparency requirements are forcing automated personalization engines to expose decision logic and maintain human override capabilities. Publishers serving European audiences must retrofit recommendation algorithms with audit trails or face operational suspension. Healthcare content distributors are responding fastest, embedding clinical review checkpoints into automated patient communication flows.
Buyer procurement patterns are compressing vendor evaluation cycles as composable architectures reduce switching costs. Retail chains now pilot headless CMS modules in three-month sprints rather than twelve-month platform migrations. This acceleration is most visible in North American omnichannel deployments, where marketing teams demand same-week content iterations across mobile apps, in-store displays, and voice interfaces.
Web Content Management Market Segmentation
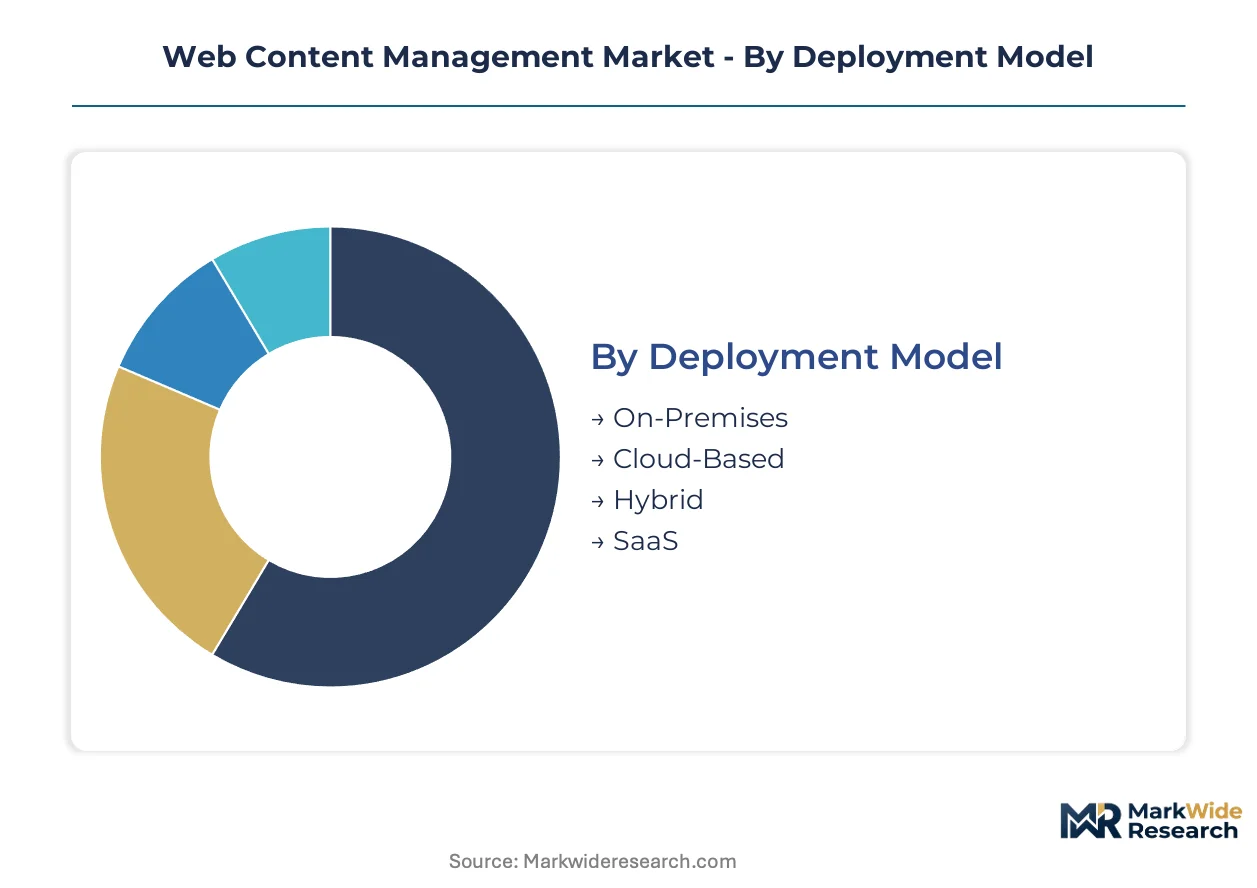
Deployment model selection directly shapes capital intensity and operational control for content operations. Industry vertical alignment determines compliance architecture and pricing power. User type segmentation reveals workflow friction points that vendors must resolve to capture expansion revenue.
Deployment Model:
Cloud-based consumption dominates volume flows while on-premises retains premium pricing in regulated environments.
- Cloud-Based:Elastic infrastructure enables pay-as-you-scale consumption without datacenter capital commitments. Retail chains in Germany and media publishers in France are migrating legacy stacks to eliminate hardware refresh cycles and accelerate omnichannel rollout timelines.
- SaaS:Multi-tenant architectures abstract maintenance burden entirely, embedding automatic security patching and feature updates. Mid-market education providers and regional healthcare networks favor this model to redirect IT headcount toward content strategy rather than platform administration.
- On-Premises:Single-tenant isolation satisfies data sovereignty requirements in defense and classified government workflows.
- Hybrid:Split architectures separate customer-facing content delivery from sensitive back-office repositories.
Mature deployment sits with on-premises installations in defense and classified sectors. Newer deployment is concentrated in SaaS offerings across education and regional healthcare networks.
Industry Vertical:
Compliance burden intensity separates margin tiers, with HIPAA and GDPR mandates creating pricing premiums unattainable in less regulated segments.
- Healthcare:Patient-data isolation requirements and FDA oversight of content accuracy command premium vendor pricing. Hospital systems and pharmaceutical distributors require immutable audit trails and clinical review checkpoints that standard CMS platforms cannot satisfy without substantial customization.
- Retail:Omnichannel velocity demands API-first architectures capable of serving mobile apps, in-store displays, and voice interfaces from unified content repositories. North American chains are consolidating fragmented supplier portals and promotional content stacks onto headless platforms to accelerate same-week campaign iterations.
- Government:Procurement complexity and security clearance requirements extend sales cycles but produce sticky multi-year contracts.
- Education:Budget constraints favor open-source and lightweight composable tools over enterprise platform commitments.
Healthcare represents the steepest expansion trajectory for compliance-embedded premium modules. Education shows the slowest vendor switching as budget freezes extend legacy system lifecycles.
Content Type:
Bandwidth cost curves are reshaping storage and delivery economics across media formats.
- Video:Streaming-first engagement models displace static architectures as delivery costs decline. Media publishers and automotive brands are investing in adaptive bitrate infrastructure and edge caching networks to support immersive product demonstrations and training sequences.
- Text:Structured data requirements for AI training corpora and regulatory documentation sustain repository demand. Financial services and legal publishers maintain heavy investment in semantic markup and version-controlled editorial workflows.
- Images:Visual asset management integrates with creative cloud workflows for brand consistency.
- Audio:Podcast and voice interface content gains share in accessibility-focused public sector deployments.
Volume concentration rests with text repositories in financial and legal publishing. Fastest share gains are occurring in video as streaming infrastructure commoditizes.
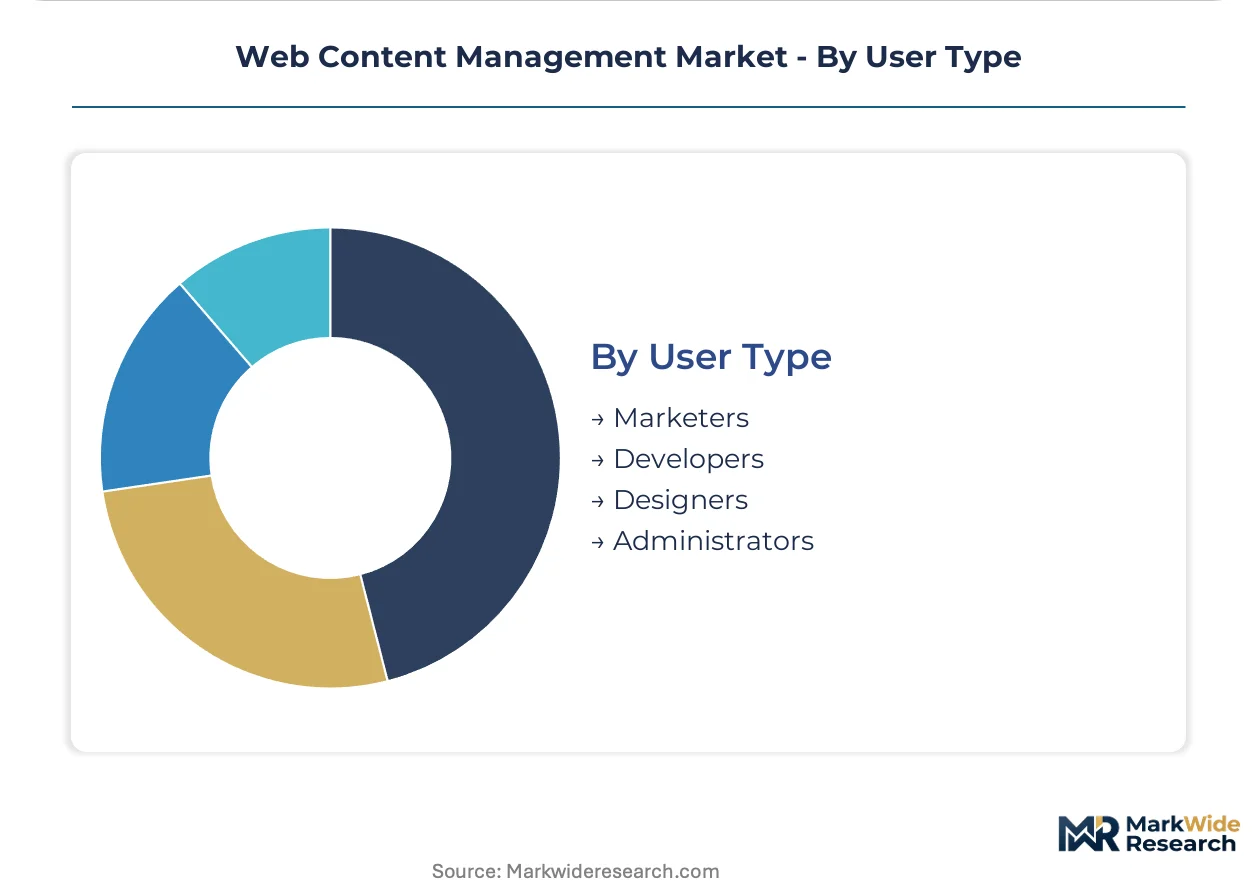
User Type:
Technical sophistication gaps drive platform fragmentation between no-code and developer-centric tooling.
- Developers:API-first and JAMstack-compatible architectures dominate procurement criteria. Engineering teams in technology and media verticals prioritize GraphQL endpoints, webhook extensibility, and edge deployment integration over native authoring interfaces.
- Marketers:Visual drag-and-drop workflows and real-time personalization engines determine platform selection. Campaign velocity requirements in retail and consumer goods push demand for pre-built templates and automated A/B testing frameworks.
- Designers:Direct creative cloud integration and asset versioning streamline cross-functional collaboration.
- Administrators:Role-based access controls and governance dashboards satisfy enterprise security mandates.
Procurement authority is consolidating with developers in technology and media organizations. Marketers retain primary vendor selection in retail and consumer goods verticals where campaign velocity outweighs architectural purity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of web content management platforms concentrates in the United States and Germany, while consumption spreads across healthcare networks in North America, automotive brands in Europe, and retail chains seeking omnichannel unification.
United States
Hospital systems and pharmaceutical distributors drive demand for HIPAA-compliant audit trails and patient-data isolation capabilities. FDA oversight of healthcare content accuracy shapes vendor product roadmaps and premium pricing structures. The Boston-Cambridge corridor hosts concentrated healthcare technology deployments where clinical review checkpoints integrate with automated patient communication flows.
Germany
Automotive and industrial brands are consolidating fragmented supplier portals and technical documentation stacks onto unified platforms. The EU AI Act mandates embedded transparency documentation and human-review checkpoints for automated personalization engines. Stuttgart and Munich anchor the steepest contract values as manufacturers unify content operations across multi-tier supplier networks.
United Kingdom
Media publishers are accelerating automated production pipelines while deploying guardrails for regulatory compliance. GDPR data-localization requirements drive sovereign cloud deployment decisions that fragment infrastructure investments. London's financial services and legal publishing clusters sustain heavy investment in semantic markup and version-controlled editorial workflows for AI training corpora.
France
Retail chains are migrating legacy stacks to eliminate hardware refresh cycles and accelerate omnichannel rollout timelines. The CNIL enforces GDPR implementation with specific guidance on automated decision-making transparency. Paris-based luxury brands and media publishers are investing in adaptive bitrate infrastructure and edge caching networks for immersive product demonstrations.
Japan
Enterprise manufacturers are adopting API-first architectures to serve emerging channels including voice interfaces and in-store displays. METI guidelines on data governance influence procurement criteria for content platforms with audit capabilities. Tokyo-Osaka industrial corridors demonstrate concentrated demand for JAMstack-compatible architectures that prioritize GraphQL endpoints and webhook extensibility.
Web Content Management Market Vendor Landscape
Top-tier vendors anchor enterprise accounts through deep creative cloud integration and bundled asset workflows, while mid-market specialists compete on API-first architecture and developer adoption. The vendor base organizes into three strategic archetypes: creative-suite incumbents leveraging ecosystem lock-in, headless pure-plays capturing JAMstack environments, and commerce-content convergence specialists. Dominant competitive moves include portfolio diversification into adjacent marketing automation segments and strategic partnerships with edge deployment networks.
Within the creative-suite tier, Adobe Experience Manager anchors enterprise positioning through deep integration with adjacent design tools. Contentful and Sitecore exemplify contrasting architectural philosophies—API-first modularity versus unified customer data layers—each capturing distinct procurement constituencies. Sanity occupies a position among developer-centric platforms prioritizing real-time collaboration and structured content primitives.
| Leading Market Players |
|---|
| Optimizely |
| Sanity |
| Adobe Experience Manager |
| WordPress VIP |
| Drupal |
| Sitecore |
| Contentstack |
| Kentico Xperience |
| Contentful |
| Others |
Supply Flow & Price Mechanics
Healthcare networks and pharmaceutical distributors in the United States anchor premium pricing power through HIPAA-mandated audit capabilities that standard SaaS vendors cannot replicate without substantial engineering investment. Subscription economics dominate vendor revenue models as enterprises abandon perpetual licenses for elastic consumption tiers.
Pricing Analysis
Margin tightening in mid-market tiers reflects substitution pressure from low-code page builders that sacrifice governance for deployment velocity. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification depth and integration complexity. Price differentiation hinges on vertical integration depth and after-sales service bundling. Healthcare buyers exhibit lowest price sensitivity due to regulatory non-negotiability, while education providers drive hardest bargain.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure compel vendors to maintain qualified deployments across multiple hyperscaler environments. Software production concentrates in the United States, Germany, and India, with engineering talent pools feeding platform development. Raw material dependencies center on compute capacity, bandwidth provisioning, and specialized AI training data. Single-source vulnerability sits with concentrated hyperscaler relationships. Distribution runs through direct enterprise sales and channel partner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor consolidation accelerates as composable architectures compress switching costs and API-first entrants erode incumbents' platform lock-in. Weaker players face elimination without differentiated compliance modules or developer ecosystem depth.
For Market Incumbents: To counter JAMstack-native challengers, Adobe and Sitecore must deepen creative cloud integration and embed EU AI Act transparency tooling into editorial workflows. Capacity addition in German automotive corridors and HIPAA certification investment in US healthcare networks defend margin position against modular disaggregation. For New Entrants and Emerging Players: API-first developer tooling offers the fastest penetration route into mid-market retailers seeking omnichannel velocity. White-space targets include French luxury brand content operations and Japanese manufacturer voice interface deployments. Go-to-market angle: edge deployment partnerships that compress content delivery latency. For Investors and Strategic Acquirers: The window for entry favors headless CMS specialists with established GraphQL endpoint architectures and webhook extensibility. Long-term viability rests on compliance-embedded premium modules that command pricing power in regulated verticals. Watch EU AI Act enforcement actions as inflection indicator for platform retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Adobe's creative cloud bundling anchors enterprise accounts against API-first challengers. |
| Strategic Partnership | Edge deployment network alliances compress latency for streaming-first retail content. |
| Acquisition of Specialist Firm | Healthcare compliance module targets capture HIPAA-mandated audit trail premiums. |
| Geographic Expansion | German automotive content consolidation creates concentrated contract values in Stuttgart. |
| Product Launch | EU AI Act transparency tooling opens upgrade cycles across European publishing workflows. |
Methodological Framework
Multi-period observation of deployment model migration patterns and developer adoption metrics anchored the trend analysis, supplemented by interviews with CTOs, platform engineers, IT procurement officers, and channel partners across North America and Europe. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie mobile deployment data, and healthcare procurement databases. Bottom-up vendor revenue triangulation against top-down enterprise IT spend estimates calibrated market sizing.
Input-output matrices mapped deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern to project segment trajectories across the analysis window. CAGRs derived from fitted growth curves applied to base-year observed values, with healthcare compliance premium and video streaming bandwidth cost curves as industry-specific forecast inputs.
The model holds under stable regulatory enforcement and continued cloud migration; deviation in EU AI Act implementation timelines or hyperscaler pricing volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Load Balancer Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Decision Support System Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market
Digital Solutions
Latin America Digital Signage Market
Digital Solutions
Event Apps Market
Digital Solutions
Service Fulfillment Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
Europe Digital Pen Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
IT Asset Management (ITAM) Software Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Self Service Technology Market