
 Communication Intelligence Market | 2026-2036
Communication Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Intelligence Market Outlook
Defense procurement channels is tilting toward integrated signals intelligence platforms that fuse real-time interception with predictive analytics. Lockheed Martin leverages decades of satellite communications expertise to anchor classified military contracts across NATO member states. Northrop Grumman sustains R&D intensity in software-defined radio architectures that enable adaptive spectrum dominance. L3Harris Technologies competes aggressively on price-performance for tactical edge systems deployed by coalition partners.
Communication intelligence encompasses the collection, processing, and exploitation of electromagnetic signals to extract actionable information from voice, data, and metadata transmissions, typically operating across frequency ranges from HF through millimeter-wave bands with sub-microsecond intercept latency requirements. Its primary purpose is enabling national security, law enforcement, and competitive organizations to anticipate threats, monitor adversaries, and protect critical information infrastructure. Natural language processing commands the fastest expansion within product type categories as multilingual neural models reduce analyst workload in real-time transcription and entity extraction. Cloud-based deployment absorbs disproportionate investment flow from enterprises seeking elastic compute for large-scale social media monitoring and compliance management applications. On-premises systems retain dominance in defense and classified settings where air-gapped architectures satisfy stringent data sovereignty mandates.
The Federal Communications Commission and National Security Agency jointly shape spectrum allocation and encryption export controls that determine which communication intelligence capabilities reach commercial versus restricted deployment. The EU AI Act imposes risk-tiered conformity assessments on automated sentiment analysis and social media monitoring tools, creating compliance cost barriers for non-European vendors. Stakeholders must monitor whether emerging quantum-resistant encryption standards force premature obsolescence of existing intercept and decryption infrastructure.
Market Dynamics
Defense procurement is pivoting from hardware-centric intercept systems toward AI-native signal processing architectures that compress analyst-to-decision timelines from hours to seconds. This structural reorientation is compressing vendor margins on legacy equipment while rewarding software-defined platforms with embedded machine learning inference engines.
Growth Catalysts
- EU AI Act compliance mandates:European security agencies must upgrade automated monitoring systems to satisfy risk-tiered conformity assessments, creating replacement demand for certified platforms.
- 5G network densification:Telecommunications infrastructure expansion multiplies interception points for lawful intelligence collection, requiring scalable spectrum monitoring solutions across sub-6 GHz and mmWave bands.
- Electronic warfare cluster concentration in Israel:Dense supplier ecosystems around Haifa and Tel Aviv accelerate technology transfer into allied defense procurement channels.
Market Restraints
- Gallium nitride substrate supply concentration:Critical wide-bandgap semiconductor materials for high-frequency front-ends depend on Chinese and Japanese refining capacity, exposing chokepoint vulnerability.
- Quantum-resistant encryption standardization lag:NIST post-quantum cryptographic algorithms remain in draft status, freezing long-term intercept infrastructure investment decisions.
- Skilled RF engineer scarcity:Specialized talent pools for analog-digital signal conversion and low-latency firmware development concentrate in defense-adjacent labor markets with security clearance barriers.
Strategic Opportunities
- Cloud-native deployment in commercial financial surveillance:Banks and payment processors seek elastic compute for real-time transaction monitoring, opening non-defense revenue streams.
- Swedish and Finnish NATO accession:New member states must harmonize signals intelligence interoperability standards, generating platform standardization contracts.
- Convergence of software-defined radio with edge AI accelerators:On-device inference enables tactical units to process intercepts without backhaul dependency, reducing detection signatures.
Industry Challenges
- TS/SCI clearance pipeline constriction:Defense contractor hiring timelines stretch to 18-24 months for positions requiring sensitive compartmented information access, throttling engineering team scaling.
- Legacy analog system integration complexity:Decades-old HF intercept archives resist automated transcription, forcing expensive manual migration or parallel infrastructure maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Intelligence Market |
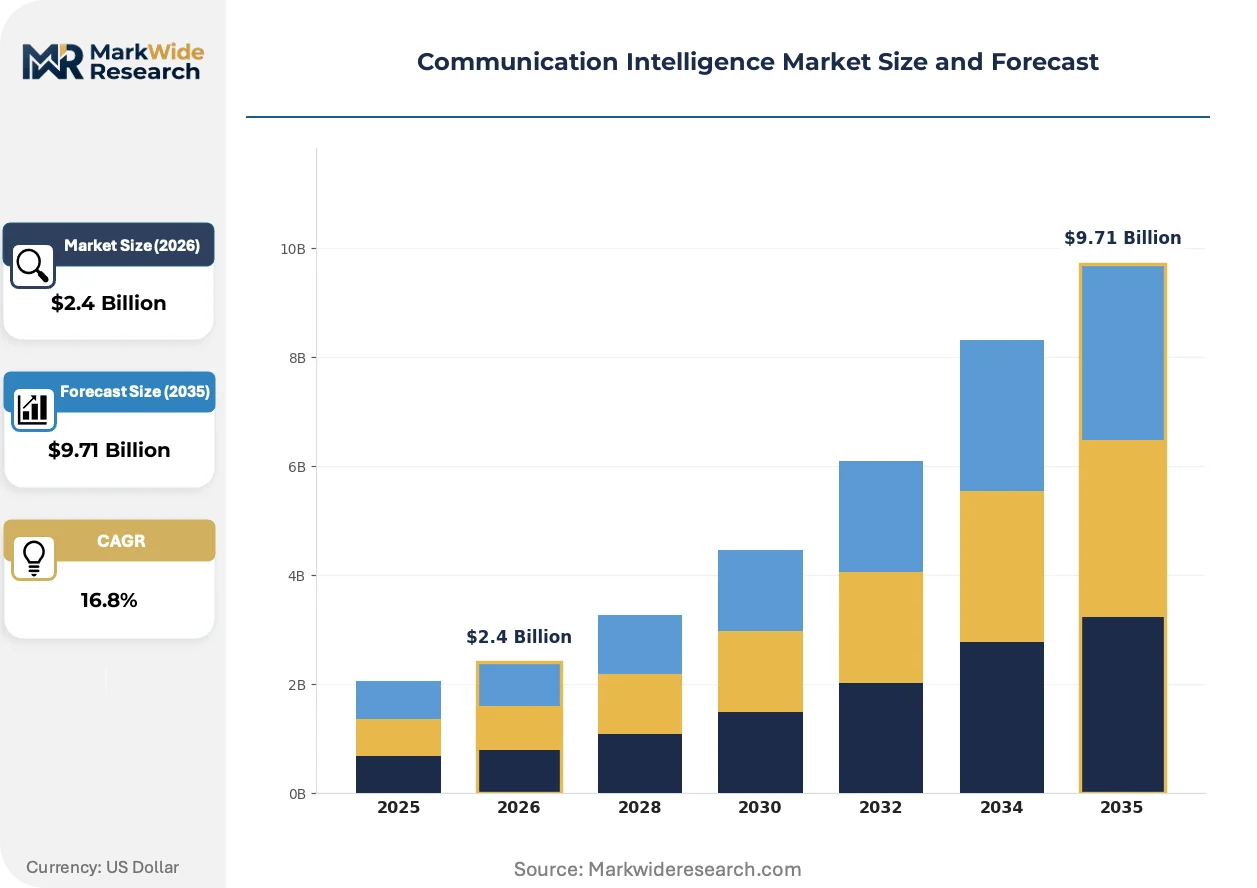
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $9.71 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Speech Analytics, Voice Recognition, Sentiment Analysis, Natural Language Processing End User: Customer Support, Market Research, Sales, Human Resources Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Application: Corporate Communication, Social Media Monitoring, Competitive Intelligence, Compliance Management |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, Raytheon Technologies Corporation, General Dynamics Corporation, BAE Systems plc, L3Harris Technologies, Inc., Thales Group, Elbit Systems Ltd., Israel Aerospace Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Intelligence Market Strategic Shifts
Signal processing architectures are abandoning centralized server farms for distributed edge computing nodes that enable real-time decision-making without bandwidth-intensive data exfiltration. This topological inversion is redrawing competitive boundaries between hardware suppliers and software platform vendors.
Software-defined radio is migrating from military-specified fixed-function hardware toward commercial-off-the-shelf modular architectures with field-programmable gate arrays. Intelligence community buyers in the United States and United Kingdom are accelerating procurement of these reconfigurable platforms. The technology is migrating from specialized defense primes toward tier-two suppliers with consumer electronics manufacturing scale, compressing unit costs and shortening refresh cycles.
The EU AI Act imposes mandatory conformity assessments on automated sentiment analysis and social media monitoring tools deployed in European jurisdictions. Vendors must document training data provenance and algorithmic bias mitigation measures before market entry. High-risk system categories face recurring audit obligations that favor established defense contractors with dedicated compliance infrastructure over emerging entrants.
Lawful intercept procurement is fragmenting from national-scale integrated programs toward modular component acquisitions that agencies assemble through systems integration contracts. European telecommunications regulators are mandating technical capability specifications that standardize interface protocols between network operators and government collection systems. This unbundling trend is most visible in Germany and France, where interior ministries now separately procure collection hardware, analytics software, and storage infrastructure.
Communication Intelligence Market Segmentation
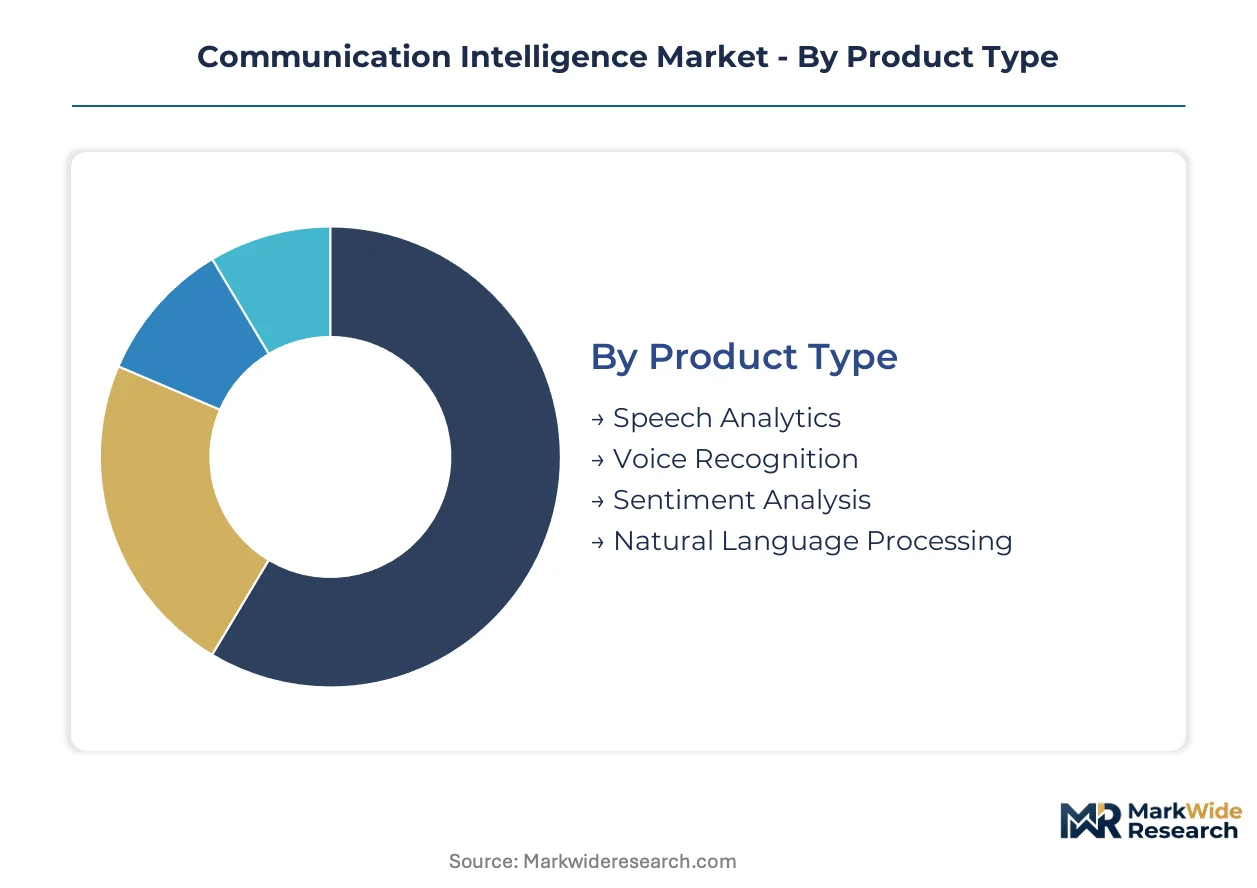
Communication intelligence procurement splits sharply between defense-grade systems with decade-long refresh cycles and commercial platforms that iterate quarterly. Understanding where each segment sits on this velocity spectrum determines vendor R&D allocation and partnership strategy.
Product Type:
Refresh cycles vary from eighteen months for cloud-native language models to seven years for hardened signal processing hardware, creating divergent margin profiles across this category.
- Speech Analytics:Real-time transcription engines process voice streams with sub-second latency for call center quality assurance and lawful intercept applications. Financial services firms in the United States drive replacement demand as PCI-DSS audit requirements tighten storage and retrieval specifications.
- Natural Language Processing:Multilingual transformer architectures extract entities and relationships from unstructured text across electromagnetic intercepts and open-source feeds. Israeli defense procurement channels absorb disproportionate volumes as the IDF integrates NLP into tactical edge systems for Hebrew-Arabic code-switching detection.
- Voice Recognition:Speaker identification algorithms match biometric voiceprints against watchlists for fraud prevention and targeted surveillance.
- Sentiment Analysis:Emotion classification models score text polarity for brand monitoring and social media threat detection, now subject to EU AI Act conformity assessments.
Speech Analytics anchors the volume base while Natural Language Processing gains share at the steepest rate.
End User:
Cost tiers separate enterprise SaaS subscriptions from classified government contracts with dedicated infrastructure mandates.
- Customer Support:Automated quality management platforms transcribe and score agent interactions for compliance and coaching. Cloud deployment dominates as Fortune 500 contact centers abandon on-premises Avaya and Cisco installations for elastic AWS and Azure instances.
- Market Research:Consumer intelligence teams apply conversation analysis to focus groups and ethnographic interviews. European pharmaceutical panels under EMA pharmacovigilance guidelines require auditable transcript chains that favor specialized vendors over generalist platforms.
- Sales:Conversation intelligence tools capture and analyze revenue team calls for deal coaching and forecast accuracy.
- Human Resources:Interview transcription and bias detection applications face GDPR Article 22 restrictions on automated decision-making in European jurisdictions.
Customer Support commands the largest installed base as Market Research climbs fastest on generative AI-enabled synthetic respondent testing.
Deployment:
Volume concentration sits with hyperscaler-hosted solutions while margin pools concentrate in air-gapped and sovereign cloud configurations.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for social media monitoring and financial surveillance without capital expenditure. FedRAMP authorization gates limit vendor participation in United States federal civilian opportunities.
- On-Premises:Physically isolated hardware satisfies TS/SCI compartmentalization requirements for signals intelligence processing. German BND and French DGSE facilities mandate on-site decryption to prevent foreign data access.
- Hybrid:Split architectures process sensitive data locally while pushing analytics workloads to commercial clouds.
- Managed Services:Outsourced operations teams handle system administration and analyst staffing for agencies lacking technical depth.
Cloud-Based deployment carries the volume weight as On-Premises expands most quickly on NATO member hardening requirements.
Application:
Maturity gradients separate established compliance use cases from emerging competitive intelligence automation.
- Compliance Management:Record-keeping and surveillance systems satisfy MiFID II, GDPR, and SEC retention mandates for financial and telecommunications sectors. Bloomberg and Refinitiv terminal integration creates switching costs that entrench incumbent vendors.
- Social Media Monitoring:Open-source intelligence platforms scrape and analyze public posts for threat indication and disinformation tracking. Brazil's ANPD and India's proposed Digital Personal Data Protection Bill impose consent and purpose-limitation constraints on automated collection.
- Corporate Communication:Internal collaboration analysis measures workforce sentiment and information flow patterns.
- Competitive Intelligence:Automated rival tracking extracts pricing, product, and strategy signals from earnings calls and patent filings.
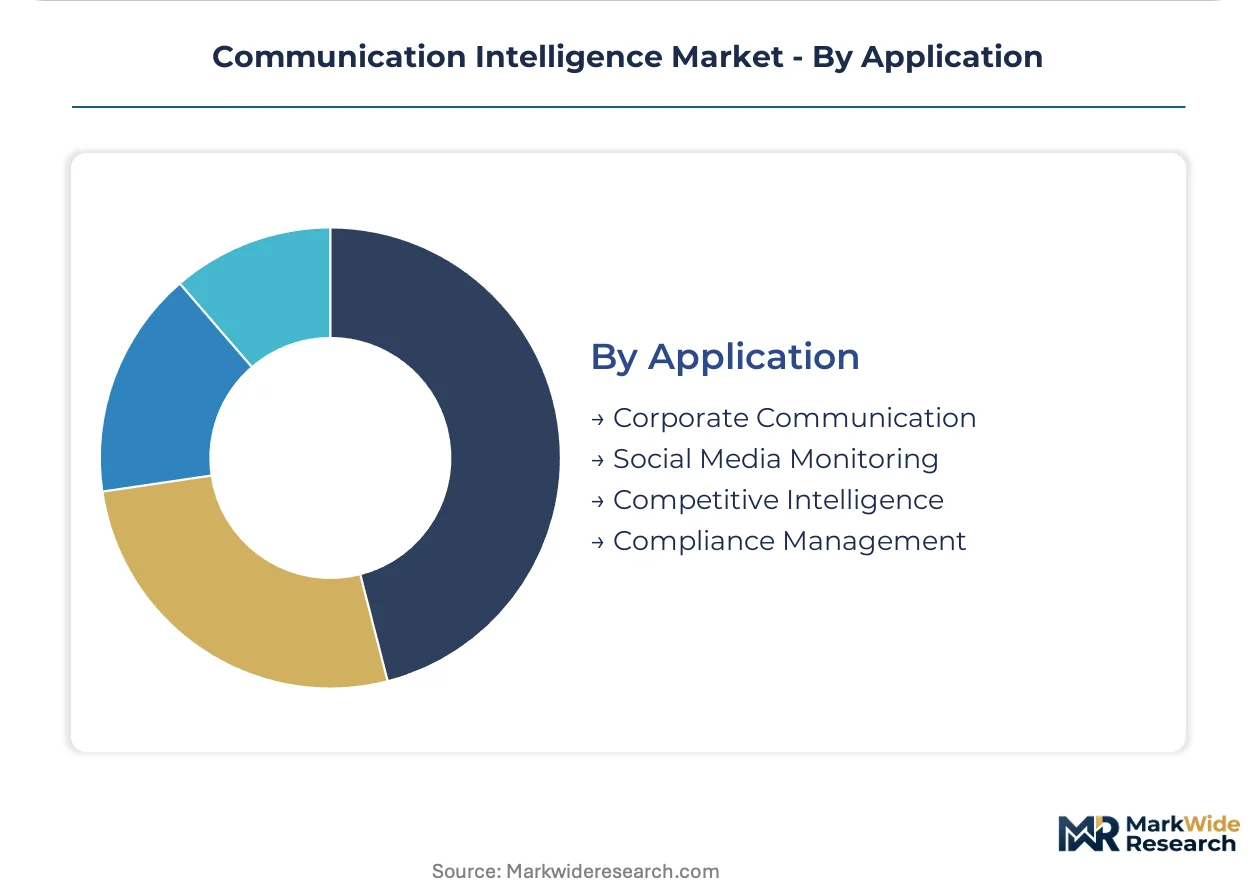
Compliance Management holds the volume anchor as Social Media Monitoring scales fastest on election security and counter-disinformation budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Communications Commission and National Security Agency jointly shape spectrum allocation and encryption export controls that determine which communication intelligence capabilities reach commercial versus restricted deployment in the United States. Defense procurement channels across NATO member states are accelerating investment in AI-enabled signal processing platforms.
United States
Defense agencies and intelligence communities accelerate procurement of integrated signals intelligence platforms that fuse real-time interception with predictive analytics. The Federal Communications Commission shapes spectrum allocation policies that determine commercial deployment boundaries. Lockheed Martin leverages decades of satellite communications expertise to anchor classified military contracts across multiple federal agencies.
Israel
Electronic warfare and signals intelligence expertise concentrates around Haifa and Tel Aviv, accelerating technology transfer into allied defense procurement channels. Dense supplier ecosystems anchor a national specialization in adaptive spectrum dominance. Elbit Systems and Israel Aerospace Industries represent the core industrial cluster driving regional export competitiveness.
Germany
The German BND mandates on-site decryption infrastructure to prevent foreign data access, sustaining demand for air-gapped system architectures. EU AI Act compliance requirements tighten procurement specifications for automated communication analysis systems. Interior ministries in Berlin separately procure collection hardware, analytics software, and storage infrastructure.
United Kingdom
Intelligence community buyers accelerate procurement of software-defined radio platforms with field-programmable gate arrays. The UK regulator framework aligns with NATO interoperability standards for signals intelligence sharing. London-based systems integrators assemble modular component acquisitions into national-scale collection programs.
France
The French DGSE mandates physically isolated hardware for compartmentalized signals intelligence processing, sustaining on-premises deployment dominance. EU AI Act risk-tiered conformity assessments create compliance cost barriers for non-European vendors. Paris-based interior ministries now unbundle lawful intercept procurement into separate hardware, software, and infrastructure contracts.
Communication Intelligence Market Competitive Environment
Defense primes and technology integrators split the market between hardware-centric legacy systems and software-defined AI-native architectures. The vendor structure concentrates around established contractors with security clearance infrastructure and dedicated compliance teams. Tier-one defense primes and tier-two technology specialists represent the dominant strategic archetypes. Competitive moves center on M&A activity targeting software-defined radio capabilities and strategic partnerships for cloud-native deployment.
Among United States-based defense contractors, Lockheed Martin, Northrop Grumman, and L3Harris Technologies exemplify the tier-one prime archetype. Lockheed Martin occupies a position representing satellite communications specialization. Northrop Grumman sits within the software-defined radio architecture segment. L3Harris Technologies anchors the tactical edge systems tier competing on price-performance metrics for coalition partner deployments.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| General Dynamics Corporation |
| BAE Systems plc |
| L3Harris Technologies, Inc. |
| Thales Group |
| Elbit Systems Ltd. |
| Israel Aerospace Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Haifa's dense concentration of RF engineering talent and GaN substrate processing facilities concentrates pricing power among Israeli defense electronics suppliers serving NATO procurement channels. Gallium nitride wafer shortages from Japanese and Chinese refiners transmit cost volatility downstream, forcing tier-two vendors to absorb margin compression or risk contract loss.
Pricing Analysis
Price spreads between Tel Aviv-engineered tactical edge systems and commoditized commercial intercept hardware stretch across an order of magnitude. Three-tier pricing structure across premium, standard, and economy levels separates TS/SCI-cleared platforms with embedded AI inference from unclassified SaaS monitoring tools. Pricing pressure stems from cloud-native entrants undercutting on-premises deployments with elastic compute economics. Commercial financial surveillance buyers exhibit acute price sensitivity, while defense primes with decade-long refresh cycles prioritize performance over unit cost.
Supply Chain Analysis
Tariff exposure between United States and Chinese semiconductor equipment dominates supply chain risk planning for RF front-end manufacturers. Critical wide-bandgap substrate supply draws from Japanese and Chinese refining capacity, with specialized FPGA packaging concentrated in Taiwan and South Korea. Single-source vulnerability around GaN-on-SiC epitaxy services threatens production continuity for millimeter-wave intercept systems. Distribution runs through defense prime integrators with security-cleared logistics networks, bypassing commercial electronics channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Communication intelligence sits in early-cycle expansion as AI-native signal processing displaces legacy hardware architectures across defense and commercial surveillance applications. NATO interoperability mandates and EU AI Act compliance deadlines accelerate replacement demand beyond organic growth rates.
For Market Incumbents: Insulate classified contract margins by deepening captive GaN substrate supply relationships and accelerating field-programmable gate array integration roadmaps. Software-defined radio commoditization from tier-two suppliers threatens hardware-centric revenue streams; counter through TS/SCI-cleared service bundling and sovereign cloud deployment certifications. For New Entrants and Emerging Players: Scandinavian NATO accession states represent underpenetrated demand for signals intelligence interoperability platforms. Cloud-native financial surveillance in European banking hubs offers the most penetrable commercial entry point, with MiFID II compliance budgets creating immediate procurement authority. Pursue FedRAMP authorization as the critical go-to-market gate for United States federal civilian opportunities. For Investors and Strategic Acquirers: Long-term, this sits as a dual-use technology play because defense-grade signal processing architectures migrate into commercial financial surveillance and lawful intercept markets with minimal adaptation. Acquisition targets should display software-defined radio expertise paired with existing security clearance infrastructure. Monitor NIST post-quantum cryptographic standardization timelines as the inflection signal for intercept infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Integration | Enables adaptive spectrum dominance across NATO interoperability standards without hardware refresh cycles. |
| EU AI Act Compliance Certification | Unlocks European law enforcement and intelligence agency procurement channels for automated monitoring systems. |
| GaN Substrate Supply Agreement | Secures wide-bandgap semiconductor feedstock critical for millimeter-wave intercept front-end performance. |
| Cloud-Native Deployment Architecture | Captures commercial financial surveillance demand with elastic compute economics absent capital expenditure barriers. |
| Strategic Partnership with Israeli Defense Cluster | Accelerates technology transfer from Haifa-Tel Aviv electronic warfare expertise into allied procurement channels. |
Study Parameters
The analysis maps signal processing hardware, AI-native analytics platforms, and lawful intercept infrastructure, each validated through signals intelligence program officers, RF engineering directors, and defense procurement executives. Primary fieldwork combined structured interviews with secondary triangulation against NSA encryption export control filings, FCC spectrum allocation dockets, and EU AI Act conformity assessment guidelines. Bottom-up segment sizing and top-down macro validation converged through iterative stakeholder feedback loops.
Assumptions held fixed include sustained NATO defense spending commitments and continued GaN substrate supply availability from Japanese refiners; varied assumptions encompassed NIST post-quantum cryptography standardization timelines and EU AI Act enforcement intensity. The analytical framework modeled deployment mode, end-user security classification tier, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level adoption curves weighted by procurement pipeline visibility and technology refresh cycle dynamics.
Practitioners should monitor quantum-resistant encryption standardization progress and gallium nitride supply chain disruptions for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Global Procurement-As-A-Service (PAAS) Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Data Integration Market
Digital Solutions
Cloud Based Manufacturing Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Web Content Management Market