
 Shipping Software Market | 2026-2036
Shipping Software Market Size, Share, and Industry Trends Forecast 2026-2036
Shipping Software Market Intelligence
Platform licensing revenue is reconfiguring margin pools away from perpetual on-premises installations toward recurring SaaS arrangements. Descartes Systems Group leverages its customs compliance engine to sustain premium pricing across North American freight corridors. SAP SE anchors enterprise-grade deployments through deep ERP integration, while Manhattan Associates dominates warehouse execution layers that feed shipping orchestration logic.
Shipping software encompasses carrier selection, label generation, rate shopping, and delivery tracking systems that interface with transportation management platforms via standardized APIs and EDI protocols. Cloud-based deployment leads segment adoption as mid-market shippers abandon server maintenance overhead, though hybrid architectures retain traction among multinationals with legacy warehouse management investments. Route optimization functionality captures disproportionate R&D allocation as fuel volatility pressures logistics providers to minimize empty miles.
FDA traceability rules for pharmaceutical shipments, EU CSRD emissions disclosure requirements, and US FAA drone delivery frameworks collectively tighten compliance burdens that software vendors must encode into platform logic. The EU AI Act will soon classify autonomous routing algorithms, forcing vendors to document decision transparency. Stakeholders should monitor which carriers open their operational data APIs, as data reciprocity terms will determine which software platforms achieve network effects.
Market Dynamics
Carrier API standardization and real-time freight visibility requirements are compressing vendor differentiation windows, forcing platforms to embed compliance logic directly into execution layers rather than bolt-on modules.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain shippers must document refrigerant emissions across multimodal legs, triggering procurement of carbon-tracking modules integrated with carrier selection algorithms.
- Mid-market e-commerce:Merchants operating Shopify and WooCommerce storefronts are abandoning manual rate shopping for automated label-generation workflows that sync directly with warehouse management systems.
- Last-mile drone frameworks:US FAA Part 135 certification pathways for autonomous aerial delivery are opening pilot zones in Texas and North Carolina, creating demand for fleet orchestration software that coordinates ground and air assets.
Market Restraints
- Cloud infrastructure concentration:AWS and Azure outages in 2023 exposed single-dependency risks for SaaS-native shipping platforms serving peak-season volumes.
- Legacy EDI protocol lock-in:Major US retailers still mandate X12 856 and 214 document standards, forcing API-first vendors to maintain expensive translation gateways.
- Freight rate volatility:Container spot markets swinging between Asia and North America corridors compress margin predictability for software vendors pricing on transaction volumes.
Strategic Opportunities
- India DGFT digitization:The country's customs modernization program is mandating pre-arrival data submission, creating whitespace for compliance-integrated shipping platforms in Mumbai and Chennai port zones.
- EU CSRD emissions disclosure:Corporate sustainability reporting mandates are forcing logistics buyers to procure carbon accounting modules that aggregate multi-carrier footprint data.
- Blockchain-IoT convergence:Pharmaceutical shippers are piloting temperature-verified smart contracts for FDA-regulated lanes, opening premium subscription tiers for immutable chain-of-custody documentation.
Industry Challenges
- API talent scarcity:Vendors struggle to hire engineers fluent in both legacy EDI X12 standards and modern REST architectures, delaying hybrid integration timelines.
- Carrier data reciprocity negotiations:Freight forwarders resist opening operational APIs without revenue-sharing agreements, constraining network-effect formation for neutral software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipping Software Market |
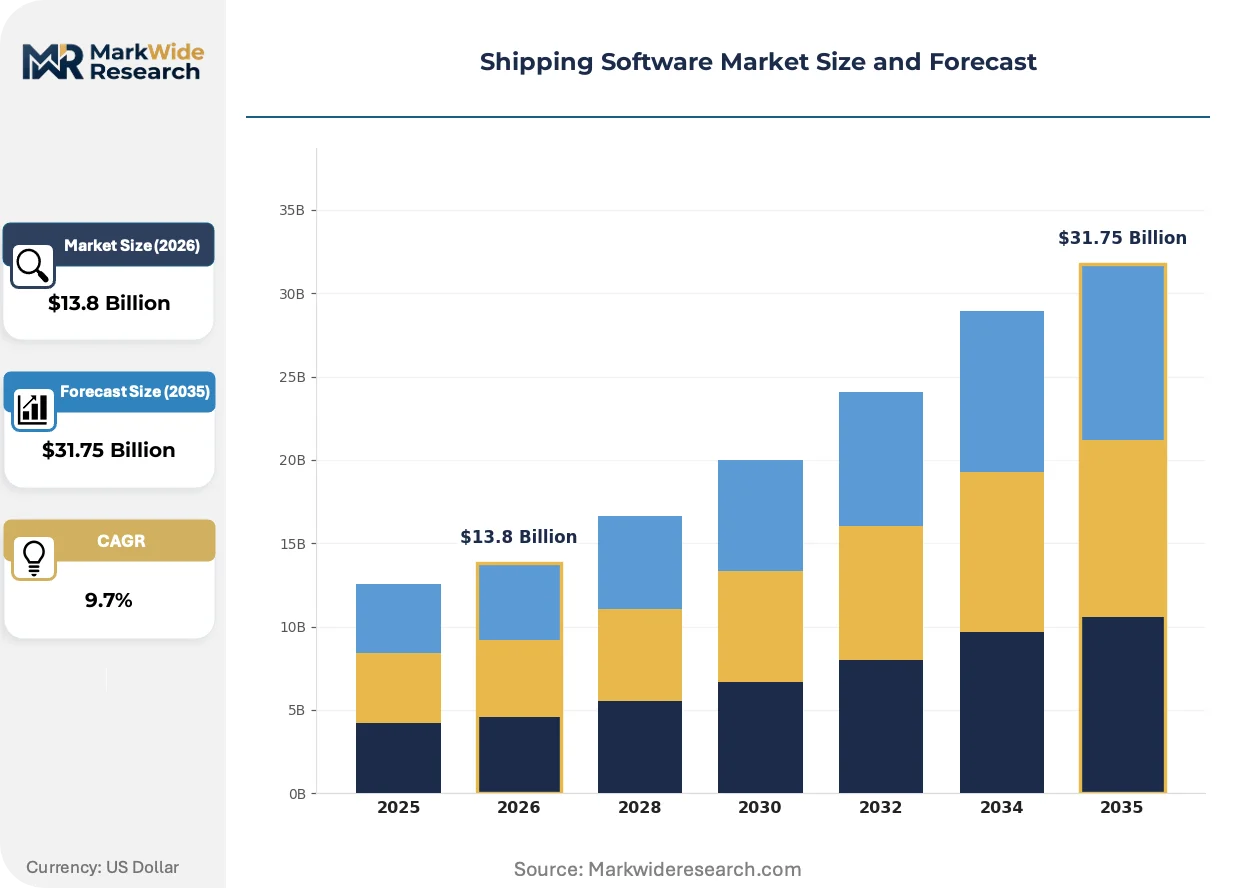
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $31.75 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: E-Commerce, Logistics Providers, Freight Forwarders, Retailers Functionality: Tracking, Billing, Inventory Management, Route Optimization Integration Level: APIs, Third-Party Solutions, ERP, CRM |
| Companies Covered | Logistyx Technologies, AfterShip, Descartes Systems Group, EASYPOST, Proship Inc., ShipStation, ShippingEasy, Manhattan Associates, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipping Software Market Strategic Shifts & Innovations
Machine-learning inference at the edge and autonomous routing algorithms are redistributing computational load away from centralized cloud instances toward distributed warehouse and vehicle nodes.
Real-time computer vision for package-damage detection is rendering obsolete manual inspection stations at sortation hubs. Third-party logistics providers in the Netherlands and Belgium are deploying camera arrays at conveyor junctions, compressing claims-resolution cycles from weeks to hours. The technology is rendering obsolete quality-control labor pools that previously represented fixed cost anchors.
EU AI Act classification requirements for autonomous decision systems are forcing vendors to document algorithmic transparency in route-optimization engines. Logistics software providers must now maintain audit trails explaining why specific carriers were selected. German freight corridors and Benelux distribution networks face the tightest compliance timelines as national regulators transpose the framework.
Subscription-based procurement of shipping software is displacing perpetual license arrangements among mid-market merchants. Annual recurring revenue models now dominate vendor pricing structures, compressing upfront implementation fees in favor of usage-scaled tiers. This shift is most visible among direct-to-consumer brands in California and New York that prioritize cash-flow flexibility over capital expenditure.
Shipping Software Market Segmentation
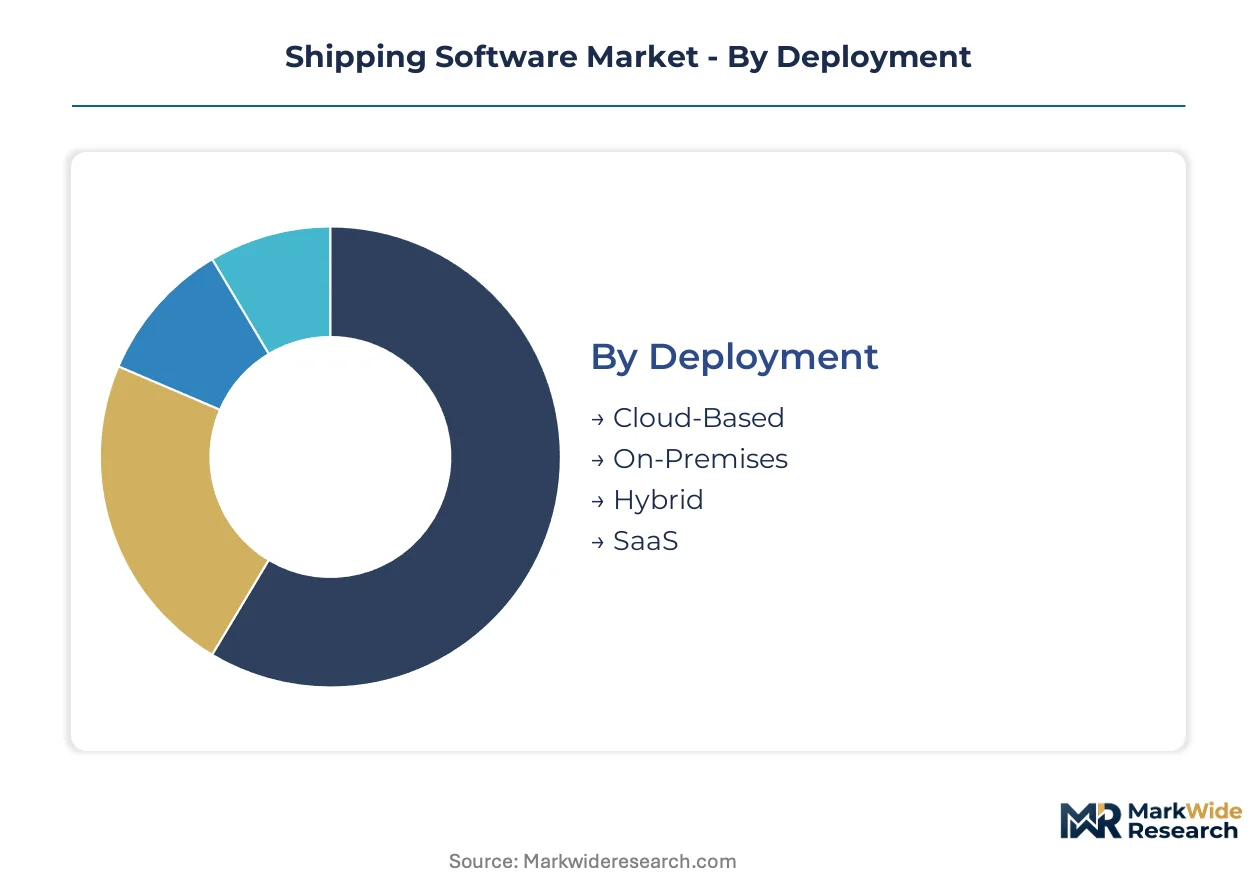
Shipping software vendors architect their product portfolios around four distinct axes that determine pricing power and implementation complexity. Deployment models dictate infrastructure ownership, while end-user profiles shape compliance requirements and integration depth. Functionality bundles separate commodity label generation from premium optimization engines.
Deployment:
Mature on-premises installations coexist with emerging serverless architectures as buyers weigh control against operational agility.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance overhead for mid-market shippers. California direct-to-consumer brands and New York apparel merchants prioritize these deployments for Black Friday elasticity.
- On-Premises:Single-tenant installations behind corporate firewalls serve defense contractors and pharmaceutical distributors with data sovereignty mandates. German automotive suppliers maintain these stacks for production-line integration.
- Hybrid:Split workloads keep rate-shopping logic in-cloud while warehouse execution remains local. Multinationals with legacy WMS investments in Benelux distribution networks favor this architecture.
- SaaS:Subscription pricing with usage-scaled tiers dominates procurement among Shopify and WooCommerce merchants. Annual recurring revenue models now displace perpetual licenses across North American freight corridors.
Cloud-Based handles the majority of throughput; SaaS is expanding most quickly on share.
End User:
Customer type determines whether procurement emphasizes carrier neutrality or captive fleet control.
- E-Commerce:Automated label generation and returns processing for marketplace sellers. Demand concentrates among California and New York direct-to-consumer brands replacing manual rate shopping.
- Logistics Providers:Multi-tenant platforms managing freight for shipper portfolios. Third-party operators in Netherlands and Belgium deploy computer vision at sortation hubs.
- Freight Forwarders:Customs compliance engines and multimodal document workflows. Mumbai and Chennai port zones drive procurement as India DGFT digitization mandates pre-arrival data submission.
- Retailers:Store-fulfillment and buy-online-pickup-in-store orchestration. Major US retailers still mandate X12 856 and 214 EDI standards, forcing API-first vendors to maintain translation gateways.
E-Commerce commands the largest procurement volume; Freight Forwarders are gaining share fastest as customs automation tightens.
Functionality:
Feature depth separates commodity modules from premium optimization engines that capture disproportionate R&D investment.
- Tracking:Real-time visibility via carrier APIs and IoT sensor feeds. Pharmaceutical shippers pilot temperature-verified blockchain-IoT smart contracts for FDA-regulated lanes.
- Billing:Freight audit and parcel invoice reconciliation. Fuel volatility across Asia-North America corridors compresses margin predictability for transaction-volume pricing.
- Inventory Management:Warehouse execution layers feeding shipping orchestration logic. Manhattan Associates dominates this segment through deep WMS integration.
- Route Optimization:Machine-learning inference for minimizing empty miles. EU AI Act classification requirements now force vendors to document algorithmic transparency in carrier selection decisions.
Tracking anchors baseline procurement; Route Optimization shows the steepest expansion trajectory as fuel costs pressure logistics providers.
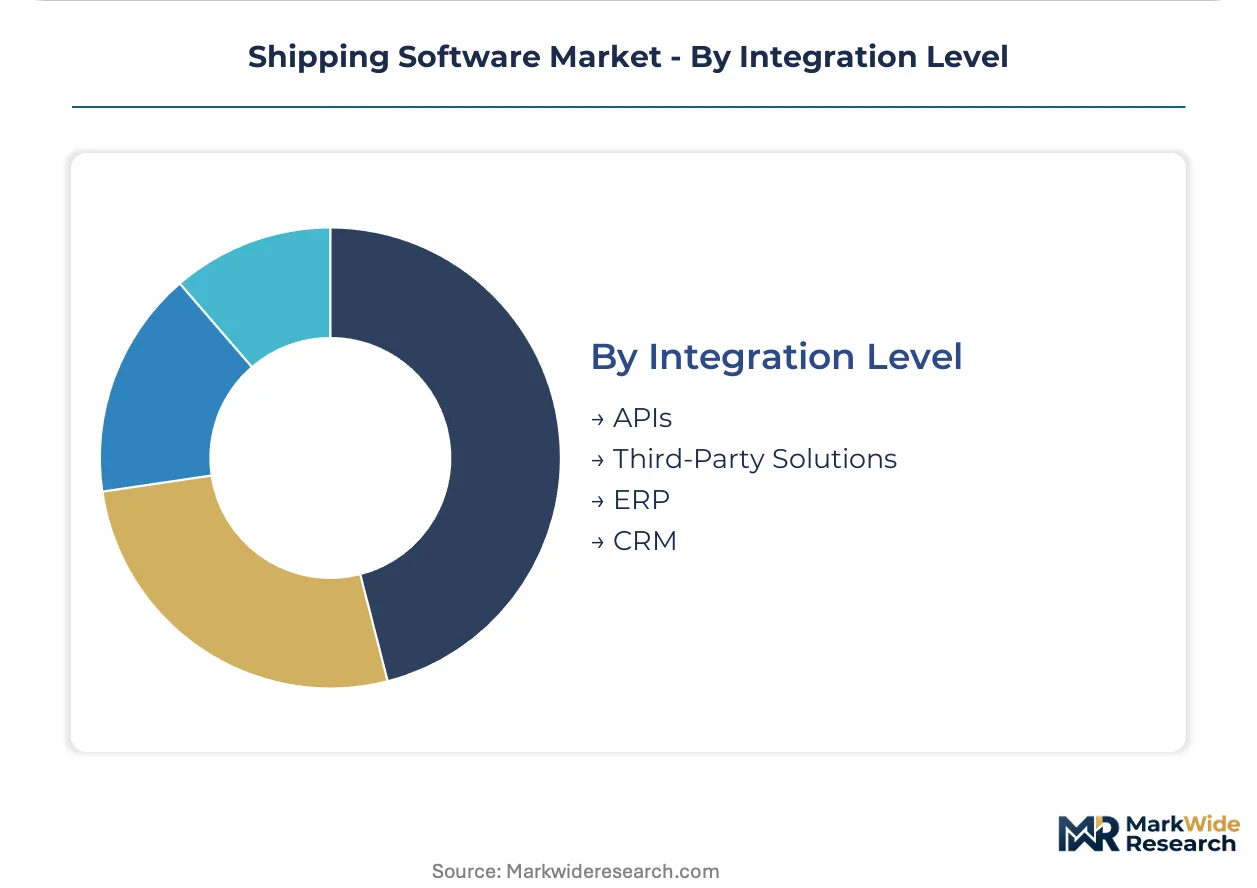
Integration Level:
Connectivity architecture determines whether platforms achieve network effects or remain siloed point solutions.
- APIs:RESTful and GraphQL interfaces for real-time carrier connectivity. Vendors struggle to hire engineers fluent in both legacy EDI X12 standards and modern REST architectures.
- Third-Party Solutions:Pre-built connectors for marketplace and storefront platforms. Shopify and WooCommerce ecosystems drive standardization here.
- ERP:Deep financial and procurement system integration. SAP SE anchors enterprise-grade deployments through this connectivity layer.
- CRM:Customer data synchronization for delivery experience management. Direct-to-consumer brands prioritize this integration for post-purchase communication workflows.
APIs carry the highest integration volume; ERP connectivity is climbing fastest as enterprises consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: North American merchants prioritize SaaS elasticity for peak-season volumes, while European buyers embed compliance modules for emissions tracking, and Asian procurement centers on customs automation for export manufacturing corridors.
United States
Direct-to-consumer brands in California and New York drive SaaS adoption for automated label generation and returns processing. The FAA's Part 135 certification pathways for drone delivery are opening pilot zones in Texas and North Carolina, creating demand for fleet orchestration software that coordinates ground and air assets. Amazon and Shopify ecosystems concentrate procurement volume in Seattle and San Francisco metro areas.
Germany
Automotive suppliers and pharmaceutical distributors anchor on-premises installations behind corporate firewalls for production-line integration. The EU F-Gas Regulation mandates refrigerant emissions documentation across multimodal cold chains, triggering procurement of carbon-tracking modules. Port digitization investments in Hamburg and multimodal integration projects in the Ruhr Valley accelerate software procurement for freight corridors.
India
Export manufacturers in Mumbai and Chennai port zones are modernizing customs workflows ahead of DGFT digitization mandates for pre-arrival data submission. Freight forwarders drive fastest-expanding procurement as compliance automation tightens. The country's PLI scheme for logistics infrastructure is concentrating vendor activity in Maharashtra and Gujarat industrial corridors.
Netherlands
Third-party logistics providers deploy computer vision arrays at sortation hubs in Rotterdam and Venlo distribution zones, compressing claims-resolution cycles from weeks to hours. The EU CSRD emissions disclosure requirements are forcing logistics buyers to procure carbon accounting modules. Benelux distribution networks face tightest compliance timelines as national regulators transpose the EU AI Act framework.
United Kingdom
Post-Brexit customs complexity drives demand for multimodal document workflows and carrier-neutral rate shopping. London-based freight forwarders prioritize API-first platforms that bridge legacy EDI X12 standards with modern REST architectures. The country's departure from EU regulatory alignment is creating whitespace for compliance-integrated shipping platforms serving cross-channel trade lanes.
Shipping Software Market Key Industry Players
Capability concentration sits with specialized compliance engines and warehouse execution layers; scale advantage sits with ERP-anchored enterprise suites and multi-tenant SaaS platforms. The market structures around three archetypes: customs compliance specialists commanding premium pricing, warehouse execution dominants feeding shipping orchestration logic, and API-native challengers displacing manual rate shopping. Consolidation pressure is mounting through strategic partnerships between carrier networks and software platforms, plus vertical integration moves by logistics providers into proprietary technology stacks.
Within the customs compliance tier, Descartes Systems Group and SAP SE occupy positions at opposite ends of the integration spectrum—Descartes anchoring freight corridor premium pricing through specialized engines, SAP anchoring enterprise-grade deployments through deep ERP connectivity. Manhattan Associates exemplifies the warehouse execution archetype that dominates fulfillment layers feeding downstream shipping logic. These three names surface repeatedly across procurement conversations in North American and European freight corridors.
| Leading Market Players |
|---|
| Logistyx Technologies |
| AfterShip |
| Descartes Systems Group |
| EASYPOST |
| Proship Inc. |
| ShipStation |
| ShippingEasy |
| Manhattan Associates |
| SAP SE |
| Others |
Cost & Logistics Intelligence
Hamburg's port digitization investments and multimodal integration corridors concentrate software engineering capacity for European freight compliance, compressing margin pools for vendors lacking localized development presence. German automotive suppliers and pharmaceutical distributors anchor premium pricing for on-premises installations with data sovereignty mandates, while California direct-to-consumer brands drive SaaS elasticity through usage-scaled subscription tiers.
Pricing Analysis
Long-term enterprise contracts with annual recurring revenue commitments dominate procurement among Fortune 500 logistics buyers, compressing upfront implementation fees in favor of per-transaction scaling. Three-tier pricing structure across premium, standard, and economy levels separates customs compliance engines with AI Act audit trails from basic label-generation modules. Cost compression in the mid-market tier is intensifying because Shopify and WooCommerce merchants prioritize cash-flow flexibility over capital expenditure. Small freight forwarders in India exhibit highest price sensitivity, while German automotive suppliers demonstrate lowest sensitivity due to production-line integration requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates vendor supply chain risk profiles as hyperscaler infrastructure dependencies concentrate in AWS and Azure regions. Software engineering talent draws from India, Poland, and Romania for API development, while legacy EDI protocol expertise rests on aging specialist pools in the United States and Germany. Single-source vulnerability in cloud infrastructure exposes SaaS-native platforms to peak-season outage risks. Distribution runs through direct sales teams for enterprise accounts and marketplace integrations for mid-market merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
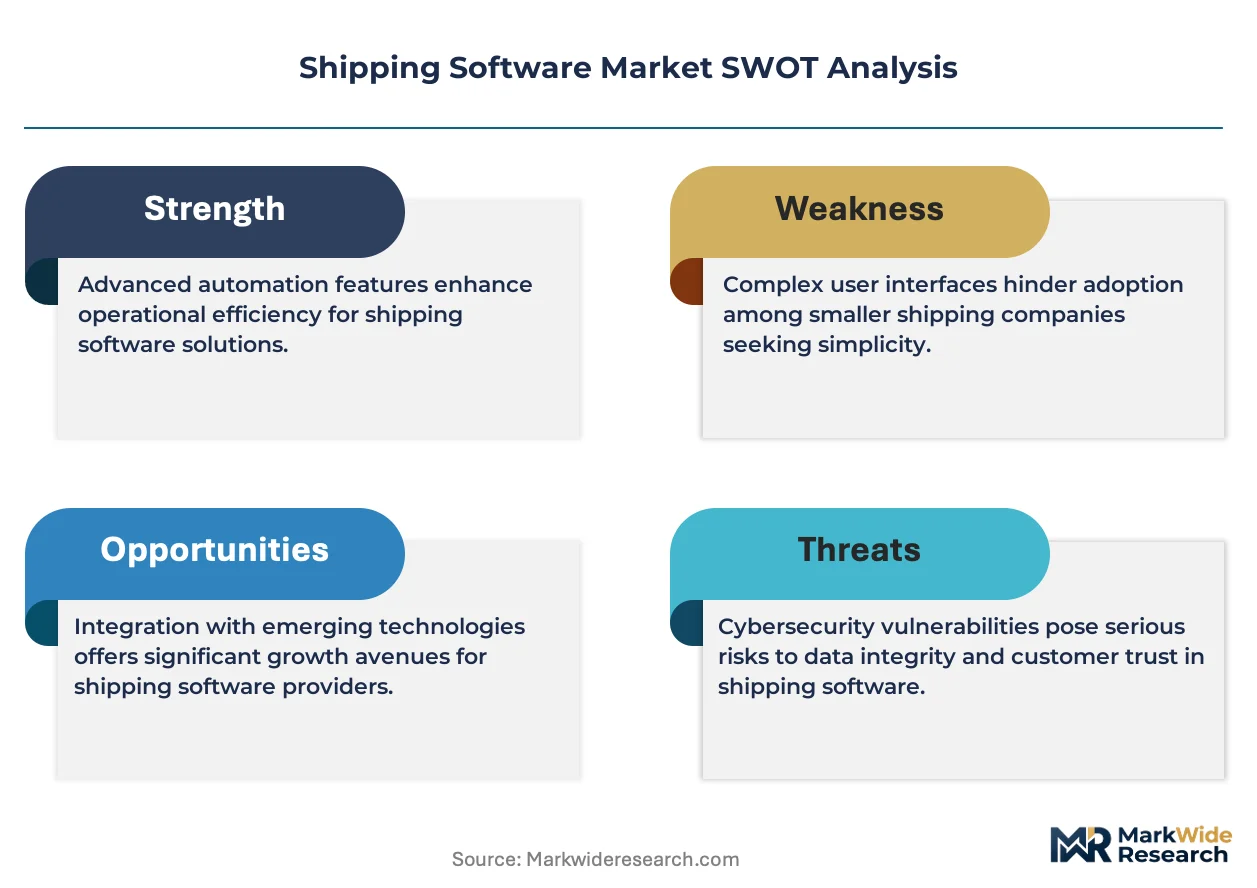
The shipping software market sits at an inflection point where EU AI Act classification requirements for autonomous routing algorithms are forcing vendors to document decision transparency or forfeit premium pricing power.
For Market Incumbents: Harden compliance engine differentiation by embedding carbon-tracking modules directly into carrier selection workflows before F-Gas Regulation mandates tighten. Acquire API-native challengers in the India DGFT digitization corridor to neutralize emerging customs automation threats. Deepen ERP integration partnerships with SAP SE and Oracle to anchor enterprise-grade deployments against SaaS displacement. For New Entrants and Emerging Players: Mid-market freight forwarders in Mumbai and Chennai port zones represent the most penetrable entry point as pre-arrival data submission mandates create whitespace for compliance-integrated platforms. Last-mile drone orchestration software for FAA Part 135 pilot zones in Texas and North Carolina offers specialized vertical expansion. Lead with blockchain-IoT temperature verification for pharmaceutical lanes to bypass incumbent rate-shopping commoditization. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because regulatory fragmentation between EU AI Act, FDA traceability rules, and US FAA frameworks perpetuates premium pricing for vendors encoding multi-jurisdiction logic. Target acquisition archetypes: customs compliance specialists with embedded carrier relationships and warehouse execution layer dominants feeding downstream shipping orchestration. Monitor which carriers open operational data APIs as the signal for network-effect formation and platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP connectivity with SAP SE anchors enterprise-grade deployment stickiness across North American freight corridors. |
| Acquisition of Specialist Firm | Customs compliance engines command premium pricing through embedded F-Gas Regulation carbon-tracking logic. |
| Strategic Partnership | Carrier data reciprocity agreements determine which platforms achieve network effects in neutral freight forwarding. |
| Product Launch | Fleet orchestration software for FAA Part 135 drone zones coordinates ground and air assets in Texas pilot regions. |
| Geographic Expansion | India DGFT digitization mandates in Maharashtra and Gujarat industrial corridors drive compliance platform procurement. |
Research Approach
The analysis maps cloud deployment architectures, on-premises installations, hybrid workloads, and SaaS subscription tiers, each validated through CTOs at third-party logistics providers, IT procurement officers at direct-to-consumer brands, platform engineers at freight forwarders, and integration specialists at ERP vendors. Primary fieldwork combined with secondary validation from SEC filings, hyperscaler capex disclosures, customs modernization program documentation, and EU regulatory transposition notices. Bottom-up segment sizing and top-down macro anchoring triangulated volume estimates.
Assumptions held fixed include prevailing cloud infrastructure concentration patterns and legacy EDI protocol persistence among major US retailers, while fuel volatility and carrier API standardization timelines were varied across sensitivity scenarios. The analytical framework modeled deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro logistics spending indicators, with EU F-Gas Regulation compliance timelines and India DGFT digitization mandates as industry-specific forecast inputs.
Practitioners should monitor carrier API openness negotiations, hyperscaler outage frequency, and EU AI Act enforcement timelines for early signals of platform consolidation acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Online Recruitment Market
Digital Solutions
Data Monetization Market
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Service Lifecycle Management Application Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Kubernetes Solutions Market
Digital Solutions
Conference Room Solutions Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Cloud Logistics Software Market
Digital Solutions
Social Networking App Market
Digital Solutions
Transport Management System Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Transit Station Display Board Market