
 Cloud Manufacturing Execution System (MES) Market | 2026-2036
Cloud Manufacturing Execution System (MES) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Manufacturing Execution System (MES) Market Outlook
Subscription-based software-defined manufacturing features is shifting how Cloud MES vendors monetize plant-floor intelligence. Siemens Opcenter leverages its industrial automation heritage to anchor large-scale automotive deployments. SAP Digital Manufacturing competes through deep ERP integration that sustains enterprise renewals. Tulip Interfaces specializes in no-code frontline applications that differentiate its platform for mid-size electronics manufacturers.
A Cloud Manufacturing Execution System is a software layer that orchestrates real-time production scheduling, machine connectivity, and quality workflows across distributed manufacturing assets, typically interfacing with OPC-UA or MQTT protocols for shop-floor data ingestion. Its primary purpose is to bridge enterprise planning systems with physical operations, enabling traceability and throughput optimization. Cloud MES deployments are outpacing on-premise installations as manufacturers prioritize elasticity over capital expenditure, while hybrid architectures retain relevance in aerospace where air-gapped quality systems remain mandatory. Production Tracking functionality leads adoption because it delivers immediate operational visibility, though Quality Management commands premium pricing in pharmaceuticals where batch records must satisfy regulator scrutiny.
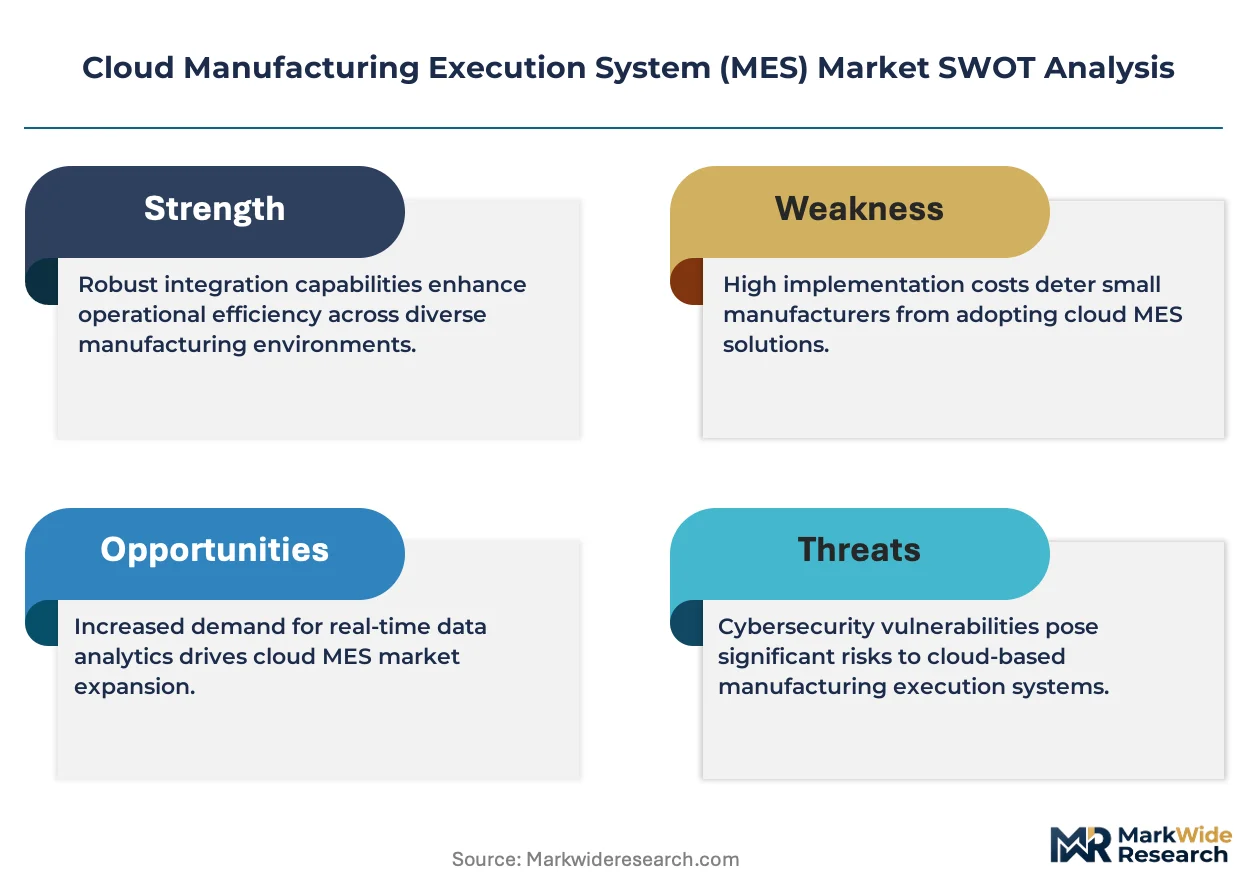
FDA 21 CFR Part 11 and EU GMP Annex 11 shape validation requirements for pharmaceutical Cloud MES deployments, forcing vendors to maintain comprehensive audit trails and electronic signature capabilities. ISO 27001 and IEC 62443 standards govern information security and operational technology cybersecurity, creating compliance barriers that favor established platforms with certified architectures. Stakeholders must weigh data sovereignty requirements against multi-cloud resilience when selecting deployment models for cross-border manufacturing networks.
Market Dynamics
Pharmaceutical serialization mandates and automotive multi-factory cloud deployments are compressing validation cycles and forcing vendors to architect elastic, audit-ready platforms that bridge air-gapped legacy systems with distributed cloud infrastructure.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail requirements in the United States are compelling pharmaceutical manufacturers to replace paper-based batch records with validated Cloud MES workflows.
- OPC-UA protocol standardization:Unified machine connectivity specifications are reducing integration friction for automotive OEMs running multi-site production tracking across supplier networks.
- Germany's Industrie 4.0 cluster:Dense concentrations of automation vendors and systems integrators in Bavaria and Baden-Württemberg are accelerating pilot-to-production transitions for cloud-native manufacturing platforms.
Market Restraints
- Air-gapped quality system mandates:Aerospace and defense contractors in the United States must maintain physically isolated MES instances, fragmenting cloud adoption and duplicating infrastructure costs.
- ISO 27001 certification scarcity:Limited pools of auditors and implementation specialists in Eastern Europe and Southeast Asia are extending vendor compliance timelines by 8-14 months.
- Hybrid architecture complexity:Manufacturers operating across jurisdictions with conflicting data sovereignty laws face architectural bloat from redundant edge-to-cloud synchronization layers.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for semiconductor and mobile device manufacturing are attracting greenfield investments that bypass legacy system entanglements entirely.
- EU Green Deal carbon tracking:Embedded emissions reporting requirements are creating demand for MES modules that correlate energy consumption data with unit-level product genealogy.
- No-code frontline application convergence:Platforms combining visual workflow builders with native OPC-UA ingestion are opening mid-market electronics and medical device segments previously blocked by integration costs.
Industry Challenges
- OT cybersecurity skill gaps:Shortages of professionals certified in IEC 62443 standards are forcing manufacturers to outsource security architecture, inflating deployment costs and creating vendor lock-in risks.
- Legacy ERP synchronization:Decades-old on-premise planning systems in automotive tier-one suppliers require custom middleware development, consuming 30-40% of typical Cloud MES implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Manufacturing Execution System (MES) Market |
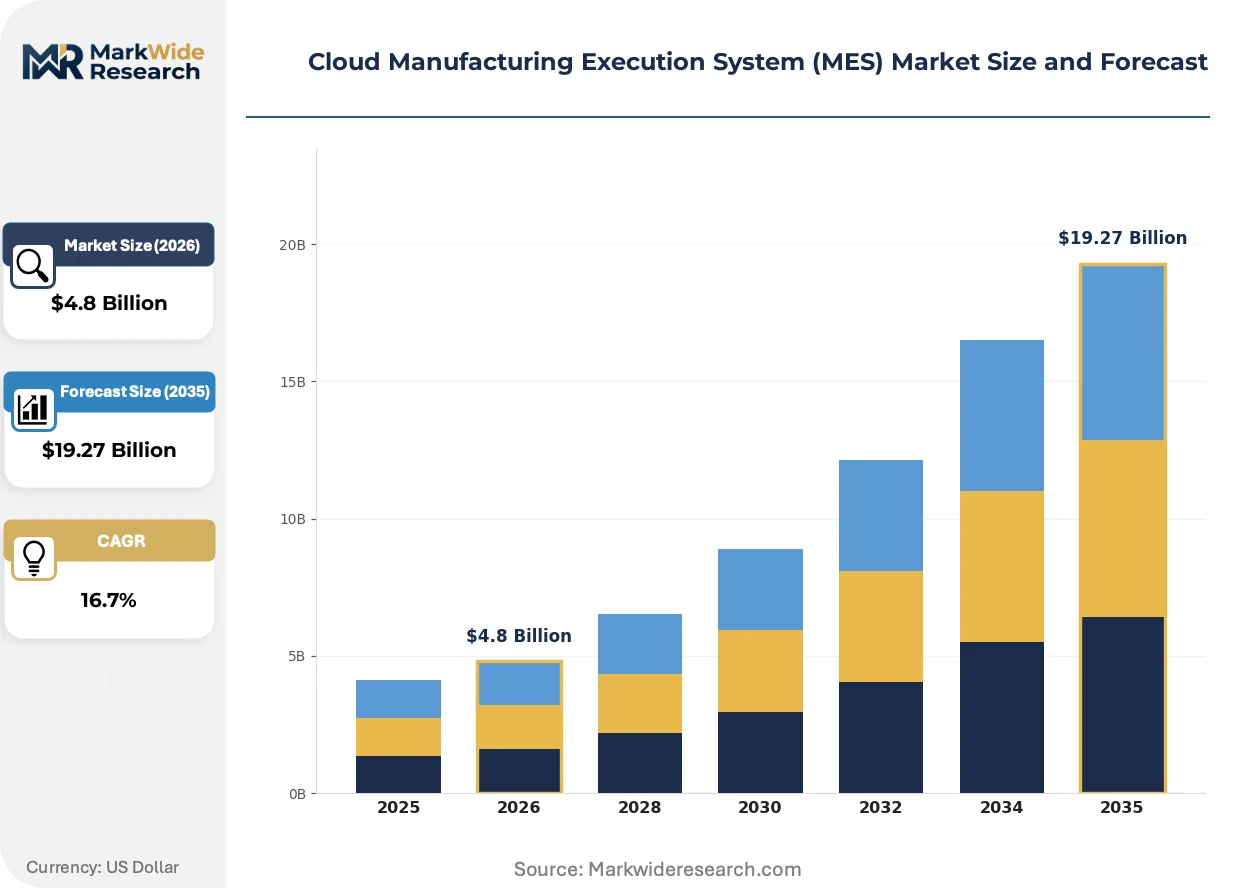
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise MES, Cloud MES, Hybrid MES, Mobile MES Industry Vertical: Automotive, Electronics, Aerospace, Pharmaceuticals Functionality: Production Tracking, Quality Management, Inventory Control, Labor Management Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Managed Service |
| Companies Covered | Factory AI, Dassault Systèmes DELMIA, SAP Digital Manufacturing, Tulip Interfaces, AVEVA MES, Siemens Opcenter, Oracle MES Cloud, SYMESTIC, Rockwell Automation Plex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Manufacturing Execution System (MES) Market Strategic Shifts
Edge-to-cloud data fabrics are collapsing latency boundaries between shop-floor sensors and enterprise analytics, enabling real-time quality interventions that were previously architecturally impossible. This infrastructure shift is redefining competitive differentiation around data sovereignty and sub-second response guarantees.
Digital twin implementations are rewriting how automotive and aerospace manufacturers validate process changes before physical deployment. BMW and Airbus suppliers are deploying virtual commissioning environments that mirror live production lines, compressing new product introduction cycles from months to weeks. The technology is rewriting capital allocation patterns as simulation fidelity reduces physical prototyping requirements.
EU AI Act risk classification rules are forcing MES vendors to document algorithmic decision pathways for quality inspection and predictive maintenance modules. Manufacturers deploying AI-enabled defect detection must now maintain human oversight interfaces and explainability logs, adding compliance layers that favor established platforms with certified governance frameworks. Pharmaceutical and medical device producers in Germany and France are accelerating procurement of compliant systems ahead of enforcement deadlines.
Equipment-as-a-service contracting is displacing traditional perpetual license purchases in mid-market metal fabrication and packaging machinery. Buyers in Italy and Spain now prioritize vendors offering consumption-based pricing tied to machine uptime or units produced, shifting vendor revenue recognition from upfront deployment to ongoing operational engagement. This procurement evolution favors cloud-native architectures with granular usage metering capabilities.
Cloud Manufacturing Execution System (MES) Market Segmentation
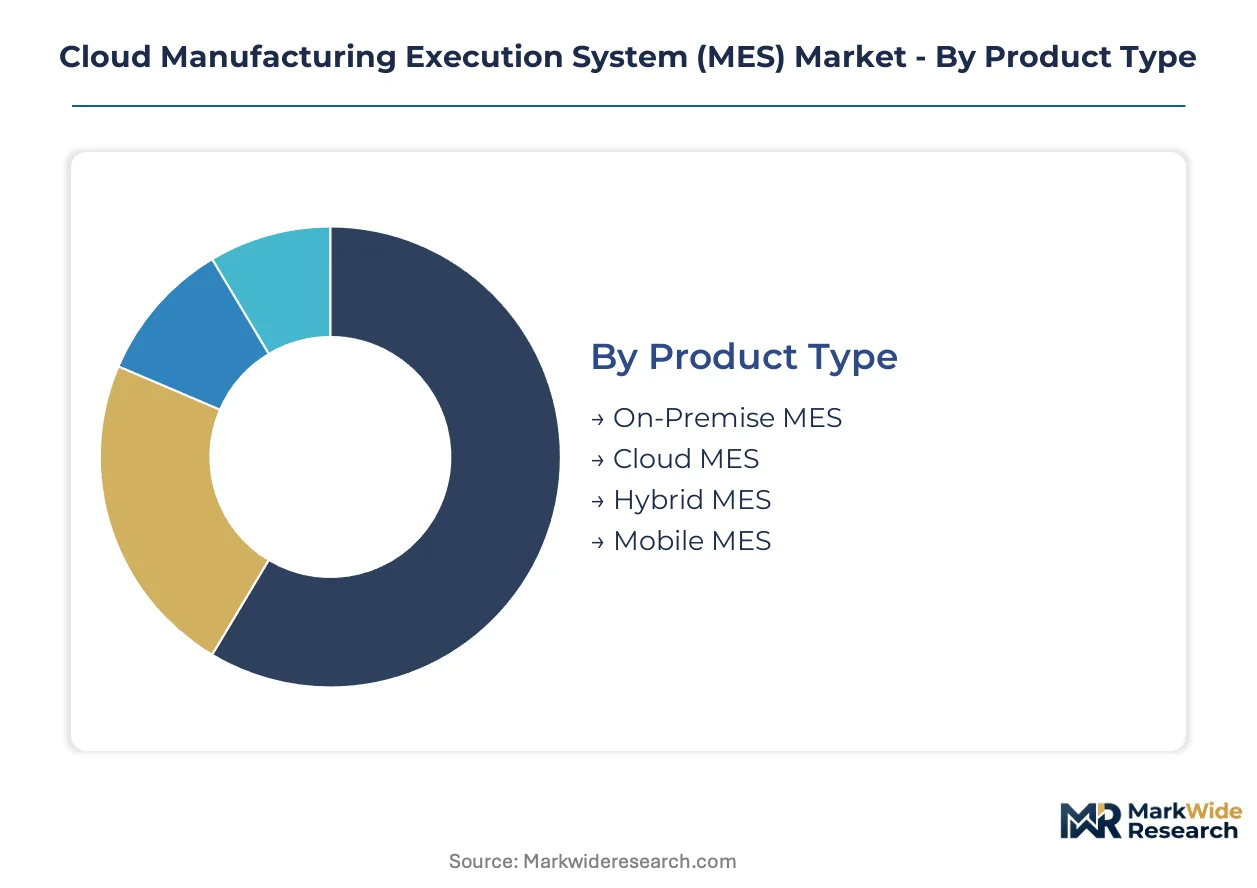
Cloud MES purchasing decisions hinge on legacy infrastructure entanglement, regulatory exposure, and workforce digital maturity. Segment boundaries blur as vendors bundle functionality into platform subscriptions, yet deployment architecture and vertical specialization remain decisive filters for buyer shortlists.
Product Type:
Pure-cloud configurations command premium valuations when buyers prioritize elasticity over capital retention, while hybrid architectures persist where air-gapped quality systems remain non-negotiable.
- Cloud MES:Native multi-tenant architectures with automatic scaling and zero on-site server footprint. Pharmaceutical manufacturers in Germany and the United States select this architecture to compress validation cycles for FDA 21 CFR Part 11 and EU GMP Annex 11 compliance.
- Hybrid MES:Edge computing layers synchronize with cloud analytics while retaining local execution for critical control loops. Aerospace contractors across France and the United States deploy this configuration to satisfy air-gapped quality mandates without sacrificing enterprise visibility.
- On-Premise MES:Perpetual-license software running on customer-managed infrastructure in isolated data centers. Defense subcontractors in restricted jurisdictions maintain these deployments to satisfy data sovereignty requirements.
- Mobile MES:Tablet-first interfaces enabling shop-floor operators to execute workflows without fixed terminal access. Electronics assemblers in India's PLI scheme zones adopt these interfaces for greenfield lines lacking legacy terminal infrastructure.
Volume sits with Hybrid MES; growth tilts toward Cloud MES.
Industry Vertical:
Regulatory stringency and serialization mandates concentrate procurement authority in quality and compliance functions rather than IT departments.
- Pharmaceuticals:Batch record digitization, electronic signatures, and genealogy tracking for FDA and EMA submissions. Serialization mandates in the United States and European Union are compressing vendor selection timelines.
- Automotive:Multi-factory production tracking and supplier network orchestration. OEMs in Germany's Industrie 4.0 cluster pilot cloud-native platforms for real-time visibility across tier-one networks.
- Electronics:Rapid product changeovers and high-mix, low-volume flexibility. India's semiconductor and mobile device manufacturers under PLI incentives bypass legacy entanglements with greenfield cloud deployments.
- Aerospace:AS9100 quality system integration and long-horizon traceability for airframe components. French and United States contractors maintain hybrid architectures to satisfy physically isolated quality mandates.
Revenue concentrates in Pharmaceuticals; Electronics expands most quickly.
Functionality:
Module selection follows operational pain points, with production visibility commanding initial deployments and quality compliance driving premium expansion.
- Production Tracking:Real-time work-in-progress visibility and machine status monitoring through OPC-UA or MQTT ingestion. Automotive OEMs deploy this module first to establish baseline operational transparency.
- Quality Management:Statistical process control, non-conformance tracking, and electronic batch records. Pharmaceutical manufacturers pay premium per-seat pricing for modules satisfying FDA 21 CFR Part 11 audit requirements.
- Inventory Control:Material genealogy and automated replenishment triggering. Electronics manufacturers leverage this functionality for component traceability in high-velocity supply chains.
- Labor Management:Skill-based routing and certification tracking for operator assignment. Aerospace contractors utilize these capabilities to enforce AS9100 personnel qualification requirements.
Adoption initiates with Production Tracking; contract value peaks with Quality Management.
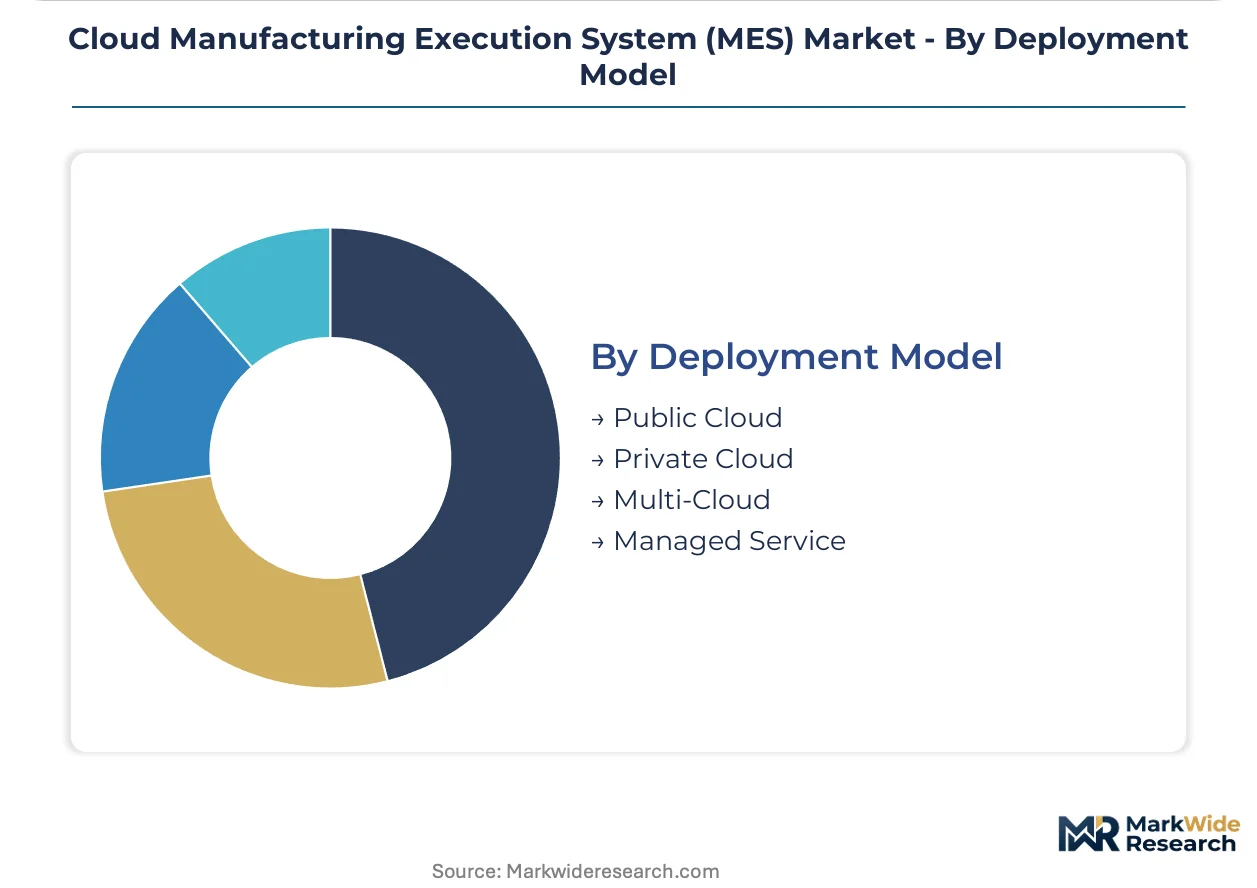
Deployment Model:
Data sovereignty requirements and cybersecurity certification availability constrain architecture choices in cross-border manufacturing networks.
- Public Cloud:Shared infrastructure with region-specific data residency guarantees. Mid-market electronics manufacturers in Germany and India select this model for fastest time-to-value without infrastructure capital.
- Private Cloud:Dedicated single-tenant environments with customized security controls. Pharmaceutical manufacturers in France and Switzerland procure these deployments to satisfy national data localization statutes.
- Multi-Cloud:Workload distribution across two or more hyperscaler environments for resilience. Automotive OEMs with supplier networks spanning Germany, the United States, and China architect this redundancy.
- Managed Service:Vendor-operated infrastructure with outsourced security and compliance maintenance. Eastern European manufacturers facing ISO 27001 certification scarcity contract these offerings to accelerate deployment.
Deployments cluster in Public Cloud; Multi-Cloud gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing execution system deployment concentrates in economies with dense industrial automation infrastructure and stringent regulatory environments. Consumption patterns diverge sharply between mature markets replacing legacy systems and emerging economies building greenfield digital capacity.
United States
Pharmaceutical serialization mandates and FDA 21 CFR Part 11 compliance requirements are compressing Cloud MES procurement timelines. The FDA enforces electronic signature and audit trail standards that eliminate paper-based batch records. Boston's life sciences corridor and North Carolina's Research Triangle host validation specialists serving multi-site pharmaceutical deployments.
Germany
Automotive OEMs pilot multi-factory cloud deployments through Industrie 4.0 standardization frameworks. The KBA coordinates vehicle traceability requirements that cascade through tier-one supplier networks. Bavaria's automation vendor cluster around Munich and Baden-Württemberg's machinery belt in Stuttgart accelerate pilot-to-production transitions for cloud-native platforms.
China
Dual carbon goals and MIIT smart manufacturing directives are accelerating domestic Cloud MES adoption in automotive and electronics sectors. The NMPA harmonizes pharmaceutical data integrity requirements with international standards. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou deploy edge-to-cloud architectures for supplier network orchestration.
India
PLI scheme incentives for semiconductor and mobile device manufacturing are attracting greenfield investments that bypass legacy system entanglements. The CDSCO aligns pharmaceutical data integrity rules with FDA and EMA precedents. Karnataka's Electronics City and Tamil Nadu's Sriperumbudur corridor host contract manufacturers deploying tablet-first MES interfaces.
France
AS9100 quality system mandates and EU AI Act risk classification rules are shaping aerospace and pharmaceutical procurement decisions. The ANSM enforces data localization requirements that favor private cloud deployments. Toulouse's aerospace cluster and Paris-Saclay's pharmaceutical research belt maintain hybrid architectures for air-gapped quality systems.
Cloud Manufacturing Execution System (MES) Market Competitive Environment
Top-tier vendors anchor enterprise pharmaceutical and automotive deployments, while specialized platforms occupy mid-market electronics and medical device segments. The market structures around three distinct competitive tiers: industrial automation heritage players, ERP-integrated suite providers, and no-code native challengers. Dominant competitive moves include strategic partnerships with systems integrators and vertical specialization through pre-validated industry templates.
Within the industrial automation tier, Siemens Opcenter and Rockwell Automation Plex exemplify heritage players leveraging decades of shop-floor control expertise. SAP Digital Manufacturing occupies the ERP-integrated position, anchoring enterprise renewals through planning system connectivity. Tulip Interfaces represents the no-code native archetype, targeting mid-market manufacturers with visual workflow builders. These three companies collectively illustrate how vendor selection hinges on legacy infrastructure entanglement and workforce digital maturity rather than feature parity alone.
| Leading Market Players |
|---|
| Factory AI |
| Dassault Systèmes DELMIA |
| SAP Digital Manufacturing |
| Tulip Interfaces |
| AVEVA MES |
| Siemens Opcenter |
| Oracle MES Cloud |
| SYMESTIC |
| Rockwell Automation Plex |
| Others |
Value Chain & Pricing Dynamics
Software engineering labor costs in Germany and the United States cascade through subscription pricing tiers, with validated pharmaceutical deployments commanding premium multiples over standard manufacturing licenses due to FDA 21 CFR Part 11 compliance overhead and specialized audit trail architectures.
Pricing Analysis
Pricing pressure intensifies in mid-market electronics segments as no-code platforms compress implementation timelines and displace traditional systems integrator margins. Three-tier pricing structure across enterprise, professional, and essential levels separates validated pharmaceutical deployments with electronic signature capabilities from standard production tracking modules. Certification grade—specifically ISO 27001 and IEC 62443 compliance—drives the widest price spreads. Buyer price sensitivity peaks among Indian contract manufacturers under PLI scheme incentives, while German automotive OEMs demonstrate lowest sensitivity due to multi-factory standardization imperatives.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale pharmaceutical and automotive buyer demand, bypassing systems integrator markups for multi-site deployments. Engineering talent pools concentrate in Germany, the United States, and India, with cloud infrastructure services drawing from hyperscaler data center networks in these same markets. Edge computing hardware and OPC-UA protocol stacks constitute critical component dependencies. Single-source vulnerability in IEC 62443-certified cybersecurity specialists extends vendor compliance timelines and inflates deployment costs across Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure mounts as FDA and EU validation requirements force smaller vendors toward acquisition or exit, favoring platforms with pre-certified audit trail architectures and established pharmaceutical reference sites.
For Market Incumbents: Deploy pre-validated industry templates as the primary defensive lever against no-code challengers eroding mid-market share. Siemens Opcenter and SAP Digital Manufacturing should deepen ERP integration moats while absorbing specialist compliance boutiques to close electronic signature capability gaps. Threat substitution from Tulip Interfaces' visual workflow builders demands rapid no-code feature parity investment.
For New Entrants and Emerging Players: FDA 21 CFR Part 11 in the United States opens a window for specialized validation-as-a-service offerings targeting mid-tier pharmaceutical manufacturers lacking internal compliance expertise. India's PLI scheme electronics corridors present the most penetrable geography for greenfield cloud-native deployments without legacy middleware entanglements. Go-to-market positioning should emphasize tablet-first interfaces for contract manufacturers building new lines from scratch.
For Investors and Strategic Acquirers: Accelerating OEM consolidation of supplier networks is the leading indicator that multi-factory cloud orchestration capabilities will command acquisition premiums. Long-term viability favors platforms with certified pharmaceutical architectures and established Industrie 4.0 reference deployments. Target acquisition archetype: mid-size vendors with ISO 27001 certification and proven FDA validation support teams.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP connectivity sustains enterprise renewals at SAP and Siemens against point solutions. |
| Acquisition of Specialist Firm | Validated compliance boutiques close electronic signature gaps for pharmaceutical market penetration. |
| Strategic Partnership | Systems integrator alliances accelerate pilot-to-production transitions in Germany's Industrie 4.0 cluster. |
| Product Launch | No-code frontline modules open mid-market electronics segments previously blocked by integration costs. |
| Geographic Expansion | India PLI scheme zones attract greenfield deployments bypassing legacy system entanglements entirely. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with MES implementation specialists, pharmaceutical quality assurance directors, automotive platform engineers, and cloud infrastructure procurement officers at Tier 1 suppliers. FDA 483 observation logs, EMA inspection reports, and ISO certification databases provided compliance timeline benchmarks. Bottom-up deployment sizing across Germany, the United States, India, and China triangulated against top-down vendor revenue attribution.
Segmentation granularity modeled deployment architecture, industry vertical, and functionality module at the country-regulator level, with cross-border data sovereignty requirements treated as a distinct constraint dimension. CAGR derivation applied elasticity-adjusted adoption curves for pharmaceutical serialization mandates and automotive multi-factory standardization programs across the projection horizon. Hyperscaler infrastructure expansion timelines and IEC 62443 auditor supply constraints fed directly into capacity-limited growth scenarios.
The model assumes a particular technology adoption path; alternative pathways for edge-to-cloud data fabric architectures would alter the outlook if aerospace air-gap mandates soften or quantum-resistant encryption accelerates compliance redesign. Forecasts reflect base-case assumptions about regulatory enforcement continuity and pharmaceutical serialization deadline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Hybrid Events Software Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Product As a Service Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Data Broker Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market