
 Subscription (Digital) Services Market | 2026-2036
Subscription (Digital) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Subscription (Digital) Services Market Analytics
Proprietary content libraries are shifting economics across video streaming as exclusive IP replaces licensed third-party catalogs. Netflix dominates original production volume, leveraging global studio networks to sustain subscriber retention across 190 countries. Disney+ anchors family-oriented content verticals, competing through franchise ecosystems that span theatrical, streaming, and merchandise channels. Spotify differentiates audio streaming with podcast exclusives, extending its platform beyond music into spoken-word advertising markets.
Subscription (Digital) Services encompass recurring-access models for software, media, and cloud infrastructure delivered over internet protocols with automatic renewal billing and usage-based tiering. These services operate on multi-tenant architectures with API-driven provisioning, enabling real-time scaling across customer segments without physical distribution overhead. Video Streaming leads service type revenue pools, while Software Subscription represents the fastest-growing structural segment as enterprises abandon perpetual licenses for SaaS consumption models. Freemium pricing models concentrate user acquisition costs in mobile-first markets, whereas Annual Subscription structures improve lifetime value metrics in enterprise customer type segments.
The EU Digital Services Act and GDPR impose content moderation and data portability obligations on platform operators serving European users. The FCC in the United States enforces net neutrality principles that affect streaming quality-of-service negotiations between ISPs and content distributors. India's TRAI mandates transparency in auto-renewal billing for over-the-top platforms, shaping subscriber retention tactics in that market. Stakeholders must monitor regulatory divergence across jurisdictions as compliance fragmentation raises operational costs for globally scaled providers.
Market Dynamics
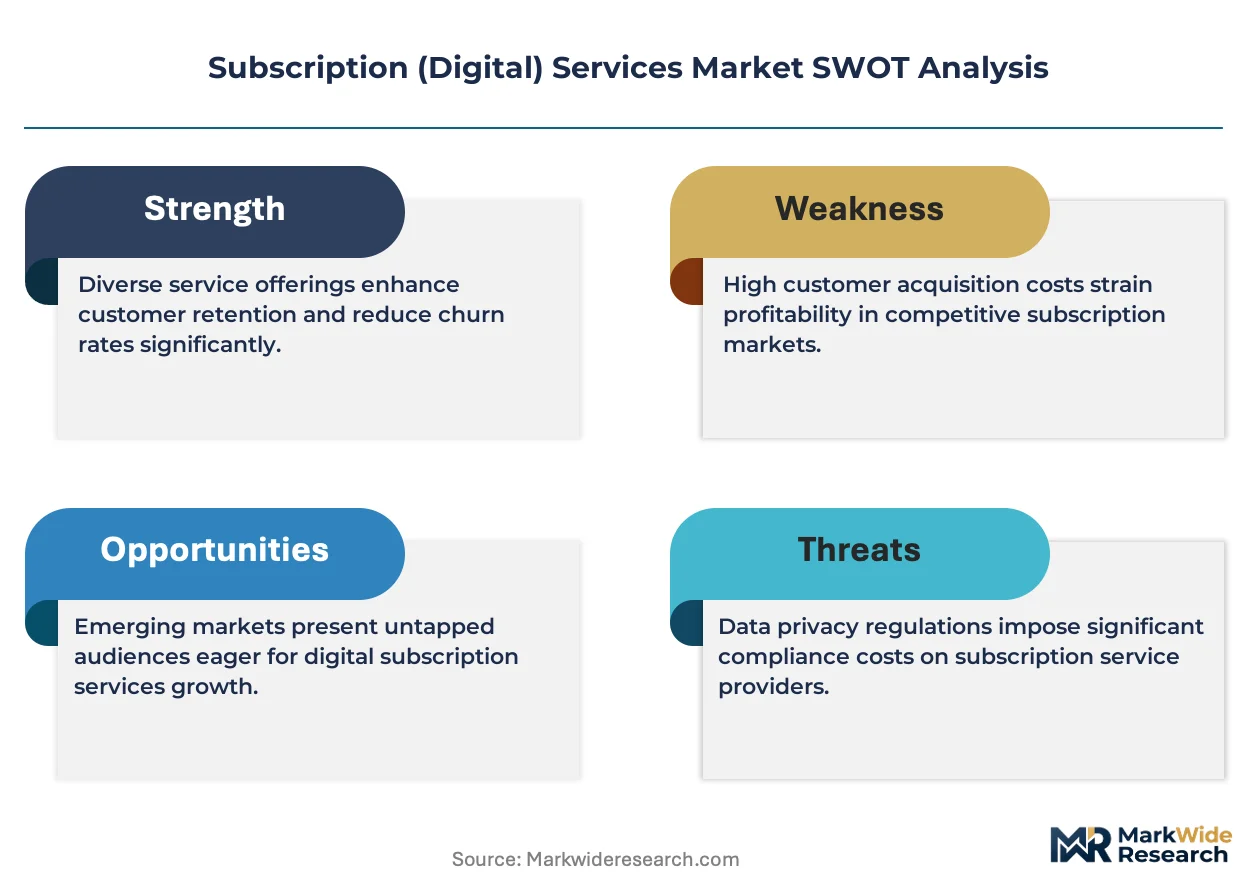
Enterprise migration from perpetual software licenses to recurring cloud consumption models is compressing revenue recognition cycles and redefining customer lifetime value calculations across the Subscription (Digital) Services ecosystem.
Growth Catalysts
- EU Digital Services Act compliance mandates:Platform accountability requirements are forcing cross-border providers to upgrade content moderation infrastructure, creating sustained demand for automated compliance tooling and third-party verification services.
- Hyperscaler infrastructure concentration in the United States:Mature payment ecosystems and data center density enable premium subscriber economics that subsidize global content acquisition budgets.
- API-driven provisioning architectures:Real-time scaling capabilities eliminate physical distribution overhead, allowing providers to serve micro-segments without marginal cost escalation.
Market Restraints
- Content acquisition cost inflation:Exclusive IP bidding wars between video streaming platforms have escalated production budgets beyond subscriber revenue growth in saturated markets.
- Regulatory fragmentation across jurisdictions:Divergent data localization requirements from India's TRAI, EU GDPR, and US state-level privacy laws multiply compliance engineering overhead.
- Freemium conversion ceiling:Mobile-first markets exhibit persistent gap between user acquisition volume and paid tier migration, straining unit economics at scale.
Strategic Opportunities
- Enterprise SaaS underpenetration in India:Small and medium enterprises remain on legacy perpetual licenses, presenting conversion runway as cloud infrastructure spreads beyond tier-one cities.
- Spoken-word advertising convergence:Podcast exclusives on audio platforms unlock incremental revenue streams beyond music licensing, attracting brand budgets from terrestrial radio.
- Annual subscription structuring:Upfront cash collection improves working capital position while reducing monthly churn volatility in B2B customer segments.
Industry Challenges
- Cross-functional talent scarcity:Subscription businesses require hybrid expertise spanning data science, content curation, and regulatory compliance that traditional software or media hiring pipelines fail to produce.
- Legacy system integration friction:Enterprises migrating from on-premise perpetual licenses face API compatibility gaps and data migration complexity that extend deployment timelines.
- Content moderation workforce scaling:Platform scale exceeds automated classification accuracy, forcing reliance on human review teams with high turnover and regional language coverage gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subscription (Digital) Services Market |
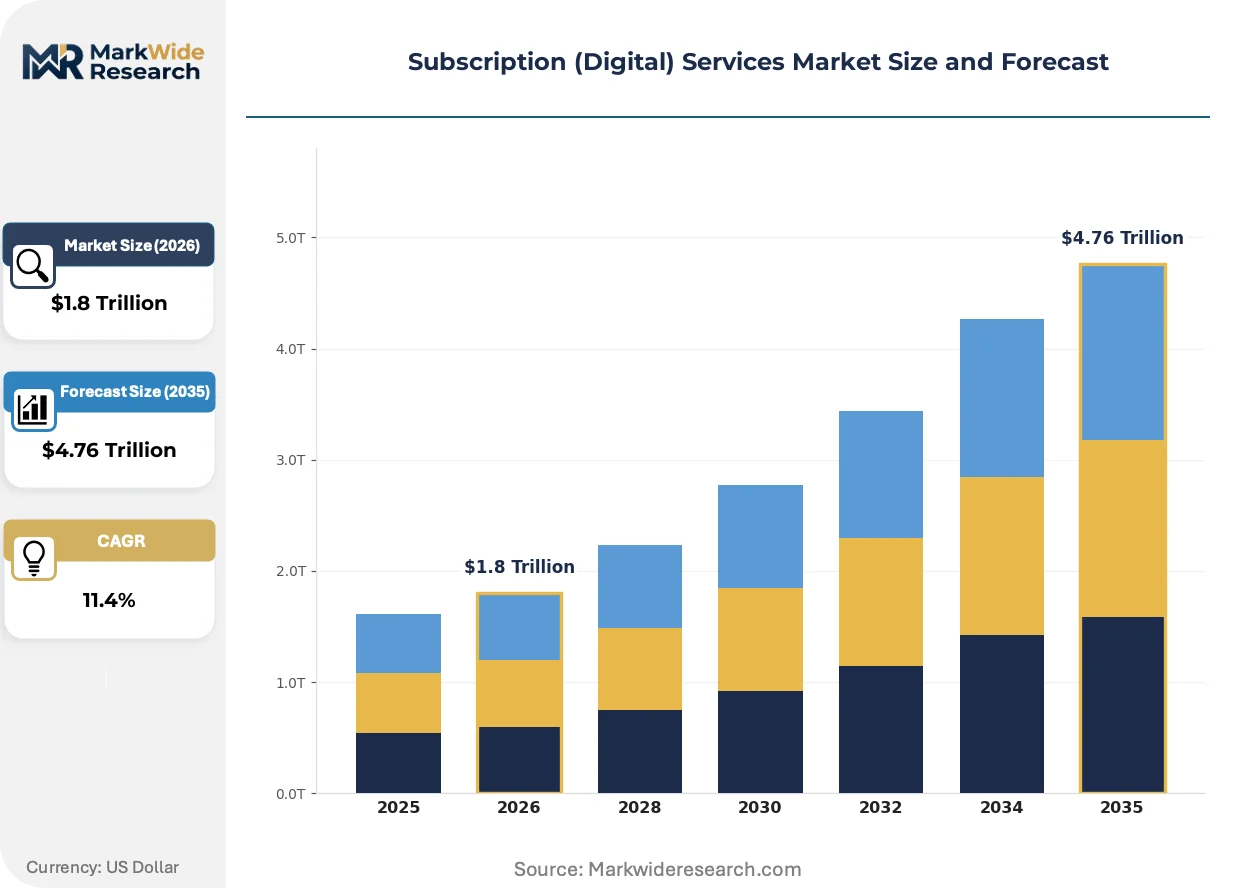
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $4.76 Trillion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Streaming, Music Streaming, Cloud Storage, Software Subscription Pricing Model: Monthly Subscription, Annual Subscription, Pay-Per-View, Freemium Customer Type: Individual Users, Small Businesses, Enterprises, Educational Institutions Platform: Web-Based, Mobile Apps, Smart TVs, Gaming Consoles |
| Companies Covered | Apple TV+, HBO Max, Netflix, Kindle Unlimited, Audible, Amazon Prime Video, Spotify, MasterClass, Disney+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subscription (Digital) Services Market Evolving Landscape
Artificial intelligence is compressing content production timelines and personalizing recommendation engines, while regulatory pressure on platform accountability is reshaping provider operational models.
Generative AI tooling for script development, localization dubbing, and thumbnail optimization is consolidating creative workflows across video streaming platforms. Mid-tier studios now deploy automated pre-visualization to reduce pilot production risk. This capability compression is enabling faster content iteration cycles that match subscriber churn velocity.
The EU Digital Services Act's transparency mandates for algorithmic ranking and content moderation are forcing platform operators to document decision logic and provide user appeal pathways. Compliance engineering teams have expanded to bridge product and legal functions. Video streaming and social audio platforms serving European users face the steepest operational recalibration.
Buyer concentration among enterprise procurement functions is displacing departmental software purchasing with centralized SaaS governance. Chief information officers now mandate API interoperability and data portability upfront. This pattern is most visible in United States technology and financial services verticals where vendor consolidation reduces integration tax.
Subscription (Digital) Services Market Segmentation
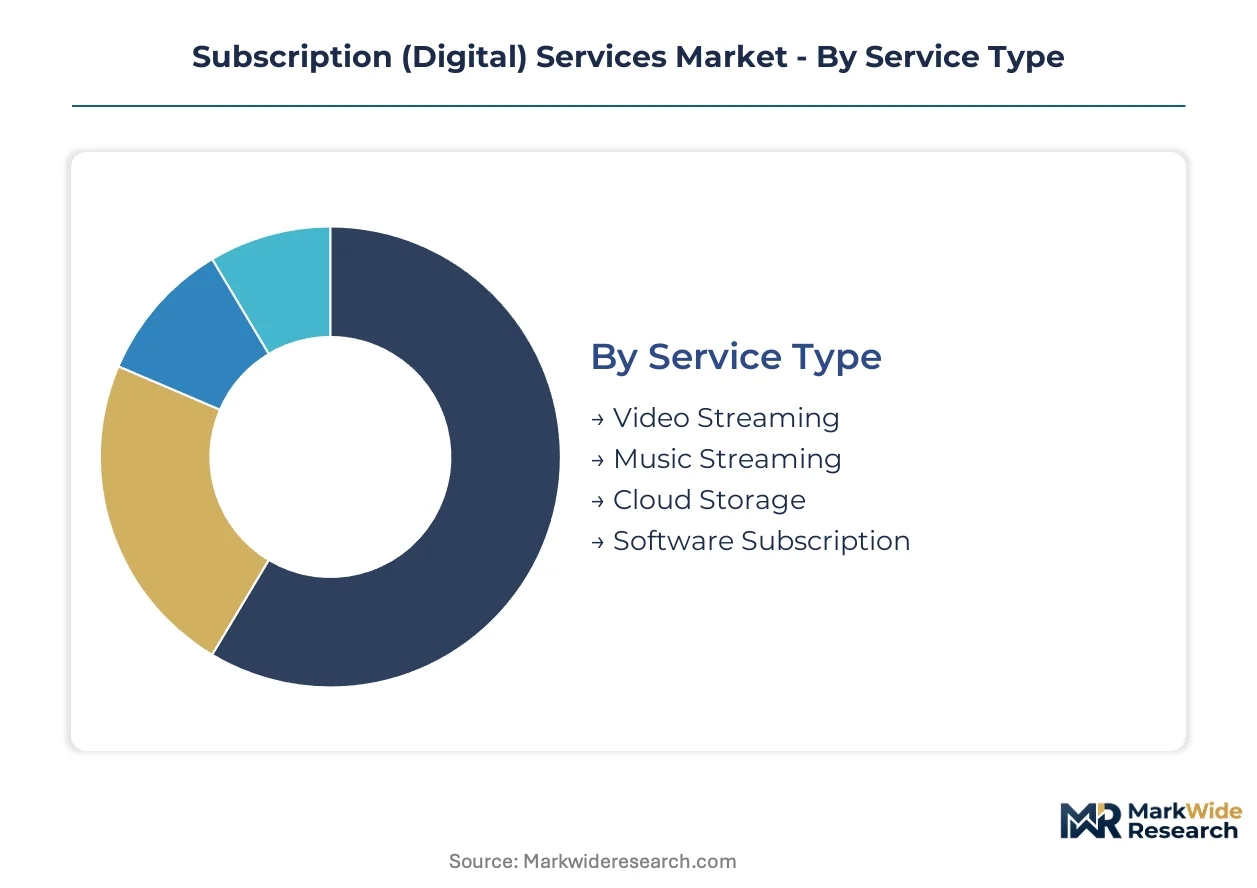
Segmentation in Subscription (Digital) Services reveals how compliance burdens, pricing elasticity, and platform architecture choices concentrate value capture across distinct user cohorts. Understanding these partitions enables providers to align provisioning infrastructure with specific retention economics and regulatory exposure.
Service Type:
EU Digital Services Act transparency mandates and GDPR data portability requirements impose tiered compliance obligations depending on content moderation complexity and cross-border data flows.
- Video Streaming:High-definition content pipelines require substantial CDN investment and regional licensing negotiations. Demand clusters in the United States where hyperscaler density supports 4K delivery economics, though EU content quotas and accessibility mandates raise localization costs for catalog breadth.
- Software Subscription:Enterprise SaaS models face escalating API interoperability demands from centralized procurement functions. Small and medium enterprises in India present conversion runway as perpetual license abandonment accelerates beyond tier-one cities.
- Music Streaming:Licensing frameworks with rights holders dominate cost structures, with spoken-word extensions unlocking incremental advertising inventory.
- Cloud Storage:Data residency requirements from India's TRAI and EU GDPR fragment infrastructure deployment strategies across jurisdictions.
Video Streaming sits at the top of the volume ranking, with Software Subscription climbing the fastest.
Pricing Model:
Cost tier stratification directly shapes working capital profiles and churn volatility across subscriber cohorts with divergent payment behaviors.
- Annual Subscription:Upfront cash collection improves liquidity positions while reducing monthly cancellation volatility, particularly valued by enterprise procurement functions negotiating multi-year SaaS agreements.
- Freemium:Mobile-first markets exhibit persistent conversion gaps between acquisition volume and paid tier migration, straining unit economics where advertising fill rates underperform.
- Monthly Subscription:Dominates consumer video and music streaming where low-commitment entry points reduce acquisition friction.
- Pay-Per-View:Live sports and theatrical windowing generate event-driven revenue spikes with minimal ongoing infrastructure burden.
Monthly Subscription commands the largest subscriber base, though Annual Subscription delivers superior lifetime value metrics.
Customer Type:
Application complexity scales with organizational size, from individual content consumption to enterprise-wide SaaS governance with mandated security certifications.
- Enterprises:Centralized IT governance now mandates API interoperability and data portability upfront, displacing departmental purchasing patterns most visible in United States technology and financial services verticals.
- Small Businesses:Legacy perpetual license dependence creates conversion friction as cloud migration requires integration engineering beyond internal technical capacity.
- Individual Users:Price sensitivity and platform switching costs dominate retention strategies across streaming and storage categories.
- Educational Institutions:Volume licensing negotiations and accessibility compliance shape procurement timelines distinct from commercial segments.
Individual Users represent the deepest addressable pool, with Enterprises expanding most quickly as procurement centralization accelerates.
Platform:
Distribution channel maturity determines addressable market reach and technical integration requirements for content delivery optimization.
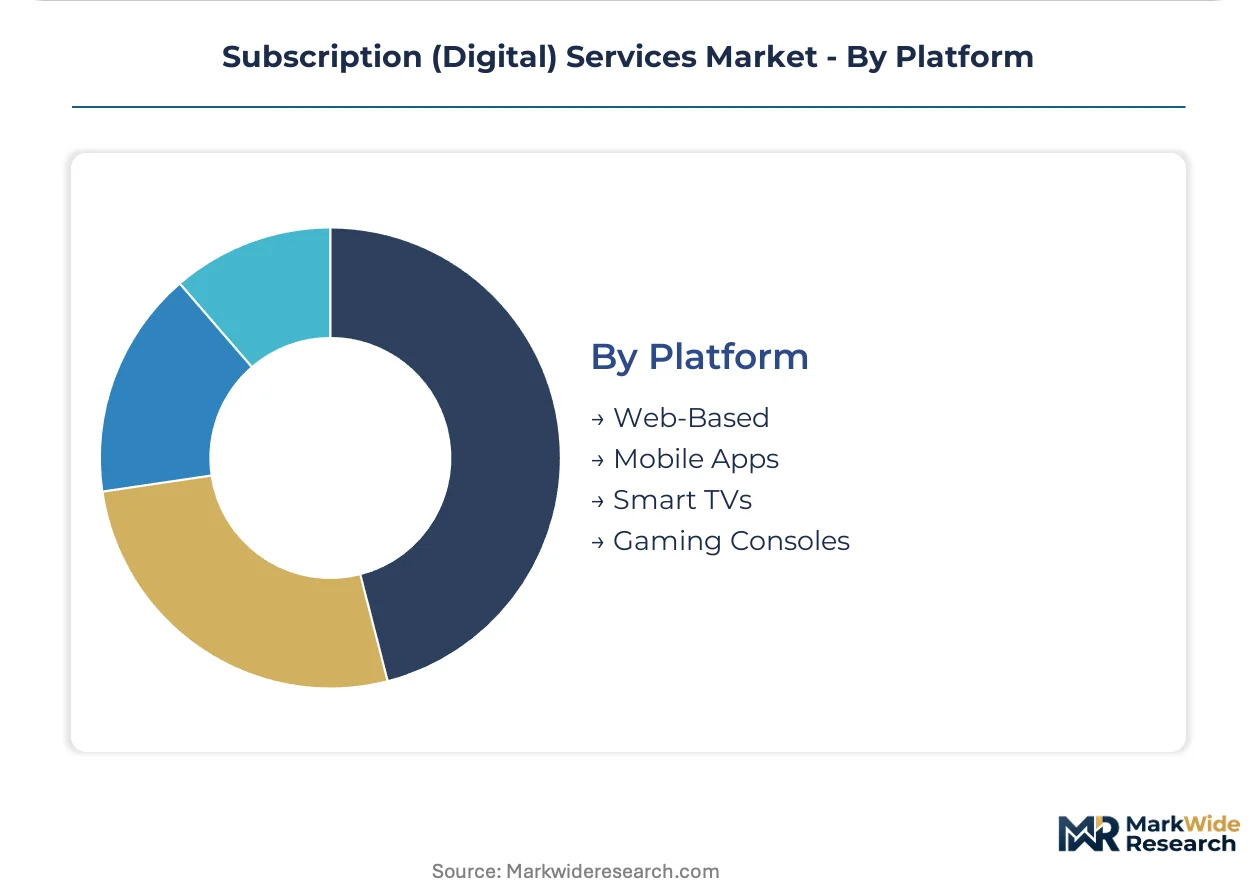
- Mobile Apps:Dominates emerging market acquisition where smartphone-first internet access concentrates subscriber onboarding, though screen size constraints limit premium tier conversion for video services.
- Smart TVs:Living room viewing drives household account sharing and premium resolution upgrades, with embedded app stores creating distribution gatekeeper dependencies.
- Web-Based:Enterprise SaaS and professional productivity tools retain browser-based delivery for cross-device workflow continuity.
- Gaming Consoles:High-engagement user bases with established payment credentials support entertainment bundle economics.
Mobile Apps lead in subscriber count, with Smart TVs gaining share fastest as connected device penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley hyperscaler concentration anchors global subscription infrastructure deployment, with mature payment ecosystems and data center density sustaining premium subscriber economics across digital service categories.
United States
Enterprise SaaS procurement centralization drives demand as CIOs mandate API interoperability and data portability upfront. FCC net neutrality enforcement shapes streaming quality-of-service negotiations between ISPs and content distributors. Seattle and San Francisco Bay Area clusters host hyperscaler headquarters that subsidize global content acquisition through domestic premium subscriber margins.
Germany
Industrial software subscription conversion accelerates as Mittelstand manufacturers abandon perpetual licenses for cloud ERP and IoT platforms. GDPR data portability requirements impose engineering overhead on cross-border service providers. Munich and Berlin technology corridors concentrate B2B SaaS development targeting automotive and machinery verticals with specialized compliance tooling.
India
Small and medium enterprise cloud migration presents conversion runway as perpetual license abandonment spreads beyond tier-one cities. TRAI mandates transparency in auto-renewal billing for over-the-top platforms, reshaping subscriber retention tactics. Bengaluru and Hyderabad technology clusters anchor domestic SaaS product development serving Southeast Asian export markets.
United Kingdom
Financial services verticals drive enterprise software demand with centralized procurement functions displacing departmental purchasing patterns. Post-Brexit regulatory divergence from EU GDPR creates compliance complexity for platform operators serving both jurisdictions. London fintech corridor concentrates subscription billing infrastructure providers targeting European expansion.
Japan
Mobile-first entertainment consumption concentrates subscriber acquisition on smartphone platforms with embedded payment credential density. METI industrial digitization incentives accelerate manufacturing software subscription adoption. Tokyo and Osaka metropolitan areas host regional headquarters for global streaming platforms localizing content catalogs for domestic preferences.
Subscription (Digital) Services Market Competitive Landscape
Content exclusivity bidding dominates the current landscape as platforms escalate original production investments to replace licensed third-party catalogs. Market structure concentrates among vertically integrated entertainment conglomerates and pure-play streaming specialists, with mid-tier regional platforms occupying niche language verticals. Strategic archetypes divide between IP-owners leveraging franchise ecosystems, technology platforms optimizing recommendation algorithms, and audio specialists expanding into spoken-word advertising. Competitive moves center on exclusive content commissioning and international market expansion through localized production hubs.
Among pure-play streaming specialists, Netflix and Spotify exemplify distinct platform archetypes—Netflix anchoring global video original production volume, Spotify occupying audio streaming with podcast exclusives extending into advertising markets. Disney+ represents the IP-owner model, leveraging theatrical-to-streaming franchise ecosystems that span merchandise and experiential channels. These three entities illustrate how proprietary content libraries and technology infrastructure combine to sustain subscriber retention across divergent consumption categories.
| Leading Market Players |
|---|
| Apple TV+ |
| HBO Max |
| Netflix |
| Kindle Unlimited |
| Audible |
| Amazon Prime Video |
| Spotify |
| MasterClass |
| Disney+ |
| Others |
Value Network & Pricing Analysis
Captive hyperscaler infrastructure in the United States anchors supply positions for global streaming platforms while enabling premium-tier pricing power through guaranteed quality-of-service delivery. This vertical integration into content delivery networks and payment processing stacks insulates major providers from third-party cost volatility that compresses margins for platform-dependent competitors.
Pricing Analysis
Input-cost pass-through from content acquisition budgets flows unevenly across subscriber tiers, with exclusive original production costs concentrated in premium offerings while licensed catalog expenses burden standard plans. Price differentiation separates ad-supported economy tiers from resolution-graded premium subscriptions, with 4K streaming commanding substantial markups over HD equivalents. Pricing pressure stems from escalating exclusive IP bidding wars between video platforms in saturated markets. Small and medium enterprises exhibit highest price sensitivity in software subscription categories, whereas enterprise procurement functions negotiate multi-year agreements with reduced churn flexibility.
Supply Chain Analysis
Direct-to-consumer streaming platforms handle hyperscale subscriber demand through proprietary content delivery networks, bypassing traditional distribution intermediaries. Geographic supply concentration centers on United States hyperscaler regions, Ireland's European data hub cluster, and Singapore's Southeast Asian infrastructure node. Raw material dependencies span licensed music catalogs, commissioned video productions, and cloud compute capacity from AWS, Azure, and Google Cloud. Supply chain risk manifests in single-source vulnerability for exclusive content IP where bidding wars eliminate alternative sourcing. Distribution runs through mobile app stores, smart TV embedded platforms, and web-based enterprise provisioning portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription (Digital) Services function as stable compounders where recurring revenue mechanics and automatic renewal infrastructure generate predictable cash generation. Enterprise migration from perpetual licenses to cloud consumption models sustains structural expansion across software categories.
For Market Incumbents: Anticipate regulatory fragmentation multiplying compliance engineering overhead as the EU Digital Services Act, India's TRAI mandates, and US state privacy laws diverge. Consolidate content moderation tooling investments to amortize verification costs across multiple jurisdictions. Defend subscriber retention through exclusive IP commissioning that raises replacement costs for churning users.
For New Entrants and Emerging Players: Small and medium enterprises in India's tier-two and tier-three cities present underserved buyer archetypes with legacy perpetual license dependence and limited internal cloud migration expertise. Target spoken-word advertising inventory gaps on audio platforms where podcast exclusives attract terrestrial radio budgets. Pursue white-label SaaS partnerships with domestic system integrators to bypass direct enterprise sales cycle disadvantages.
For Investors and Strategic Acquirers: Roll-up economics work for vertical software specialists because procurement centralization among CIOs favors consolidated vendor relationships with proven API interoperability. Long-term viability hinges on recurring revenue concentration exceeding eighty percent of total sales. Monitor content acquisition cost inflation as an inflection indicator for video streaming margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Original Content Commissioning | Netflix's global studio network demonstrates exclusive IP retention power across 190 countries. |
| API Interoperability Certification | Enterprise CIO mandates in US technology verticals now require upfront data portability guarantees. |
| Podcast Exclusive Acquisition | Spotify's spoken-word extensions capture advertising budgets migrating from terrestrial radio. |
| Annual Subscription Structuring | Upfront cash collection improves working capital while reducing monthly churn volatility in B2B segments. |
| Regional Localization Hub Deployment | EU content quotas and accessibility mandates raise catalog breadth costs for non-compliant platforms. |
Research Methodology
Direct dialogue with platform engineering directors, enterprise SaaS procurement officers, content licensing executives, and regulatory compliance specialists grounded qualitative findings in operational reality. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie mobile engagement data, and EU Digital Services Act implementation guidance. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from trade associations and regulatory filings.
Segment-level projections across service type, pricing model, customer type, and platform dimensions fed into consolidated market estimates over the projection horizon. CAGRs were derived from historical growth trajectory analysis adjusted for structural shift impacts including enterprise cloud migration acceleration and content exclusivity investment cycles. Forecast inputs incorporated content production cost indices, subscriber churn benchmarks by geography, and payment ecosystem maturity differentials.
Underlying measurement precision varies by segment; video streaming and enterprise SaaS carry tighter precision than emerging spoken-word advertising categories due to disclosure standardization gaps. Forecasts reflect assumptions regarding regulatory implementation timelines and content cost inflation persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Molecular Information Systems Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Big Data Technology Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
Email Deliverability Tools Market