
 CNV (Choroidal Neovascularization) Market | 2026-2036
CNV (Choroidal Neovascularization) Market Size, Share, and Industry Trends Forecast 2026-2036
CNV (Choroidal Neovascularization) Market Outlook
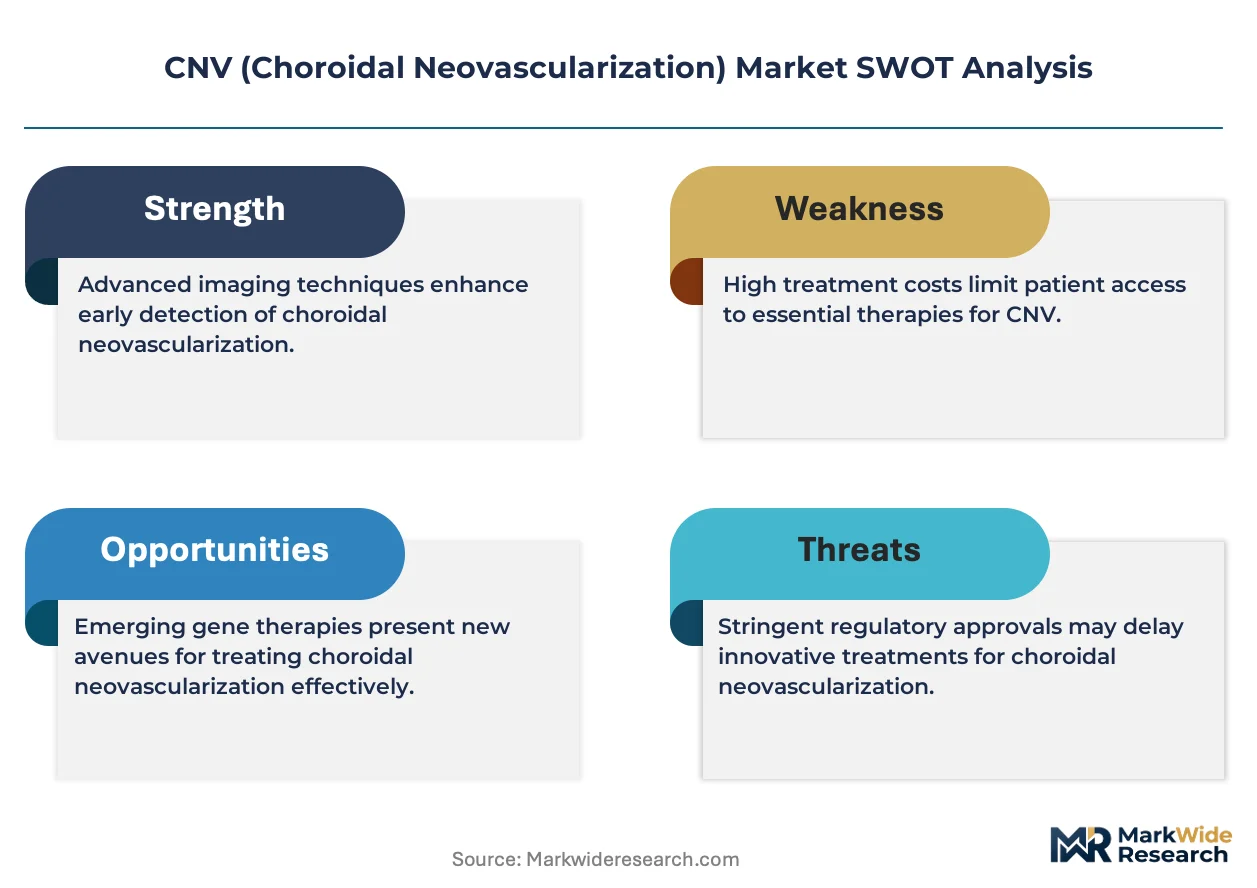
The EU MDR is decoupling legacy device approvals from new biologic-delivery combinations, forcing manufacturers to revalidate combination-product filings. Roche Holding AG anchors European ophthalmology networks through sustained Eylea manufacturing commitments. Novartis AG differentiates via Beovu positioning in high-need retinal segments. Bayer AG leverages its diagnostic-imaging portfolio to control referral pathway influence across German and French hospital systems.
Choroidal neovascularization denotes pathological blood vessel proliferation originating from the choroid through Bruch's membrane into the subretinal space, typically measured by optical coherence tomography central subfield thickness and leakage patterns on fluorescein angiography. Anti-VEGF agents dominate therapeutic value pools due to repeatable intravitreal dosing cycles and established safety profiles across wet age-related macular degeneration. Intravitreal injection leads delivery-mode utilization because physician reimbursement and facility fees align with office-based administration. Age-related macular degeneration anchors application demand, while myopic CNV represents a faster-growing subset driven by East Asian demographic prevalence.
The FDA, EMA, and ISO 14155 govern clinical-trial conduct and biologic-approval standards, with FDA accelerated pathways compressing development timelines for novel anti-VEGF mechanisms. EMA's MDR transition extends conformity-assessment durations for combination delivery devices, reshaping European launch sequencing. Stakeholders must monitor biosimilar entry timelines and evolving Payer value-framework integration to preserve pricing power and access breadth.
Market Dynamics
The FDA's accelerated approval pathways for ophthalmic biologics are compressing development timelines and intensifying competitive pressure among anti-VEGF developers, while Medicare reimbursement structures in the United States lock in office-based intravitreal injection as the dominant delivery mode.
Growth Catalysts
- Accelerated FDA pathways:The FDA's breakthrough therapy and fast track designations for novel anti-VEGF mechanisms shorten Phase III-to-approval intervals, enabling earlier revenue capture for sponsors targeting wet age-related macular degeneration.
- East Asian myopic CNV prevalence:High myopia rates in China, Japan, and South Korea expand the addressable patient pool beyond traditional AMD indications, with diagnostic infrastructure scaling to capture this subpopulation.
- Optical coherence tomography angiography:Non-invasive OCT-A imaging reduces fluorescein angiography dependency, streamlining diagnosis in hospital-based retinal clinics and expanding treatable case identification.
Market Restraints
- Anti-VEGF biosimilar entry timelines:Pending patent expirations for reference biologics threaten pricing power across European and North American markets, with formulary substitution protocols accelerating share erosion.
- EU MDR conformity assessment bottlenecks:The European Medical Device Regulation extends combination-product revalidation timelines, delaying synchronized biologic-device launches and fragmenting regional rollout sequencing.
- Intravitreal injection facility capacity:Sterile compounding pharmacy constraints and retinal specialist availability limit throughput in high-demand United States metropolitan markets.
Strategic Opportunities
- Sustained-release implant platforms:Port delivery systems and hydrogel depot technologies reduce injection frequency burden, targeting patient compliance gaps in Medicare-covered populations.
- Gene therapy for complement pathway modulation:Single-administration vectors addressing underlying angiogenic drive represent a functional cure paradigm distinct from chronic anti-VEGF suppression.
- Indian ophthalmology network expansion:Tier-2 and tier-3 city hospital chains in Maharashtra, Tamil Nadu, and Karnataka remain underpenetrated for retinal biologic access despite rising AMD incidence.
Industry Challenges
- Vitreoretinal surgeon training pipelines:Fellowship program throughput in the United States, Germany, and Japan fails to match injection volume growth, creating procedural access bottlenecks.
- Cold chain integrity for biologic distribution:Temperature excursion risks during last-mile delivery to office-based ophthalmology practices compromise product efficacy and invite regulatory scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNV (Choroidal Neovascularization) Market |
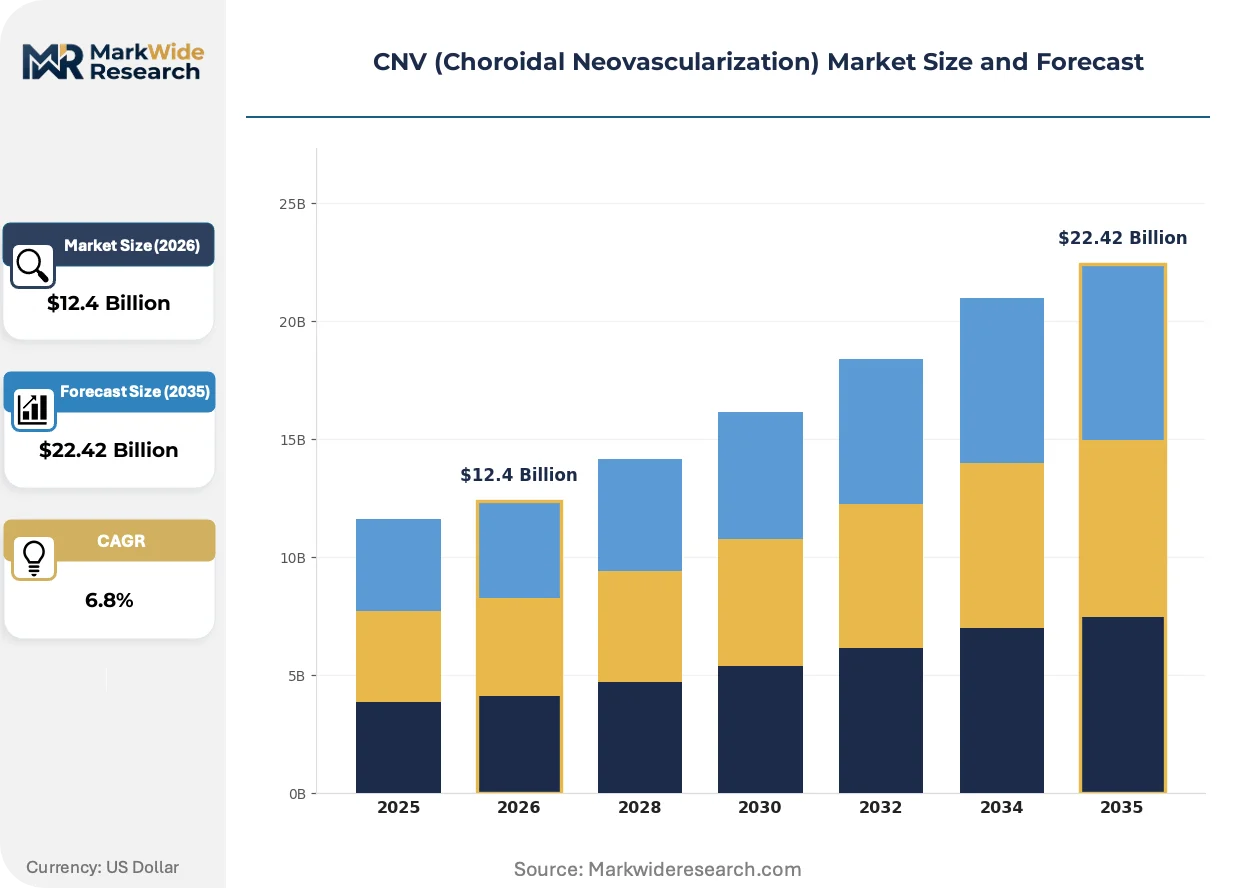
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF, Corticosteroids, PDT, Laser Treatment Delivery Mode: Intravitreal Injection, Oral, Topical, Systemic End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutes Application: Age-related Macular Degeneration, Diabetic Macular Edema, Myopic CNV, Others |
| Companies Covered | Bayer AG, Roche Holding AG, Novartis AG, Adverum Biotechnologies, Bausch Health Companies, Regeneron Pharmaceuticals, AbbVie, Neuracle Genetics, Genentech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNV (Choroidal Neovascularization) Market Strategic Shifts
Biologic delivery engineering and diagnostic imaging integration are redefining treatment protocols across retinal specialty practices. These shifts compress dosing cycles, alter site-of-care economics, and reshape competitive differentiation beyond molecular mechanism alone.
Extended-release anti-VEGF formulations are converging with refillable intravitreal implant architectures to reduce treatment burden. Retinal specialists in United States academic medical centers and large group practices are piloting port delivery systems with ranibizumab, shifting from monthly injections toward semi-annual refill intervals. This convergence is compressing the addressable market for conventional intravitreal syringes while expanding the device-biologic combination product segment.
The EU Medical Device Regulation is extending conformity assessment timelines for combination delivery systems, forcing manufacturers to decouple legacy device approvals from new biologic filings. European notified bodies face capacity constraints for ophthalmic implant reviews, delaying synchronized launches across EMA member states. German and French hospital procurement consortia are responding by front-loading diagnostic imaging contracts to maintain referral pathway control pending therapeutic device availability.
Retinal clinics are unbundling diagnostic imaging from injection reimbursement, creating distinct revenue streams for OCT-A and fluorescein angiography services. United States office-based practices are consolidating imaging equipment ownership to capture technical component fees separately from professional injection charges. This unbundling is most visible in Florida, Texas, and California markets where Medicare Advantage penetration drives site-of-care competition between hospital outpatient departments and independent specialty practices.
CNV (Choroidal Neovascularization) Market Segmentation
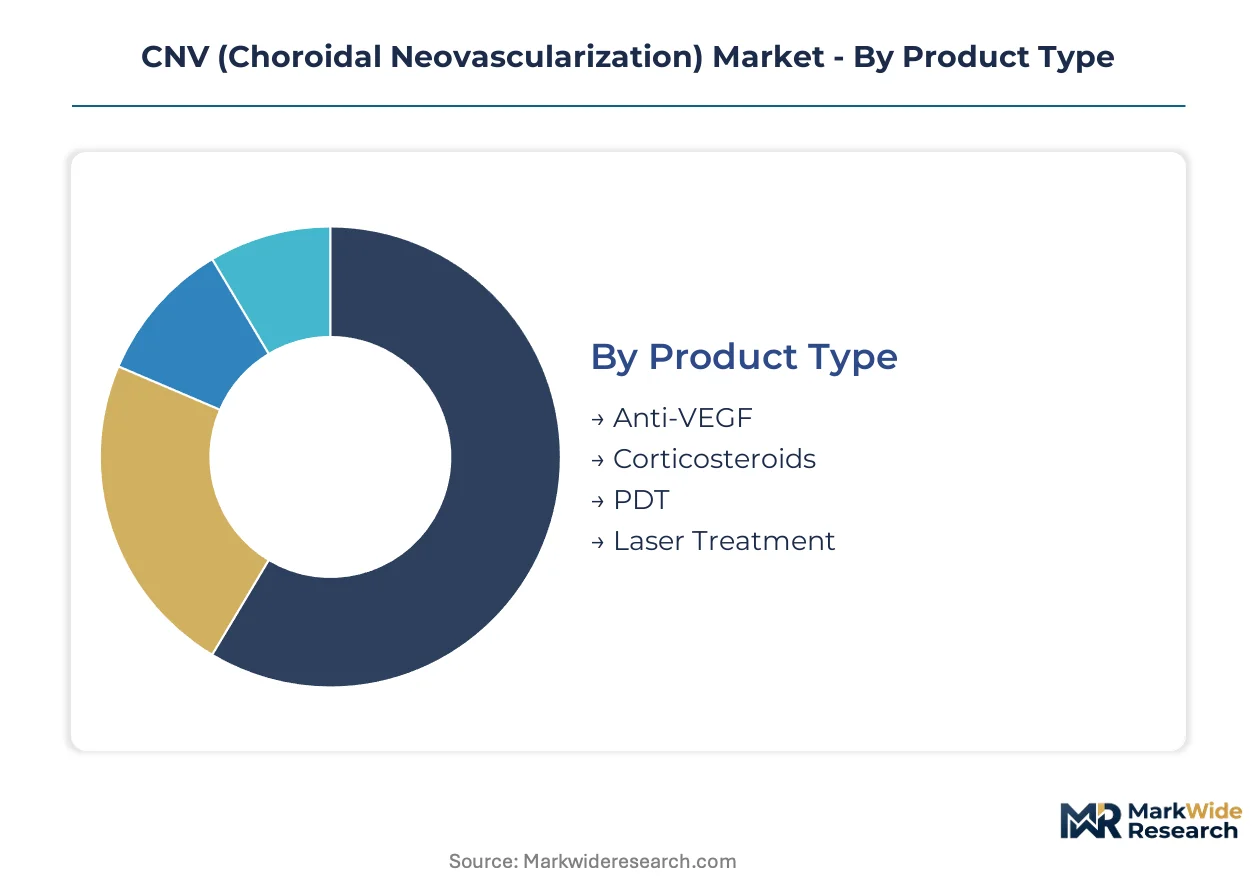
Segmentation in choroidal neovascularization therapeutics reveals divergent growth economics across mechanism classes and administration settings. Product type splits expose the revenue concentration in biologic agents versus the margin compression facing legacy modalities. Delivery mode and site-of-care segmentation directly determines reimbursement capture and patient compliance economics.
Product Type:
Volume concentration clusters in anti-VEGF biologics, while premium pricing persists in combination and sustained-release platforms.
- Anti-VEGF:Intravitreal ranibizumab, aflibercept, and bevacizumab formulations suppress vascular endothelial growth factor signaling to halt pathological angiogenesis. United States retinal specialists administer these agents in office-based settings where Medicare physician fee schedules lock in reimbursement advantages. Demand concentrates in wet age-related macular degeneration with treatment cycles extending across years.
- Corticosteroids:Triamcinolone acetonide and dexamethasone implants modulate inflammatory cascades complementary to anti-VEGF mechanisms. Diabetic macular edema applications in United States academic medical centers drive utilization where steroid-responsive inflammation coexists with vascular proliferation.
- PDT:Verteporfin photodynamic therapy activates reactive oxygen species in neovascular endothelium.
- Laser Treatment:Thermal photocoagulation ablates extrafoveal leakage points in classic CNV presentations.
Mature deployment sits with Anti-VEGF. Newer deployment is concentrated in sustained-release corticosteroid implants.
Delivery Mode:
Site-of-care economics and reimbursement alignment determine utilization patterns across administration routes.
- Intravitreal Injection:Direct vitreous cavity administration achieves therapeutic concentrations at the retinal surface without systemic exposure. United States office-based ophthalmology practices capture facility fees alongside professional component reimbursement under Medicare Part B. Injection volume growth strains sterile compounding pharmacy capacity in Florida, Texas, and California metropolitan markets.
- Oral:Systemic tyrosine kinase inhibitors and integrin antagonists target angiogenic signaling without invasive administration. Patient preference for non-invasive therapy drives exploratory demand in myopic CNV populations across East Asian markets where injection anxiety limits compliance.
- Topical:Periocular and transcorneal formulations deliver agents to posterior segments through non-penetrating routes.
- Systemic:Intravenous biologics and small molecules address bilateral disease or extraocular manifestations.
Established practice patterns favor Intravitreal Injection. Oral delivery is gaining share fastest in compliance-sensitive patient segments.
End User:
Capital intensity and reimbursement differentials fragment patient capture across institutional settings.
- Hospitals:Academic medical centers and hospital-based retinal clinics house optical coherence tomography angiography infrastructure and fellowship-trained specialists. German and French hospital procurement consortia bundle diagnostic imaging with therapeutic services to control referral pathways. Medicare cost-to-charge ratios disadvantage hospital outpatient departments relative to independent practices in United States markets.
- Specialty Clinics:Independent retinal practices consolidate imaging ownership to unbundle technical component fees from professional injection charges. Florida and California markets exhibit the most pronounced site-of-care competition between specialty clinics and hospital outpatient departments.
- Ambulatory Surgical Centers:Medicare-certified facilities capture surgical case volume requiring anesthesia support.
- Research Institutes:Clinical trial sites administer investigational agents under FDA and EMA protocols.
Revenue concentration rests with Specialty Clinics. Capacity expansion is concentrated in Ambulatory Surgical Centers.
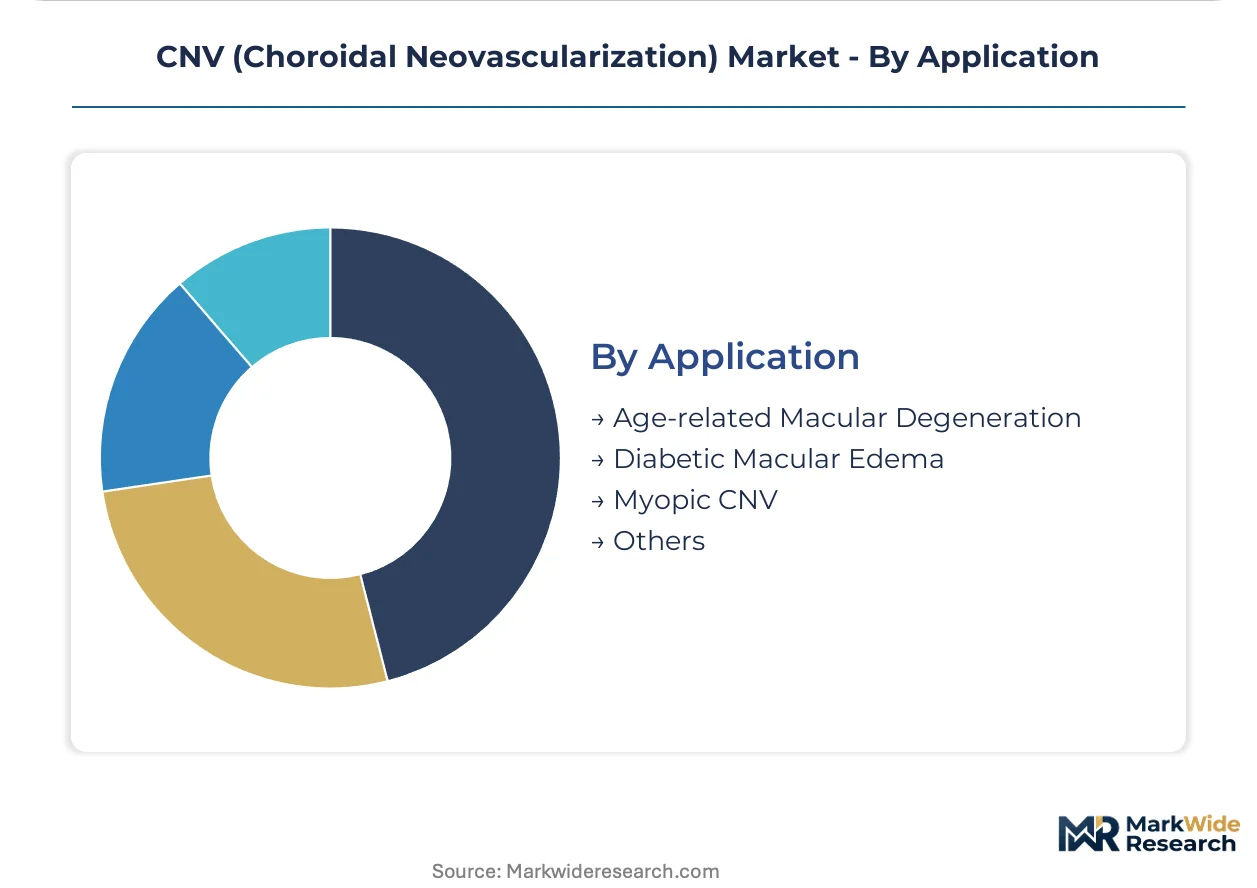
Application:
Disease prevalence and diagnostic penetration determine addressable patient pools across indication categories.
- Age-related Macular Degeneration:Neovascular AMD originates from Bruch's membrane breakdown permitting choroidal vessel invasion into subretinal space. United States Medicare beneficiaries represent the core demographic with diagnostic infrastructure scaling through optometric referral networks. Anti-VEGF therapy has transformed visual outcomes from inevitable blindness to maintained functional acuity.
- Myopic CNV:Pathological myopia drives neovascular complications in younger patients across China, Japan, and South Korea where high myopia prevalence exceeds twenty percent. Diagnostic infrastructure expansion in tier-2 Chinese cities captures previously undiagnosed cases.
- Diabetic Macular Edema:Retinal vascular permeability complicates diabetic retinopathy progression.
- Others:Ocular histoplasmosis syndrome and angioid streaks represent niche indications.
Therapeutic maturity anchors Age-related Macular Degeneration. Steepest expansion trajectory characterizes Myopic CNV.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-based retinal clinics in Boston and Philadelphia anchor United States therapeutic demand for anti-VEGF protocols, with Medicare reimbursement structures locking in office-based injection economics across Northeast and Southeast metropolitan corridors.
United States
Medicare Part B physician fee schedules favor independent retinal practices in Florida and Texas, where unbundled imaging technical component fees create distinct revenue streams from injection services. FDA accelerated approval pathways compress Phase III-to-market intervals for novel anti-VEGF mechanisms. Retinal specialist fellowship programs in California and New York fail to match injection volume growth, creating procedural access bottlenecks in Los Angeles and Manhattan markets.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia bundle diagnostic imaging with therapeutic services to control referral pathways. EU MDR conformity assessment bottlenecks delay synchronized biologic-device launches across EMA member states. Heidelberg and Munich academic medical centers house optical coherence tomography angiography infrastructure that streamlines CNV diagnosis in hospital-based retinal clinics.
China
High myopia prevalence exceeding twenty percent in Shanghai and Guangzhou expands the addressable patient pool for myopic CNV beyond traditional AMD indications. NMPA regulatory frameworks govern clinical-trial conduct and biologic-approval standards for ophthalmic therapeutics. Tier-2 city hospital chains in Sichuan-Chongqing and Shandong Peninsula remain underpenetrated for retinal biologic access despite rising age-related macular degeneration incidence.
Japan
PMDA oversight of ophthalmic biologics maintains rigorous safety standards for intravitreal anti-VEGF therapies administered in Tokyo and Osaka retinal specialty practices. METI industrial policy supports diagnostic imaging infrastructure deployment across Kansai and Chubu regions. Nagoya and Kyoto academic centers pilot sustained-release implant platforms to reduce injection frequency burden in aging patient populations.
India
Tier-2 and tier-3 city hospital chains in Maharashtra, Tamil Nadu, and Karnataka present underpenetrated expansion opportunities for retinal biologic access. CDSCO regulates clinical-trial conduct and biologic-approval standards for ophthalmic therapeutics entering the Indian market. Mumbai and Chennai metropolitan clusters concentrate diagnostic infrastructure and fellowship-trained retinal specialists capable of scaling intravitreal injection throughput.
CNV (Choroidal Neovascularization) Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with established ophthalmology networks. Anti-VEGF value pools concentrate among developers with sustained manufacturing commitments and diagnostic-imaging portfolio control. Three archetypes dominate: integrated biologic-device combination product specialists, pure-play retinal therapeutics developers, and diversified healthcare conglomerates leveraging diagnostic referral pathway influence. Competitive moves center on sustained-release platform engineering and EU MDR combination-product revalidation capabilities.
Among Swiss and German pharmaceutical conglomerates, Roche Holding AG, Bayer AG, and Novartis AG occupy positions anchored by European ophthalmology network commitments and diagnostic portfolio breadth. Roche exemplifies the integrated biologic-device archetype through sustained Eylea manufacturing and port delivery system investments. Bayer represents the diagnostic-referral pathway model, leveraging imaging portfolio control across German and French hospital procurement networks. Novartis sits within the high-need retinal segment specialization tier, with Beovu positioning targeting treatment-resistant patient populations.
| Leading Market Players |
|---|
| Bayer AG |
| Roche Holding AG |
| Novartis AG |
| Adverum Biotechnologies |
| Bausch Health Companies |
| Regeneron Pharmaceuticals |
| AbbVie |
| Neuracle Genetics |
| Genentech |
| Others |
Value Chain & Pricing Dynamics
EU MDR environmental compliance for combination-product revalidation gates qualified supply access for sustained-release implant platforms and anchors premium-tier pricing for manufacturers with notified body certification in Germany and France.
Pricing Analysis
Outcome-based pricing anchors anti-VEGF reimbursement through Medicare physician fee schedules that tie payment to injection throughput and visual acuity maintenance benchmarks. Price differentiation separates port delivery system premiums from standard intravitreal syringe reimbursement tiers, with brand premiums persisting for Eylea and Beovu against biosimilar pressure. Pricing pressure stems from formulary substitution protocols accelerating reference biologic share erosion in European markets. Hospital outpatient departments exhibit highest price sensitivity due to Medicare cost-to-charge ratio disadvantages versus independent specialty clinics.
Supply Chain Analysis
Dual-sourcing requirements from United States retinal practices mandate qualified sterile compounding pharmacy networks alongside primary manufacturer supply channels to mitigate cold chain excursion risks. Manufacturing concentration centers on Roche's Genentech facilities in California, Novartis production in Switzerland, and Bayer pharmaceutical operations in Germany. Raw material dependencies span recombinant DNA cell lines, prefilled syringe components, and temperature-controlled packaging systems. Single-source vulnerability sits with retinal specialist fellowship training pipelines constraining injection throughput capacity. Distribution runs through cold chain logistics partners to office-based ophthalmology practices and hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-VEGF biosimilar entry timelines compress margin structures into a consolidation play where manufacturers lacking sustained-release platform capabilities face forced exit.
For Market Incumbents: To counter biosimilar formulary substitution protocols, prioritize backward integration into refillable implant manufacturing and secure EU MDR notified body pre-certification for combination-product filings ahead of synchronized launch sequencing. For New Entrants and Emerging Players: Begin with tier-2 Indian city hospital chains in Maharashtra and Tamil Nadu where retinal biologic access remains underpenetrated despite rising AMD incidence, leveraging diagnostic imaging bundling as the primary go-to-market wedge. For Investors and Strategic Acquirers: FDA accelerated approval pathway designations for novel anti-VEGF mechanisms are the leading indicator that sustained-release platform developers will command premium valuations; target gene therapy vectors addressing complement pathway modulation as the acquisition archetype with the longest viability window.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Combination-Product Revalidation | Notified body certification in Germany and France accelerates synchronized EMA member state launches. |
| Sustained-Release Implant Platform Development | Port delivery system engineering reduces injection frequency burden in Medicare-covered populations. |
| East Asian Diagnostic Infrastructure Expansion | OCT-A deployment in tier-2 Chinese cities captures previously undiagnosed myopic CNV cases. |
| Retinal Specialist Fellowship Pipeline Investment | California and New York academic centers address procedural access bottlenecks in high-demand metropolitan markets. |
| Gene Therapy Complement Pathway Modulation | Single-administration vectors target functional cure paradigms distinct from chronic anti-VEGF suppression. |
Study Parameters
Independent corroboration across retinal specialist interviews, hospital procurement manager discussions, and payer formulary director consultations underwrites the qualitative findings. Primary fieldwork engaged drug development executives at anti-VEGF manufacturers, regulatory affairs leads navigating FDA accelerated pathways, and GPO contracts managers at United States hospital systems. Secondary validation drew from FDA 510(k) filings, EMA marketing authorization applications, ClinicalTrials.gov ophthalmology protocols, and CMS Medicare Part B reimbursement databases. Bottom-up patient volume estimates triangulated against top-down pharmaceutical revenue disclosures.
Comparable-period anchoring to historical anti-VEGF injection volume growth patterns informed the projection framework across the analysis window. Segmentation modeling spanned mechanism class, delivery mode architecture, site-of-care setting, and regional regulatory cluster. CAGRs derived from weighted average of epidemiological prevalence trends, diagnostic infrastructure deployment rates, and reimbursement policy trajectory assumptions. Forecast inputs incorporated myopic CNV incidence projections for East Asian markets and EU MDR conformity assessment duration estimates for combination-product categories.
Underlying measurement precision varies by segment; anti-VEGF biologic volume estimates carry tighter precision than emerging gene therapy addressable patient projections. Forecasts reflect assumptions regarding FDA breakthrough therapy designation velocity and EMA notified body capacity expansion. Deviation in biosimilar interchangeability determination timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Synoptophore Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Pseudotumor Cerebri Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
Ocular Pain Market
Ophthalmology
North America Vision Care Market