
 Asia-Pacific Glaucoma Treatment Market | 2026-2036
Asia-Pacific Glaucoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Glaucoma Treatment Market Analysis
Hospital procurement of glaucoma therapies is rotating toward ophthalmology clinics and home care settings across the Asia-Pacific region. Santen Pharmaceutical Co., Ltd dominates the Japanese market through its deep geographic entrenchment in East Asian ophthalmology channels. Zhaoke Ophthalmology leverages its China-centric R&D infrastructure to develop sustained-release formulations tailored to local patient profiles. Alcon AG competes across the premium surgical segment with laser and drainage device portfolios calibrated for Asian eye anatomy.
Glaucoma treatment encompasses pharmacological and surgical interventions that lower intraocular pressure through aqueous humor suppression, outflow enhancement, or shunt implantation, with prostaglandin analogs functioning as first-line topical therapy by increasing uveoscleral drainage. The primary commercial purpose spans disease progression halting and vision preservation across open-angle and angle-closure patient populations. Prostaglandin analogs anchor the product type landscape as the established volume leader, while sustained-release delivery modes capture expanding margin pools by reducing patient adherence failures. Minimally invasive surgery represents the fastest-growing technology segment as clinicians shift from conventional trabeculectomy toward stent-based and ablative procedures with shorter recovery windows.
Japan's PMDA and Australia's TGA enforce divergent clinical evidence standards for novel drainage implants, creating fragmented market access timelines across the region. India's CDSCO aligns with BIS pharmaceutical standards to govern generic manufacturing quality for beta blocker and carbonic anhydrase inhibitor exports. China's NMPA implements accelerated review pathways for innovative ophthalmic devices under its priority审评程序. Stakeholders must monitor regulatory harmonization momentum between ASEAN national agencies and major Western reference authorities to anticipate approval bottleneck shifts.
Market Dynamics
Japan's PMDA accelerated approval pathways for sustained-release drug delivery systems are compressing product launch timelines across the Asia-Pacific region, forcing competitors to recalibrate their clinical trial investments and regulatory submission sequencing.
Growth Catalysts
- India's National Blindness Control Program:Government-funded screening expansion is widening treatment access in rural districts previously underserved by ophthalmology infrastructure.
- Minimally Invasive Glaucoma Surgery (MIGS):Stent-based and ablative procedures with shorter recovery windows are displacing conventional trabeculectomy in Southeast Asian clinics.
- China's NMPA Priority Review Program:Accelerated device approvals under the 审评程序 are compressing market entry timelines for innovative drainage implants.
Market Restraints
- Prostaglandin analog supply concentration:Active pharmaceutical ingredient production clusters in select Indian manufacturing zones create single-source vulnerability for first-line topical therapies.
- Divergent clinical evidence standards:Australia's TGA imposes distinct trial requirements from Japan's PMDA for novel drainage implants, fragmenting regional approval timelines.
- Cost barriers to sustained-release systems:Premium pricing for drug-eluting implants limits penetration in price-sensitive public hospital procurement channels.
Strategic Opportunities
- Indonesia's underpenetrated screening infrastructure:Archipelago geography and ophthalmologist scarcity create whitespace for telemedicine-enabled diagnostic networks.
- Home care medication administration:Patient-administered sustained-release formulations are opening direct-to-consumer channels bypassing clinic-centered distribution.
- ASEAN regulatory harmonization momentum:Alignment initiatives between national agencies and reference authorities promise streamlined multi-country market access.
Industry Challenges
- Microsurgical skill scarcity:MIGS stent placement and laser ablation techniques require specialized training unavailable in many tier-two hospital systems.
- Legacy device integration friction:New drainage implants must interface with existing phacoemulsification platforms, complicating surgical workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Glaucoma Treatment Market |
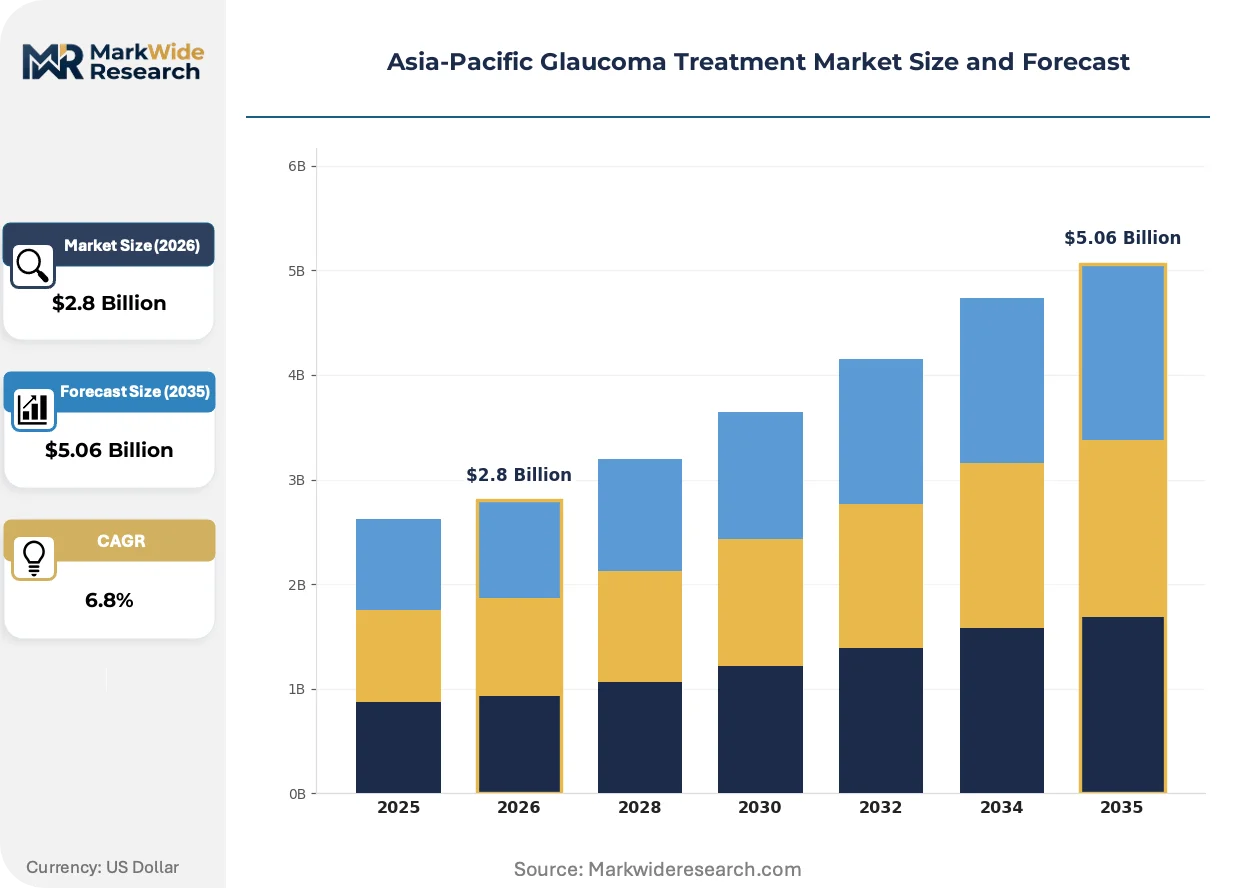
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prostaglandin Analogs, Beta Blockers, Alpha Agonists, Carbonic Anhydrase Inhibitors Delivery Mode: Topical, Injectable, Oral, Sustained Release End User: Hospitals, Ophthalmology Clinics, Home Care, Research Institutions Technology: Laser Surgery, Medication, Minimally Invasive Surgery, Drainage Devices |
| Companies Covered | AbbVie Inc, Novartis AG, Santen Pharmaceutical Co., Ltd, Teva Pharmaceutical Industries Ltd, Sun Pharmaceutical Industries Ltd, Zhaoke Ophthalmology, Bausch & Lomb Inc, Thea Pharma Inc, Alcon AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Glaucoma Treatment Market Emerging Trajectories
Sustained-release drug delivery systems are bifurcating competitive positioning across the Asia-Pacific glaucoma landscape, separating manufacturers with platform capabilities from those dependent on conventional topical formulations.
Implantable drug reservoirs are bifurcating the pharmacological segment by eliminating adherence failures that plague daily drop regimens. Ophthalmology clinics in Japan and South Korea are prioritizing these devices for elderly populations with manual dexterity limitations. The technology is bifurcating margin pools toward procedure-based revenue models and away from recurring prescription economics.
China's NMPA priority review program is compressing approval timelines for innovative ophthalmic devices, creating first-mover advantages for sponsors with established local clinical trial infrastructure. Domestic manufacturers leveraging this pathway are securing market access ahead of multinational competitors awaiting reference-country approvals. The regulatory tailwind most benefits sustained-release implants and laser-based surgical platforms targeting angle-closure populations.
Hospital procurement committees are unbundling device selection from surgeon preference, centralizing purchasing decisions at health system level across Australia and urban China. This consolidation is displacing individual clinician-driven adoption patterns that historically governed trabecular meshwork device selection. The shift is most visible in Singapore's integrated hospital networks and Thailand's provincial health authorities.
Asia-Pacific Glaucoma Treatment Market Segmentation
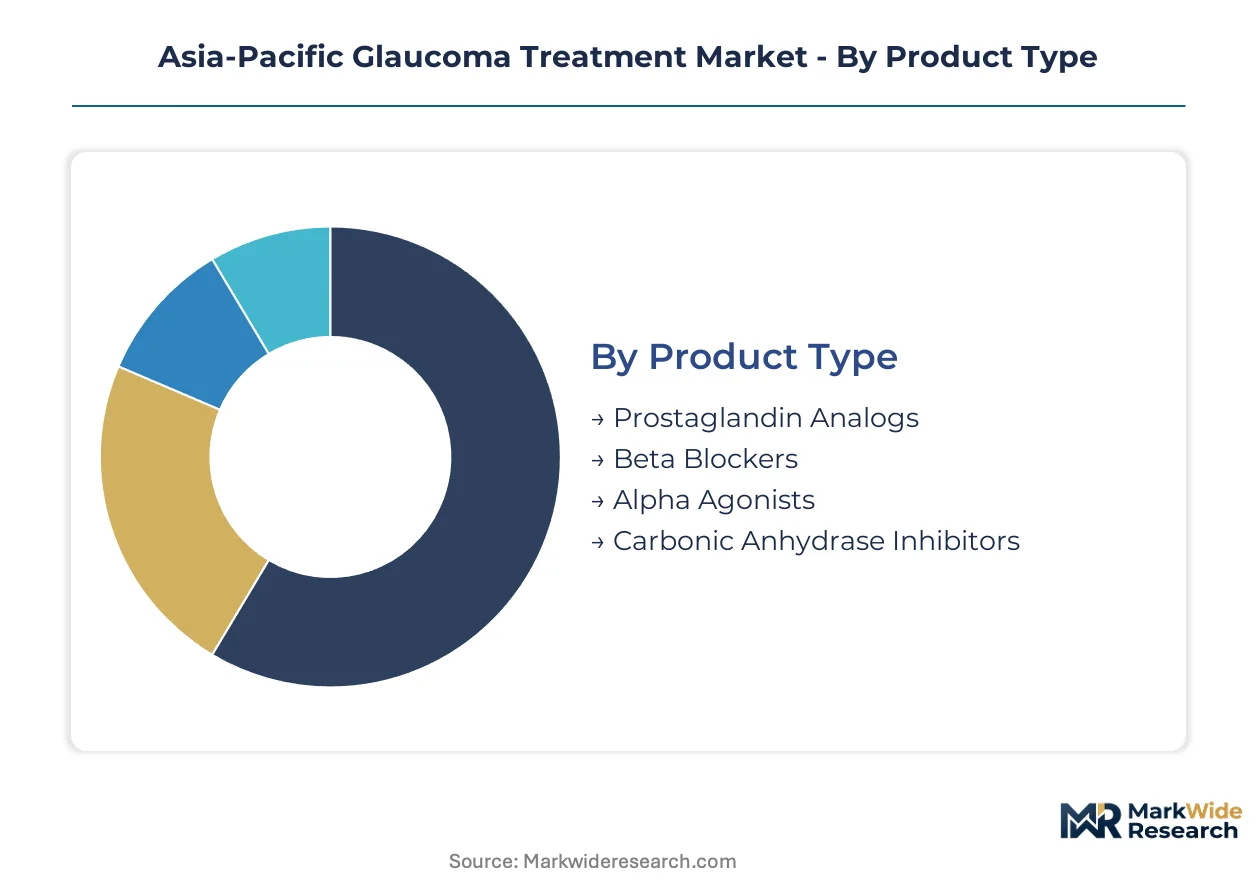
Segmentation in the Asia-Pacific glaucoma treatment market reveals how margin pools concentrate around procedure-based revenue models and away from commoditized topical therapies. Understanding these splits enables manufacturers to calibrate R&D investments toward sustained-release platforms and MIGS technologies capturing premium pricing.
Product Type:
Margin pools concentrate in formulations with patent-protected mechanisms and dosing advantages that command reimbursement premiums.
- Prostaglandin Analogs:These agents increase uveoscleral outflow through FP receptor agonism, typically administered as once-daily drops. Demand concentrates in India's National Blindness Control Program procurement channels, where latanoprost and bimatoprost generics face price compression from domestic manufacturers.
- Beta Blockers:Non-selective beta-adrenergic antagonists reduce aqueous humor production through ciliary body suppression. Japanese ophthalmology clinics favor fixed-dose combinations with prostaglandins, rotating procurement toward convenience-driven formulations that improve adherence in elderly populations.
- Alpha Agonists:Brimonidine and similar agents work through dual aqueous suppression and uveoscleral enhancement mechanisms.
- Carbonic Anhydrase Inhibitors:Oral and topical formulations targeting ciliary body bicarbonate transport remain secondary lines due to systemic side effect profiles.
Prostaglandin analogs hold installed capacity. Fixed-dose combinations are rotating up the share rankings.
Delivery Mode:
Cost tier stratification separates daily self-administered therapies from premium implantable systems requiring surgical placement.
- Sustained Release:Biodegradable reservoirs and intracameral implants eliminate adherence failures through months-long drug elution. South Korean clinics prioritize these for patients with manual dexterity limitations, with PMDA accelerated pathways compressing access timelines.
- Topical:Eye drop formulations dominate prescription volumes but face margin erosion from Indian generic manufacturing clusters supplying Southeast Asian markets.
- Injectable:Intravitreal and subconjunctival administration routes enable depot formulations bypassing corneal barriers.
- Oral:Systemic carbonic anhydrase inhibitors serve acute pressure reduction scenarios in hospital settings.
Sustained release commands premium tier pricing. Topical formulations anchor volume leadership.
End User:
Customer type determines procurement authority and pricing leverage, with health system consolidation shifting purchasing away from individual clinicians.
- Ophthalmology Clinics:Specialized facilities across Southeast Asia are expanding MIGS procedural capacity, capturing patients from hospital outpatient departments through shorter recovery protocols and dedicated surgical scheduling.
- Hospitals:Tertiary centers in Australia and urban China maintain complex case referral networks for refractory glaucoma requiring trabeculectomy or tube shunt revision.
- Home Care:Patient-administered therapies open direct-to-consumer channels, particularly for established topical regimens with stable dosing.
- Research Institutions:Academic medical centers in Japan and South Korea drive clinical trial enrollment for novel sustained-release platforms.
Ophthalmology clinics are gaining procedure share. Hospital procurement committees retain high-complexity case control.
Technology:
Application focus separates chronic medical management from interventional approaches with discrete reimbursement events.
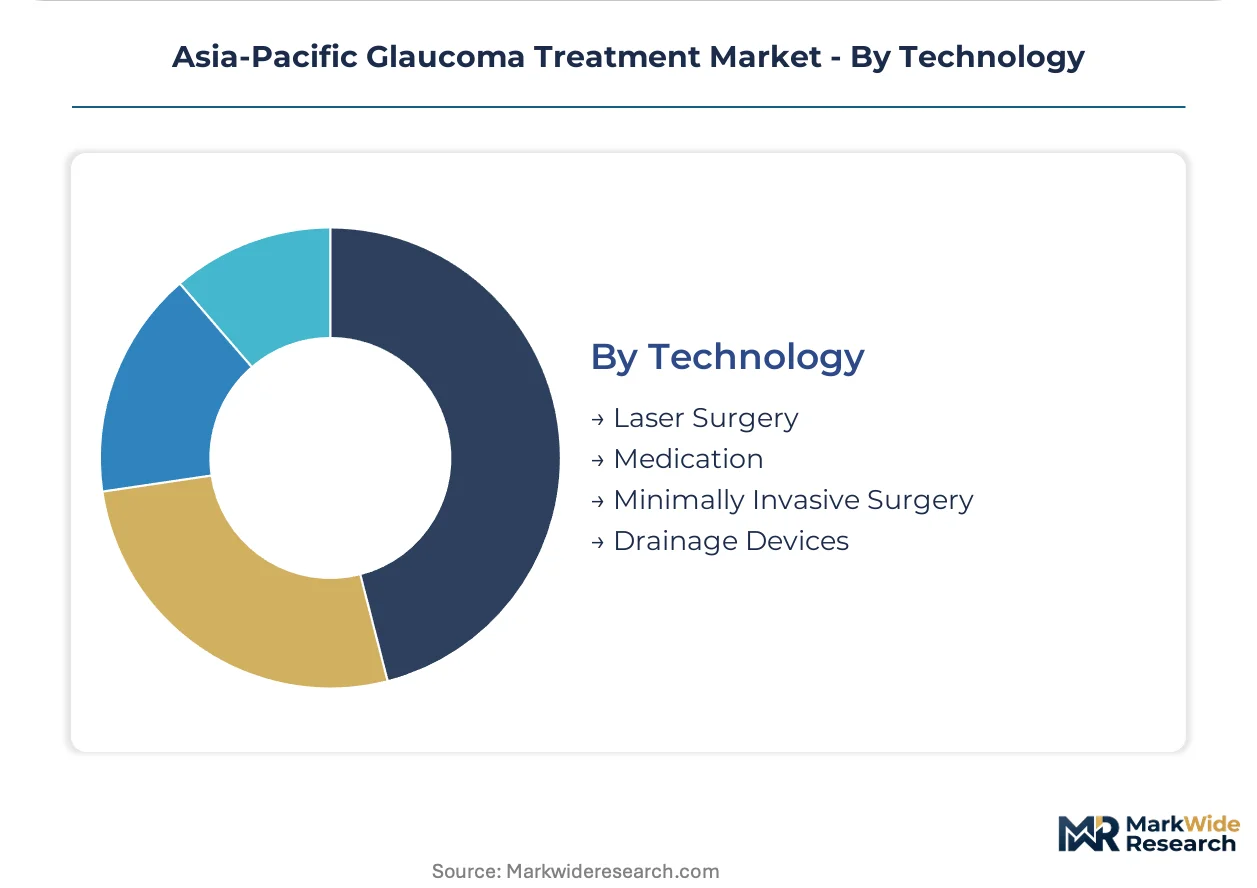
- Minimally Invasive Surgery:Stent-based trabecular meshwork bypass and ablative procedures displace conventional filtration surgery across Thailand's provincial health systems, with shorter recovery windows enabling higher surgical throughput.
- Laser Surgery:Selective laser trabeculoplasty and iridotomy serve early-stage disease and angle-closure prophylaxis in Singapore's integrated hospital networks.
- Medication:Pharmacological management remains first-line across public health programs with constrained surgical capacity.
- Drainage Devices:Ahmed and Baerveldt tube shunts address refractory cases failing prior interventions.
Medication anchors first-line treatment. Minimally invasive surgery is climbing the fastest as MIGS platforms expand indication breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore's container throughput underwrites Southeast Asia's role as the distribution hub for ophthalmic devices entering Indonesia, Thailand, and Vietnam. Japan's Shinkansen freight network enables rapid cold-chain transport of sustained-release implants from Osaka manufacturing zones to Tokyo's tertiary hospitals.
Japan
Elderly populations with manual dexterity limitations drive demand for implantable drug reservoirs in Kanto region clinics. PMDA accelerated approval pathways compress product launch timelines for sustained-release delivery systems. Osaka's pharmaceutical manufacturing corridor hosts production facilities supplying East Asian ophthalmology channels.
China
Angle-closure glaucoma prevalence in northern provinces sustains demand for laser-based surgical platforms. NMPA priority review programs compress market entry timelines for innovative drainage implants. Yangtze River Delta medical device clusters in Suzhou and Shanghai manufacture stent-based platforms for domestic and export markets.
India
Rural district screening expansion under the National Blindness Control Program widens treatment access beyond urban ophthalmology centers. CDSCO alignment with BIS pharmaceutical standards governs generic manufacturing quality for beta blocker exports. Active pharmaceutical ingredient production clusters in Gujarat and Maharashtra supply prostaglandin analog formulations across Southeast Asian markets.
Australia
Integrated hospital networks in New South Wales centralize procurement decisions for MIGS devices away from individual surgeon preferences. TGA clinical evidence standards for novel drainage implants diverge from Japanese requirements, fragmenting regional approval timelines. Sydney's quaternary referral centers maintain complex case networks for refractory glaucoma requiring tube shunt revision.
South Korea
Seoul Capital Area clinics prioritize sustained-release implants for aging patients with adherence challenges. MFDS regulatory frameworks align with international reference standards for ophthalmic device approvals. Busan-Ulsan's medical technology corridor hosts manufacturing facilities serving domestic and Asia-Pacific export demand.
Asia-Pacific Glaucoma Treatment Market Vendor Landscape
Listed leaders compete with private specialists across patent-protected formulation portfolios and generic manufacturing scale. The vendor base spans multinational pharmaceutical conglomerates with ophthalmology divisions, regional specialists with deep geographic entrenchment, and domestic manufacturers leveraging local regulatory pathways. Three archetypes dominate: platform technology developers with sustained-release capabilities, volume-driven generic producers, and surgical device innovators with MIGS portfolios. Competitive moves concentrate on regulatory submission sequencing and health system procurement consolidation.
Among Japan-based specialists, Santen Pharmaceutical Co., Ltd anchors the East Asian ophthalmology channel position. Chinese domestic manufacturers exemplified by Zhaoke Ophthalmology occupy positions leveraging NMPA priority review infrastructure. Swiss-incorporated multinationals represented by Novartis AG sit within the premium formulation tier. These three entities represent distinct competitive vectors: geographic channel control, regulatory pathway optimization, and global brand equity.
| Leading Market Players |
|---|
| AbbVie Inc |
| Novartis AG |
| Santen Pharmaceutical Co., Ltd |
| Teva Pharmaceutical Industries Ltd |
| Sun Pharmaceutical Industries Ltd |
| Zhaoke Ophthalmology |
| Bausch & Lomb Inc |
| Thea Pharma Inc |
| Alcon AG |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for prostaglandin analog APIs concentrate pricing power with Gujarat and Maharashtra manufacturing clusters, while Japanese PMDA accelerated pathways for sustained-release implants compress procurement timelines and expand margin capture for procedure-based revenue models across ophthalmology clinics.
Pricing Analysis
Volume-discount tiering structures separate public hospital procurement in India from premium private channels in Japan and South Korea. Three-tier pricing stratification across sustained-release implants, fixed-dose combinations, and generic monotherapies reflects patent status and reimbursement classification. Price differentiation hinges on NMPA priority review certification and surgical placement bundling. Cost compression in generic topical segments intensifies as CDSCO-aligned manufacturers expand export capacity, while private ophthalmology clinics in Tokyo and Seoul demonstrate lowest price sensitivity for implantable drug reservoirs.
Supply Chain Analysis
Just-in-time inventory strategies dominate Japanese and South Korean clinic procurement for biodegradable implants, while Indian and Southeast Asian distributors maintain strategic stockpiles of prostaglandin analog APIs against monsoon logistics disruptions. Active pharmaceutical ingredient production clusters in India, China, and Japan anchor upstream supply for first-line topical therapies. Raw material dependencies include latanoprost acid intermediates, silicone stent polymers, and biodegradable PLGA matrices. Single-source vulnerability concentrates in select Gujarat API facilities. Distribution runs through Singapore's container hub for Southeast Asian markets and Osaka's cold-chain network for East Asian ophthalmology channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from sustained-release platforms displacing recurring prescription economics, requiring defensive repositioning around procedure-based revenue capture and adherence-failure elimination.
For Market Incumbents: Compound platform technology advantages by acquiring biodegradable implant manufacturing capabilities and securing PMDA accelerated pathway precedents before competitors replicate submission strategies. Prioritize backward integration into PLGA polymer supply to defend margin position against API cost volatility from Indian manufacturing clusters. The threat of Chinese domestic manufacturers leveraging NMPA priority review demands preemptive clinical trial infrastructure deployment in Suzhou and Shanghai.
For New Entrants and Emerging Players: Telemedicine-enabled diagnostic networks in Indonesia's archipelago geography represent the most penetrable whitespace, where ophthalmologist scarcity and island logistics fragment incumbent reach. Target provincial health authorities in Thailand with MIGS device leasing models that circumvent capital procurement committee centralization. A direct-to-consumer channel for patient-administered sustained-release formulations bypasses clinic-centered distribution entirely.
For Investors and Strategic Acquirers: Long-term, this sits as a demographic tailwinds play because Asia-Pacific aging populations and angle-closure prevalence sustain structural demand for pressure-lowering interventions across the analysis window. Acquisition targets should display platform technology capabilities spanning biodegradable reservoirs and laser-based surgical platforms rather than single-product dependencies. Watch MFDS-PMDA regulatory harmonization momentum as the signal indicating accelerated multi-country market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Accelerated Approval Pathway | Compresses product launch timelines for sustained-release implants in Japanese ophthalmology channels. |
| NMPA Priority Review Program | Creates first-mover advantages for domestic manufacturers ahead of multinational reference-country approvals. |
| Hospital System Partnership | Centralizes procurement decisions in Singapore's integrated networks and Thailand's provincial authorities. |
| Backward Integration into API Supply | Secures captive production of prostaglandin analog intermediates against Gujarat cluster concentration risk. |
| Telemedicine Diagnostic Network | Addresses Indonesia's archipelago geography constraints and ophthalmologist scarcity through remote screening. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with ophthalmology clinic directors, hospital procurement committee members, regulatory affairs specialists at PMDA and NMPA, and pharmaceutical manufacturing executives in Osaka and Suzhou. Secondary validation drew from FDA 510(k) filings for drainage implants, CDSCO manufacturing facility inspection records, ClinicalTrials.gov enrollment data for sustained-release platforms, and ASEAN harmonization working group publications. Bottom-up prescription volume modeling and top-down healthcare expenditure triangulation anchored market sizing.
Across the projection horizon, the analytical framework segmented value pools by product type, delivery mode, end user, and technology intervention, with regional regulatory clusters treated as distinct access scenarios. CAGRs derived from procedure volume trajectories in Southeast Asian clinics and reimbursement rate assumptions for MIGS devices. Forecast inputs included National Blindness Control Program procurement expansion timelines and NMPA priority review queue velocities.
Material uncertainties — regulatory harmonization reversals, API facility shutdowns, and MIGS training capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about PMDA-TGA alignment momentum and sustained-release implant adoption curves in elderly populations. Revision becomes warranted when ASEAN regulatory convergence stalls or prostaglandin analog supply concentration triggers procurement disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Pseudotumor Cerebri Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Astigmatism Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Vernal Keratoconjunctivitis Market