
 North America Vision Care Market | 2026-2036
North America Vision Care Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vision Care Market Intelligence
Silicone hydrogel is displacing traditional hydrogel in daily disposable lenses and is realigning manufacturing cost structures across the supply base. Alcon Inc. leverages captive polymer science to sustain margins on premium toric and multifocal designs. EyeCare Partners LLC anchors its position through dense clinic networks across the southeastern United States. National Vision Holdings, Inc. competes on price-accessibility through Walmart Inc. store-in-store locations.
Vision care encompasses the diagnosis, correction, and management of refractive errors and ocular surface conditions using optical devices, pharmaceutical agents, and procedural interventions. Contact lenses now incorporate surface-wetting technologies with oxygen permeability exceeding 100 Dk/t to support extended wear protocols. Eyeglasses retain the largest revenue pool due to replacement-driven purchase cycles and fashion-linked frame turnover. Online retail represents the fastest-growing distribution channel as virtual try-on tools and prescription verification workflows reduce friction for replacement-lens reordering.
FDA 510(k) pathways govern clearance of novel contact lens materials and designs, while the FTC Eyeglass Rule mandates prescription release to protect consumer choice. State-level optometry practice acts vary in permitting collaborative arrangements between retailers and licensed professionals. Stakeholders must monitor how FDA guidance on myopia-control devices and evolving state telehealth regulations reshape competitive access and service delivery models.
Market Dynamics
Silicone hydrogel polymer chemistry is compressing product development cycles and forcing wholesale recalibration of manufacturing asset bases across the North American contact lens supply chain.
Growth Catalysts
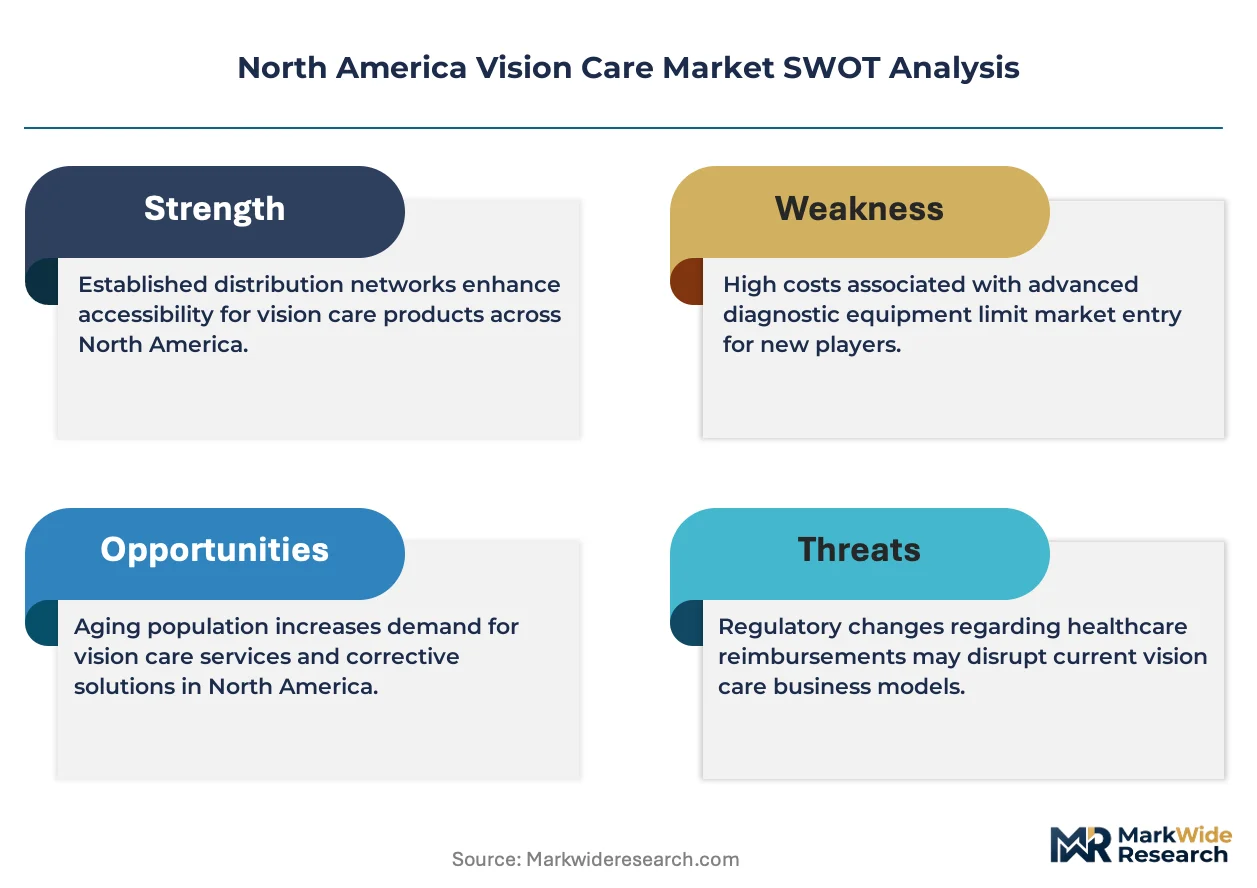
- FDA 510(k) pathway compression:Accelerated clearance timelines for extended-wear silicone hydrogel designs are shortening the gap between R&D completion and commercial launch.
- Presbyopia correction demand:Aging populations in the United States are intensifying pull for multifocal and toric lens configurations.
- California and Texas metropolitan density:Concentrated patient bases in these states sustain dense optical retail and clinic networks that drive replacement-lens velocity.
Market Restraints
- Silicone monomer supply concentration:Critical polymer feedstocks concentrate among a narrow supplier base, exposing manufacturers to input volatility.
- State-level optometry practice act fragmentation:Varied regulations governing collaborative arrangements between retailers and licensed professionals create compliance friction.
- Lasik and refractive surgery substitution:Permanent vision correction procedures capture younger demographics who otherwise would enter contact lens replacement cycles.
Strategic Opportunities
- Telehealth-enabled prescription verification:Virtual try-on tools and remote prescription workflows are unlocking online channel expansion for replacement-lens reordering.
- FDA myopia-control device guidance:Emerging regulatory clarity for pediatric myopia management devices opens pediatric-specialist channel development.
- Southeastern United States clinic network gaps:Underpenetrated rural and exurban markets present whitespace for dense service-point expansion.
Industry Challenges
- Polymer science talent scarcity:Captive silicone hydrogel formulation expertise concentrates at incumbent manufacturers, constraining new entrant R&D velocity.
- Legacy prescription management system integration:Optical retailers face friction unbundling in-store verification workflows for omnichannel fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vision Care Market |
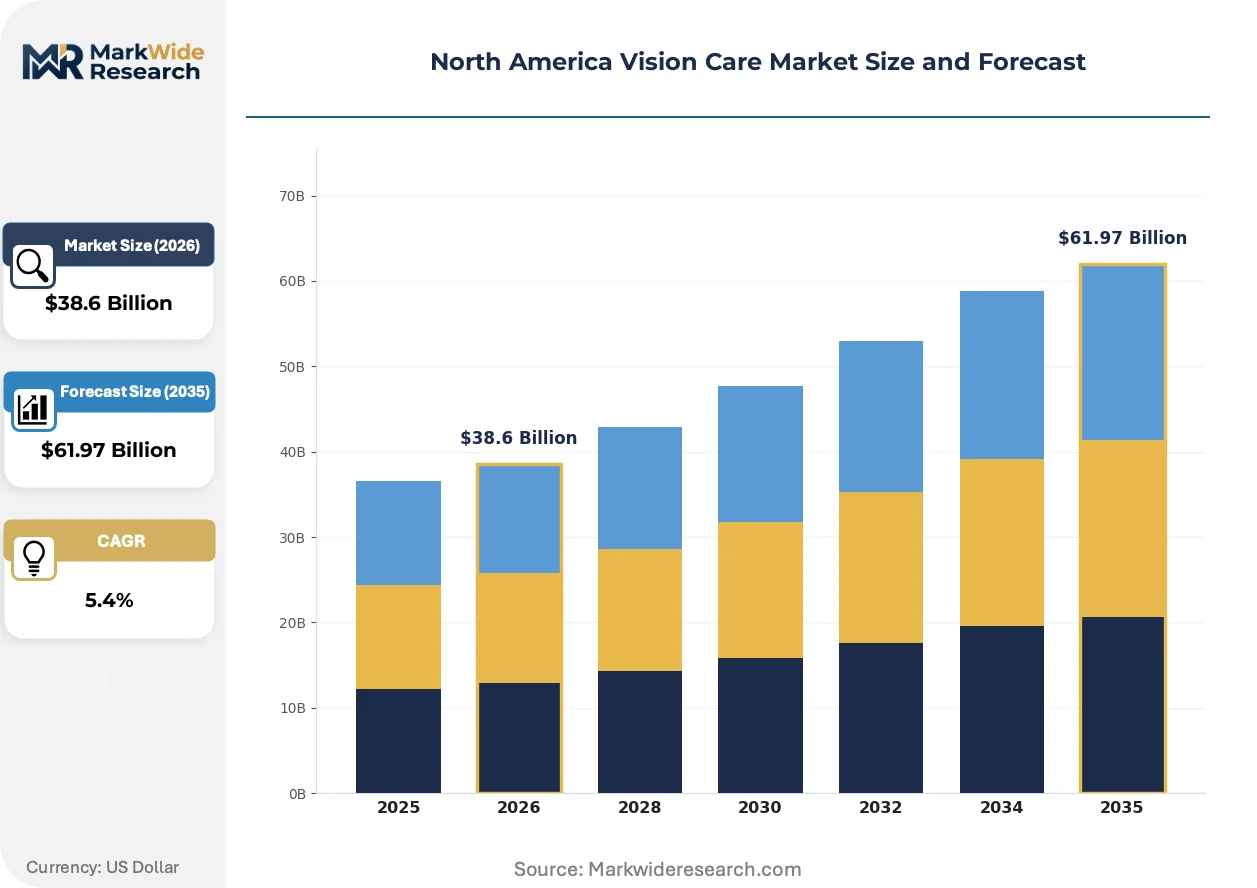
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
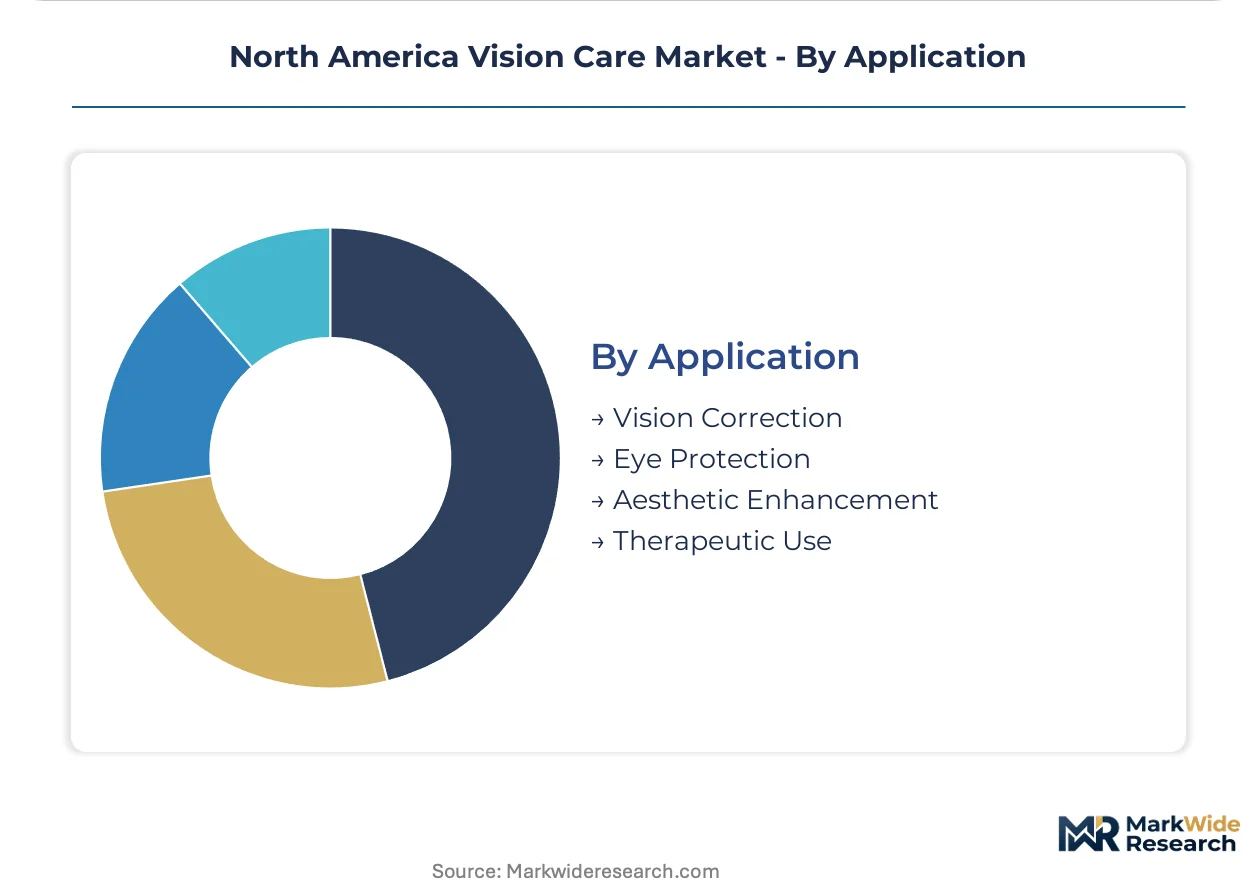
| Segmentation | Product Type: Contact Lenses, Eyeglasses, Prescription Sunglasses, Low Vision Aids End User: Individuals, Eye Care Professionals, Retail Stores, Clinics Distribution Channel: Online Retail, Optical Stores, Supermarkets, Pharmacies Application: Vision Correction, Eye Protection, Aesthetic Enhancement, Therapeutic Use |
| Companies Covered | EyeCare Partners LLC, Capital Vision Services dba MyEyeDr., Vision Source, AEG Vision, Visionworks of America, Inc., Walmart Inc., Costco Wholesale, Alcon Inc., National Vision Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vision Care Market Strategic Shifts & Innovations
Surface-wetting technologies and oxygen permeability engineering are redefining extended-wear protocols, while digital distribution infrastructure compresses traditional optical retail intermediation.
Silicone hydrogel lens fabrication is modularizing production economics across the North American supply base. Captive polymer science capabilities allow manufacturers to iterate toric and multifocal designs without full asset retooling. This modularity is compressing time-to-market for premium configurations and eroding the cost advantage of traditional hydrogel commodity production.
FDA guidance development on myopia-control devices is reshaping pediatric vision care access protocols. The agency's evolving framework for optical devices targeting childhood myopia progression is forcing manufacturers to build clinical evidence packages earlier in development cycles. Pediatric optometry practices in the United States are restructuring service models to accommodate device-based intervention workflows.
Online retail channels are capturing replacement-lens volume through prescription verification automation. Virtual try-on tools and digital prescription upload workflows are disintermediating traditional optical retail for established wearers with stable prescriptions. California and Texas urban markets exhibit the highest digital channel penetration, where dense metropolitan logistics networks enable same-day or next-day fulfillment.
North America Vision Care Market Segmentation
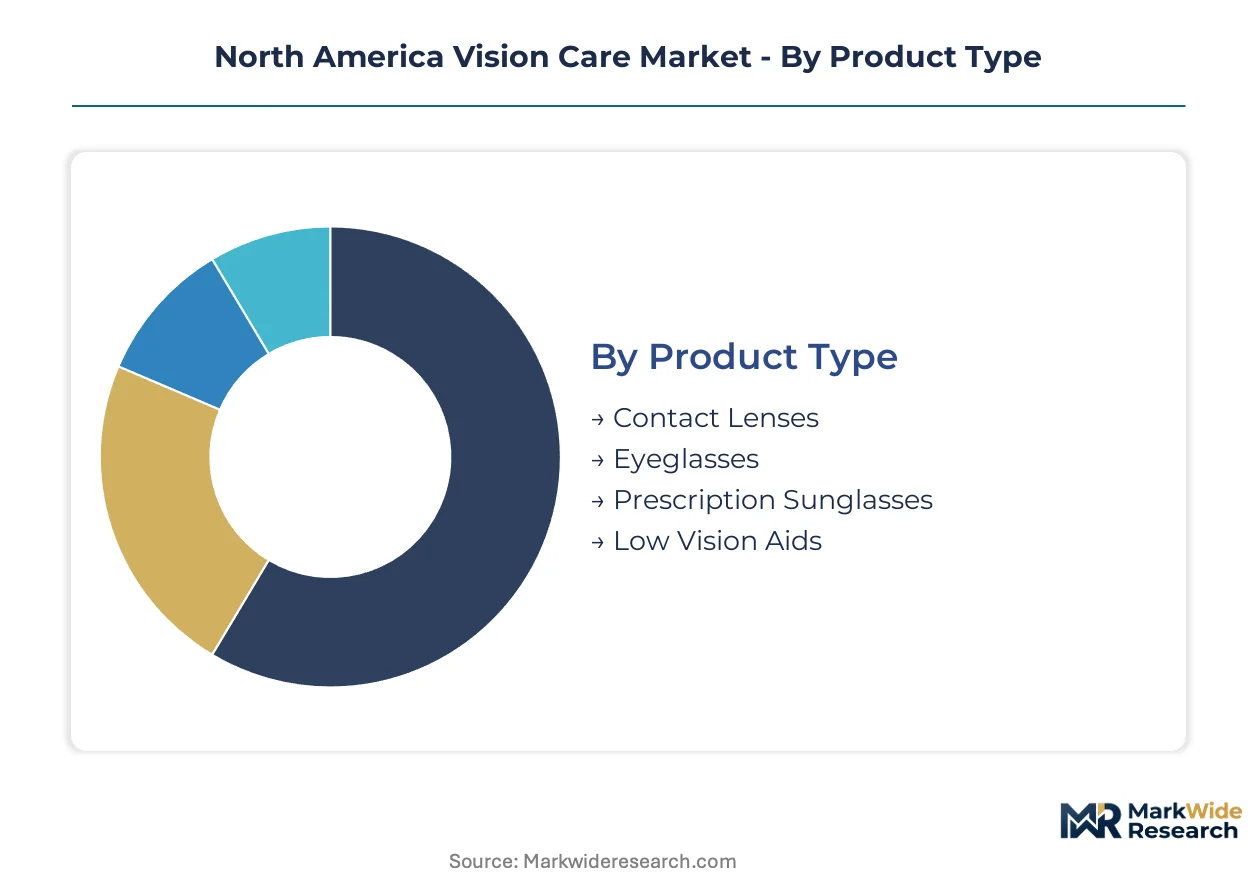
Vision care markets fragment across device categories, professional service models, and retail fulfillment pathways that each carry distinct margin profiles and regulatory exposure. Understanding these segment boundaries clarifies where silicone hydrogel polymer investments concentrate versus where fashion-driven frame turnover sustains replacement economics.
Product Type:
Customization intensity spans from mass-produced daily disposables to individually surfaced progressive lenses requiring precise vertex measurements and pupillary distance calibration.
- Contact Lenses:Silicone hydrogel formulations now dominate extended-wear protocols with oxygen permeability exceeding 100 Dk/t. Presbyopia correction demand in California and Texas metropolitan corridors pulls multifocal and toric configurations fastest.
- Eyeglasses:Replacement-driven purchase cycles combine with fashion-linked frame turnover to sustain the largest revenue pool. Independent optical retailers in dense urban markets capture premium positioning through in-house edging labs and designer frame exclusives.
- Prescription Sunglasses:Polarized and photochromic lens technologies address UV protection compliance alongside refractive correction. Coastal states with intense solar exposure drive seasonal velocity spikes.
- Low Vision Aids:Magnification devices and electronic vision enhancement systems serve age-related macular degeneration and diabetic retinopathy populations. Medicare reimbursement pathways govern access velocity for these higher-acuity interventions.
Most installed capacity flows through Eyeglasses. Expansion is steepest in Contact Lenses.
End User:
Professional credentialing requirements create sharp segmentation between direct-to-consumer transactions and clinically supervised device fitting protocols.
- Individuals:Direct purchasers span stable-prescription replacement-lens reorderers to first-time presbyopia seekers requiring education-intensive consultation. Online prescription verification workflows are compressing traditional optical retail intermediation for this segment.
- Eye Care Professionals:Optometrists and ophthalmologists anchor medically necessary contact lens fittings and myopia management protocols. FDA 510(k) clearance pathways for novel materials require clinical evidence packages that these professionals help generate.
- Retail Stores:Mass merchandisers and warehouse clubs compete on price-accessibility through high-volume frame-lens bundling. Walmart Inc. store-in-store locations exemplify this channel's geographic penetration strategy.
- Clinics:Dense service-point networks in the southeastern United States concentrate pediatric myopia management and post-surgical vision rehabilitation. EyeCare Partners LLC anchors position through multi-site clinic ownership in this corridor.
Volume concentrates with Individuals. Value capture tilts toward Eye Care Professionals.
Distribution Channel:
Fulfillment economics diverge between inventory-light digital workflows and capital-intensive optical retail requiring in-store verification equipment and licensed professional staffing.
- Online Retail:Virtual try-on tools and automated prescription upload workflows enable replacement-lens reordering without physical store visits. California and Texas urban markets exhibit highest penetration where logistics networks support same-day fulfillment.
- Optical Stores:Independent and chain locations combine eye examination services with immediate frame dispensing. State-level optometry practice act fragmentation creates compliance friction for retailers seeking omnichannel integration.
- Supermarkets:Limited-service optical departments emphasize convenience and price transparency for single-vision lens configurations. Foot traffic dependency ties performance to grocery anchor store volume.
- Pharmacies:CVS and Walgreens locations extend reading glass and basic vision screening access. Pharmacy benefit manager integration remains underdeveloped for prescription optical products.
Capital deployment favors Optical Stores. Share gains are accelerating in Online Retail.
Application:
Clinical purpose determines reimbursement eligibility, regulatory pathway, and required professional supervision intensity.
- Vision Correction:Refractive error management through spherical, toric, and multifocal designs constitutes the core revenue base. FDA myopia-control device guidance is reshaping pediatric application protocols.
- Eye Protection:Safety eyewear for industrial and athletic environments must satisfy ANSI Z87.1 impact resistance standards. OSHA workplace regulations mandate employer provision for hazardous occupations.
- Aesthetic Enhancement:Plano cosmetic lenses and non-prescription blue-light filtering glasses serve appearance and perceived wellness goals. Fashion cycle acceleration compresses product lifecycles in this application.
- Therapeutic Use:Bandage lenses for corneal healing and drug-eluting contact devices require medical device classification and prescription-only distribution. Narrow patient populations limit volume but sustain premium pricing.
Revenue depth sits with Vision Correction. Regulatory attention is intensifying around Therapeutic Use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American vision care manufacturing and distribution infrastructure, with silicone hydrogel polymer production and optical retail networks clustering across the southern United States. FDA clearance pathways and state-level optometry regulations shape competitive access across sub-regional markets. Metropolitan density in California and Texas drives replacement-lens velocity through dense clinic and retail networks.
United States
California and Texas metropolitan corridors concentrate presbyopia correction demand and support dense optical retail networks. FDA 510(k) pathways govern clearance timelines for extended-wear silicone hydrogel designs, compressing gaps between R&D completion and commercial launch. The Dallas-Fort Worth metroplex hosts manufacturing assets and distribution infrastructure serving replacement-lens markets across the southern and western states.
Canada
Ontario and Quebec urban centers concentrate vision care service delivery through provincial healthcare reimbursement frameworks. Health Canada regulates contact lens materials through medical device licensing pathways parallel to FDA structures. The Greater Toronto Area supports dense optometry clinic networks and optical retail chains serving stable-prescription replacement-lens demand.
Mexico
Mexico City and Monterrey metropolitan areas anchor vision care manufacturing for export-oriented optical component production. COFEPRIS medical device regulations govern contact lens importation and domestic manufacturing compliance. The Bajío Region hosts contract manufacturing facilities serving North American private-label frame and lens assembly.
North America Vision Care Market Key Industry Players
Global majors compete with regional champions across polymer science capabilities and retail channel access, producing a tiered structure where captive R&D assets separate premium-tier manufacturers from price-accessibility competitors. Incumbents with silicone hydrogel formulation expertise defend position through toric and multifocal design iteration, while retail consolidators capture volume through dense clinic networks and mass-merchandiser partnerships. Strategic moves concentrate on M&A-driven clinic network expansion and omnichannel prescription verification integration.
Among North American vision care operators, Alcon Inc. and National Vision Holdings, Inc. exemplify divergent archetypes: the former represents captive polymer science and premium lens manufacturing, while the latter anchors price-accessibility positioning through mass-retail partnerships. EyeCare Partners LLC occupies a position within the clinical services consolidation tier, demonstrating how dense multi-site ownership captures replacement-lens velocity in underpenetrated southeastern markets.
| Leading Market Players |
|---|
| EyeCare Partners LLC |
| Capital Vision Services dba MyEyeDr. |
| Vision Source |
| AEG Vision |
| Visionworks of America, Inc. |
| Walmart Inc. |
| Costco Wholesale |
| Alcon Inc. |
| National Vision Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
FDA sustainability mandates for silicone hydrogel manufacturing effluent gating qualified supply and premium-tier pricing access. Manufacturers without compliant polymer chemistry capabilities face exclusion from extended-wear protocol certifications, compressing margins on commodity hydrogel alternatives.
Pricing Analysis
Input-cost pass-through from silicone monomer feedstocks concentrates pricing power among captive polymer science holders. Three-tier pricing structure across premium, standard, and economy levels separates toric-multifocal configurations from daily disposable commodities. Pricing pressure stems from narrow supplier concentration for critical polymer inputs. Mass-merchandiser buyers exhibit highest price sensitivity while pediatric myopia specialists accept premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese silicone monomer suppliers feeding North American lens fabrication. Raw material dependencies center on tris(trimethylsilyl)silane precursors, platinum catalyst systems, and precision molding equipment. Tariff exposure on imported polymer feedstocks creates margin volatility for non-integrated manufacturers. Distribution runs through Dallas-Fort Worth logistics hubs serving dense California and Texas metropolitan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage FDA 510(k) pathway compression in the United States against Health Canada's parallel medical device licensing timelines to optimize regulatory capital deployment. Cost differentials between southern U.S. manufacturing clusters and Mexican Bajío contract assembly create margin expansion opportunities.
For Market Incumbents: To counter Lasik substitution capturing younger demographics, Alcon Inc. and EyeCare Partners LLC should deepen captive silicone hydrogel formulation expertise and expand pediatric myopia management clinic networks across underpenetrated southeastern corridors. Channel control through dense multi-site ownership defends replacement-lens velocity against online disintermediation. For New Entrants and Emerging Players: FDA myopia-control device guidance in the United States opens a window for pediatric-specialist channel development and telehealth-enabled prescription verification workflows. White-space concentrates in rural southeastern clinic networks and direct-to-consumer online replacement-lens reordering. Go-to-market positioning should anchor on virtual try-on tools with automated prescription upload. For Investors and Strategic Acquirers: Valuations sit cheapest among regional optical retail consolidators lacking captive polymer science. Long-term viability favors clinic network operators with dense southeastern presence and omnichannel prescription verification infrastructure. Watch FDA pediatric myopia guidance finalization as inflection signal for device-based intervention workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Hydrogel Capacity Expansion | Captive polymer production insulates Alcon Inc. from monomer supply volatility. |
| Telehealth Prescription Verification Platform | Automated workflows unlock online channel share from traditional optical retail. |
| Pediatric Myopia Management Network | Dense clinic ownership in southeastern states captures device intervention demand. |
| Mass-Retail Store-in-Store Partnership | Walmart Inc. locations extend National Vision Holdings' price-accessibility positioning. |
| FDA 510(k) Accelerated Pathway Investment | Early clinical evidence packages compress time-to-market for extended-wear designs. |
Research Approach
Multiple input streams — optometry practice administrators, silicone hydrogel polymer chemists, optical retail procurement managers, FDA regulatory affairs specialists — were reconciled against secondary validation. Primary interviews with EyeCare Partners LLC clinic operators and National Vision Holdings channel executives combined with FDA 510(k) filing records, Health Canada device licensing databases, and state-level optometry practice act compilations. Bottom-up replacement-lens volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Historical prescription velocity patterns cross-referenced against expert panel inputs on myopia-control device adoption curves. Segmentation modeling spanned product type, end user archetype, distribution channel, and application purpose across the projection horizon. CAGRs derived from metropolitan demographic projections and silicone hydrogel penetration assumptions. Forecast inputs incorporated FDA guidance timeline uncertainty and state telehealth regulatory evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA myopia-control device approval delays or silicone monomer supply disruptions. Forecasts reflect documented assumptions on presbyopia demographic trajectories and online channel penetration ceilings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Macular Edema Market
Ophthalmology
Lazy Eye Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Exophthalmos Treatment Market