
 Retail E-Commerce Market | 2026-2036
Retail E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Retail E-Commerce Market Intelligence
Chinese fulfillment networks is repositioning global logistics benchmarks through automated sortation and same-day delivery infrastructure. Amazon leverages its captive warehouse network to sustain delivery speed advantages across North American corridors. Alibaba Group Holding Limited anchors cross-border trade flows between East Asian manufacturing clusters and European consumers. JD.com dominates fresh grocery e-commerce through proprietary cold-chain assets in tier-one Chinese cities.
Retail e-commerce denotes the digital sale of goods to end consumers through internet-connected platforms, typically involving electronic payment settlement, algorithmic product recommendation engines, and last-mile logistics orchestration. The primary commercial purpose is to disintermediate physical retail infrastructure while capturing consumer behavioral data for predictive inventory positioning. Apparel and electronics categories generate the deepest margin pools due to high return frequency and accessory attach rates. Mobile apps represent the fastest-growing distribution channel as in-app checkout reduces cart abandonment versus browser-based purchasing.
The EU Digital Services Act and GDPR impose content moderation and data portability obligations on marketplace operators serving European consumers. The US FTC scrutinizes subscription billing practices and dark pattern interfaces under Section 5 enforcement authority. China's SAMR enforces anti-monopoly provisions against dominant platforms while promoting domestic cloud infrastructure standards. Stakeholders must monitor divergent regulatory timelines across these jurisdictions to calibrate compliance investment and market entry sequencing.
Market Dynamics
Automated fulfillment infrastructure is compressing delivery windows while the EU Digital Services Act and GDPR impose algorithmic accountability and data portability obligations on marketplace operators serving European consumers.
Growth Catalysts
- Cross-border logistics modernization:Automated sortation systems and proprietary cold-chain networks are enabling same-day delivery for fresh grocery categories in dense urban clusters.
- GDPR-mandated data portability:European consumers now transfer purchase histories between platforms, reducing switching costs and intensifying competition for retention.
- Mobile-first checkout optimization:In-app payment settlement is automating cart recovery and reducing abandonment versus browser-based purchasing workflows.
Market Restraints
- Last-mile labor cost volatility:Courier wage inflation in tier-one Chinese cities and North American metropolitan corridors is eroding unit economics for express delivery.
- Platform liability expansion:The EU Digital Services Act imposes direct accountability for product safety violations and counterfeit listings, elevating compliance overhead.
- Return logistics complexity:Apparel and electronics categories generate return rates exceeding 25%, consuming reverse logistics capacity and compressing net margins.
Strategic Opportunities
- Southeast Asian market penetration:Indonesia and Vietnam exhibit underpenetrated grocery e-commerce adoption among working professionals in secondary cities.
- Algorithmic transparency tooling:The EU AI Act and Digital Services Act create demand for explainable recommendation engines and audit-ready ranking systems.
- Social commerce integration:Live-streaming checkout and influencer-curated storefronts are converging entertainment and transaction in East Asian markets.
Industry Challenges
- Warehouse automation talent scarcity:Robotics integration and predictive inventory positioning require scarce mechatronics and machine-learning operations specialists.
- Legacy ERP integration friction:Mid-market retailers face multi-year timelines to connect cloud-native storefronts with on-premise inventory and finance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail E-Commerce Market |
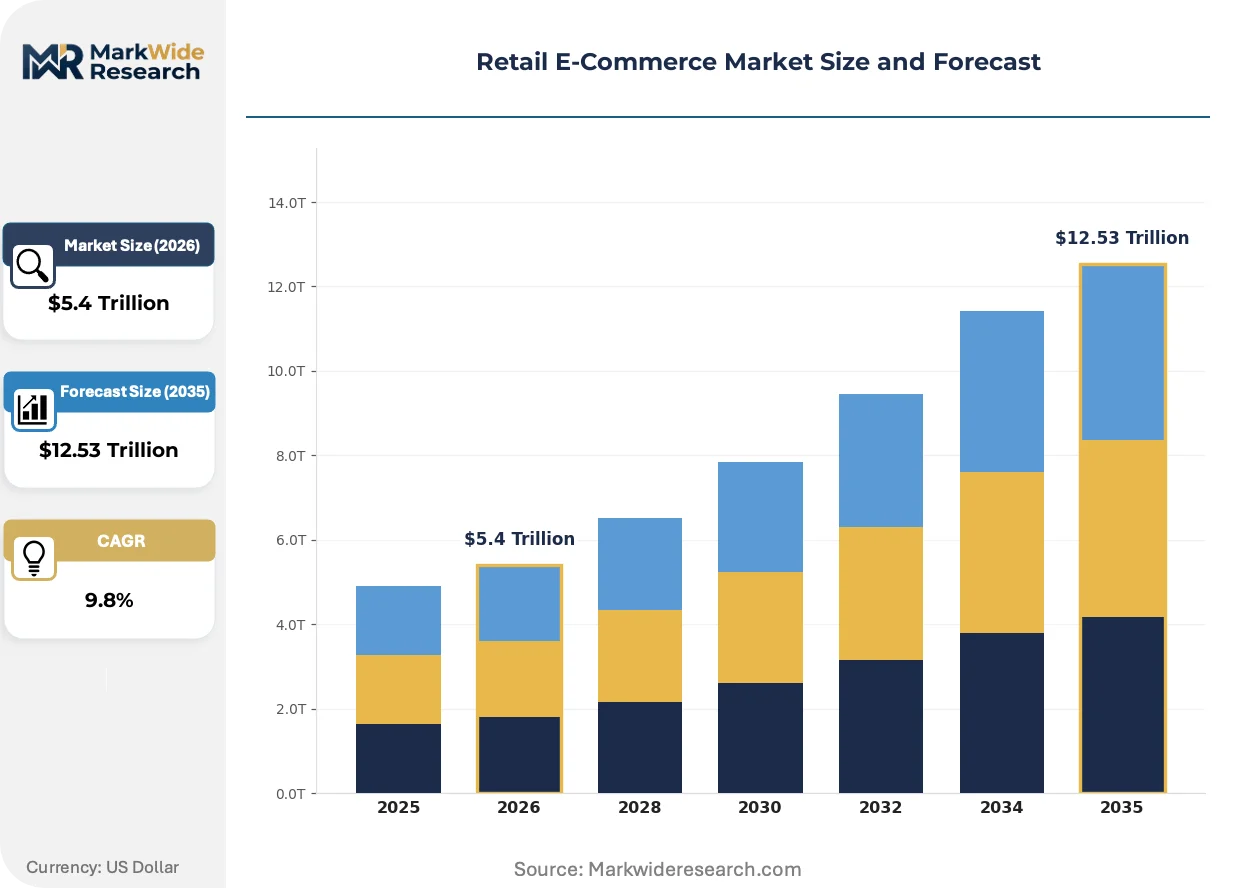
| Market Size in 2026 | $5.4 Trillion |
| Market Size in 2035 | $12.53 Trillion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Beauty Products, Home Goods Distribution Channel: Online Marketplaces, Brand Websites, Social Media, Mobile Apps Customer Segment: Millennials, Gen Z, Working Professionals, Parents Sales Model: B2C, C2C, Subscription, Flash Sales |
| Companies Covered | Amazon, Alibaba Group Holding Limited, Walmart, eBay, Shopify, Apple, JD.com, Target, The Home Depot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail E-Commerce Market Strategic Shifts & Innovations
Three interconnected shifts are restructuring competitive advantage: fulfillment automation is compressing delivery windows, regulatory frameworks are mandating algorithmic transparency, and procurement patterns are favoring consolidated platform relationships over fragmented vendor portfolios.
Autonomous mobile robots and automated storage and retrieval systems are automating warehouse picking density and throughput. Third-party logistics providers and captive retailer networks are deploying these systems at scale in Chinese and North American distribution hubs. This automation is automating labor cost structures while enabling same-day service level guarantees that lock in consumer preference.
The EU Digital Services Act imposes mandatory risk assessments and external audit requirements for algorithmic product ranking and recommendation systems. Marketplace operators must now document how automated systems amplify or suppress specific seller visibility. Fashion and electronics verticals face the steepest compliance burden due to high seller fragmentation and frequent algorithmic curation disputes.
Enterprise procurement departments are consolidating vendor relationships around integrated platform ecosystems that bundle purchasing, expense management, and analytics. This concentration displaces fragmented supplier portfolios and standalone procurement software. The shift is most visible among professional services firms and healthcare systems in Germany and the United States, where procurement centralization mandates are accelerating platform selection cycles.
Retail E-Commerce Market Segmentation
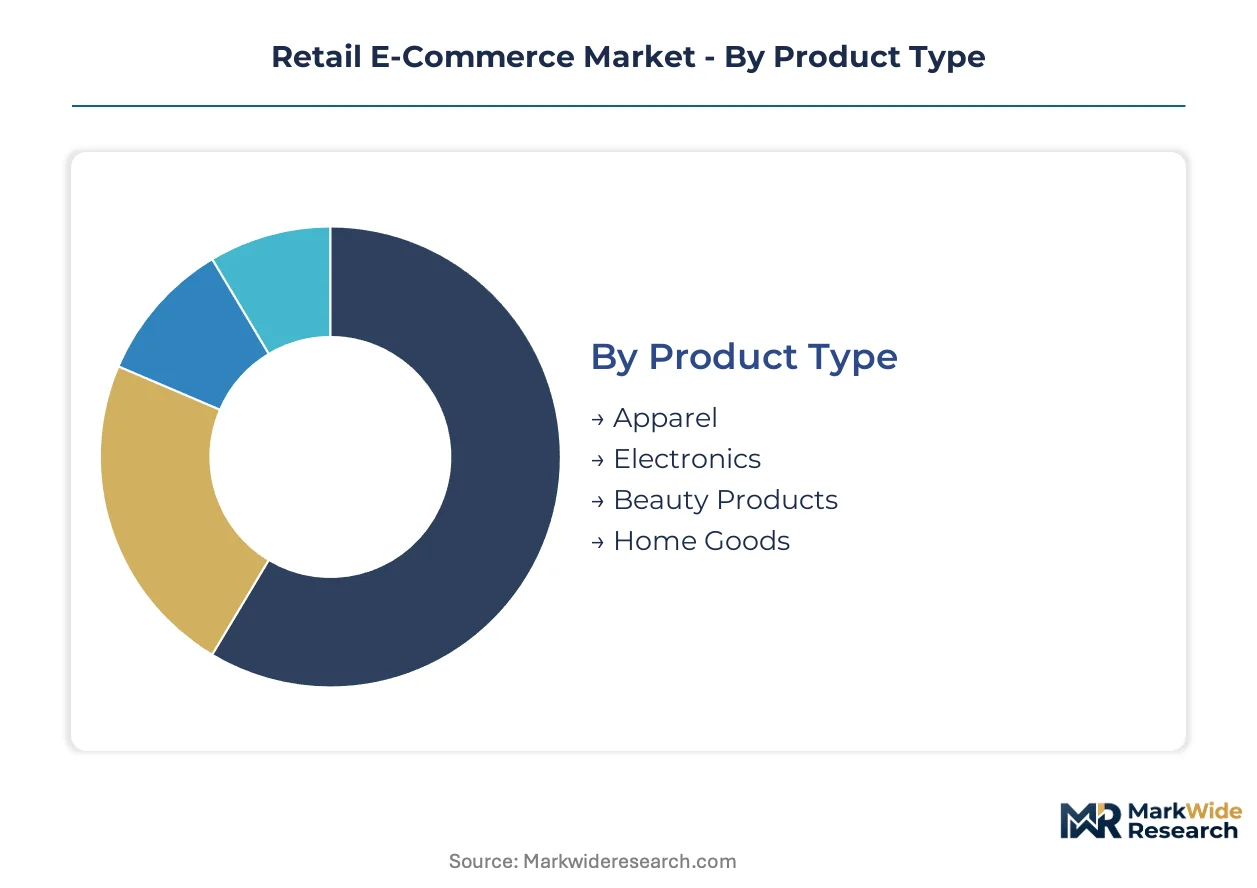
Retail e-commerce segmentation reveals how purchase behavior fragments across product categories, access points, and demographic cohorts. Platform operators calibrate inventory depth, payment options, and fulfillment speed to match the distinct margin profiles and loyalty patterns of each slice.
Product Type:
Material composition and return economics differentiate margin structures across physical goods sold online.
- Apparel:Fabric-based SKUs with size-variant complexity drive 25%+ return rates, consuming reverse logistics capacity. Demand concentrates among working professionals in tier-one Chinese cities and Southeast Asian urban clusters where same-day fitting room alternatives remain scarce. Accessory attach rates and seasonal refresh cycles deepen lifetime value.
- Electronics:Semiconductor-intensive devices with high unit values and warranty dependencies require specialized last-mile handling. Demand clusters in North American metropolitan corridors and German industrial regions where consumer financing penetration supports premium pricing. Rapid obsolescence compresses inventory turns.
- Beauty Products:Regulated cosmetic formulations with expiration sensitivity and sampling dependencies. Fragrance and skincare subcategories dominate basket composition in France and South Korea.
- Home Goods:Bulky furniture and décor with freight cost intensity and assembly friction. Demand localizes around urban residential development zones in Indonesia and Vietnam.
Apparel leads on scale; Electronics leads on momentum.
Distribution Channel:
Interface architecture determines checkout completion rates and data capture depth.
- Online Marketplaces:Aggregator platforms hosting third-party sellers with algorithmic search ranking and unified payment settlement. Network effects concentrate seller liquidity in Amazon's North American captive warehouse corridors and Alibaba's East Asian manufacturing cluster linkages. Commission structures erode seller margins while platform advertising displaces organic discovery.
- Mobile Apps:Native iOS and Android storefronts with biometric checkout and push-notification re-engagement. In-app cart recovery automation reduces abandonment versus browser workflows. Penetration climbs fastest among Gen Z cohorts in Indonesia and Vietnam.
- Brand Websites:First-party domains with direct consumer relationship ownership and margin retention. Loyalty program integration and exclusive drops sustain traffic.
- Social Media:Live-streaming commerce and influencer-curated storefronts converging entertainment with transaction. East Asian markets exhibit the deepest creator economy infrastructure.
Online Marketplaces dominate transaction volume; Mobile Apps expand most quickly.
Customer Segment:
Life stage and income stability shape purchase frequency and category breadth.
- Gen Z:Digital-native cohort with platform-hopping behavior and social proof dependency. Demand concentrates in beauty and apparel verticals with unboxing content virality and resale platform integration.
- Working Professionals:Time-constrained segment with premium convenience willingness and subscription affinity. Fresh grocery and electronics categories capture disproportionate wallet share in Chinese tier-one cities.
- Millennials:Household formation stage with furniture and children's goods purchase acceleration. Platform consolidation around integrated ecosystems reduces vendor fragmentation tolerance.
- Parents:Planned purchase behavior with bulk buying patterns and safety certification scrutiny. Recurring replenishment needs sustain subscription model adoption.
Working Professionals lead on scale; Gen Z leads on momentum.
Sales Model:
Commercial structure determines inventory risk placement and cash flow timing.
- B2C:First-party retail with captive inventory ownership and brand-controlled customer experience. Fulfillment automation investments compress delivery windows in JD.com's Chinese cold-chain network and Amazon's North American sortation hubs.
- Subscription:Recurring revenue contracts with predictive demand smoothing and reduced customer acquisition cost amortization. Beauty replenishment and pet supplies verticals exhibit the highest retention rates.
- C2C:Peer-to-peer marketplace facilitation with platform-mediated trust mechanisms and payment escrow. Secondhand apparel and electronics liquidity concentrates in specialized resale platforms.
- Flash Sales:Time-limited inventory liquidation with scarcity-driven conversion optimization and margin compression. Excess apparel and seasonal goods dominate event calendars.
B2C leads on scale; Subscription leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping e-commerce investment flows as platforms relocate data infrastructure and fulfillment assets to jurisdictions with lighter compliance burdens. The EU Digital Services Act and GDPR impose algorithmic accountability costs that some operators offset through Southeast Asian market expansion. This divergence creates distinct competitive zones defined by enforcement intensity rather than consumer demand alone.
United States
Working professionals drive fresh grocery e-commerce adoption in dense metropolitan corridors. The FTC enforces Section 5 authority against subscription billing dark patterns and deceptive checkout interfaces. Amazon's captive warehouse network in California and Texas sustains same-day delivery speed advantages across North American logistics corridors.
China
JD.com dominates fresh grocery e-commerce through proprietary cold-chain assets in Beijing and Shanghai. SAMR enforces anti-monopoly provisions against dominant platforms while promoting domestic cloud infrastructure standards. Automated sortation systems in Shenzhen and Hangzhou distribution hubs compress delivery windows for urban consumers.
Germany
Enterprise procurement departments consolidate vendor relationships around integrated platform ecosystems in industrial regions. The CSRD and GDPR impose data portability obligations that reduce consumer switching costs between marketplaces. Berlin and Munich anchor demand for algorithmic transparency tooling among fashion and electronics verticals.
Indonesia
Mobile-first checkout optimization accelerates among Gen Z cohorts in Jakarta and secondary cities. The national data protection authority imposes localization requirements on consumer transaction records. Working professionals in Surabaya and Bandung exhibit underpenetrated grocery e-commerce adoption relative to regional peers.
Vietnam
Social commerce integration converges live-streaming checkout with influencer-curated storefronts in Ho Chi Minh City. The Ministry of Industry and Trade tightens e-commerce licensing for cross-border marketplace operators. Da Nang and Hanoi cluster last-mile logistics investment targeting middle-class household formation demand.
Retail E-Commerce Market Key Industry Players
North American platforms anchor one tier; East Asian specialists hold fulfillment automation advantages through proprietary infrastructure. The market structure concentrates around vertically integrated operators with captive warehouse networks and fragmented long-tail sellers dependent on third-party logistics. Three archetypes dominate: ecosystem aggregators bundling marketplace, cloud, and payment services; vertical specialists owning cold-chain or fashion logistics; and software-as-a-service enablers powering independent merchant storefronts. Competitive moves center on geographic expansion into Southeast Asian corridors and strategic partnerships for cross-border payment settlement.
Among ecosystem aggregators, Amazon and Alibaba Group Holding Limited exemplify divergent geographic anchoring strategies. Amazon represents North American captive logistics integration, while Alibaba occupies a position bridging East Asian manufacturing clusters with European consumer markets. JD.com anchors the vertical specialist tier through cold-chain ownership in Chinese tier-one cities. These three operators collectively illustrate how infrastructure control determines service level guarantees and customer retention economics across regional markets.
| Leading Market Players |
|---|
| Amazon |
| Alibaba Group Holding Limited |
| Walmart |
| eBay |
| Shopify |
| Apple |
| JD.com |
| Target |
| The Home Depot |
| Others |
Cost & Logistics Intelligence
Captive warehouse networks anchor both supply position and pricing power in retail e-commerce, as operators with in-house fulfillment infrastructure command delivery speed premiums that algorithmic marketplaces cannot match. The EU Digital Services Act compliance costs and Southeast Asian logistics investments create divergent cost structures that platforms arbitrage through geographic asset relocation.
Pricing Analysis
Retailer markup layers stratify across premium, standard, and economy tiers based on fulfillment speed guarantees and brand certification levels. Price differentiation stems from same-day delivery premiums and GDPR-compliant data handling overhead. Pricing pressure intensifies in express delivery segments due to courier wage inflation in Chinese tier-one cities and North American metropolitan corridors. Working professionals exhibit lowest price sensitivity for fresh grocery convenience, while Gen Z cohorts drive price elasticity in apparel and beauty verticals.
Supply Chain Analysis
Dual-sourcing requirements from enterprise procurement departments mandate multi-supplier qualification for cloud infrastructure and last-mile logistics partners. Geographic supply concentrates in China, the United States, and Germany for automated sortation systems and warehouse robotics. Raw material dependencies include cold-chain refrigeration units, packaging substrates, and semiconductor components for IoT tracking devices. Single-source vulnerability in Chinese cold-chain equipment manufacturing elevates supply risk. Distribution runs through captive fulfillment networks, third-party logistics partnerships, and platform-aggregated seller marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail e-commerce operates as a geographic-arbitrage play where operators relocate data infrastructure to Southeast Asian jurisdictions with lighter compliance burdens than the EU Digital Services Act enforcement zone.
For Market Incumbents: Anchor defensive positioning through proprietary cold-chain capacity additions in Jakarta and Ho Chi Minh City, countering JD.com's East Asian fulfillment automation lead. Reinforce algorithmic transparency tooling investments to preempt EU AI Act audit requirements. Consolidate seller liquidity through unified payment settlement and advertising platform integration, displacing fragmented third-party logistics dependencies. For New Entrants and Emerging Players: Capture underpenetrated grocery e-commerce adoption among working professionals in Indonesian secondary cities like Surabaya and Bandung, where mobile-first checkout infrastructure remains nascent. Penetrate through social commerce integration converging live-streaming checkout with influencer-curated storefronts, replicating East Asian creator economy models. Partner with local logistics providers for last-mile coverage rather than building captive networks. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-market retailers face multi-year ERP integration timelines connecting cloud-native storefronts with on-premise inventory systems. Long-term viability favors vertically integrated operators with captive warehouse networks over SaaS-enabled merchant aggregators. Target acquisition archetype: regional logistics specialists with automated sortation assets in Southeast Asian growth corridors. Watch for inflection signals in EU Digital Services Act enforcement intensity against algorithmic ranking opacity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Network Expansion | Proprietary refrigerated fulfillment assets in Jakarta and Ho Chi Minh City lock in fresh grocery market share. |
| Algorithmic Transparency Tooling | Explainable recommendation engines satisfy EU Digital Services Act audit requirements for fashion and electronics verticals. |
| Social Commerce Integration | Live-streaming checkout infrastructure captures Gen Z purchasing behavior in Indonesian and Vietnamese urban clusters. |
| Mobile-First Checkout Optimization | Biometric in-app payment settlement reduces cart abandonment versus browser-based workflows in Southeast Asian markets. |
| Enterprise Procurement Consolidation | Integrated platform ecosystems displace fragmented vendor portfolios among German industrial and US healthcare buyers. |
Research Approach
Coverage spans North America, East Asia, and Southeast Asia, with primary inputs from each regional cluster combining executive interviews with e-commerce platform operators, logistics procurement directors, and regulatory compliance officers. Secondary validation draws from SEC filings of publicly traded marketplace operators, EU Digital Services Act implementation guidance, and customs data on cross-border e-commerce flows. Bottom-up segment sizing triangulates with top-down macroeconomic consumption indicators.
Granularity-level modeling disaggregates revenue projections by product category, distribution channel, customer segment, and sales model across the analysis window. Treatment of CAGRs reflects segment-specific growth trajectories derived from historical penetration rates and regulatory enforcement timelines. Forecast inputs include mobile app adoption curves in Indonesian and Vietnamese urban centers, plus cold-chain infrastructure deployment schedules in Chinese tier-one cities.
EU regulatory enforcement intensity, Southeast Asian logistics labor cost trajectories, and cross-border payment settlement friction are the dominant revision risks to the outlook. Deviation in EU Digital Services Act audit implementation timelines would shift competitive positioning between algorithmic transparency-compliant operators and those relocating infrastructure to lighter-regulation jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Global Omnichannel Retail Commerce Platform Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
3D Interactive Ticketing Solutions Market
E-Commerce Solutions
M-Commerce Market
E-Commerce Solutions
Latvia E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Global Ecommerce Platform Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market