
 Ambient Commerce Market | 2026-2036
Ambient Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Ambient Commerce Market Intelligence
Enterprise retailers is bifurcating from boutique hospitality operators as the primary deployment capital for ambient commerce infrastructure. Amazon leverages its computer vision stack and vertical warehouse integration to dominate prototype-to-scale transitions. Walmart anchors North American grocery and big-box rollout velocity through its existing store network density. Google competes on edge AI inference efficiency, positioning its Tensor processing units for low-latency shelf monitoring.
Ambient commerce denotes retail and service environments where transactions execute without explicit checkout actions, typically orchestrated through fused sensor arrays, biometric identification, and real-time inventory telemetry. Systems integrate weight-sensitive shelving, ceiling-mounted cameras, and RFID mesh networks to construct persistent digital twins of physical stock, enabling automatic billing upon customer exit. Cloud-based deployment leads current infrastructure spend because centralized model training and cross-store analytics offset latency costs for non-grocery formats. AI-powered solutions represent the fastest-expanding technology segment as transformer-based visual recognition displaces rule-based detection in shrinkage-sensitive categories. Hardware devices still occupy the dominant share of offering value, though integration services capture expanding margin pools as legacy POS retrofit complexity rises.
FCC equipment authorization governs wireless sensor density in US retail environments, while the EU AI Act imposes conformity assessment obligations on biometric inference systems deployed in European stores. GDPR and state-level biometric privacy statutes in Illinois and Texas constrain facial recognition deployment, forcing vendors toward palm-vein and behavioral gait alternatives that reduce regulatory exposure. Stakeholders must monitor evolving algorithmic accountability frameworks and decide whether to standardize on privacy-preserving edge architectures or maintain cloud-dependent stacks with jurisdiction-specific data residency.
Market Dynamics
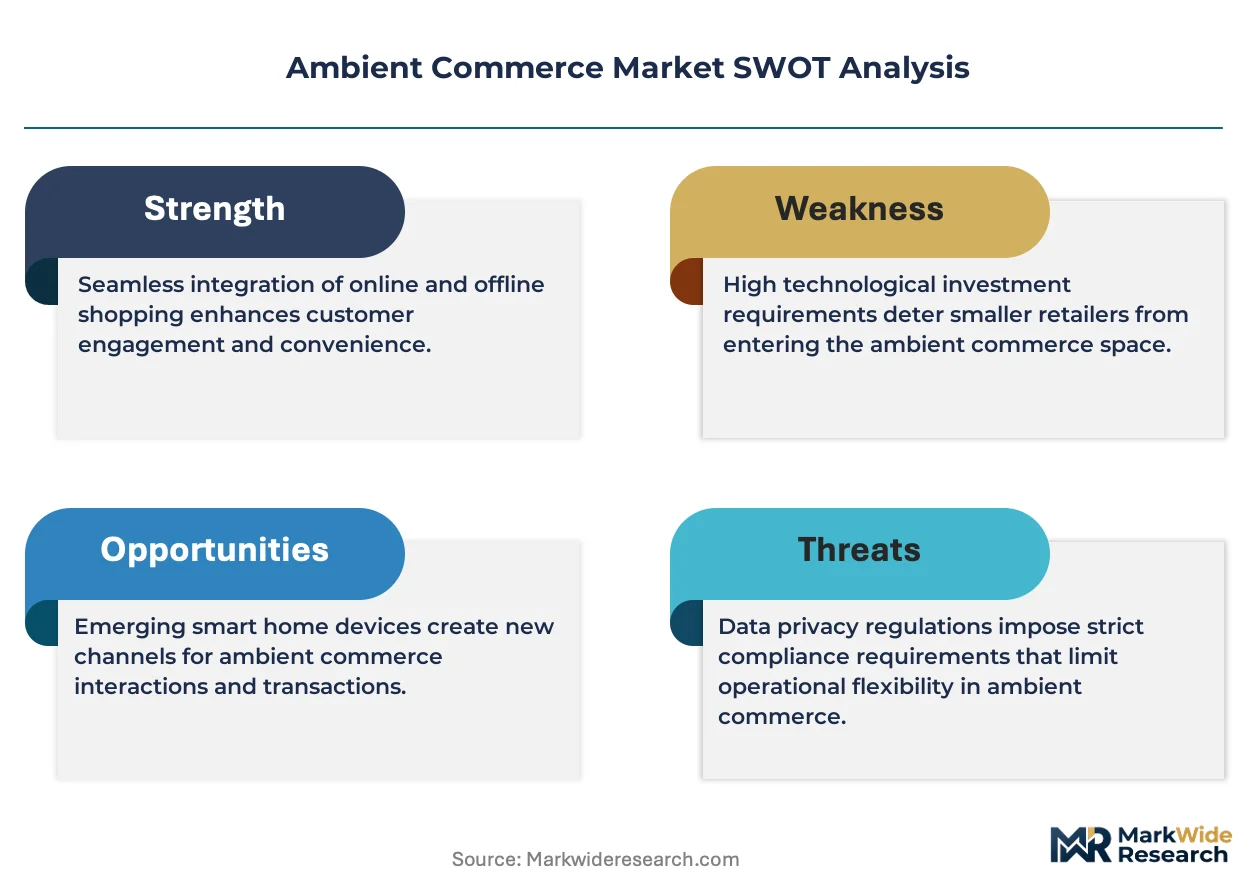
The convergence of edge AI inference and biometric authentication protocols is compressing deployment timelines for frictionless retail infrastructure, while GDPR and the EU AI Act impose divergent compliance architectures across Atlantic markets.
Growth Catalysts
- Computer vision maturation:Transformer-based shelf recognition systems now operate at sub-100ms latency, enabling real-time inventory digital twins in high-SKU grocery environments.
- FCC equipment authorization:Streamlined certification for dense wireless sensor arrays accelerates US pilot-to-production scaling for ceiling-mounted camera mesh networks.
- Convenience retail consolidation:Chain operators with 500-plus store footprints amortize fixed integration costs across locations, converting capital expenditure into unit economics advantages.
Market Restraints
- Silicon supply concentration:Edge AI chip fabrication depends on Taiwan-based foundry capacity, exposing deployment schedules to geopolitical disruption risks.
- Biometric data friction:Illinois BIPA and Texas biometric privacy statutes impose per-violation liability structures that chill facial recognition rollout in 23 US states.
- Legacy POS retrofit complexity:ERP integration with 15-year-old inventory management systems consumes 40% of implementation timelines in established retail footprints.
Strategic Opportunities
- Palm-vein authentication:Vascular pattern recognition circumvents facial recognition bans while maintaining biometric convenience, opening deployment in BIPA-regulated jurisdictions.
- Hospitality vertical expansion:Stadium concessions and airport terminals represent greenfield environments lacking legacy POS entanglement, reducing integration overhead.
- EU AI Act conformity assessment:Early certification as a "high-risk biometric system" provider creates regulatory moats against later entrants in European markets.
Industry Challenges
- Edge ML operations talent scarcity:Deployment of tensor-optimized inference pipelines requires specialists fluent in both retail operations and embedded systems engineering.
- Shrinkage algorithm calibration:Computer vision false-positive rates for theft detection remain above acceptable thresholds in apparel categories with high SKU velocity.
- Cross-border data residency:Cloud-dependent analytics architectures face fragmentation as France, Germany, and Spain impose divergent data localization mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambient Commerce Market |
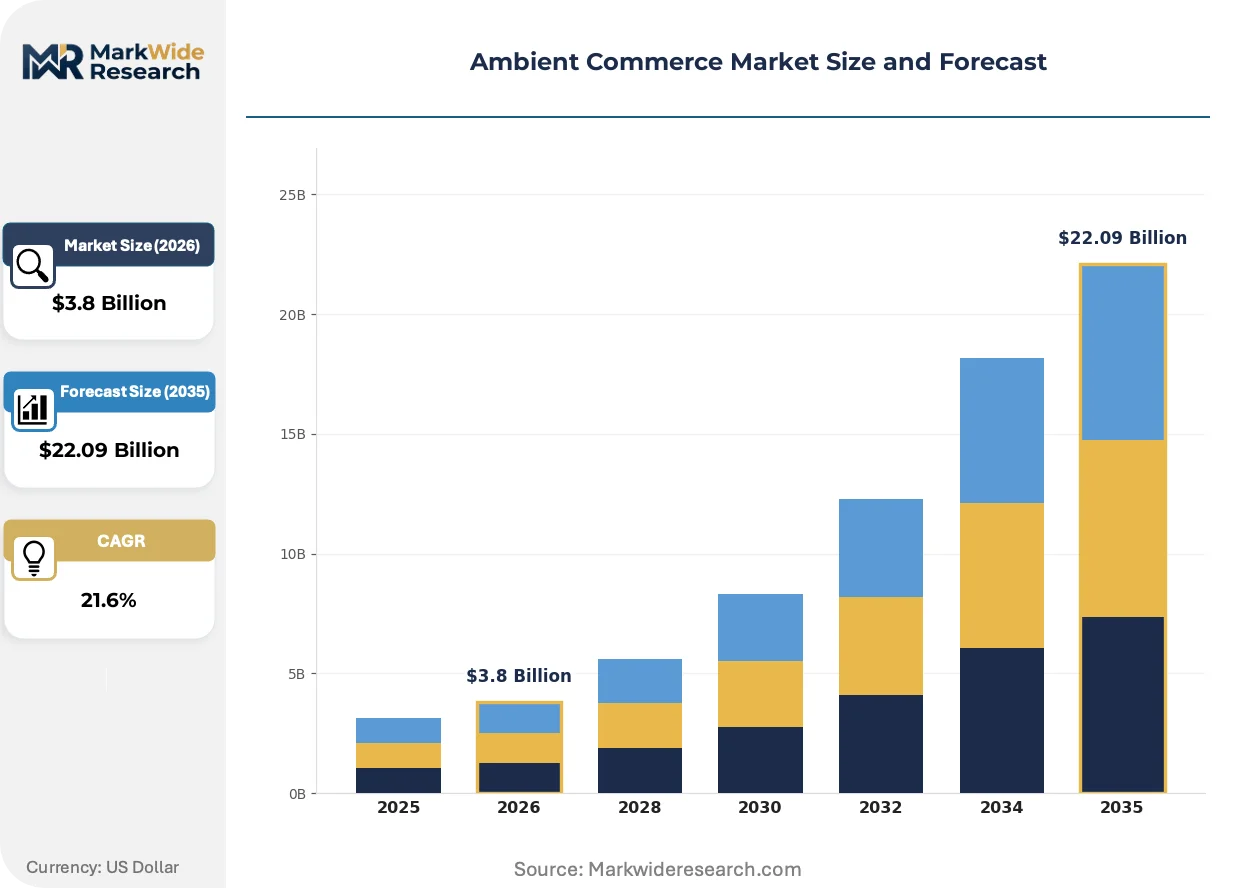
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $22.09 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Devices, AI-Powered Solutions, Smart Sensors, Voice Assistants Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Platforms End User: Retailers, E-Commerce Platforms, Hospitality Providers, Digital Marketers Offering: Software Solutions, Hardware Devices, Integration Services, Analytics Tools |
| Companies Covered | Amazon, Apple Inc., Alibaba Group, Google, Microsoft, Walmart, Samsung, IBM, Shopify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambient Commerce Market Strategic Shifts & Innovations
Transformer architectures are migrating from cloud training to edge inference, compressing the latency-response window for real-time retail analytics while biometric modalities fragment across regulatory jurisdictions.
Edge-deployed vision transformers are supplanting rule-based object detection in shelf-monitoring applications. Grocery chains with fresh-produce departments adopt these models to track bruising and spoilage in real time. The shift collapses the accuracy gap between centralized cloud inference and local processing, enabling autonomous checkout in bandwidth-constrained locations.
The EU AI Act's risk-classification framework imposes third-party conformity assessment on biometric inference systems deployed in European retail environments. Vendors must document algorithmic accountability measures and maintain technical files for notified body review. France and Germany are witnessing early certification bottlenecks as notified body capacity fails to match application volume.
Buyers now demand outcome-based shrinkage reduction guarantees rather than capital equipment purchases. Retailers with high employee turnover prefer service contracts bundling hardware, software, and loss-prevention performance metrics. This preference shift concentrates most visibly in US big-box grocery, where CFOs prioritize opex predictability over balance-sheet asset ownership.
Ambient Commerce Market Segmentation
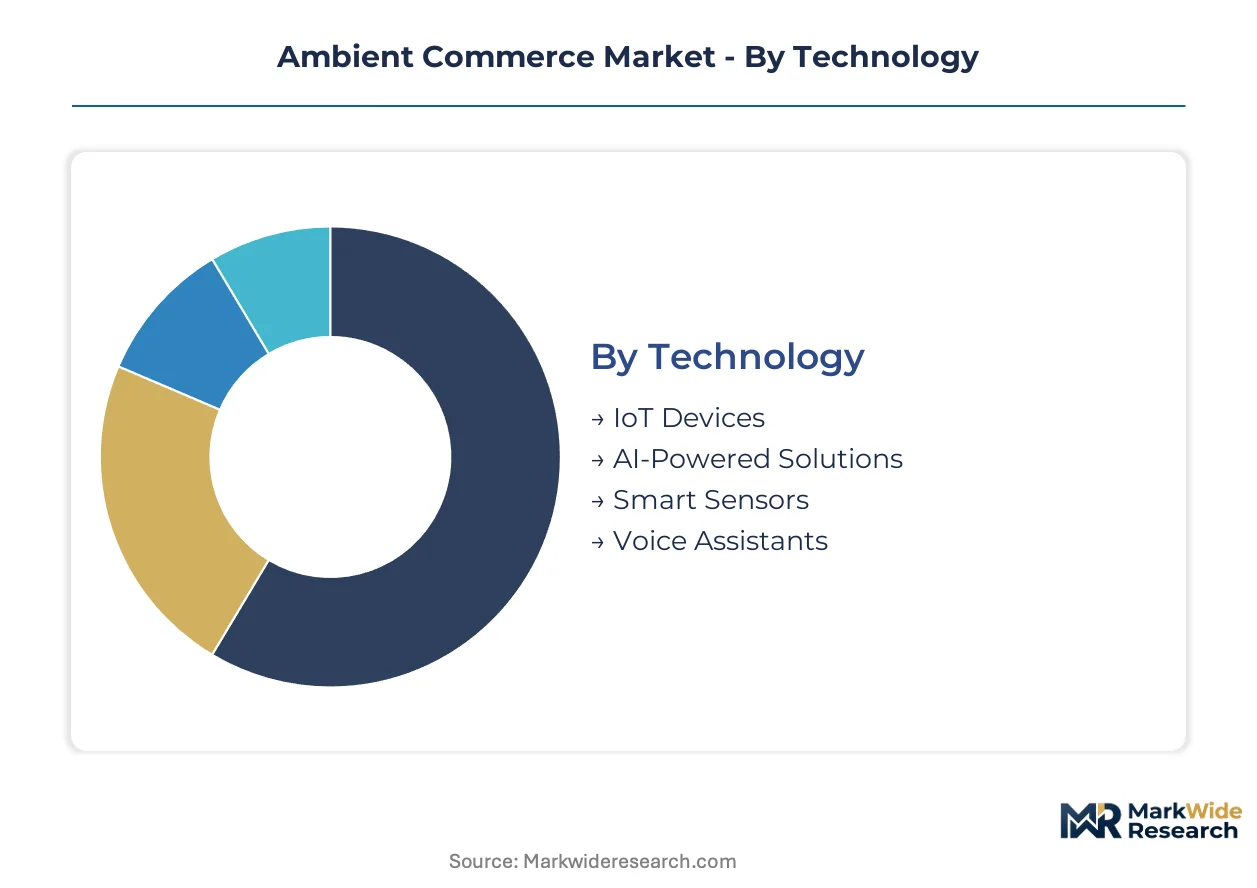
Segmentation in ambient commerce reveals where infrastructure investment concentrates and which technology stacks capture margin expansion. Vendors align R&D roadmaps and partnership strategies around deployment mode preferences and end-user operational constraints.
Technology:
Margin pools concentrate in inference optimization layers that reduce cloud dependency and latency penalties for real-time checkout.
- IoT Devices:Edge-connected weight sensors, camera arrays, and RFID mesh nodes form the physical sensing substrate. Grocery chains in the United States prioritize these deployments for shrinkage reduction in high-SKU produce departments, though FCC equipment authorization timelines create deployment bottlenecks for dense sensor configurations.
- AI-Powered Solutions:Transformer-based computer vision models now execute shelf recognition at sub-100ms latency on edge silicon. This segment attracts the steepest R&D allocation as retailers demand autonomous checkout without cloud round-trip delays that interrupt customer flow.
- Smart Sensors:Multi-modal fusion devices combine pressure, temperature, and motion detection for inventory digital twins.
- Voice Assistants:Natural language interfaces enable hands-free reordering and product location services in warehouse-scale retail formats.
AI-Powered Solutions holds installed capacity. IoT Devices is rotating up the share rankings.
Deployment:
Cost tier stratification separates capital-intensive on-premises builds from recurring-revenue cloud subscriptions preferred by mid-market retailers.
- Cloud-Based:Centralized model training and cross-store analytics dominate current infrastructure spend. Non-grocery formats with lower transaction velocity accept latency tradeoffs for unified data lakes and reduced IT staffing requirements.
- On-Premises:Local inference servers and dedicated edge clusters serve retailers with strict data residency mandates or bandwidth-constrained locations. European deployments under GDPR fragmentation increasingly require this architecture despite higher upfront capital.
- Hybrid Solutions:Tiered processing splits training workloads to cloud while inference runs locally.
- Mobile Platforms:Smartphone-dependent checkout experiences bypass fixed infrastructure entirely.
Cloud-Based holds installed capacity. Hybrid Solutions is rotating up the share rankings.
End User:
Application intensity varies sharply between legacy retail footprints with ERP entanglement and greenfield environments lacking technical debt.
- Retailers:Enterprise grocery and big-box operators drive volume deployment, leveraging existing store networks to amortize integration costs across hundreds of locations. These buyers now demand outcome-based shrinkage guarantees rather than capital equipment purchases.
- Hospitality Providers:Stadium concessions, airport terminals, and hotel retail represent deployment frontiers without legacy POS retrofit complexity. The absence of fifteen-year-old inventory systems reduces implementation timelines by approximately forty percent relative to established retail.
- E-Commerce Platforms:Pure-play digital merchants extend into physical pickup points and automated lockers.
- Digital Marketers:Ad-tech vendors leverage ambient transaction data for attribution modeling.
Retailers holds installed capacity. Hospitality Providers is rotating up the share rankings.
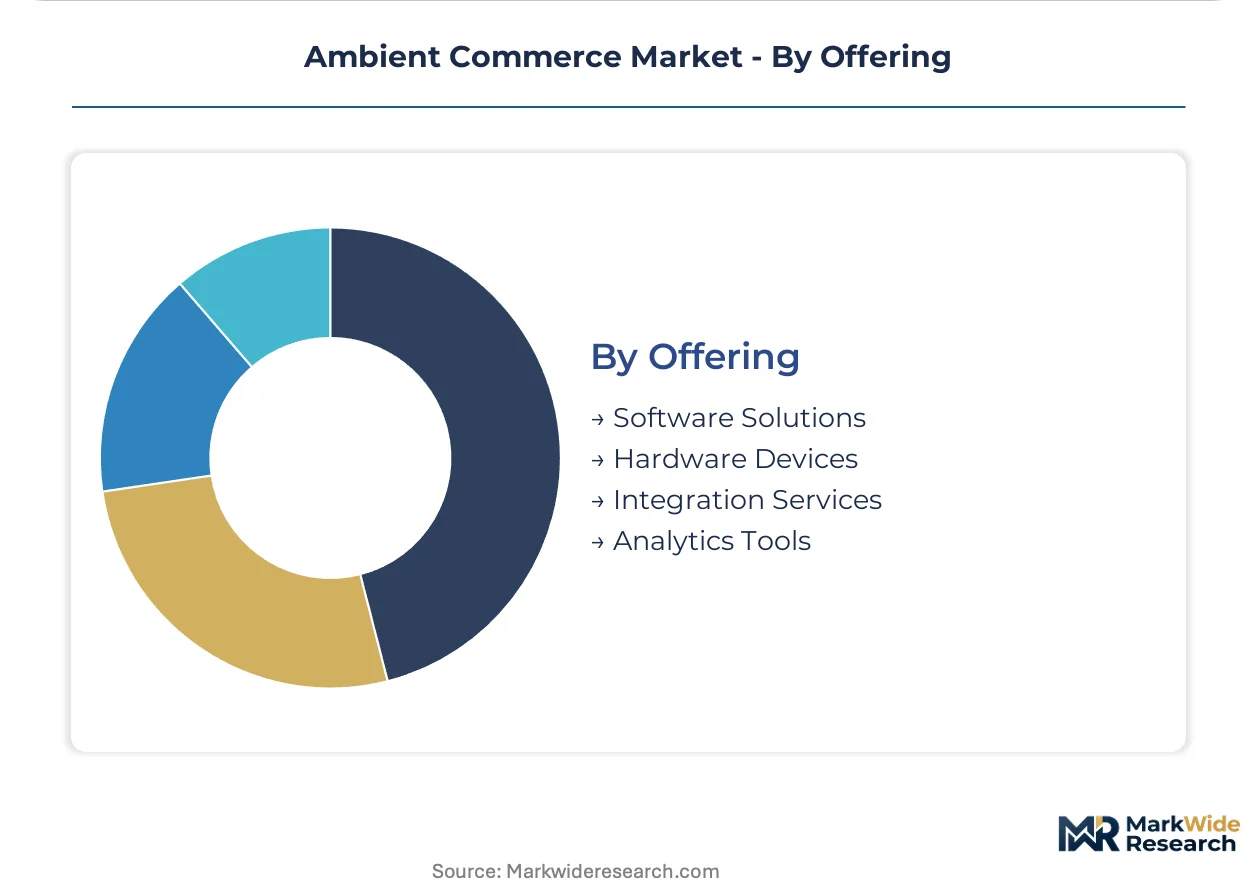
Offering:
Customer type preferences are forcing margin migration from hardware sales toward bundled service contracts with performance guarantees.
- Hardware Devices:Ceiling-mounted cameras, edge AI servers, and sensor arrays still occupy the dominant share of offering value. Fabrication concentration in Taiwan-based foundries exposes deployment schedules to geopolitical supply disruption.
- Integration Services:ERP connectivity and legacy POS retrofit expertise capture expanding margin pools as implementation complexity rises. Vendors with fifteen-year-old retail system fluency command pricing premiums unavailable to pure technology suppliers.
- Software Solutions:Computer vision platforms and inventory management applications.
- Analytics Tools:Shrinkage prediction and customer flow optimization dashboards.
Hardware Devices holds installed capacity. Integration Services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise retailers concentrate deployment capital in the United States, while European markets reshape vendor certification pathways under emerging biometric regulations. Asian technology conglomerates anchor supply-side innovation for edge AI silicon and computer vision platforms.
United States
Amazon and Walmart anchor grocery and big-box rollout velocity through existing store network density. FCC equipment authorization governs wireless sensor density for ceiling-mounted camera mesh deployments. Seattle and Bentonville operational templates now propagate to Chicago, Dallas, and Atlanta metro pilots.
China
Alibaba Group drives cashierless format experimentation across Hema supermarket locations in Shanghai and Beijing. MIIT standards for edge computing equipment shape local hardware certification timelines. Shenzhen hardware clusters supply camera arrays and RFID mesh nodes to domestic and Southeast Asian deployments.
Germany
Retailers pilot frictionless checkout under GDPR and EU AI Act conformity assessment obligations for biometric inference. KBA and federal data protection authorities coordinate on palm-vein authentication approval pathways. Berlin and Munich technology clusters host edge AI inference optimization startups serving European grocery chains.
United Kingdom
Tesco and Sainsbury's trial computer vision systems for shrinkage reduction in London and Manchester locations. UK Information Commissioner's Office guidance constrains facial recognition deployment, accelerating behavioral gait and palm-vein alternatives. Cambridge computer vision research clusters feed talent pipelines for edge AI engineering.
Japan
Convenience retail chains pilot autonomous checkout in Tokyo and Osaka metro corridors with METI support for productivity-enhancing retail automation. JIS standards for sensor interoperability reduce integration overhead for domestic equipment vendors. Nagoya industrial clusters manufacture precision weight-sensitive shelving for regional export.
Ambient Commerce Market Key Industry Players
Player mix skews toward diversified technology conglomerates with captive cloud infrastructure and vertical retail operations. Market structure concentrates around three strategic archetypes: hyperscale cloud providers monetizing edge AI inference stacks, retail operators amortizing infrastructure across proprietary store networks, and enterprise software vendors retrofitting legacy POS environments. Dominant competitive moves include strategic partnerships between silicon foundries and computer vision platforms, plus geographic expansion of certified biometric authentication modalities into BIPA-regulated US states.
Within the diversified technology tier, Amazon exemplifies vertical integration from cloud infrastructure through retail deployment, while Google anchors edge AI inference efficiency positioning. Alibaba Group occupies a comparable position in Asian market development. Walmart represents the retail-operator archetype, leveraging network density for rapid pilot-to-production scaling. These entities illustrate how capital concentration and regulatory early-mover advantages are reshaping competitive positioning across Atlantic and Pacific markets.
| Leading Market Players |
|---|
| Amazon |
| Apple Inc. |
| Alibaba Group |
| Microsoft |
| Walmart |
| Samsung |
| IBM |
| Shopify |
| Others |
Cost & Logistics Intelligence
FCC equipment authorization for dense wireless sensor arrays gates both vendor qualification and price differentiation in US ambient commerce deployments, separating certified integrators from commodity hardware resellers while compressing margins for retrofit-heavy installations.
Pricing Analysis
Cost-plus contracts with Taiwan foundry indexation dominate hardware procurement, embedding silicon price volatility directly into edge AI server costs. Pricing stratifies across EU AI Act-certified, GDPR-compliant, and non-certified system tiers, with certification premiums widening as biometric liability exposure intensifies. Cost compression in cloud-based deployment tiers is intensifying because hyperscalers bundle inference-as-a-service below standalone on-premises economics. Mid-market grocery chains exhibit highest price sensitivity, prioritizing opex-predictable service contracts over capital equipment ownership.
Supply Chain Analysis
Strategic stockpiling of edge AI accelerators is displacing just-in-time procurement as lead time uncertainty from Taiwan-based foundries reshapes inventory policy. Hardware fabrication draws from Taiwan, South Korea, and China, while sensor assembly clusters in Shenzhen and Nagoya. Single-source vulnerability in TSMC advanced node capacity exposes deployment schedules to geopolitical disruption. Distribution runs through systems integrators with fifteen-year retail ERP fluency, capturing margin pools unavailable to pure technology vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of edge ML operations talent fluent in both tensor optimization and retail loss prevention is constraining deployment velocity, creating acquisition premiums for teams with production-grade computer vision pipelines.
For Market Incumbents: Compound certification advantages under EU AI Act conformity assessment to erect regulatory moats against later entrants in European markets. Deepen backward integration into edge silicon design to reduce Taiwan foundry exposure. Prioritize palm-vein authentication R&D to preempt biometric bans spreading beyond Illinois and Texas. For New Entrants and Emerging Players: Lead with hospitality verticals—stadium concessions and airport terminals—where legacy POS absence slashes implementation timelines by forty percent versus established retail. Target greenfield European deployments requiring GDPR-compliant edge architectures that incumbents with cloud-dependent stacks cannot easily replicate. Position on outcome-based shrinkage guarantees rather than capital equipment sales to align with CFO preference shifts in US big-box grocery. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across on-premises edge infrastructure as data residency mandates fragment cloud economics. Favor acquisition targets with notified body relationships and existing EU AI Act technical files, which compress European market entry from years to quarters. Watch for inflection when edge transformer latency consistently breaches fifty milliseconds, collapsing the accuracy gap with cloud inference.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | Early certification under KBA coordination creates regulatory moats in German and French markets. |
| Palm-Vein Authentication Development | Vascular pattern recognition circumvents BIPA liability structures chilling facial recognition rollout. |
| Edge Transformer Optimization | Sub-100ms inference latency enables real-time spoilage detection in high-SKU grocery produce departments. |
| Legacy POS Integration Services | Fifteen-year ERP system fluency commands pricing premiums unavailable to pure technology suppliers. |
| Hospitality Vertical Expansion | Stadium and airport greenfield deployments lack technical debt, reducing implementation overhead substantially. |
Research Approach
Cross-validation between primary interviews with retail technology executives and secondary analysis of FCC equipment authorization filings anchors the qualitative findings. The study combines discussions with edge AI engineering leads, grocery chain CFOs, systems integration specialists, and biometric compliance officers with SEC 10-K disclosures, hyperscaler capex reports, and EU notified body certification databases. Bottom-up store deployment counts and top-down infrastructure spend estimates triangulate market sizing.
Sensitivity analysis across deployment mode preferences, biometric regulatory scenarios, and edge silicon supply conditions shapes the analytical framework. Segmentation dimensions modeled include technology stack, deployment architecture, end-user vertical, and offering type, with regional regulatory clusters treated as distinct demand environments. CAGRs derive from installed base growth rates and average revenue per deployment trends, with shrinkage reduction performance guarantees and outcome-based contract penetration serving as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Taiwan foundry capacity and stable trans-Atlantic data transfer mechanisms would require recalibration. Forecasts reflect assumptions about computer vision accuracy improvement curves and biometric privacy statute diffusion. Revision becomes warranted when edge AI chip lead times exceed eighteen months or EU AI Act enforcement intensity crosses thresholds that fragment vendor certification pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
India Digital Gift Card Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Belgium E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
Estonia E-Commerce Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
Digital Gift Cards (Egift Cards) Market