
 Argentina E-Commerce Market | 2026-2036
Argentina E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina E-Commerce Market Analysis
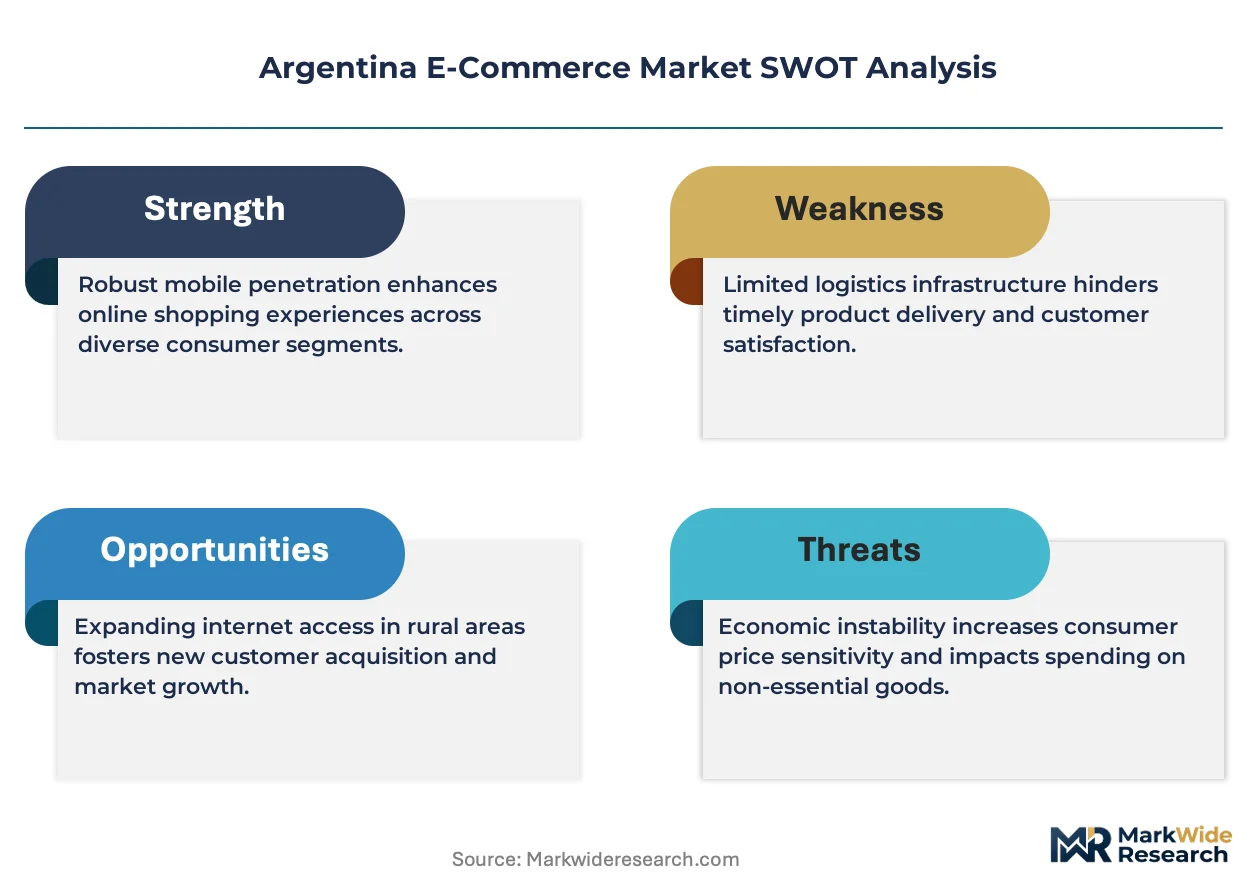
AFIP's electronic invoicing mandate is recalibrating the cost-of-entry calculus for new marketplace entrants. Mercado Libre Argentina S.R.L. leverages its captive logistics network to sustain fulfillment advantages across provincial zones. Frávega S.A.C.I. e I. anchors its position through specialized electronics assortments and in-store pickup integration. Grupo Carrefour Argentina S.A. competes on grocery velocity, deploying dark stores in metropolitan Buenos Aires.
Argentina e-commerce denotes digitally mediated retail transactions executed through web platforms and mobile applications, encompassing product discovery, payment processing, and last-mile fulfillment orchestration. The sector relies on real-time inventory APIs, encrypted payment gateways, and route-optimization algorithms to coordinate demand with distributed warehousing capacity. Electronics and apparel product categories dominate transaction volumes, though home goods segments are capturing margin expansion as furniture retailers deploy augmented-reality visualization tools. Individual consumers represent the core customer type, while same-day delivery models are attracting premium pricing power in dense urban zones where micro-fulfillment nodes proliferate.
AFIP enforces tax transparency protocols that shape seller registration requirements and transaction reporting granularity. The country's central bank, BCRA, regulates foreign-currency settlement flows for cross-border purchases, constraining payment method flexibility for international platforms. Stakeholders must monitor how regulatory tightening around consumer data protection and import duty structures will reshape platform economics and cross-border seller participation thresholds.
Market Dynamics
AFIP's electronic invoicing mandate is compressing seller onboarding timelines while concentrating transaction data visibility under federal tax authority oversight, fundamentally altering marketplace operator compliance architectures.
Growth Catalysts
- Electronic Invoicing Mandate:AFIP's factura electrónica requirements are forcing informal sellers onto formal platforms, expanding the addressable merchant base for established marketplaces.
- Logistics Network Density:Micro-fulfillment nodes in Greater Buenos Aires and Córdoba are enabling same-day delivery promises that capture premium pricing from time-sensitive buyers.
- QR Code Payment Rails:Argentina's interoperable QR payment infrastructure is reducing friction at checkout, accelerating conversion rates for mobile-first transactions.
Market Restraints
- Foreign Currency Settlement Controls:BCRA restrictions on dollar-denominated transactions constrain cross-border purchase flexibility and inflate effective costs for imported goods.
- Last-Mile Cost Volatility:Fuel price fluctuations and informal labor dynamics in provincial zones compress margins for fulfillment operators outside metropolitan corridors.
- Import Duty Structures:Argentina's complex tariff schedules on electronics and apparel create pricing distortions that favor domestic assembly over finished goods imports.
Strategic Opportunities
- Mendoza and Rosario Corridors:Secondary urban centers with rising disposable income remain underpenetrated by specialized category retailers, offering first-mover positioning.
- Augmented Reality Visualization:Furniture and home goods segments are deploying AR tools that reduce return rates and unlock margin expansion in historically problematic categories.
- Dark Store Grocery Velocity:Metropolitan Buenos Aires zoning permits rapid-deployment fulfillment nodes that enable 15-minute delivery promises for fresh categories.
Industry Challenges
- Tax Compliance Talent Scarcity:Marketplace operators face acute shortages of professionals capable of navigating AFIP's evolving electronic reporting protocols and audit procedures.
- Legacy ERP Integration:Established retailers with decades-old inventory management systems encounter friction when connecting real-time APIs to modern marketplace architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina E-Commerce Market |
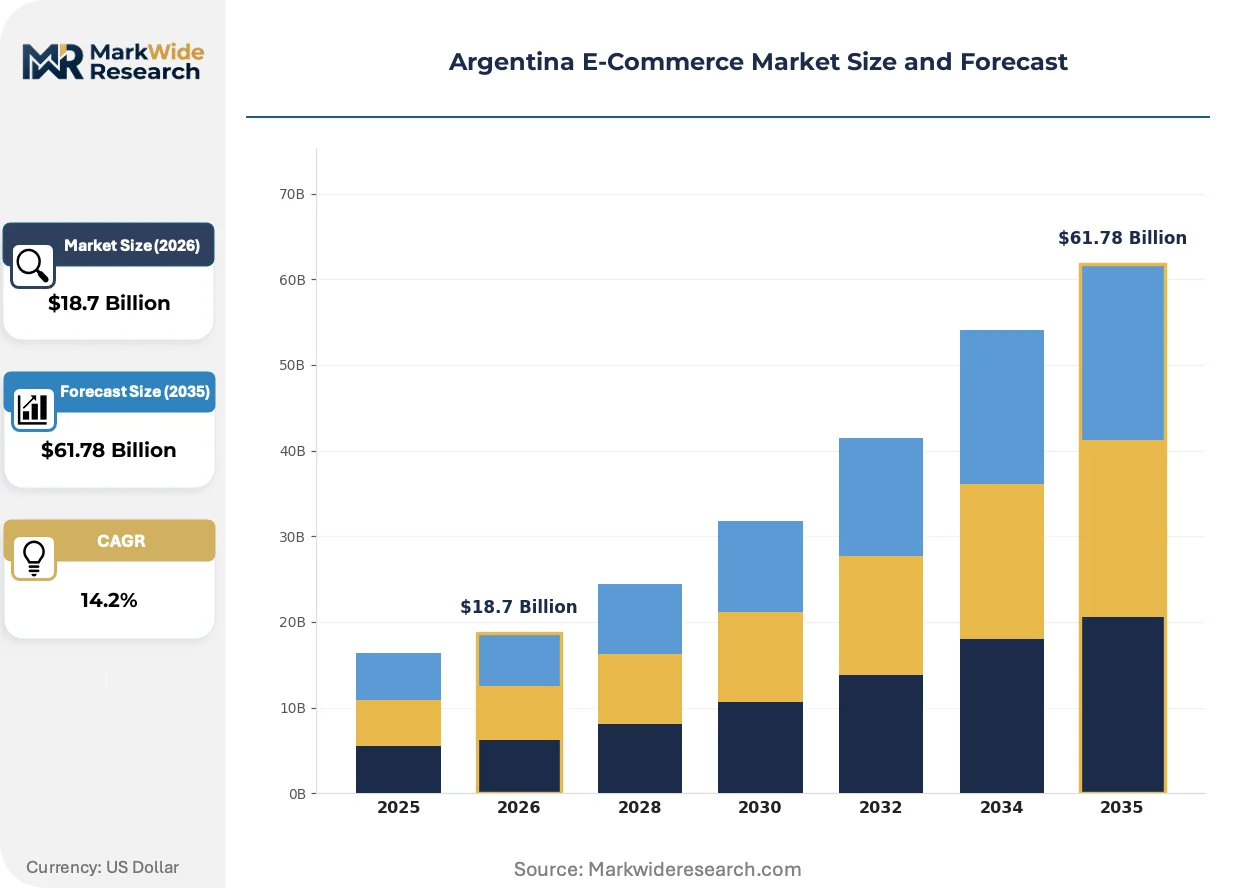
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Apparel, Home Goods, Beauty Products Customer Type: Individual Consumers, Small Businesses, Large Enterprises, Government Entities Delivery Model: Standard Shipping, Express Delivery, Click & Collect, Same-Day Delivery Payment Method: Credit Card, Debit Card, Mobile Payment, Bank Transfer |
| Companies Covered | Mercado Libre Argentina S.R.L., Frávega S.A.C.I. e I., Grupo Carrefour Argentina S.A., Musimundo S.A., Amazon.com Inc., Tiendamia LLC, Easy.com, Garbarino S.A., Cencosud S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina E-Commerce Market Emerging Trajectories
Digital infrastructure investments are compressing fulfillment windows while regulatory data requirements are reshaping seller-platform relationships across Argentina's urban corridors.
Real-time inventory APIs are rewriting coordination between distributed warehousing nodes and front-end discovery layers. Mid-market apparel retailers are adopting these systems fastest, collapsing stockout-induced cart abandonment from days to hours. The structural consequence is a shift from periodic replenishment to continuous availability promises that lock in repeat purchase behavior.
AFIP's escalating granularity requirements for transaction reporting are forcing platform operators to rebuild data architectures around audit-ready telemetry. Industrial consequence includes elevated compliance staffing ratios and automated flagging systems for anomalous seller behavior. Electronics and high-value goods categories face the steepest adaptation curves as invoice-level traceability becomes mandatory.
Subscription-based replenishment models are displacing episodic purchase patterns in household consumables. Direct-to-consumer brands are capturing pantry-share through auto-ship algorithms, bypassing traditional retail intermediaries. This behavioral shift concentrates most visibly in Greater Buenos Aires apartment clusters where delivery density supports economically viable micro-fulfillment economics.
Argentina E-Commerce Market Segmentation
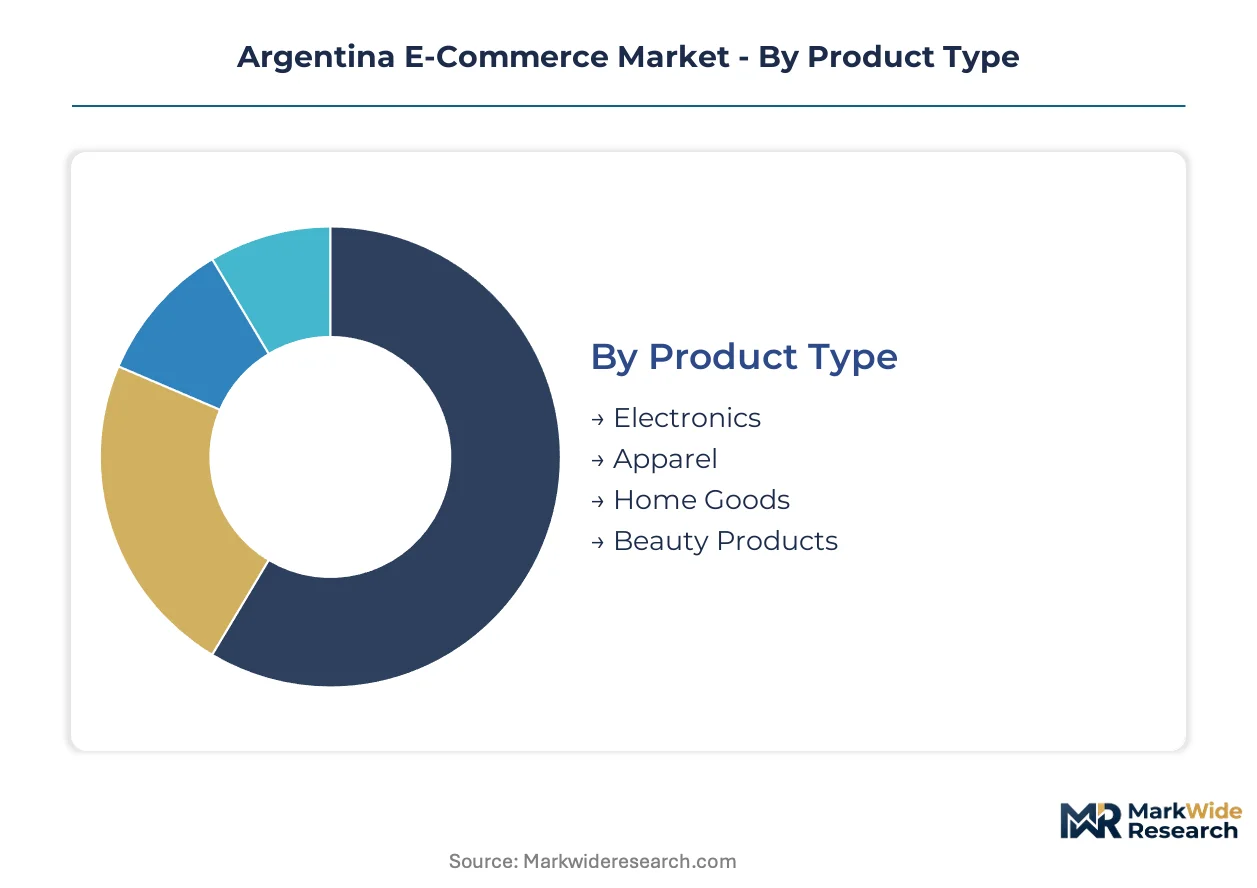
Argentina's e-commerce segmentation reveals how platform operators must align fulfillment infrastructure with divergent product economics and customer procurement behaviors. Category-specific logistics requirements and payment method preferences create distinct operational submarkets across Greater Buenos Aires and provincial corridors.
Product Type:
Electronics dominate transaction value while home goods command expanding margin premiums through visualization technology adoption.
- Electronics:Smartphones, laptops, and consumer appliances require specialized handling protocols and warranty integration. Demand concentrates in Greater Buenos Aires corridor where Mercado Libre's captive logistics network enables same-day fulfillment for high-value SKUs, though BCRA currency controls inflate landed costs for imported inventory.
- Apparel:Fashion and accessories categories drive highest purchase frequency with lowest average order values. Mid-market retailers in Córdoba urban zone are adopting real-time inventory APIs fastest, collapsing stockout windows from days to hours and locking repeat purchase behavior.
- Home Goods:Furniture and décor segments deploy augmented-reality visualization tools to reduce return rates.
- Beauty Products:Cosmetics and personal care categories benefit from subscription replenishment models penetrating apartment-dense Buenos Aires neighborhoods.
Today's leader: Electronics. Tomorrow's challenger: Home Goods.
Customer Type:
Procurement patterns diverge sharply between individual consumption and institutional purchasing, with compliance requirements scaling across the spectrum.
- Individual Consumers:Argentina's core e-commerce demand source, characterized by mobile-first discovery and QR-code payment preference. AFIP's electronic invoicing mandate is forcing informal sellers onto formal platforms, expanding addressable merchant base for established marketplaces serving this segment.
- Small Businesses:Digital marketplace procurement is gaining traction among SMEs seeking supplier diversification. Tax compliance talent scarcity creates operational friction as these buyers navigate AFIP's evolving reporting protocols.
- Large Enterprises:B2B procurement platforms require ERP integration and volume-based pricing structures.
- Government Entities:Public sector purchasing mandates electronic invoicing compliance and transparent tender processes.
Individual Consumers anchor current volume. Small Businesses are climbing the fastest as formalization pressures intensify.
Delivery Model:
Fulfillment speed stratification creates pricing power tiers across metropolitan and provincial geographies.
- Standard Shipping:Cost-optimized ground delivery through third-party carriers dominates provincial zones. Fuel price volatility and informal labor dynamics compress margins for operators outside Greater Buenos Aires and Córdoba corridors.
- Same-Day Delivery:Micro-fulfillment nodes in dense urban zones enable premium pricing capture from time-sensitive buyers. Dark store deployments in metropolitan Buenos Aires zoning permit 15-minute delivery promises for fresh grocery categories.
- Express Delivery:Accelerated fulfillment windows command 20-40% price premiums over standard options.
- Click & Collect:In-store pickup integration anchors Frávega's electronics positioning, reducing last-mile costs.
Standard Shipping holds volume dominance. Same-Day Delivery shows steepest expansion trajectory as micro-fulfillment economics mature.
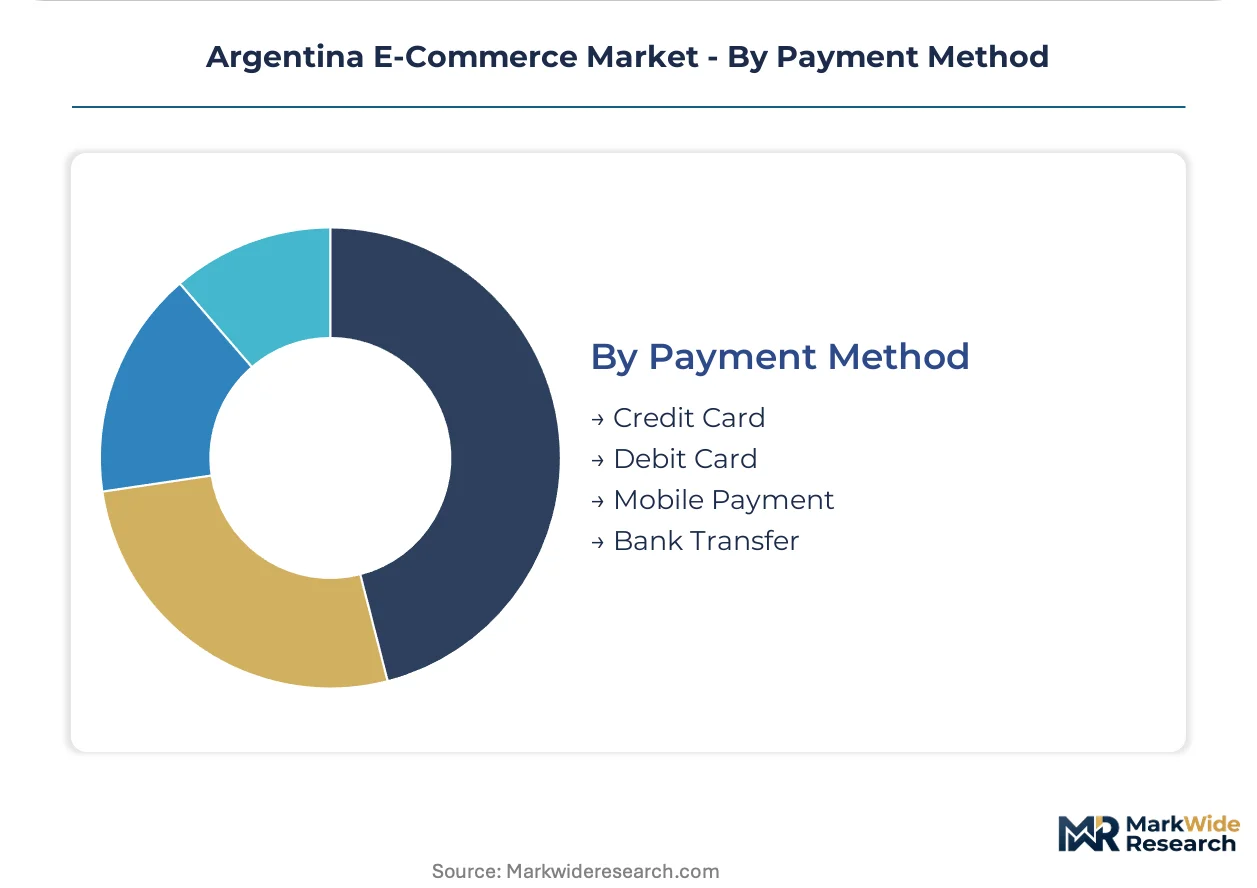
Payment Method:
Argentina's interoperable QR infrastructure is reshaping checkout friction and conversion optimization.
- Mobile Payment:QR-code rails reduce transaction friction and accelerate conversion rates for smartphone-native buyers. Argentina's interoperable payment infrastructure is displacing card-present habits fastest among under-35 demographics in urban corridors.
- Credit Card:Installment financing options sustain purchasing power amid inflation volatility. BCRA restrictions on dollar-denominated settlements constrain cross-border purchase flexibility, elevating domestic card network preference.
- Debit Card:Immediate settlement preference among budget-conscious segments limits merchant chargeback exposure.
- Bank Transfer:High-value B2B transactions favor this method for audit trail requirements.
Mobile Payment is gaining share fastest. Credit Card retains premium transaction value leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's e-commerce workforce clusters in Greater Buenos Aires, where logistics engineers and compliance specialists concentrate around micro-fulfillment infrastructure. Provincial corridors in Córdoba, Mendoza, and Rosario draw secondary talent pools as delivery density economics mature.
Greater Buenos Aires
Metro Buenos Aires generates the highest transaction velocity through dense micro-fulfillment node deployment. AFIP's electronic invoicing mandate concentrates compliance talent in the capital's financial district. Dark store proliferation in Palermo and Belgrano enables 15-minute grocery delivery promises.
Córdoba Urban Corridor
Córdoba's electronics and apparel retailers adopt real-time inventory APIs fastest outside the capital. Provincial tax authorities enforce AFIP reporting protocols with intensifying audit frequency. The city's Nueva Córdoba district anchors mid-market fashion logistics operations.
Mendoza Metropolitan Zone
Rising disposable income in Mendoza creates underpenetrated demand for specialized category retailers. BCRA currency settlement restrictions elevate domestic platform preference over cross-border alternatives. The Godoy Cruz commercial corridor attracts first-mover positioning from grocery velocity operators.
Rosario Industrial Belt
Rosario's SME procurement digitization accelerates as formalization pressures intensify. The national tax authority's data visibility requirements reshape seller-platform relationships. The city's Puerto Norte logistics cluster supports expanding same-day delivery coverage.
La Plata-Quilmes Axis
Buenos Aires province's southeastern corridor exhibits fastest small business marketplace adoption. AFIP audit procedures drive demand for compliance-integrated platform solutions. The Ringuelet distribution zone connects provincial fulfillment networks to capital infrastructure.
Argentina E-Commerce Market Vendor Landscape
The competitive structure tilts toward integrated marketplace-logistics operators with captive fulfillment networks. Three archetypes dominate: full-stack platforms controlling end-to-end delivery, category-specialized retailers with physical-digital integration, and international entrants navigating currency settlement constraints. Consolidation pressures favor operators with AFIP compliance automation and dense last-mile node deployment. Geographic expansion into secondary corridors and AR visualization technology licensing represent dominant competitive vectors.
Among Argentina-based marketplace operators, Mercado Libre Argentina S.R.L., Frávega S.A.C.I. e I., and Grupo Carrefour Argentina S.A. occupy positions across the integrated platform, specialized electronics, and grocery velocity archetypes respectively. Mercado Libre exemplifies captive logistics network advantages. Frávega represents in-store pickup integration models. Grupo Carrefour anchors dark store deployment for fresh categories. International entrants including Amazon.com Inc. and Tiendamia LLC navigate BCRA settlement restrictions that constrain payment flexibility.
| Leading Market Players |
|---|
| Mercado Libre Argentina S.R.L. |
| Frávega S.A.C.I. e I. |
| Grupo Carrefour Argentina S.A. |
| Musimundo S.A. |
| Amazon.com Inc. |
| Tiendamia LLC |
| Easy.com |
| Garbarino S.A. |
| Cencosud S.A. |
| Others |
Supply Flow & Price Mechanics
Argentine peso volatility against the US dollar cascades through e-commerce supply chains, compressing margins for imported electronics while elevating domestic fulfillment networks to premium pricing tiers. Currency-driven cost compression forces platforms to unbundle logistics services from product pricing, creating transparent fee structures that shift buyer behavior toward consolidated cart values.
Pricing Analysis
Unbundled fulfillment fees now dominate Argentine e-commerce transactions, separating last-mile costs from product list prices to maintain checkout conversion. Three-tier pricing structures across premium same-day, standard 48-hour, and economy 5-day delivery levels reflect density economics in Greater Buenos Aires versus provincial zones. Pricing pressure stems from BCRA currency settlement restrictions inflating landed costs for cross-border inventory, with informal sellers facing steepest compression under AFIP formalization mandates. Small businesses in Mendoza and Rosario corridors exhibit highest price sensitivity, while metropolitan consumers absorb premium delivery surcharges for time-sensitive categories.
Supply Chain Analysis
AFIP's domestic-content reporting requirements for electronic invoicing are reshaping seller sourcing toward Argentine-registered suppliers with compliant tax documentation. Fulfillment infrastructure concentrates in Greater Buenos Aires, Córdoba, and Mendoza provinces, with cross-border inventory flows drawing from China, Brazil, and USA manufacturing hubs. Micro-fulfillment nodes depend on imported automation hardware and domestic warehouse labor pools, exposing operators to tariff volatility on conveyor systems and sorting equipment. Single-source vulnerability concentrates in last-mile delivery partnerships outside capital corridors. Distribution runs through captive logistics networks for integrated platforms and third-party carrier aggregators for specialized retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's e-commerce market compounds steadily as AFIP's formalization mandates permanently expand the addressable merchant base onto taxable digital platforms. Regulatory-driven seller migration creates durable volume growth independent of macroeconomic cycles.
For Market Incumbents: Cement logistics density advantages through micro-fulfillment node expansion into Rosario and Mendoza corridors before competitors achieve viable delivery economics. Deepen AFIP compliance automation to capture informal sellers fleeing unregulated channels, while anchoring electronics category share against cross-border platforms constrained by BCRA settlement restrictions.
For New Entrants and Emerging Players: SME procurement officers in La Plata-Quilmes industrial belt represent the most penetrable buyer archetype, with tax compliance talent scarcity creating demand for integrated B2B marketplace solutions. White-space targets include augmented-reality visualization tools for furniture retailers and subscription replenishment algorithms for household consumables. A channel partnership with provincial logistics cooperatives accelerates coverage without captive fleet investment.
For Investors and Strategic Acquirers: Consolidation pressure builds where AFIP compliance automation intersects with dense last-mile node deployment, favoring acquisition of mid-market platforms with established seller tax integration. Long-term viability frames around 5-10 year regulatory formalization trajectories rather than cyclical consumption swings. The signal to watch is BCRA easing of dollar-denominated settlement thresholds, which would restructure cross-border competitive dynamics overnight.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Node Expansion | Deploys dark stores in Palermo and Belgrano to capture 15-minute grocery delivery premiums. |
| AFIP Compliance Automation | Integrates electronic invoicing APIs to onboard informal sellers ahead of audit enforcement waves. |
| QR Payment Infrastructure Partnership | Links interoperable checkout rails to reduce cart abandonment among mobile-native demographics. |
| Augmented Reality Visualization Licensing | Reduces furniture return rates through AR placement tools in historically problematic home goods segments. |
| Provincial Logistics Cooperative Alliance | Extends same-day coverage to Mendoza and Rosario without captive fleet capital deployment. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with marketplace operators, logistics engineers, AFIP compliance specialists, and retail category managers with secondary validation. Primary fieldwork drew from customs records, BCRA foreign exchange filings, and AFIP electronic invoicing disclosure patterns. Secondary sources included SEC filings from listed marketplace parents, Argentine Chamber of Electronic Commerce industry surveys, and provincial economic development board statistics. Bottom-up seller enumeration and top-down consumption expenditure estimates were triangulated to anchor market sizing.
Comparable historical periods anchored the projection framework, with growth trajectories modeled across the analysis window using category-specific demand elasticities. Segmentation dimensions included product type, customer archetype, delivery speed tier, and payment method preference, with urban density and regulatory compliance burden as cross-cutting variables. CAGRs were derived from logistic diffusion curves fitted to formalization-driven seller adoption patterns, incorporating fuel price volatility and currency depreciation scenarios as sensitivity inputs.
Underlying measurement precision varies by segment; Greater Buenos Aires transaction volumes carry tighter precision than provincial corridors due to data availability disparities. Forecasts reflect assumptions around AFIP enforcement intensity and BCRA currency regime stability, with either factor capable of revising trajectory materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
Panama E-Commerce Market
E-Commerce Solutions
Resale E-Commerce Platform Market
E-Commerce Solutions
Saudi Arabia E-Commerce Market
E-Commerce Solutions
UK Ecommerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
E-Commerce Software Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
Latin America E-Commerce Logistics Market