
 United States E-Invoicing Market | 2026-2036
United States E-Invoicing Market Size, Share, and Industry Trends Forecast 2026-2036
United States E-Invoicing Market Intelligence
Subscription-based SaaS financing is rewriting competitive entry barriers for e-invoicing platforms, allowing vendors to bypass heavy upfront enterprise sales cycles. SAP SE leverages its embedded ERP footprint to anchor invoice automation within existing financial workflows. Coupa Software Inc sustains differentiation through specialized procurement-to-pay network density. Basware Corporation dominates North American manufacturing verticals with deep EDI integration capabilities.
Electronic invoicing comprises structured digital document exchange between buyers and suppliers, typically formatted in XML, UBL, or EDI standards with embedded validation rules for tax and remittance data. Its primary commercial purpose is to eliminate manual data entry, accelerate payment cycles, and enforce regulatory compliance through automated audit trails. Cloud-based deployment leads the solution architecture as enterprises prioritize API connectivity over on-premises infrastructure maintenance. Invoice processing solutions capture the largest solution segment share, while compliance management functions are expanding fastest as state tax authorities mandate real-time reporting.
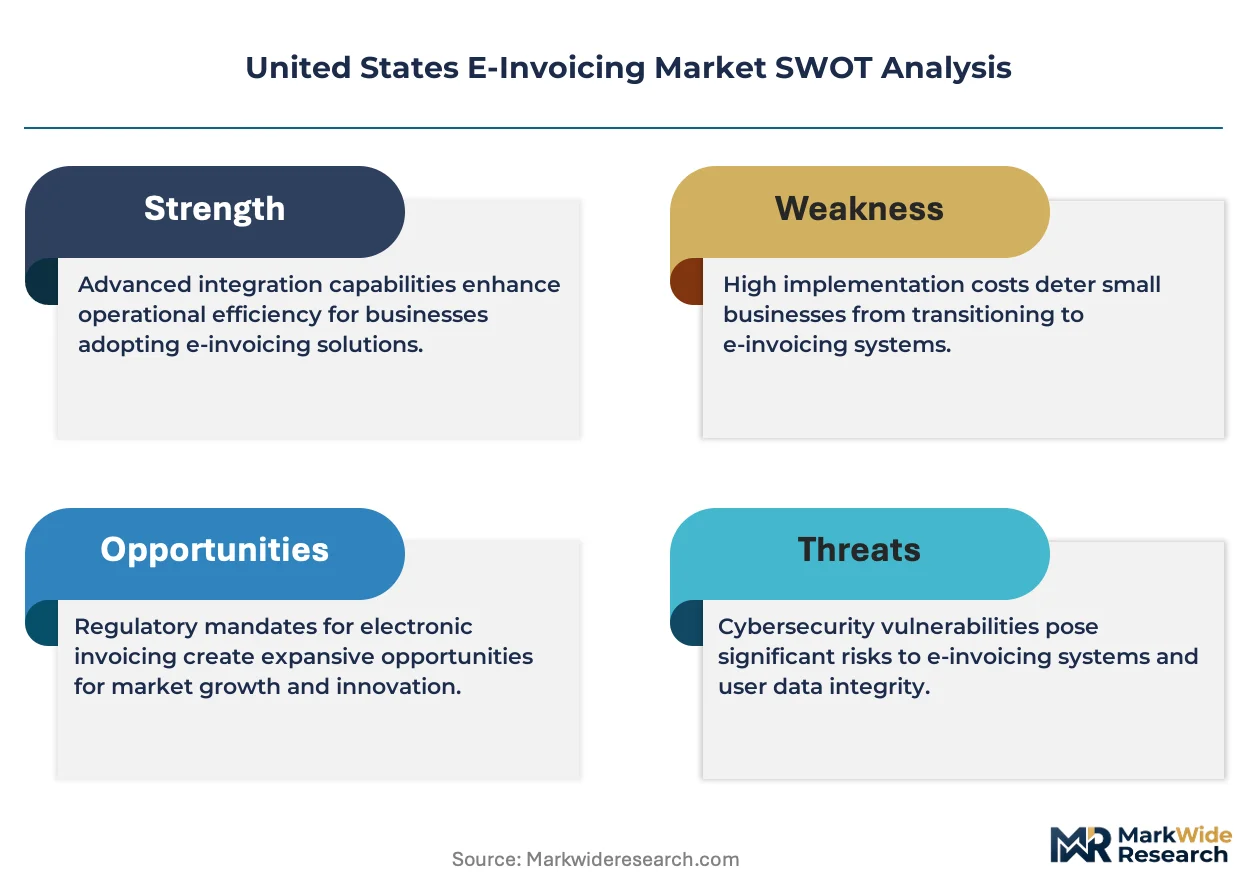
The IRS, state revenue departments, and the Financial Crimes Enforcement Network shape demand through electronic filing mandates, sales tax automation requirements, and anti-money-laundering documentation standards. HIPAA intersects where healthcare providers exchange electronic payment records with insurers, adding data security specifications to invoice platform procurement. Stakeholders must monitor how fragmented state-level e-invoicing requirements converge or diverge, as this will determine whether centralized national platforms or federated regional solutions prove more durable.
Market Dynamics
The IRS e-file mandates and state-level sales tax digitization requirements are forcing enterprise system upgrades across healthcare provider networks and mid-market manufacturers, compressing procurement cycles for automated invoice-to-payment workflows.
Growth Catalysts
- HIPAA-Compliant Healthcare Automation:Healthcare provider networks are accelerating adoption of automated invoice-to-payment workflows to exchange electronic payment records with insurers while meeting data security specifications.
- State Sales Tax Digitization:State revenue departments are mandating real-time reporting requirements that compel accounts-payable modernization among Midwest and Southeast manufacturers.
- API-First Cloud Architecture:Enterprises are prioritizing API connectivity over on-premises infrastructure maintenance, expanding deployment of cloud-based invoice processing solutions.
Market Restraints
- Fragmented State Requirements:Divergent e-invoicing mandates across state revenue departments create compliance complexity that favors regional solutions over centralized national platforms.
- Legacy ERP Integration Costs:Technical debt in existing financial workflows raises switching costs for mid-market manufacturers with limited IT modernization budgets.
- EDI Infrastructure Lock-In:Deep EDI integration capabilities in North American manufacturing verticals create supplier concentration risk and path dependency.
Strategic Opportunities
- Mid-Mark Manufacturing Penetration:Midwest and Southeast manufacturers seeking accounts-payable modernization represent underpenetrated demand concentration for SaaS-based platforms.
- Real-Time Compliance Management:State tax authorities mandating real-time reporting are expanding the fastest-growing solution segment beyond basic invoice processing.
- Procurement-to-Pay Network Density:Specialized network effects in supplier-buyer connectivity create white space for platforms embedding financing and payment orchestration.
Industry Challenges
- Multi-Standard Format Complexity:XML, UBL, and EDI standards with embedded validation rules require specialized technical talent scarce in enterprise IT departments.
- Anti-Money-Laundering Documentation:Financial Crimes Enforcement Network standards add compliance timeline friction to platform procurement and deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States E-Invoicing Market |
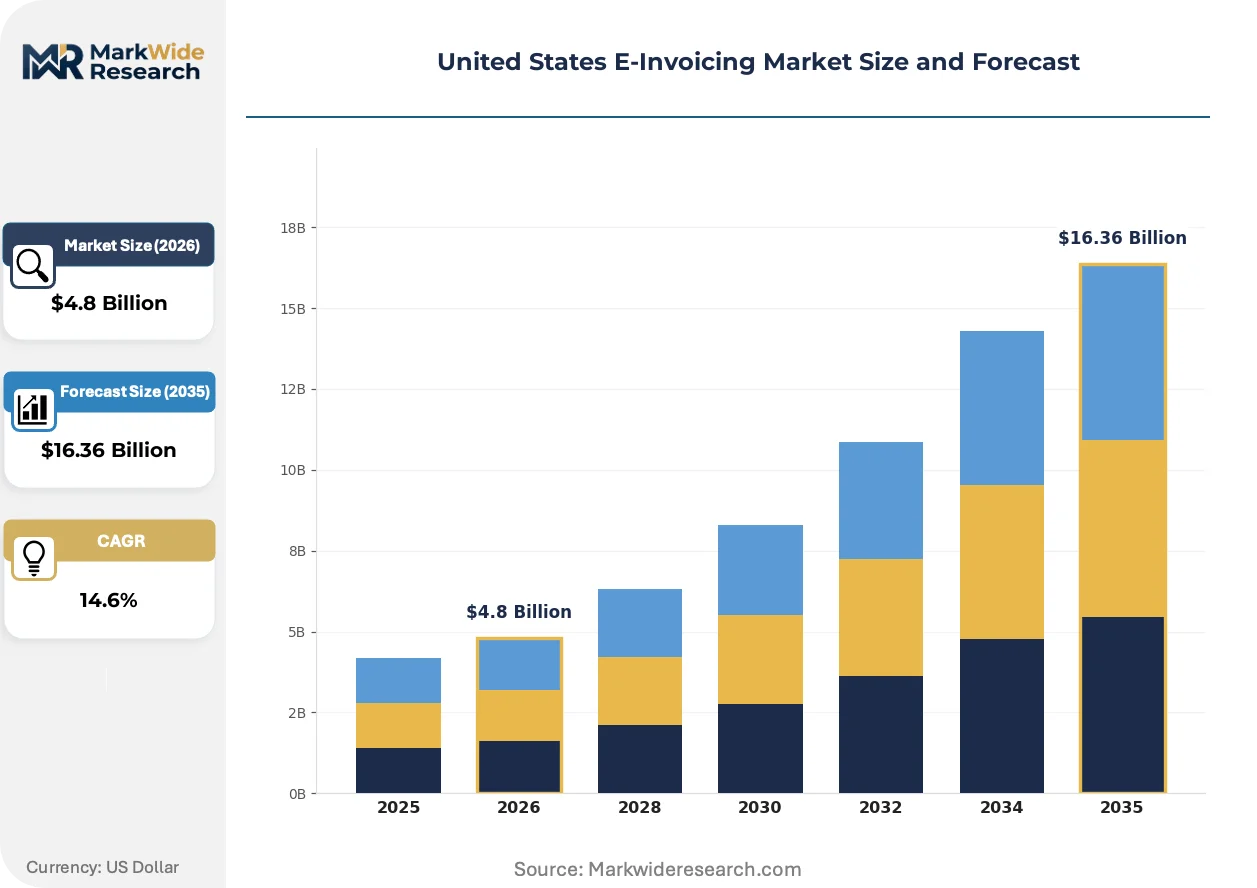
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retail, Manufacturing, Healthcare, BFSI Solution: Invoice Processing, Payment Collection, Compliance Management, Tax Management Integration Level: API Integration, EDI Integration, ERP Integration, Standalone |
| Companies Covered | Coupa Software Inc, SAP SE, Basware Corporation, Sage Group Plc, Tradeshift, International Business Machines Corp, Comarch SA, Cegedim SA, Vertex Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States E-Invoicing Market Strategic Shifts & Innovations
Structured digital document exchange is actively displacing manual data entry across buyer-supplier relationships, with validation automation and embedded audit trails compressing payment cycles and enforcement mechanisms.
Machine learning-powered data extraction from unstructured invoice formats is rendering obsolete manual OCR validation workflows in enterprise accounts-payable departments. Healthcare providers and mid-market manufacturers are adopting these tools at accelerated procurement cycles. The technology is compressing headcount requirements in shared service centers while raising accuracy thresholds for tax and remittance data capture.
The IRS electronic filing mandates are reshaping enterprise upgrade roadmaps by attaching penalty structures to non-compliance deadlines. Manufacturing verticals with complex supplier networks face the steepest adaptation curves as they reconcile federal requirements against fragmented state-level sales tax automation rules. Platform vendors are responding with modular compliance layers that segment functionality by jurisdiction.
Buyers are consolidating vendor relationships around embedded ERP footprints rather than standalone point solutions. SAP-anchored financial workflows are displacing best-of-breed procurement for enterprises prioritizing integration depth over specialized feature sets. This concentration is most visible among Midwest manufacturers with limited IT staff capacity to manage multi-vendor API ecosystems.
United States E-Invoicing Market Segmentation
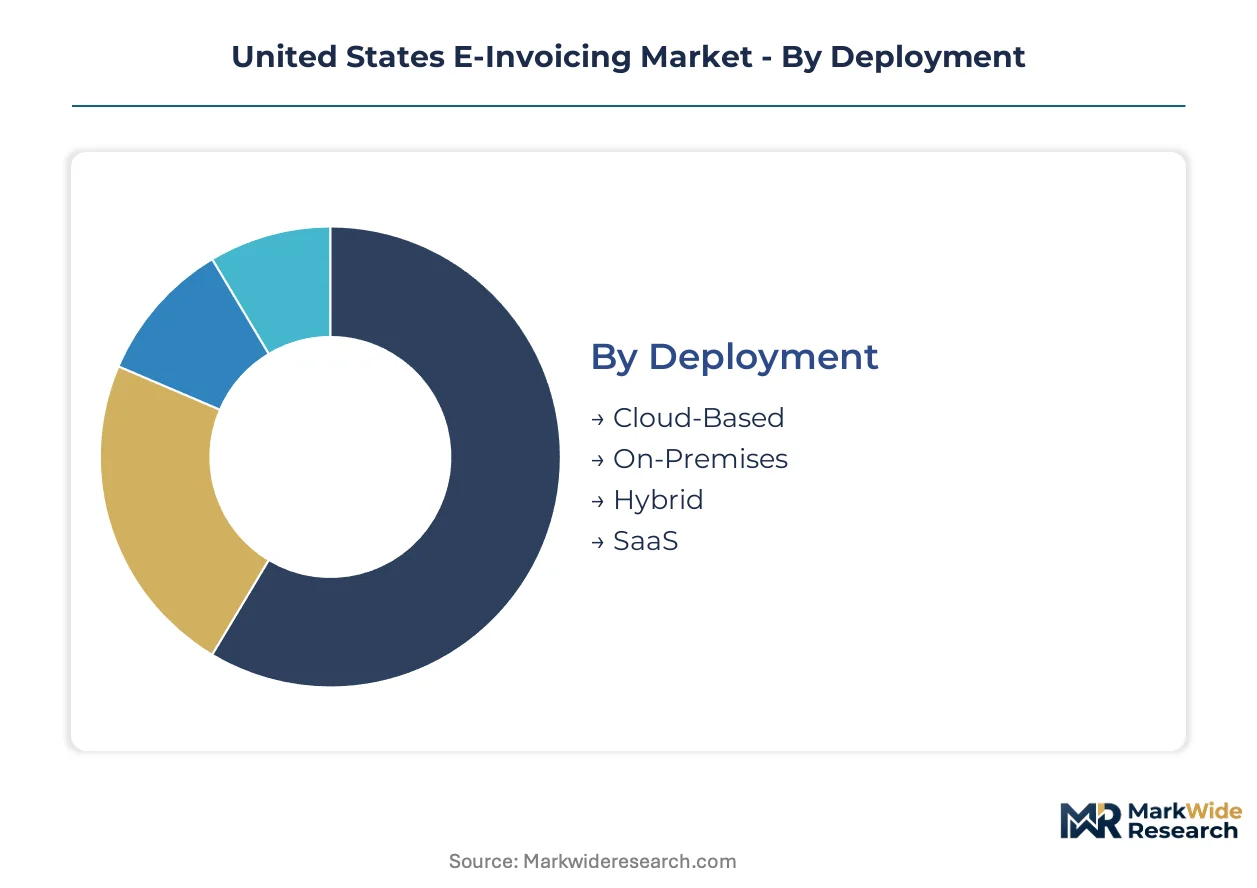
Deployment architecture determines service continuity commitments and upgrade cadence for e-invoicing vendors. End-user verticals impose distinct compliance overlays that reshape feature prioritization across platform roadmaps.
Deployment:
Post-implementation support intensity varies sharply across deployment modes, with cloud-native architectures demanding continuous API maintenance rather than episodic hardware servicing.
- Cloud-Based:Multi-tenant architectures with automatic patch management and elastic compute scaling. Demand concentrates among mid-market manufacturers in the Southeast seeking to eliminate data center overhead while maintaining HIPAA-aligned audit trails for healthcare supplier exchanges.
- SaaS:Subscription licensing with embedded compliance module updates and usage-based tiering. Healthcare provider networks in the Midwest are adopting these platforms fastest to satisfy state sales tax digitization mandates without dedicated IT infrastructure teams.
- Hybrid:Split processing between private invoice data repositories and public validation gateways. Appeals to BFSI institutions with legacy core systems requiring air-gapped transaction records.
- On-Premises:Single-tenant installations with full operational control over encryption keys and network segmentation. Persists in defense-adjacent manufacturing supply chains with classified procurement workflows.
Cloud-Based holds the largest share; momentum sits with SaaS as procurement cycles compress.
End User:
Application complexity scales with transaction volume heterogeneity and regulatory exposure depth across buyer-supplier networks.
- Healthcare:HIPAA-governed invoice exchanges with insurers requiring encrypted transmission protocols and immutable audit logs. Provider networks in Texas and Florida are accelerating automated workflows to meet IRS e-file deadlines for electronic payment record documentation.
- Manufacturing:High-velocity supplier onboarding with EDI document standards and multi-state tax jurisdiction reconciliation. Midwest automotive and industrial equipment producers dominate procurement activity as state revenue departments mandate real-time sales tax reporting.
- BFSI:Anti-money-laundering documentation standards from FinCEN layered onto payment orchestration platforms. Regional banks prioritize API-first architectures to avoid core system replacement costs.
- Retail:Seasonal volume spikes and marketplace seller integration complexity. National chains with distributed supplier bases favor modular compliance layers segmented by state tax authority requirements.
Manufacturing holds the largest share; momentum sits with Healthcare as provider network digitization accelerates.
Solution:
Margin profiles diverge between commoditized document conversion and high-value regulatory interpretation services.
- Compliance Management:Real-time validation against fragmented state e-invoicing mandates with automated penalty risk scoring. Expanding most quickly as state tax authorities in the Southeast and Midwest deploy mandatory reporting timelines.
- Invoice Processing:Machine learning-powered data extraction from unstructured formats with embedded XML, UBL, and EDI standard conversion. Captures the largest solution segment share among enterprises eliminating manual OCR workflows.
- Tax Management:Jurisdiction-specific rate calculation and remittance scheduling across multi-state supplier networks. Critical for manufacturers with complex nexus exposure.
- Payment Collection:Embedded financing and early-payment discount orchestration between buyers and suppliers. Network density effects concentrate value in platforms with high supplier adoption rates.
Invoice Processing holds the largest share; Compliance Management is gaining share fastest.
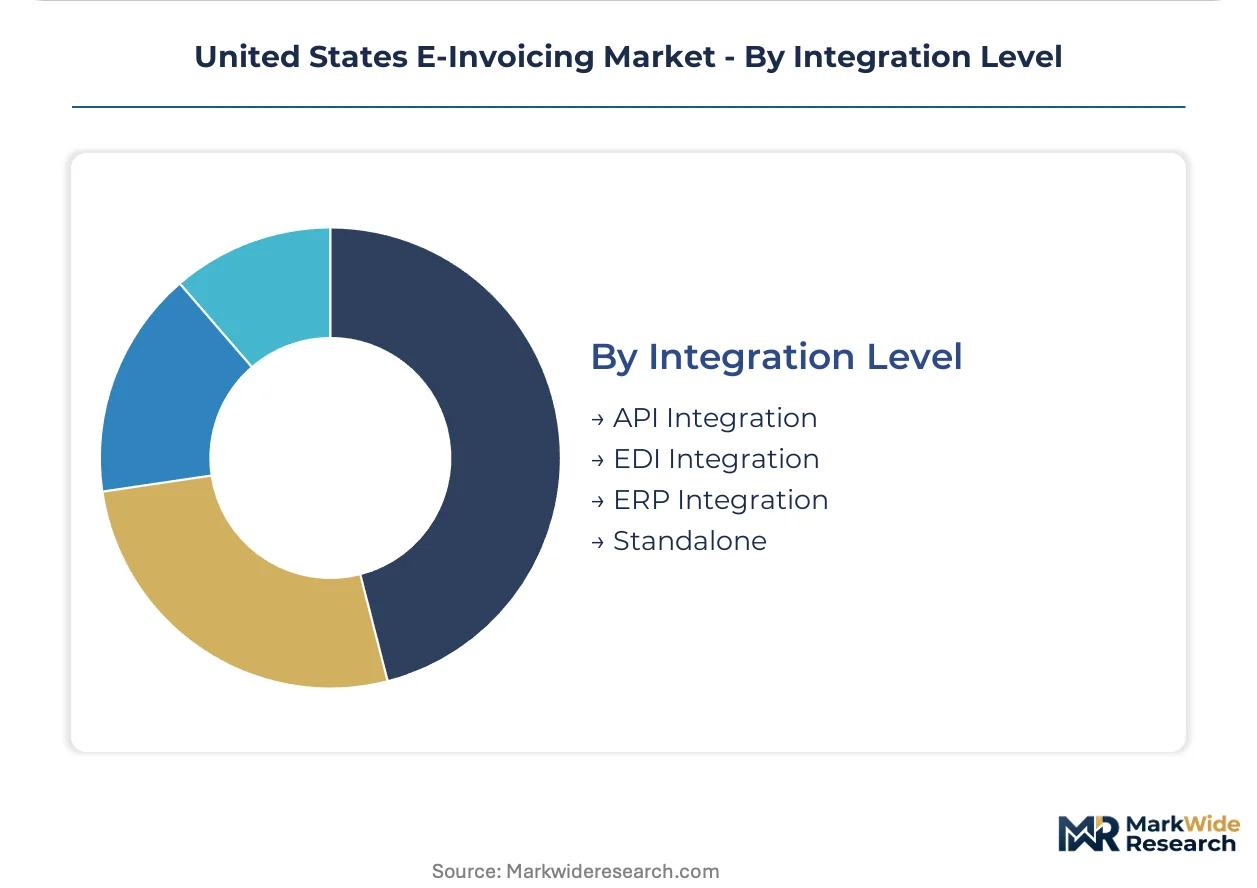
Integration Level:
Technical debt in existing financial workflows dictates switching cost tolerance and vendor consolidation patterns.
- ERP Integration:Native modules within SAP and Oracle financial suites with pre-built invoice automation workflows. Midwest manufacturers with limited IT staff capacity favor this path to avoid multi-vendor API ecosystem management.
- API Integration:RESTful connectivity layers enabling best-of-breed procurement-to-pay orchestration. Fastest-growing approach among mid-market enterprises prioritizing specialized feature depth over embedded footprint convenience.
- EDI Integration:Legacy document exchange protocols with deep supplier network lock-in. Dominates North American manufacturing verticals where technical path dependency raises competitive barriers.
- Standalone:Point solutions requiring manual data export to financial systems. Declining share as enterprises consolidate around connected platform architectures.
ERP Integration holds the largest share; API Integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market manufacturers in the Midwest and Southeast drive procurement velocity, while healthcare provider networks in Texas and Florida compress implementation timelines for automated invoice-to-payment workflows.
Southeast
Automotive and industrial equipment producers in Georgia and Alabama accelerate accounts-payable modernization to satisfy state revenue department mandates for real-time sales tax reporting. The IRS e-file requirements attach penalty structures to non-compliance deadlines, compelling enterprise system upgrades. Atlanta anchors supplier network density where platforms embed EDI integration capabilities for manufacturing verticals.
Midwest
Chicago and Detroit manufacturing clusters prioritize ERP-anchored financial workflows to avoid multi-vendor API ecosystem management with limited IT staff capacity. Michigan and Ohio state tax authorities deploy mandatory reporting timelines that expand compliance management solution adoption. Automotive tier-one suppliers concentrate procurement activity around native SAP modules with pre-built invoice automation.
Texas
Houston and Dallas healthcare provider networks exchange electronic payment records with insurers under HIPAA data security specifications, accelerating automated workflow procurement. The state revenue department digitization requirements intersect with federal mandates to compress vendor selection cycles. Medical billing service bureaus in Austin adopt SaaS platforms with embedded compliance module updates.
Florida
Miami and Tampa healthcare systems face dual pressure from IRS e-file deadlines and state-level sales tax automation rules, driving modular compliance layer adoption. Provider networks segment functionality by jurisdiction to reconcile fragmented requirements. Orlando medical groups prioritize API-first cloud architectures to eliminate data center overhead.
California
Los Angeles and San Francisco Bay Area enterprises consolidate vendor relationships around embedded ERP footprints rather than standalone point solutions. Technology sector procurement prioritizes integration depth over specialized feature sets. Sacramento healthcare networks adopt hybrid deployment architectures for air-gapped transaction records with public validation gateways.
United States E-Invoicing Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where embedded ERP footprints anchor enterprise relationships and API-first specialists capture mid-market procurement cycles. The vendor base segments into three strategic archetypes: ERP-embedded incumbents leveraging existing financial workflow integration, procurement-to-pay network specialists building supplier-buyer density, and compliance-focused platforms targeting real-time tax reporting mandates. Dominant competitive moves include M&A activity consolidating point solutions into connected platform architectures and strategic partnerships embedding financing capabilities within invoice automation workflows.
Within the ERP-embedded tier, SAP SE and Coupa Software Inc occupy positions that exemplify divergent integration strategies, while Basware Corporation anchors the North American manufacturing vertical specialization. SAP SE represents the embedded footprint archetype where native modules displace best-of-breed procurement for IT-constrained enterprises. Coupa Software Inc exemplifies network density specialization through procurement-to-pay connectivity. Basware Corporation sits within the EDI integration archetype where deep supplier network lock-in creates path dependency for manufacturing accounts-payable modernization.
| Leading Market Players |
|---|
| Coupa Software Inc |
| SAP SE |
| Basware Corporation |
| Sage Group Plc |
| Tradeshift |
| International Business Machines Corp |
| Comarch SA |
| Cegedim SA |
| Vertex Inc |
| Others |
Cost & Logistics Intelligence
Single-source dependency on cloud infrastructure hyperscalers determines both SaaS subscription tier spreads and supply chain resilience architecture across the United States e-invoicing market. AWS and Azure concentration in Midwest data centers creates pricing power asymmetry while forcing vendor diversification into multi-cloud orchestration layers.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate enterprise procurement of invoice automation platforms, anchoring annual subscription escalators to Bureau of Labor Statistics technology services indices. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-compliant healthcare modules from basic manufacturing document conversion, with customization depth and API call volume driving tier placement. Pricing pressure stems from mid-market manufacturers consolidating vendor relationships around embedded ERP footprints, compressing standalone solution margins. Healthcare provider networks exhibit lowest price sensitivity due to penalty exposure from IRS e-file non-compliance, while Southeast automotive suppliers negotiate aggressively on per-seat licensing.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from platform vendors to implementation partners compress working capital cycles across the ecosystem. Software development concentrates in the United States, India, and Ireland, with machine learning engineering talent clustering in Austin and Bangalore. Cloud compute and API gateway dependencies rest on hyperscaler infrastructure, with single-region outage risk driving multi-availability-zone architecture mandates. Distribution runs through direct enterprise sales teams and systems integrator channel partners, with SAP-certified consultants capturing implementation margin in Midwest manufacturing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mid-market manufacturers consolidating around ERP-embedded procurement, fragmenting demand for standalone point solutions and compressing pricing power for non-integrated vendors.
For Market Incumbents: Harden defensive moats by deepening native SAP and Oracle module integration to capture IT-constrained Midwest manufacturing procurement, while accelerating compliance management feature development to outpace state revenue department mandate expansion. Threat substitution from API-first specialists requires preemptive multi-cloud orchestration investment to neutralize infrastructure lock-in objections. For New Entrants and Emerging Players: Southeast healthcare provider networks in Florida and Georgia represent the most penetrable entry point, where dual IRS and state tax digitization pressures compress vendor selection cycles and favor modular SaaS deployment. Target medical billing service bureaus with usage-based tiering and embedded HIPAA audit trail automation as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors procurement-to-pay network density specialists over standalone document conversion tools. Long-term viability hinges on supplier-buyer transaction volume capture rather than per-seat licensing expansion. Watch state revenue department real-time reporting mandate adoption velocity as the inflection signal for compliance management solution valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native SAP and Oracle module embedding captures IT-constrained Midwest manufacturing procurement cycles. |
| Compliance Module Expansion | Real-time state tax validation layers address fragmented mandate expansion across Southeast and Midwest revenue departments. |
| Strategic Partnership | Medical billing service bureau alliances accelerate healthcare provider network penetration in Texas and Florida. |
| Acquisition of Specialist Firm | Machine learning data extraction capabilities eliminate manual OCR headcount in shared service center deployments. |
| Geographic Expansion | Atlanta and Chicago sales presence captures automotive and industrial equipment supplier network density. |
Research Approach
Desk research of SEC 10-K filings, IRS regulatory guidance documents, and state revenue department mandate disclosures preceded structured interviews with healthcare CFOs, manufacturing procurement directors, and SaaS platform product managers. Primary fieldwork with Midwest automotive tier-one suppliers and Southeast medical billing service bureaus validated secondary data on implementation timelines and compliance module adoption. Bottom-up deployment model sizing and top-down enterprise IT spending allocation triangulated market estimates across the analysis window.
Assumptions held state-level e-invoicing mandate convergence patterns and cloud migration velocity fixed, while varying mid-market manufacturer IT staff capacity constraints and healthcare provider network consolidation rates. Segmentation modeling spanned deployment architecture, end-user vertical, solution type, and integration complexity dimensions. CAGRs derived from logistic adoption curve fitting against historical ERP upgrade cycle patterns, with API connectivity penetration and real-time compliance module attach rates serving as key forecast inputs.
Practitioners should monitor state revenue department mandate divergence or convergence signals for early indicators of platform architecture durability. Macroeconomic deviation affecting mid-market manufacturer IT modernization budgets, regulatory acceleration of federal e-invoicing standardization, or technological breakthrough in unstructured document extraction would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
North America E-Commerce Market
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Global Omnichannel Retail Commerce Platform Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
Estonia E-Commerce Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market