
 Retail Sourcing and Procurement Market | 2026-2036
Retail Sourcing and Procurement Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Sourcing and Procurement Market Intelligence
The retail sourcing and procurement landscape is recalibrating around a widening split between premium AI-orchestrated platforms and commodity procurement tools. SAP Ariba leverages deep ERP integration to anchor enterprise-grade contract management across Fortune 500 retailers. Oracle Corporation competes through autonomous procurement databases that reduce manual supplier onboarding cycles. Zycus Inc. specializes in cognitive spend analysis, differentiating its position in mid-market retail chains seeking predictive sourcing capabilities.
Retail sourcing and procurement encompasses the strategic identification, evaluation, contracting, and management of suppliers across merchandise categories, typically executed through software platforms integrating spend analytics, supplier risk scoring, and automated purchase order workflows. The primary commercial purpose centers on reducing cost leakage, ensuring inventory continuity, and enforcing ethical compliance across multi-tier supplier networks. Technology solutions within the service type dimension command the deepest margin pools as retailers replace legacy on-premise installations with API-first cloud architectures. Direct-to-consumer distribution channels now require procurement systems capable of dynamically reallocating inventory between fulfillment nodes based on real-time demand signals. Small enterprises represent an underserved customer type where modular, pay-per-supplier pricing models are displacing traditional seat-based licensing.
The Federal Trade Commission scrutinizes supplier concentration risks in US retail supply chains, while the EU AI Act imposes transparency obligations on automated procurement scoring algorithms deployed across European operations. India's BIS standards for electronic product sourcing create compliance gateways for cross-border retail procurement platforms entering that market. Stakeholders must monitor how divergent data localization mandates between jurisdictions reshape cloud procurement architecture decisions.
Market Dynamics
Cloud-native procurement platforms are compressing supplier onboarding cycles from months to weeks, forcing legacy ERP vendors to rearchitect around API-first connectivity rather than monolithic suites.
Growth Catalysts
- EU AI Act transparency mandates:Automated supplier scoring algorithms now require explainability layers, driving retailers toward platforms with built-in audit trails and bias-detection modules.
- Grocery chain modernization:Supermarket networks are consolidating fragmented supplier bases onto unified sourcing platforms to reduce stockout risks across perishable categories.
- Real-time inventory reallocation:Direct-to-consumer fulfillment nodes now demand procurement systems that dynamically shift purchase orders between distribution centers based on demand signals.
Market Restraints
- Data localization mandates:Divergent cross-border data residency requirements between the United States, European Union, and India force redundant cloud infrastructure investments.
- Supplier concentration in East Asian manufacturing:Heavy reliance on concentrated electronics and textile production clusters creates vulnerability to geopolitical trade disruptions.
- Legacy system integration friction:Decades-old on-premise ERP installations resist API connectivity, delaying cloud migration timelines for mid-market retailers.
Strategic Opportunities
- Modular pricing for small enterprises:Pay-per-supplier models are displacing seat-based licensing in underserved customer segments with fewer than 50 vendor relationships.
- Blockchain-IoT convergence:Immutable supplier provenance tracking combined with sensor-verified shipment conditions enables automated compliance enforcement for ethical sourcing claims.
- India's PLI scheme for electronics:Production-linked incentives for domestic manufacturing create procurement localization opportunities for cross-border retail platforms entering that market.
Industry Challenges
- Procurement data science talent scarcity:Retailers struggle to hire analysts capable of interpreting AI-generated spend insights and translating them into supplier negotiation tactics.
- Multi-tier supplier visibility gaps:Mapping beyond direct vendors into sub-tier networks requires capital-intensive supplier onboarding and ongoing audit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Sourcing and Procurement Market |
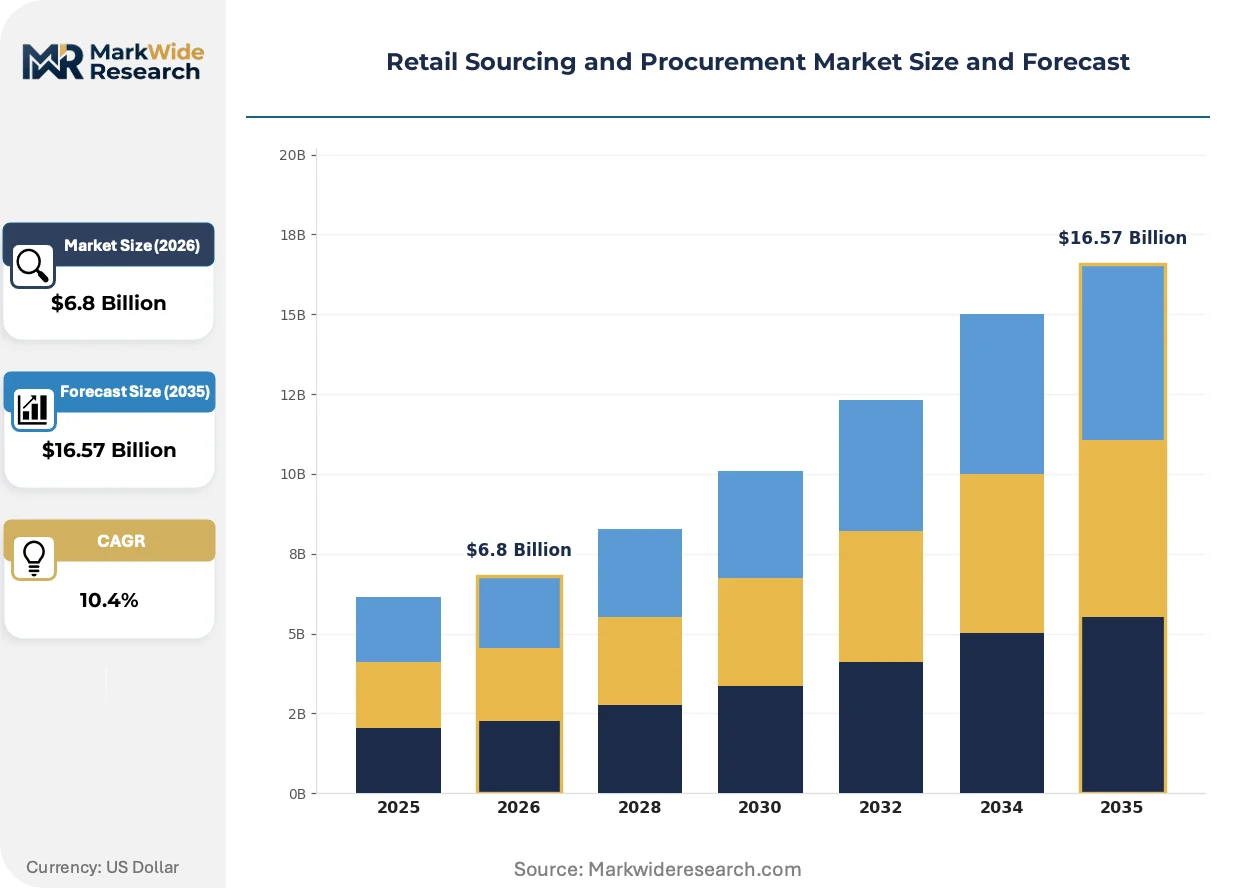
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $16.57 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Electronics, Home Goods, Groceries Service Type: Consulting, Technology Solutions, Market Research, Logistics Distribution Channel: Online, Wholesale, Direct-to-Consumer, Partnerships Customer Type: Small Enterprises, Large Corporations, Start-ups, Non-profits |
| Companies Covered | Kinaxis, JAGGAER, SAP Ariba, IBM Corporation, Zycus Inc., Oracle Corporation, Basware Corporation, Proactis Holdings Plc., Coupa Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Sourcing and Procurement Market Strategic Shifts & Innovations
Generative AI is rewriting contract negotiation playbooks while sustainability scoring becomes a procurement gatekeeper rather than a secondary filter.
Autonomous sourcing agents are integrating natural language processing to draft supplier communications, evaluate counteroffers, and flag contractual risks without human intervention. Mid-market retail chains are piloting these tools fastest, compressing sourcing cycle times by eliminating manual email threads and spreadsheet-based bid comparisons. The technology is integrating directly into existing cloud procurement stacks through embedded AI modules rather than standalone platforms.
The EU AI Act imposes algorithmic transparency obligations on automated procurement scoring systems deployed across European retail operations. Retailers must now document how supplier risk ratings are calculated and provide appeal mechanisms for vendors flagged by automated decisions. Fashion and electronics procurement teams face the steepest compliance burdens given their reliance on predictive supplier performance models.
Outcome-based supplier contracts are replacing unit-price agreements in private-label merchandise categories. Retailers now tie payment terms to sell-through rates, quality defect thresholds, and carbon footprint reductions rather than per-unit costs. Grocery and apparel verticals lead this shift in North American and Western European markets where margin pressure and ESG commitments converge.
Retail Sourcing and Procurement Market Segmentation
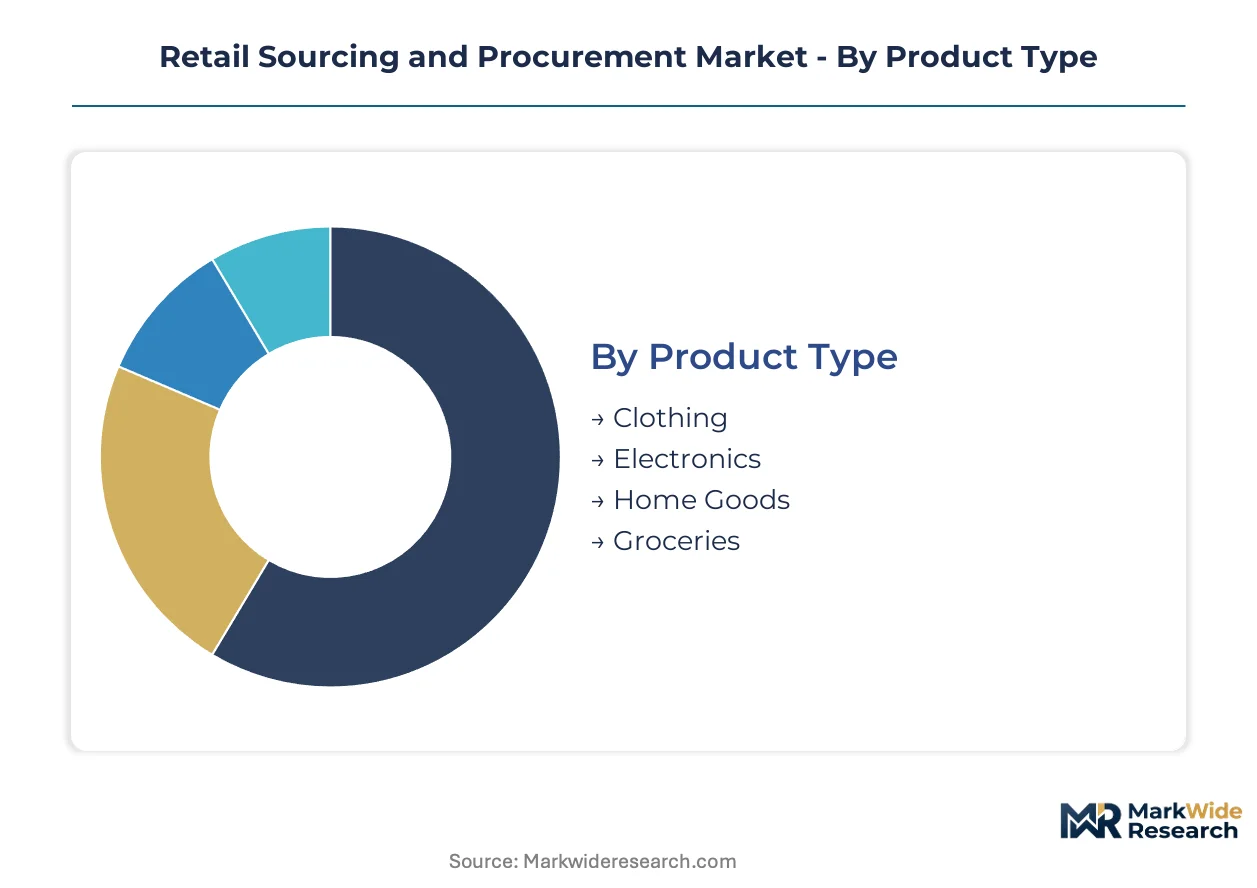
Retail procurement segmentation reveals how sourcing priorities diverge across merchandise volatility, technology intensity, and organizational scale. Understanding these fault lines clarifies why cloud platform vendors pursue radically different pricing architectures for perishable goods versus durable categories.
Product Type:
Buyer procurement cycles vary dramatically by inventory depreciation risk and supplier geographic concentration.
- Clothing:Seasonal SKU turnover demands agile supplier switching capabilities. Fast-fashion retailers in Italy and Bangladesh concentrate procurement spend on nearshoring partnerships to compress design-to-rack timelines.
- Electronics:Long lead times for semiconductor components require predictive sourcing algorithms. US and German retailers prioritize supplier risk scoring modules that flag single-source dependencies before disruption cascades.
- Home Goods:Bulky logistics favor consolidated supplier relationships with freight-integrated contracts.
- Groceries:Perishability mandates real-time quality verification and temperature-monitored shipment tracking.
Groceries leads volumes today; electronics is gaining share fastest.
Service Type:
Margin capture concentrates in technology layers that embed proprietary data assets rather than hourly consulting engagements.
- Technology Solutions:API-first cloud platforms command recurring revenue through supplier network effects. Mid-market retail chains in France and South Korea adopt modular spend analytics that integrate with existing ERP stacks without full replacement.
- Consulting:Strategic sourcing advisory focuses on category management and negotiation playbook design for private-label expansion programs.
- Market Research:Supplier benchmarking databases deliver competitive intelligence on pricing spreads across comparable vendor portfolios.
- Logistics:Freight procurement optimization tools dynamically route shipments between ocean, air, and rail modes based on cost and carbon trade-offs.
Technology Solutions dominates revenue contribution; Logistics exhibits the steepest expansion trajectory.
Distribution Channel:
Channel selection determines whether procurement systems optimize for bulk container economics or fragmented last-mile fulfillment nodes.
- Direct-to-Consumer:Micro-fulfillment centers require procurement modules that split purchase orders across multiple regional distribution nodes. UK and Japanese retailers pilot AI-driven inventory reallocation that shifts stock between warehouses based on real-time demand signals.
- Online:Marketplace sellers demand supplier onboarding portals with automated compliance documentation for cross-border trade.
- Wholesale:Volume-tiered pricing contracts anchor procurement relationships with predictable annual commitments.
- Partnerships:Co-branded merchandise programs require joint supplier governance frameworks with revenue-sharing transparency.
Wholesale maintains the largest transaction volumes; Direct-to-Consumer is climbing the fastest.
Customer Type:
Organizational scale dictates whether procurement technology investments prioritize automation depth or implementation speed.
- Large Corporations:Multi-divisional retailers deploy enterprise-grade contract lifecycle management with automated compliance monitoring across tiered supplier networks. US-based Fortune 500 chains mandate ESG scoring integration into every sourcing decision.
- Small Enterprises:Pay-per-supplier pricing models displace seat-based licensing for retailers managing fewer than 50 active vendor relationships.
- Start-ups:Rapid scaling demands procurement platforms with instant supplier onboarding and pre-negotiated marketplace rates.
- Non-profits:Donation-in-kind sourcing and mission-aligned supplier screening create specialized procurement workflows.
Large Corporations anchor current procurement technology spend; Small Enterprises represents the most underserved expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement technology talent clusters in the United States anchor the sector's innovation pipeline, with secondary concentrations emerging in Germany and India as cloud platform development scales.
United States
Enterprise retailers headquartered in Chicago and Dallas drive demand for real-time supplier risk management tools. The FTC scrutinizes supplier concentration risks under antitrust frameworks, forcing procurement platforms to embed compliance monitoring. Seattle and San Francisco host the densest cloud-native development clusters for automated contract lifecycle management.
Germany
Automotive and industrial retailers in Stuttgart and Munich prioritize predictive sourcing algorithms for semiconductor procurement. The EU AI Act mandates explainability layers for automated supplier scoring, compelling platform vendors to retrofit audit trail capabilities. Bavaria's manufacturing belt concentrates procurement software R&D investment.
India
Mid-market retail chains in Bangalore and Mumbai adopt modular spend analytics as BIS standards for electronics sourcing create compliance gateways. The PLI scheme for domestic manufacturing attracts procurement platform localization investments. Hyderabad's technology corridor hosts expanding delivery centers for cloud procurement implementations.
United Kingdom
Grocery and fast-fashion retailers in London and Manchester pilot AI-driven inventory reallocation between micro-fulfillment nodes. GDPR compliance requirements shape cloud procurement architecture decisions for cross-border supplier data flows. The Midlands logistics corridor concentrates freight procurement optimization tool deployment.
Japan
Department store networks in Tokyo and Osaka consolidate fragmented supplier bases onto unified sourcing platforms. METI guidelines for supply chain resilience encourage predictive risk scoring adoption. The Nagoya manufacturing hub drives demand for semiconductor procurement visibility tools.
Retail Sourcing and Procurement Market Key Industry Players
Capital-heavy ERP suite producers compete with asset-light cloud-native specialists for procurement technology budgets. The vendor landscape fragments across three tiers: legacy enterprise suites with deep integration capabilities, API-first platforms targeting mid-market displacement, and niche cognitive analytics providers. Strategic moves concentrate on M&A for supplier network data assets and geographic expansion through localized compliance modules.
Within the enterprise integration tier, SAP Ariba and Oracle Corporation anchor positions through ERP ecosystem lock-in, while Zycus Inc. occupies the cognitive spend analysis specialization. These three exemplify divergent architectural bets: suite consolidation versus modular best-of-breed deployment.
| Leading Market Players |
|---|
| Kinaxis |
| JAGGAER |
| SAP Ariba |
| IBM Corporation |
| Zycus Inc. |
| Oracle Corporation |
| Basware Corporation |
| Proactis Holdings Plc. |
| Coupa Software |
| Others |
Cost & Logistics Intelligence
Container freight index volatility cascades through retail procurement tiers, compressing margins for mid-market chains while amplifying pricing power for cloud-native platform vendors with freight-integrated contracts.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning. SaaS-tiered subscription models dominate enterprise accounts, while pay-per-supplier modular pricing captures small enterprises with fewer than 50 vendor relationships. Price differentiation hinges on AI-orchestration depth and API integration complexity, with grocery chains showing highest sensitivity due to perishable inventory pressures. Cost compression in mid-market tiers intensifies as legacy ERP migration delays extend procurement cycles.
Supply Chain Analysis
BIS certification gating for electronics sourcing in India, combined with EU AI Act transparency mandates, reshapes supplier qualification workflows. Manufacturing concentration centers on China, Vietnam, and Bangladesh for textiles; Taiwan and South Korea for semiconductor components. Raw material dependencies span lithium-ion batteries, rare earth elements, and agricultural commodities. Single-source vulnerability in East Asian electronics clusters creates tariff exposure. Distribution runs through consolidated ocean freight contracts with last-mile micro-fulfillment node splitting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail sourcing and procurement has matured into a late-cycle quality story as enterprise buyers prioritize explainable AI procurement scoring over commodity automation tools.
For Market Incumbents: Extend cognitive spend analytics capabilities into sub-tier supplier visibility layers. Defensive consolidation through supplier network data asset acquisition neutralizes cloud-native API-first challengers. ESG scoring integration investment anchors contract lifecycle management renewals against modular disrupters. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for explainability-layer specialists targeting fashion and electronics procurement teams. India's PLI scheme for domestic electronics manufacturing creates localization partnership opportunities. White-space concentration sits with modular spend analytics for French and South Korean mid-market retail chains seeking ERP-preserving deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with cognitive analytics providers possessing proprietary supplier risk scoring datasets. Five-to-ten year viability favors platforms with embedded compliance modules for divergent data localization mandates. The signal to watch is FTC enforcement intensity on supplier concentration risk disclosures.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Cloud-native architectures displace monolithic ERP suites through modular connectivity layers. |
| Supplier Network Data Acquisition | Proprietary risk scoring datasets create defensible moats against commodity procurement tools. |
| ESG Scoring Module Development | Automated carbon footprint tracking satisfies Fortune 500 procurement mandate requirements. |
| Geographic Compliance Localization | India BIS and EU AI Act modules enable market entry without full platform rearchitecture. |
| Cognitive Spend Analytics Expansion | Predictive sourcing algorithms reduce semiconductor procurement lead time uncertainty. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured sourcing directors, cloud platform engineers, supplier risk analysts, and grocery chain procurement leads across North America, Europe, and Asia-Pacific. Secondary validation drew from SEC filings, customs trade databases, EU regulatory filings, and cloud vendor capex disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume estimates.
Segment-weighting approach distributed value across technology solutions, consulting, market research, and logistics service types. Deployment model, organization scale, merchandise category volatility, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs derived from historical trajectory analysis and adoption curve modeling across the projection horizon. Cloud migration pace and AI module penetration rates served as category-specific forecast inputs.
Revisions become necessary when divergent data localization mandates intensify, geopolitical trade disruptions cascade through East Asian manufacturing clusters, or legacy ERP integration friction delays cloud adoption timelines. Deviation in FTC antitrust enforcement on supplier concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Smart Shelf Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Self-Service Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Digital Kiosk Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Global Restaurant Point of Sale (POS) Terminals Market
Retail Technology
Smart Shelves Market
Retail Technology
E-Retail Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Smart Retail Systems Market