
 Mobile Commerce Market | 2026-2036
Mobile Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Commerce Market Intelligence
Progressive web applications with embedded payment SDKs is tilting merchant infrastructure away from standalone native apps toward browser-based checkout experiences. Amazon.com Inc. leverages its fulfillment network to anchor same-day delivery expectations within mobile interfaces. Apple Inc. differentiates through its closed-loop wallet and biometric authentication stack. Tencent Holdings Ltd. dominates super-app commerce in Asia by integrating messaging, payments, and mini-program storefronts within a single interface.
Mobile commerce encompasses commercial transactions conducted through wireless handheld devices, typically involving encrypted data transmission over cellular or Wi-Fi networks with tokenized payment credentials and device fingerprinting for fraud prevention. Its primary purpose is to enable frictionless purchasing, account management, and financial services outside traditional branch or desktop environments. Digital wallets now capture the deepest margin pools as they lock in recurring transaction flows and reduce interchange leakage for merchants. In-app purchases within mobile apps represent the fastest-growing transaction type as content creators and game developers bypass web checkout entirely. Payment processing services remain the most mature segment, with infrastructure commoditization pressuring standalone gateway providers to bundle value-added fraud analytics.
The Consumer Financial Protection Bureau in the United States scrutinizes buy-now-pay-later products embedded in mobile checkout flows, while the EU's Digital Markets Act imposes interoperability mandates on gatekeeper platforms operating wallet and app store services. India's Reserve Bank enforces tokenization rules and transaction limits that shape how digital wallets onboard users and route payments. Stakeholders must monitor whether open banking APIs and real-time payment rails will disintermediate card networks from the mobile checkout stack before infrastructure investments harden around incumbent architectures.
Market Dynamics
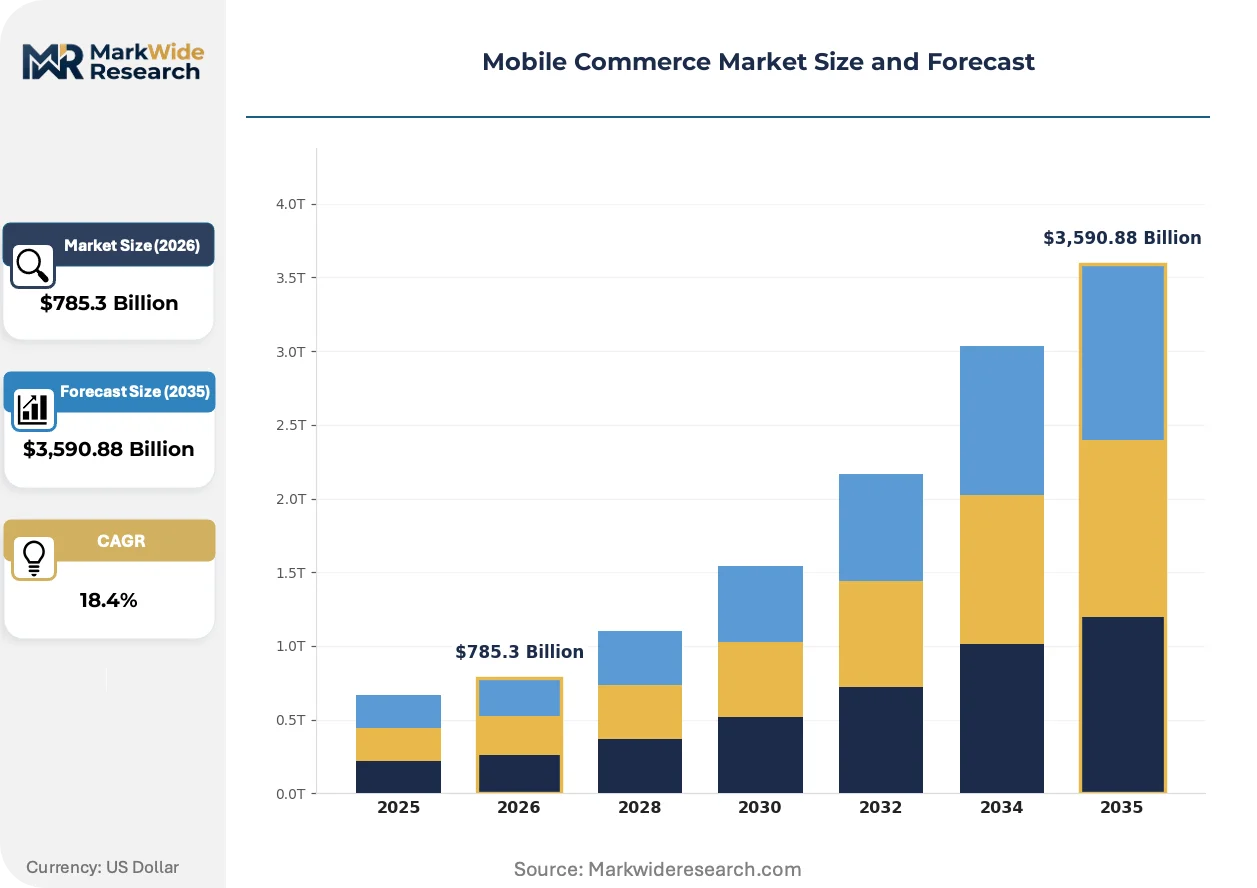
The mobile commerce infrastructure is bifurcating between super-app ecosystems and open-wallet architectures, with merchant acquisition costs and payment routing economics determining which model captures transaction volume in emerging versus developed markets.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Domestic handset production is reducing device costs and accelerating smartphone penetration in tier-two and tier-three cities where mobile-first internet access dominates.
- Real-time payment rails:India's UPI and Brazil's Pix are embedding instant settlement into mobile checkout flows, reducing merchant working capital requirements and interchange leakage.
- Progressive web applications:Browser-based checkout experiences with embedded payment SDKs are lowering merchant onboarding friction compared to native app development and app store compliance costs.
Market Restraints
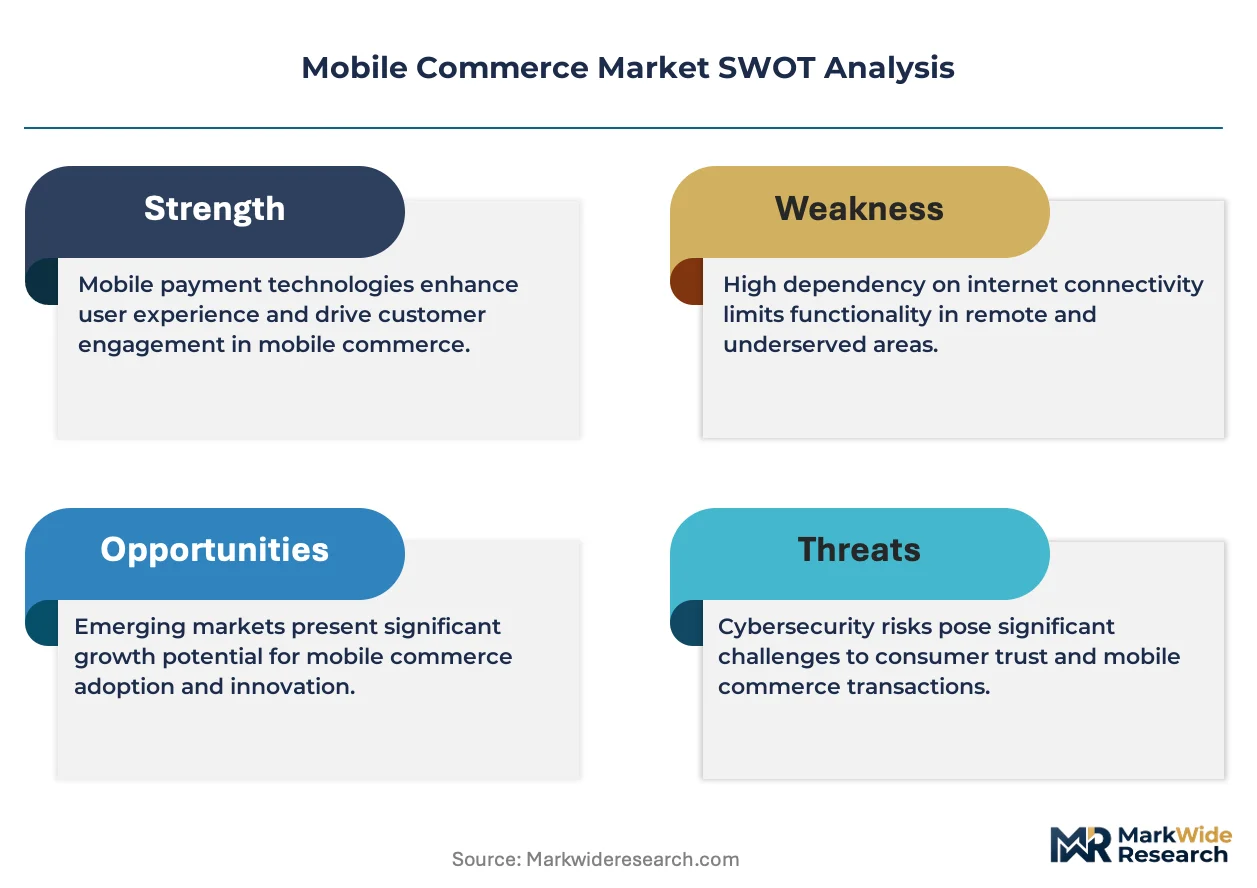
- Tokenization infrastructure concentration:India's RBI-mandated card-on-file tokenization rules create compliance overhead for smaller merchants lacking direct gateway relationships.
- Biometric authentication hardware costs:Fingerprint and facial recognition sensors in budget smartphones remain unevenly distributed across price tiers, creating security fragmentation.
- Super-app platform dependency:Merchants in Asia face revenue concentration risk from Tencent's WeChat Pay and Alipay ecosystems that control discovery, payment, and fulfillment within closed loops.
Strategic Opportunities
- Open banking API convergence:Account-to-account payment initiation layered with embedded lending is displacing card-based checkout in European markets regulated under PSD2.
- Tier-two Indian city merchant digitization:Kirana stores and regional retailers remain underpenetrated by full-stack commerce platforms, creating white space for localized inventory and logistics solutions.
- Buy-now-pay-later regulatory arbitrage:The CFPB's scrutiny of BNPL products in the United States is diverging product development toward interest-bearing installment loans versus merchant-subsidized splits.
Industry Challenges
- Fraud analytics talent scarcity:Device fingerprinting and behavioral biometrics require machine learning engineers with payments-specific risk modeling experience that competes with fintech lending priorities.
- Legacy core banking integration:Real-time balance checks and instant settlement require API connections to batch-oriented mainframe systems that resist modernization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Commerce Market |
| Market Size in 2026 | $785.3 Billion |
| Market Size in 2035 | $3,590.88 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Mobile Websites, Payment Gateways, Digital Wallets Service Type: Order Management, Customer Support, Payment Processing, User Authentication Customer Type: Retail Consumers, Business Enterprises, Freelancers, Service Providers Transaction Type: In-App Purchases, Subscription Services, One-Time Purchases, Peer-to-Peer Transfers |
| Companies Covered | Alphabet Inc., Apple Inc., Amazon.com Inc., Mastercard Inc., Visa Inc., PayPal Holdings Inc., Ant Group Co., Ltd., Tencent Holdings Ltd., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Commerce Market Strategic Shifts & Innovations
Checkout architecture is compressing from multi-step redirects into single-interface embedded flows, with authentication, payment selection, and fulfillment confirmation collapsing into unified mobile experiences.
Progressive web application technology is collapsing the distinction between browser and native app commerce by enabling push notifications, offline functionality, and hardware access without app store distribution. Tier-two Indian merchants are adopting PWAs at three times the rate of standalone native apps due to reduced data consumption and storage requirements. This compression is eliminating the download friction that previously gated merchant discovery and repeat purchase frequency.
The EU's Digital Markets Act interoperability mandates are forcing Apple to open its NFC chip and wallet infrastructure to competing payment applications by 2025. Gatekeeper platforms must now permit third-party wallet apps to access device hardware previously reserved for Apple Pay, eroding the closed-loop advantage that anchored premium interchange rates. European neobanks and retailer wallets are responding by pre-positioning tokenized credential migration tools ahead of enforcement deadlines.
Consumer tolerance for checkout abandonment is compressing purchase completion windows from minutes to seconds across Southeast Asian markets. Super-app interfaces in Indonesia and Vietnam have conditioned buyers to expect one-tap confirmation without password re-entry or redirect pages. This behavioral shift is forcing standalone e-commerce platforms to embed biometric authentication and stored credential tokenization or lose conversion to integrated ecosystem alternatives.
Mobile Commerce Market Segmentation
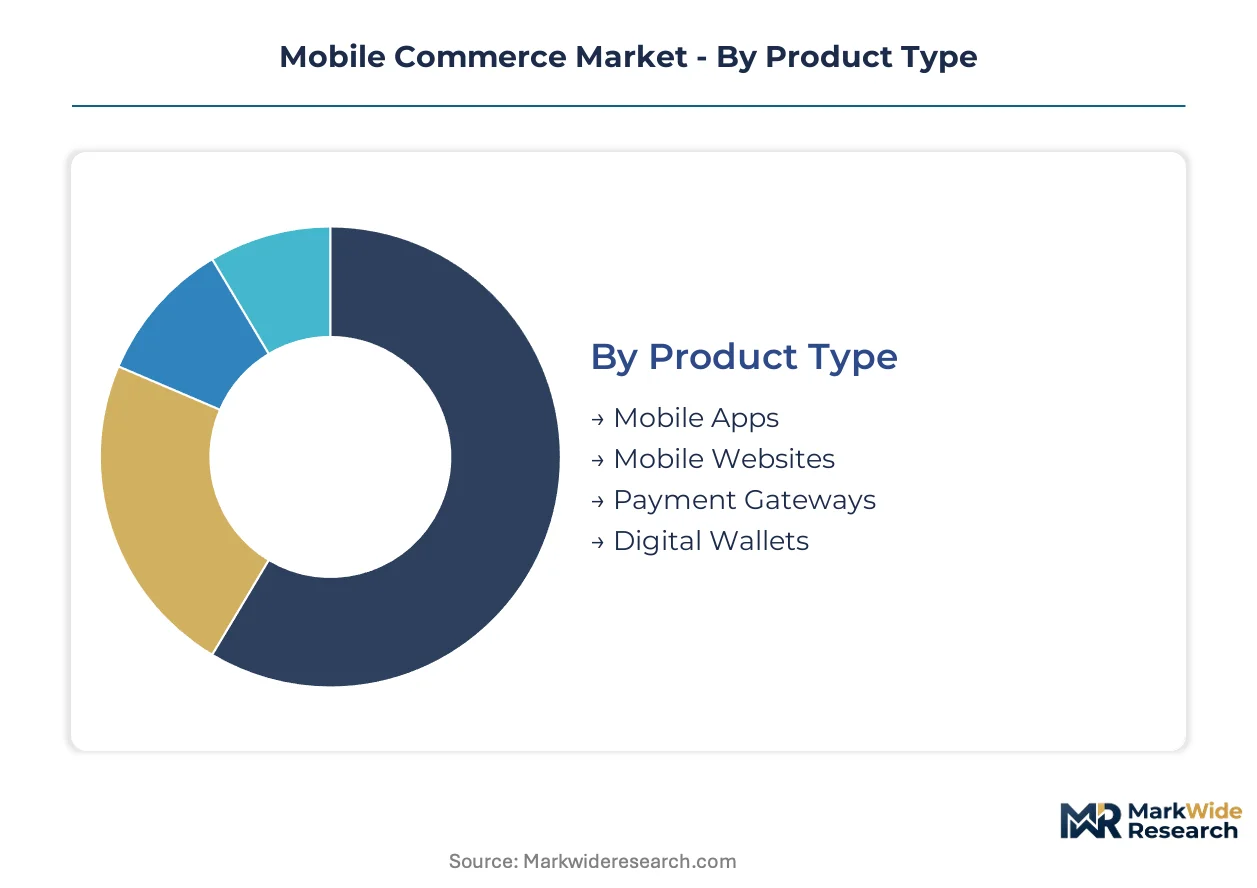
Mobile commerce infrastructure fragments across interface layers, backend services, and transaction modalities. Each segment carries distinct margin profiles and integration complexity that shape vendor competitive positioning.
Product Type:
After-sales service intensity varies sharply across interface technologies, with payment infrastructure demanding continuous compliance updates and security patching.
- Mobile Apps:Native applications compiled for iOS and Android operating systems with deep hardware integration for biometric authentication and push notifications. Demand concentrates among large retailers in India seeking direct customer relationships outside super-app ecosystems, though app store commission structures erode merchant margins.
- Digital Wallets:Tokenized credential storage systems enabling one-tap checkout with embedded loyalty and identity verification layers. India's UPI-linked wallets are capturing merchant onboarding volume fastest in tier-two and tier-three cities where banked populations first encounter smartphone-native payments.
- Mobile Websites:Browser-rendered commerce interfaces requiring responsive design frameworks and cross-device compatibility testing.
- Payment Gateways:API middleware routing encrypted transaction data between merchant systems and acquiring banks.
By volume, Mobile Apps leads. By growth pace, Digital Wallets is climbing the fastest.
Service Type:
Cost tier stratification separates commodity transaction processing from high-margin fraud prevention and identity services.
- Payment Processing:Real-time authorization, settlement, and reconciliation services managing fund flows across card networks and real-time payment rails. Brazil's Pix and India's UPI are displacing traditional four-party card schemes with instant account-to-account transfers that compress merchant working capital cycles.
- User Authentication:Multi-factor identity verification combining device fingerprinting, behavioral biometrics, and tokenized credentials. European neobanks are embedding Strong Customer Authentication flows ahead of PSD3 implementation, driving demand for FIDO2-compliant solutions.
- Order Management:Inventory synchronization, fulfillment orchestration, and returns processing across distributed warehouse networks.
- Customer Support:Chatbot interfaces, dispute resolution workflows, and chargeback management services.
By revenue concentration, Payment Processing dominates. By margin expansion, User Authentication is gaining share fastest.
Customer Type:
Application context determines feature requirements, with enterprise deployments demanding API customization and consumer segments prioritizing interface simplicity.
- Retail Consumers:Individual purchasers conducting product discovery, comparison, and checkout through smartphone interfaces. India's tier-two city populations are migrating from cash-on-delivery to prepaid digital transactions as UPI penetration deepens.
- Business Enterprises:Corporate procurement teams managing supplier payments, expense reconciliation, and treasury operations through mobile dashboards. Mid-market firms in Southeast Asia are adopting embedded corporate cards with real-time spend controls.
- Freelancers:Independent professionals invoicing clients and receiving cross-border payments through mobile-first platforms.
- Service Providers:Gig economy platforms and marketplace sellers managing storefront operations and customer relationships.
By transaction count, Retail Consumers leads. By revenue per user, Business Enterprises is expanding most quickly.
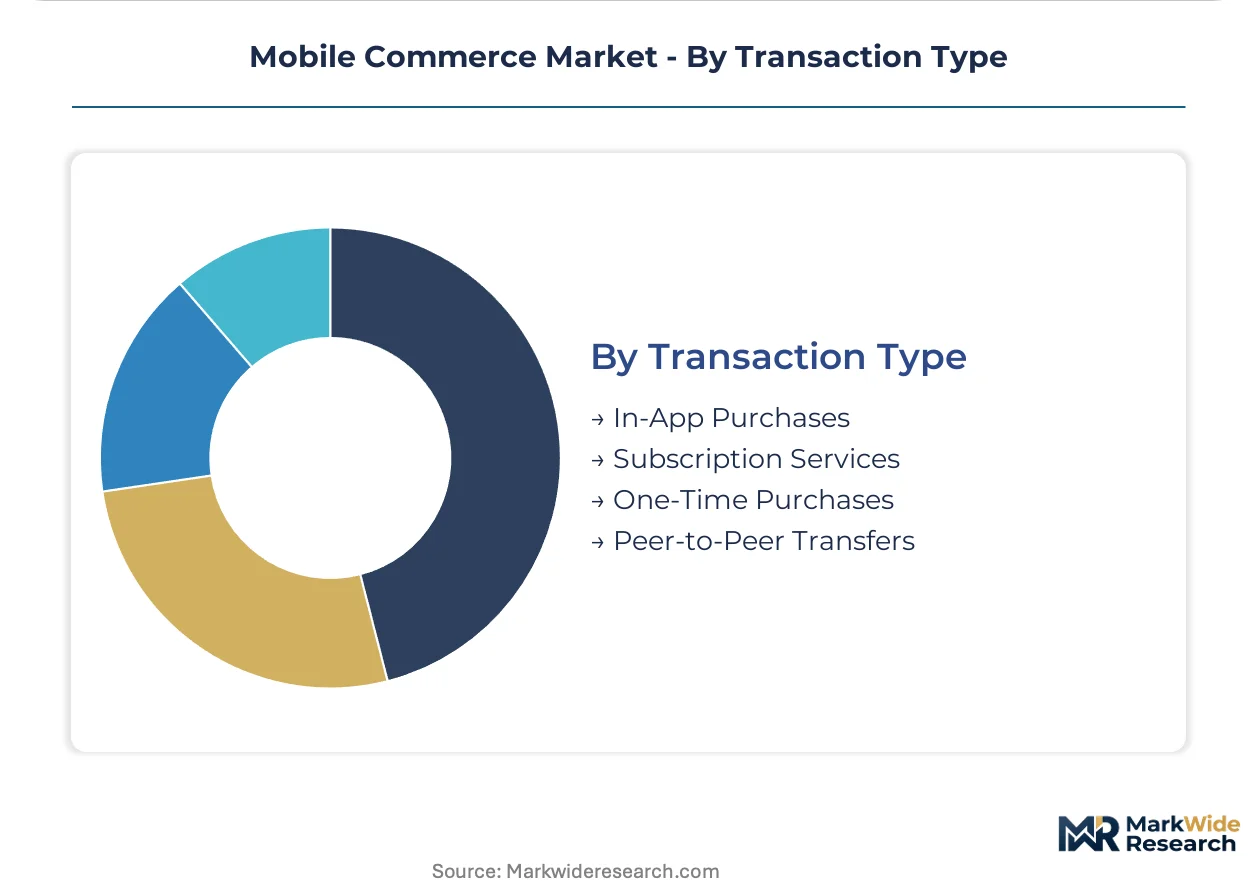
Transaction Type:
Maturity gradients separate established one-time purchase flows from emerging subscription and peer-to-peer modalities with distinct regulatory treatment.
- In-App Purchases:Digital goods and content transactions executed within native applications, bypassing web checkout entirely. Game developers and streaming platforms in Asia are optimizing for super-app mini-program environments where discovery and payment collapse into single interfaces.
- Subscription Services:Recurring billing arrangements with stored credential tokenization and automated renewal management. The US CFPB's scrutiny of dark patterns in subscription cancellation flows is forcing merchants to implement frictionless opt-out mechanisms.
- One-Time Purchases:Single-transaction commerce with guest checkout options and minimal account creation requirements.
- Peer-to-Peer Transfers:Individual-to-individual fund movements through mobile number or QR code identification.
By gross merchandise value, One-Time Purchases leads. By growth trajectory, In-App Purchases is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade surpluses in mobile payment infrastructure components flow from East Asian manufacturing clusters toward deficit markets in South Asia and Latin America. India's electronics import bill for smartphones and components shapes regional capital allocation. Brazil's fintech export of Pix protocol licensing reverses traditional technology trade patterns with Europe.
India
Tier-two and tier-three cities drive merchant onboarding as UPI penetration deepens beyond metropolitan centers. The RBI enforces card-on-file tokenization rules that reshape wallet provider compliance architectures. Bangalore's fintech corridor hosts payment gateway startups building for Bharat-level merchants in Indore, Lucknow, and Coimbatore.
United States
Buy-now-pay-later adoption concentrates in suburban retail corridors where mobile checkout displaces in-store card swipes. The CFPB scrutinizes embedded lending products for consumer protection violations. Seattle's logistics-tech cluster anchors same-day delivery expectations that propagate through merchant mobile interfaces nationwide.
China
Super-app commerce volume concentrates in provincial manufacturing cities where WeChat Pay and Alipay mini-programs replace standalone retail apps. SAMR enforces anti-monopoly provisions against platform exclusivity in merchant contracts. Shenzhen's hardware ecosystem supplies biometric sensors and secure elements for wallet-enabled devices across Southeast Asian export markets.
Brazil
Pix instant payment rails displace card-based checkout in São Paulo's retail corridors and Recife's merchant corridors alike. The central bank mandates open banking APIs that enable account-to-account payment initiation. Curitiba's fintech cluster develops white-label wallet infrastructure licensed to Colombian and Mexican banking partners.
Germany
Open banking API adoption accelerates as PSD2 Strong Customer Authentication matures into embedded checkout flows. The Bundesbank supervises real-time payment rail integration with European neobank wallets. Berlin's SaaS corridor hosts checkout infrastructure providers serving Dutch and French merchant expansions.
Mobile Commerce Market Key Industry Players
On the supply side, the industry is bifurcating between closed-loop platform operators and open-architecture infrastructure providers. Payment networks and cloud hyperscalers occupy distinct tiers with limited direct overlap. Strategic archetypes include super-app ecosystems, card network tokenization services, and merchant-facing checkout SDK platforms. Consolidation pressures concentrate among gateway providers as real-time payment rails commoditize routing infrastructure.
Within the technology platform tier, Alphabet Inc. and Apple Inc. occupy positions that exemplify contrasting architectural philosophies around browser-based versus native app commerce. Amazon.com Inc. anchors fulfillment-integrated checkout expectations that competitors must match or bypass. These three entities represent the dominant competitive anchors against which regional wallet providers and neobank interfaces define differentiation strategies.
| Leading Market Players |
|---|
| Alphabet Inc. |
| Apple Inc. |
| Amazon.com Inc. |
| Mastercard Inc. |
| Visa Inc. |
| PayPal Holdings Inc. |
| Ant Group Co., Ltd. |
| Tencent Holdings Ltd. |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Shenzhen's hardware manufacturing cluster anchors secure element and biometric sensor production, concentrating component supply leverage among wallet-enabled device suppliers and compressing margins for downstream payment gateway providers competing on transaction routing fees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates full-stack platform providers from modular SDK vendors and commodity gateway resellers. Price differentiation centers on fraud analytics sophistication and tokenization certification grade, with RBI-mandated compliance tiers in India creating additional stratification. Cost compression in the economy tier is intensifying because progressive web application technology eliminates app store distribution overhead. Tier-two Indian merchants exhibit highest price sensitivity, while Southeast Asian super-app ecosystems demonstrate lowest sensitivity due to revenue concentration risk tolerance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates semiconductor component sourcing decisions for secure enclaves and NFC controllers. Manufacturing concentrates in Taiwan, South Korea, and Vietnam for advanced chip fabrication and assembly operations. Raw material dependencies include rare earth elements for magnetometers, gallium arsenide for RF components, and high-purity silicon substrates. Single-source vulnerability persists for cryptographic processor IP cores licensed from UK and Israeli design houses. Distribution runs through EMS providers in Malaysia and Mexico serving regional fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time payment rails threaten to disintermediate card-based transaction economics, forcing incumbents to defend merchant relationships against account-to-account substitution before infrastructure investments harden around legacy architectures.
For Market Incumbents: Entrench merchant lock-in through embedded lending products and inventory financing tools that deepen switching costs beyond payment routing alone. Vertical integration into fraud analytics talent pools addresses scarcity in machine learning engineers with payments-specific risk modeling expertise. Defend against open banking API convergence by pre-positioning tokenized credential migration tools ahead of regulatory enforcement deadlines in European markets.
For New Entrants and Emerging Players: Build out localized PWA-based checkout infrastructure for India's tier-two kirana store segment, where full-stack commerce platforms remain underpenetrated and UPI-linked wallet adoption accelerates fastest. Target white-label wallet infrastructure licensing to Latin American banking partners seeking Pix-compatible technology transfer. Lead with merchant onboarding friction reduction rather than competing on interchange rates.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors checkout SDK platforms with embedded authentication layers over standalone gateway providers facing commoditization pressure from real-time payment rails. Long-term viability across the next decade rests on owning the identity verification stack rather than transaction volume alone. The signal to watch is central bank digital currency pilot programs that could reshape wallet provider economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Progressive Web Application Deployment | PWAs reduce merchant onboarding friction by eliminating app store compliance overhead in India's tier-two cities. |
| Biometric Authentication Integration | Embedded FIDO2-compliant flows address PSD3 requirements while compressing checkout abandonment windows in Southeast Asia. |
| Real-Time Payment Rail Connectivity | UPI and Pix integration displaces card network dependency while compressing merchant working capital cycles. |
| Fraud Analytics Capability Buildout | Behavioral biometrics and device fingerprinting differentiate platform offerings as gateway routing commoditizes. |
| Tokenization Infrastructure Investment | RBI-mandated card-on-file rules create compliance moats for providers with direct gateway relationships. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, payment network disclosure documents, and central bank policy circulars. Primary interviews engaged mobile commerce platform executives, merchant acquisition leads at digital wallet providers, payment gateway technical architects, and regulatory compliance officers at tier-one Indian banks. Secondary validation drew from RBI circulars on tokenization, UPI transaction volume disclosures, EU Digital Markets Act implementation guidance, and SEC filings from publicly traded payment networks. Bottom-up merchant onboarding estimates triangulate against top-down payment rail transaction data.
Forecast inputs include interface technology adoption curves, real-time payment rail penetration rates, and merchant digitization indices across emerging market city tiers. Segmentation modeling spans product type, service tier, customer archetype, and transaction modality dimensions across the projection horizon. CAGRs derive from S-curve technology adoption patterns applied to smartphone penetration trajectories and digital wallet activation rates. Industry-specific inputs incorporate PLI scheme handset production targets and central bank digital currency pilot timelines.
Stress conditions across regulatory enforcement intensity, merchant acquisition cost inflation, and super-app ecosystem expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about payment rail interoperability timelines and biometric hardware cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Resale E-Commerce Platform Market
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
ASEAN E-Commerce Logistics Market
E-Commerce Solutions
Social Commerce Market
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
Global Omnichannel Retail Commerce Platform Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Slovakia E-Commerce Market