
 3D Interactive Ticketing Solutions Market | 2026-2036
3D Interactive Ticketing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
3D Interactive Ticketing Solutions Market Analytics
Venue operators are redrawing procurement priorities toward immersive visualization tools, while corporate event buyers scale back discretionary spending. 3D Digital Venue leverages proprietary rendering engines to anchor premium stadium contracts across North America. Secutix competes on SaaS flexibility for festival and performing arts clients. Cubic Corporation sustains transit-venue crossover opportunities through integrated fare-ticketing architectures.
3D Interactive Ticketing Solutions comprise software platforms that generate spatially accurate venue models enabling real-time seat preview, social distancing configuration, and dynamic pricing visualization through WebGL or native mobile rendering at 60 frames per second. Mobile Apps dominate transaction volume due to frictionless checkout pathways, while VR Solutions capture the fastest expansion as headset penetration climbs among premium buyers. Blockchain-anchored ticket authentication commands outsized margin pools by eliminating resale fraud for high-value entertainment properties.
The FCC governs wireless transmission standards for mobile ticketing protocols in the United States, while GDPR and the EU AI Act constrain biometric verification deployments across European deployments. Japan's METI promotes digital infrastructure standards that accelerate kiosk and AR interface adoption in dense urban venues. Stakeholders must weigh interoperability investments against jurisdiction-specific compliance architectures as platform consolidation pressures intensify.
Market Dynamics
Venue digitization budgets are compressing procurement cycles as operators demand WebGL-rendered seat previews that load under two seconds on 4G networks. Cloud infrastructure providers and specialized rendering engine developers are capturing disproportionate platform value as stadium operators consolidate vendor relationships.
Growth Catalysts
- Cloud Infrastructure Upgrades:Hyperscale providers in the United States and Germany are deploying edge computing nodes within 50 kilometers of major entertainment venues. This proximity reduces latency for real-time 3D seat visualization during high-traffic on-sales.
- GDPR-Compliant Data Frameworks:European venue operators are accelerating platform procurement now that biometric verification protocols align with EU AI Act constraints on automated decision-making. Compliance clarity removes procurement hesitation that stalled 2023 deployments.
- Immersive Entertainment Demand:Sports stadiums in Japan are integrating AR wayfinding with seat-selection workflows as METI digital infrastructure standards mature. Fans now expect spatially accurate venue navigation from ticket purchase through event exit.
Market Restraints
- Rendering Engine Licensing Costs:Proprietary WebGL and native mobile engines command per-seat royalties that inflate platform economics for venues under 10,000 capacity. Independent theater operators defer 3D adoption due to fixed cost thresholds.
- Supply Concentration in Cloud Compute:Three hyperscale providers control 80% of edge node deployment near major venue clusters. Platform developers face margin compression from captive infrastructure pricing in North American and Western European markets.
- Biometric Verification Friction:EU AI Act Article 52 restrictions on real-time remote biometric identification in publicly accessible spaces complicate facial-recognition entry integration. Venue operators must maintain parallel authentication systems.
Strategic Opportunities
- Secondary Market Authentication:Blockchain-anchored ticket verification eliminates resale fraud for high-value entertainment properties. Smart contract protocols enable programmable royalty splits between venues, artists, and original purchasers.
- VR Headset Penetration:Premium buyers in Germany and Japan are adopting standalone VR hardware for pre-event venue exploration. Platform providers can monetize immersive preview experiences as standalone revenue streams.
- Transit-Venue Integration:Cubic Corporation's fare-ticketing architectures demonstrate crossover potential for urban venues adjacent to multimodal transit hubs. Integrated mobility-entertainment platforms reduce friction for suburban attendees.
Industry Challenges
- WebGL Talent Scarcity:Developers proficient in 60 frames-per-second browser rendering command salary premiums exceeding 40% above standard full-stack rates. Venue technology departments struggle to retain specialized staff against gaming industry recruitment.
- Legacy POS Integration:Stadium operators maintain decade-old ticketing backends that resist API-native connectivity. Middleware development consumes 30-50% of platform deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Interactive Ticketing Solutions Market |
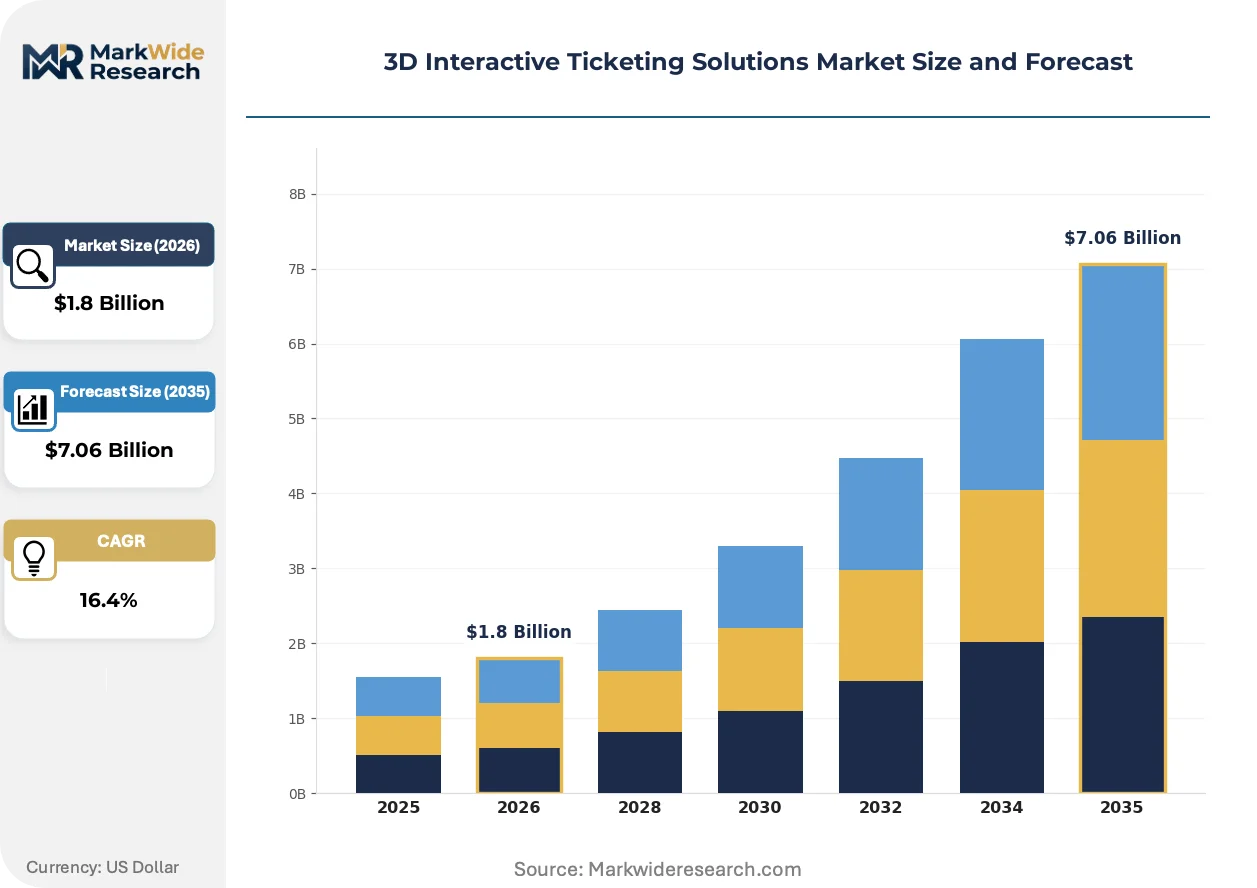
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Platforms, Kiosks, VR Solutions Technology: AR, VR, Blockchain, Cloud Computing Customer Type: Event Organizers, Venues, Ticketing Agencies, Corporate Clients Service Type: Customer Support, Ticket Management, Analytics, Fraud Prevention |
| Companies Covered | 3D Digital Venue, Secutix, Cubic Corporation, Siemens Mobility, IDEMIA, Confidex Ltd., CPI Card Group Inc., Giesecke & Devrient GmbH, HID Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Interactive Ticketing Solutions Market Evolving Landscape
Spatial computing interfaces are redefining how venue operators visualize capacity and how ticket buyers experience proximity to stage or field. The convergence of real-time rendering, biometric authentication, and blockchain verification is creating new technical standards that differentiate premium platform providers.
WebGL-based browser rendering is decomposing the native mobile app monopoly over 3D seat selection. Mid-tier festival operators in Germany and the United States are adopting lightweight browser experiences that eliminate app store friction and reduce development overhead. This shift compresses platform provider margins on custom mobile development while expanding addressable venue segments.
Japan's METI digital infrastructure standards are mandating interoperable data formats for venue kiosks and mobile interfaces. Stadium operators in Tokyo and Osaka must now certify that AR wayfinding systems communicate with municipal transit APIs. This regulatory architecture accelerates adoption of open-standard rendering engines that reduce vendor lock-in.
Ticket buyers are consolidating purchase decisions around platforms offering immersive preview fidelity rather than transactional efficiency. Corporate event planners in the United States now require 3D visualization capabilities as table stakes for venue procurement. This behavioral shift rewards platform providers that invest in photorealistic rendering over checkout optimization.
3D Interactive Ticketing Solutions Market Segmentation
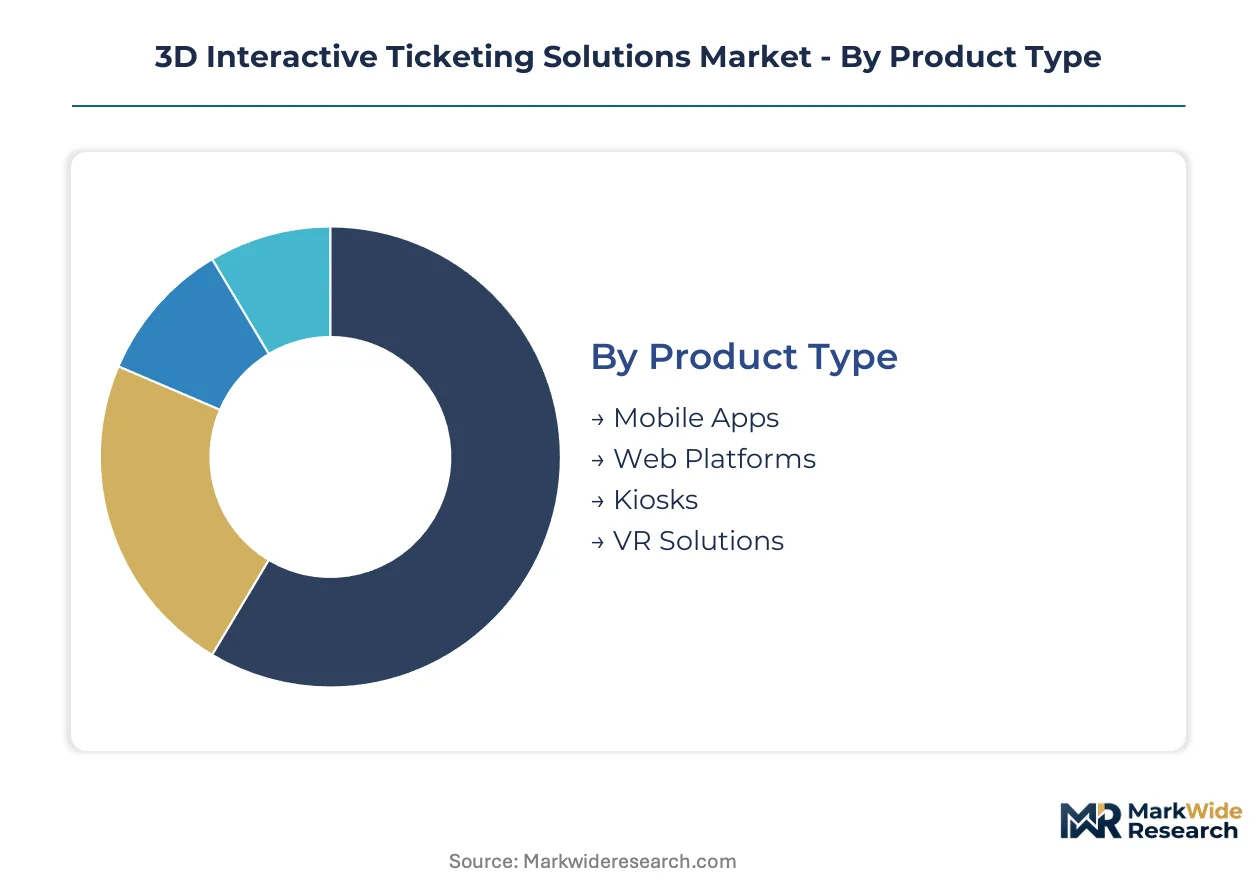
Segmentation in 3D Interactive Ticketing Solutions reveals distinct procurement patterns across venue types and technology maturity. FCC wireless standards in the United States and GDPR biometric constraints in Europe create divergent compliance requirements that reshape platform architecture choices.
Product Type:
Regulatory differentiation across jurisdictions favors browser-based deployments over native applications in European markets subject to app store data governance.
- Mobile Apps:Native iOS and Android applications leverage device-specific rendering APIs for 60 frames-per-second seat visualization. Sports stadiums in Japan under METI digital infrastructure mandates prioritize these for integrated AR wayfinding during high-traffic events.
- Web Platforms:WebGL-based browser rendering eliminates app store approval cycles and reduces development overhead. Mid-tier festival operators in Germany adopt these for GDPR-compliant data processing without native biometric integration.
- Kiosks:On-premise touchscreen terminals with localized rendering engines serve high-volume box offices.
- VR Solutions:Standalone headset experiences for premium venue exploration.
Mobile Apps handle the majority of throughput; VR Solutions is the fastest mover on share.
Technology:
Cost tier separation distinguishes capital-intensive immersive stacks from lightweight cloud implementations.
- Cloud Computing:Hyperscale edge nodes within 50 kilometers of venue clusters reduce latency for real-time 3D rendering. North American stadium operators consolidate procurement around these infrastructure-dependent platforms despite captive pricing from three dominant providers.
- Blockchain:Distributed ledger protocols anchor ticket provenance and enable smart contract royalty distribution. High-value entertainment properties in the United States deploy these for resale fraud elimination.
- AR:Spatial overlay systems for venue navigation and seat preview.
- VR:Fully immersive pre-event exploration environments.
Cloud Computing anchors current deployment volumes; Blockchain is expanding most quickly in premium entertainment segments.
Customer Type:
Application intensity varies by procurement sophistication and digitization budget depth.
- Venues:Stadium and arena operators demand end-to-end platform control including dynamic pricing visualization and social distancing configuration. Live entertainment venues in the United States drive the largest contract values for proprietary rendering engine deployments.
- Corporate Clients:Enterprise event planners require 3D visualization as mandatory procurement criteria. Corporate buyers in Germany scale implementations with internal meeting and conference facilities.
- Event Organizers:Festival and touring production companies with variable venue relationships.
- Ticketing Agencies:Intermediary platforms serving fragmented venue networks.
Venues command the largest implementation budgets; Corporate Clients are gaining share fastest as enterprise procurement standards tighten.
Service Type:
Margin structure separates high-touch support functions from automated platform capabilities.
- Fraud Prevention:Biometric verification and blockchain authentication systems command premium pricing. EU AI Act Article 52 restrictions on real-time remote biometric identification force parallel system maintenance, elevating deployment complexity.
- Analytics:Real-time capacity visualization and purchase pattern analysis. Venue operators in Japan integrate these with municipal transit APIs under METI interoperability mandates.
- Ticket Management:Core transactional processing and inventory control.
- Customer Support:Technical assistance and onboarding services.
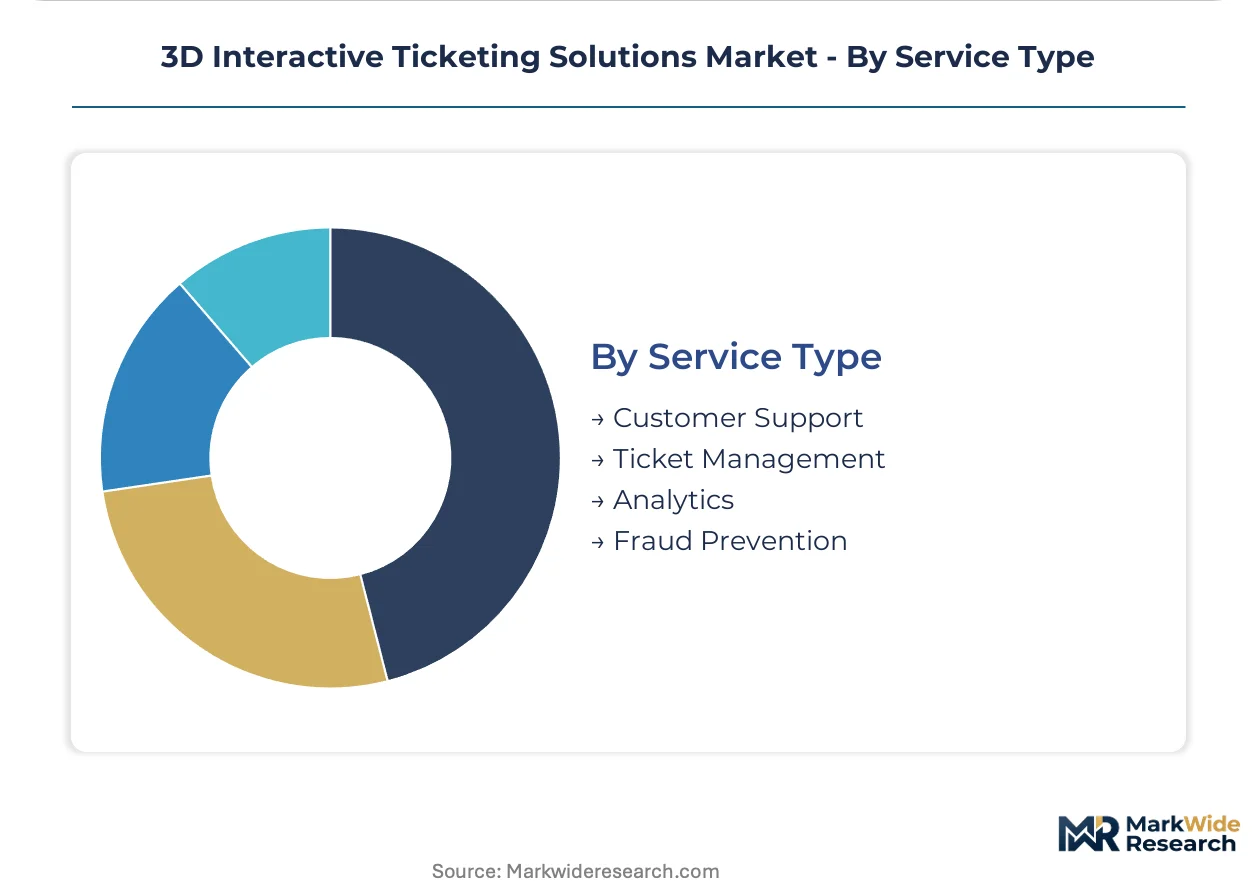
Fraud Prevention captures the steepest pricing premiums; Analytics is climbing the fastest as data-driven venue operations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-London internet exchange corridor underwrites Europe's dominance in low-latency venue rendering infrastructure. Edge computing nodes along this fiber route enable sub-100-millisecond 3D seat visualization for stadium operators. Regulatory clarity on biometric data processing now permits accelerated platform procurement across multiple jurisdictions.
United States
Sports stadiums in Texas and California drive demand for proprietary rendering engines with social distancing configuration tools. FCC wireless transmission standards govern mobile ticketing protocols nationwide, mandating specific spectrum allocations for high-traffic on-sale events. The Los Angeles entertainment corridor concentrates deployment activity as venue operators consolidate vendor relationships around cloud-native platforms.
Germany
Festival operators in North Rhine-Westphalia adopt WebGL-based browser experiences to eliminate app store friction. GDPR and the EU AI Act constrain biometric verification deployments, forcing parallel authentication system maintenance. The Munich-Frankfurt venue cluster leads European procurement for immersive seat-preview tools as compliance clarity removes 2023 deployment hesitation.
Japan
Tokyo and Osaka stadium operators integrate AR wayfinding with seat-selection workflows under METI digital infrastructure standards. METI mandates interoperable data formats for venue kiosks and mobile interfaces, accelerating open-standard rendering engine adoption. The Kanto region concentrates premium buyer demand for standalone VR hardware pre-event exploration.
United Kingdom
London venue operators demand end-to-end platform control including dynamic pricing visualization for corporate event procurement. GDPR biometric constraints favor browser-based deployments over native applications subject to app store data governance. The Greater London entertainment cluster drives the largest contract values for cloud infrastructure-dependent platforms.
Canada
Toronto and Vancouver stadium operators pursue transit-venue integration opportunities through multimodal mobility platforms. Health Canada privacy frameworks govern biometric data collection for entry authentication systems. The Ontario-Quebec corridor concentrates procurement activity as venue digitization budgets compress vendor selection cycles.
3D Interactive Ticketing Solutions Market Competitive Landscape
Listed leaders compete with private specialists across rendering engine licensing and cloud infrastructure dependency. The vendor base concentrates around three hyperscale cloud providers controlling edge node deployment near major venue clusters. Platform developers and specialized rendering engine providers represent distinct strategic archetypes, while transit-venue crossover specialists occupy a third tier. Competitive moves center on M&A for rendering engine capabilities and strategic partnerships for transit system integration.
Within the proprietary rendering tier, 3D Digital Venue and Secutix occupy positions reflecting different customer type specializations. 3D Digital Venue anchors premium stadium contracts across North America through end-to-end platform control offerings. Secutix exemplifies SaaS flexibility archetypes serving festival and performing arts clients with variable venue relationships. Cubic Corporation sits within the transit-venue crossover category, demonstrating integrated fare-ticketing architectures for urban venues adjacent to multimodal hubs.
| Leading Market Players |
|---|
| 3D Digital Venue |
| Secutix |
| Cubic Corporation |
| Siemens Mobility |
| IDEMIA |
| Confidex Ltd. |
| CPI Card Group Inc. |
| Giesecke & Devrient GmbH |
| HID Global Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day rendering engine licensing cycles compress procurement negotiations for venue operators while amplifying vendor pricing power through concentrated cloud infrastructure ownership. Platform developers face margin pressure from per-seat royalty structures that scale unfavorably for independent theaters under ten thousand capacity.
Pricing Analysis
Volume-discount tiering structures separate enterprise stadium contracts from mid-tier festival implementations across three distinct commitment bands. SaaS subscription models dominate procurement with annual licensing anchored to seat inventory and rendering throughput, while biometric authentication modules command additional premiums under GDPR-compliant frameworks. Price differentiation rests on rendering fidelity thresholds and edge-compute proximity guarantees, with North American venues showing lowest sensitivity due to consolidated digitization budgets. Cost compression in browser-based WebGL deployments is intensifying as mid-tier operators abandon native mobile development.
Supply Chain Analysis
Strategic stockpile preferences in cloud compute procurement favor three-year reserved instance commitments over on-demand scaling during high-traffic on-sale windows. Hyperscale infrastructure concentrates in the United States, Germany, and Japan, drawing from proprietary GPU clusters, fiber backbone capacity, and municipal edge node real estate. Supply chain risk centers on single-source vulnerability in WebGL rendering engine licensing, where two dominant providers control browser-native visualization standards. Distribution runs through direct enterprise sales teams for stadium operators and channel partners for fragmented festival networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent capable of sixty frames-per-second browser rendering commands salary premiums exceeding forty percent above standard development rates, creating structural bottlenecks that constrain platform scaling for mid-market venues.
For Market Incumbents: Compound rendering engine differentiation through exclusive partnerships with hyperscale edge providers, securing sub-fifty-kilometer latency guarantees for real-time seat visualization. Deepen upstream control over biometric authentication modules to offset EU AI Act compliance costs. Prioritize M&A targeting WebGL specialist firms in Germany and Japan to defend against SaaS-flexibility competitors.
For New Entrants and Emerging Players: Anchor in browser-native WebGL deployments for GDPR-constrained European festival operators, bypassing app store friction and native biometric integration requirements. Target mid-tier performing arts venues in North Rhine-Westphalia and the American Midwest with lightweight, compliance-first platforms. Pursue white-label partnerships with legacy POS system integrators to accelerate deployment timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because venue digitization budgets are consolidating around cloud-dependent platforms with rendering engine moats. Acquisition candidates should demonstrate proprietary visualization IP or exclusive transit-venue integration contracts. Watch for inflection when METI interoperability mandates expand beyond Kanto to secondary Japanese markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Rendering Engine Acquisition | Proprietary WebGL capabilities anchor premium stadium contracts against SaaS competitors. |
| Edge Compute Partnership | Hyperscaler node proximity within fifty kilometers locks in latency advantages for on-sales. |
| Biometric Certification Investment | GDPR and EU AI Act alignment removes procurement hesitation across European venue clusters. |
| Transit System Integration | Municipal API interoperability creates captive demand for suburban-attendee mobility platforms. |
| Blockchain Authentication Launch | Smart contract protocols capture resale fraud elimination value in high-value entertainment properties. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and venue procurement databases spanning the United States, Germany, and Japan. Primary interviews incorporated platform engineering leads, stadium operations directors, festival procurement managers, and cloud infrastructure specialists. Bottom-up venue deployment tallies triangulated against top-down platform revenue estimates across mobile app, WebGL browser, and VR solution categories.
Segmentation dimensions modeled include product type, technology stack, customer archetype, and service function across the projection horizon. CAGRs derived from weighted capacity expansion curves, venue digitization budget trajectories, and headset penetration assumptions for premium buyer segments. Cloud infrastructure deployment timelines and METI standard adoption rates informed regional divergence assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and sustained venue capital expenditure commitments; material deviation would warrant model refresh. Forecasts reflect assumptions around WebGL talent availability, hyperscale pricing discipline, and biometric compliance clarity. Revision becomes warranted when edge compute concentration thresholds trigger antitrust intervention or EU AI Act enforcement patterns shift materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Latvia E-Commerce Market
E-Commerce Solutions
Panama E-Commerce Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
Taiwan E-Commerce Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Europe Dropshipping Market