
 Indonesia CRM Software Market | 2026-2036
Indonesia CRM Software Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia CRM Software Market Insights
API-first architecture is fragmenting legacy CRM monoliths into composable service layers across Indonesian enterprises. SAP SE anchors large-scale manufacturing deployments with deep ERP integration, while Salesforce Inc. competes through its AppExchange ecosystem tailored to Southeast Asian workflows. HashMicro differentiates by offering Bahasa Indonesia-native interfaces and localized tax compliance modules.
Indonesia CRM software comprises modular applications that centralize customer interaction data, automate sales pipelines, and orchestrate marketing campaigns through cloud-native or on-premise infrastructure. The platform typically integrates with enterprise resource planning systems via REST APIs and supports real-time analytics dashboards for pipeline forecasting. Cloud-based deployment leads adoption among Jakarta-headquartered enterprises seeking elastic scalability without capital expenditure, while sales automation captures the largest solution-level margin pool due to its direct revenue-attachment metrics. Customer support modules are gaining traction among e-commerce platforms managing high-volume ticket resolution across the archipelago.
BSSN, the national cybersecurity agency, enforces data localization standards that shape vendor infrastructure decisions, while the Ministry of Communication and Informatics administers UU PDP compliance timelines affecting product roadmaps. The Financial Services Authority requires audit trails for customer-facing digital channels, tightening CRM specifications for banking and insurance adopters. Stakeholders must evaluate whether hybrid deployment architectures or full cloud migration better align with evolving cross-sector data sovereignty enforcement.

Market Dynamics
API-first architectures are fragmenting legacy CRM monoliths into composable service layers, forcing Indonesian enterprises to rebuild integration stacks around microservices rather than monolithic suites. This structural decomposition is redistributing vendor power toward specialized module providers and away from integrated suite incumbents.
Growth Catalysts
- UU PDP Compliance Mandate:Indonesia's Personal Data Protection Law compels organizations to deploy localized data residency architectures, creating replacement demand for cloud-native CRM platforms with sovereign infrastructure.
- Digital Onboarding Workflows:Indonesian banks and fintech lenders are expanding CRM deployments to manage KYC automation and loan origination pipelines, attaching revenue metrics directly to platform ROI.
- Jakarta-Surabaya Enterprise Corridor:Concentrated demand from manufacturing mid-markets in Surabaya and enterprise headquarters in Jakarta generates scalable reference architectures for vendor expansion.
Market Restraints
- Data Localization Infrastructure Costs:BSSN-mandated sovereign hosting requirements impose capital-intensive edge data center deployments that compress SaaS margin structures for foreign vendors.
- Legacy ERP Integration Friction:Deep SAP SE and Oracle installations in Indonesian manufacturing create technical debt that slows CRM replacement cycles and extends sales timelines.
- Talent Scarcity in API Architecture:Shortage of developers skilled in REST API orchestration and microservices design limits enterprise ability to execute composable CRM migrations.
Strategic Opportunities
- Eastern Indonesia Archipelago Expansion:Underpenetrated markets in Makassar and Medan present first-mover advantages for vendors with Bahasa Indonesia-native support and localized implementation partners.
- AI-Enabled Sales Forecasting Convergence:Integration of predictive analytics engines with pipeline management modules creates premium pricing tiers for vendors combining CRM with machine learning capabilities.
- OJK Audit Trail Mandates:Financial Services Authority requirements for customer-facing digital channel documentation tighten CRM specifications, favoring compliant vendors in banking and insurance verticals.
Industry Challenges
- Hybrid Deployment Complexity:Enterprises struggle to architect seamless data flows between on-premise legacy systems and cloud-native CRM modules without violating UU PDP residency rules.
- Localization Timeline Compression:Vendors face compressed product roadmaps to build Bahasa Indonesia interfaces, Indonesian tax compliance modules, and regional payment gateway integrations before compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia CRM Software Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,032.72 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Solution: Sales Automation, Marketing Automation, Customer Support, Analytics End User: Retail, Healthcare, Manufacturing, Financial Services Service Type: Consulting, Integration, Support, Training |
| Companies Covered | SAP SE, Barantum, Salesforce Inc., HashMicro, Mekari Qontak, Microsoft Dynamics 365, Zoho Corporation Pvt. Ltd., Pipedrive OU, Oracle Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia CRM Software Market Trends and Innovations
Composable architecture principles are displacing suite-based procurement patterns across Indonesian enterprises, with buyers assembling best-of-breed modules rather than accepting monolithic vendor bundles. This shift is redistributing competitive advantage toward integration-native specialists.
Low-code workflow builders are rendering obsolete traditional customization dependencies that required vendor professional services for every process adaptation. Mid-market manufacturers in Surabaya are deploying citizen-developed automation layers atop core CRM data models within weeks rather than quarters. This compression is eliminating the services revenue moat that historically protected incumbent suite vendors.
BSSN data localization standards are reshaping infrastructure procurement by mandating sovereign hosting for customer data processing. Foreign SaaS vendors must establish Indonesian edge presence or cede ground to domestic providers with existing local infrastructure. Banking and insurance adopters are prioritizing compliant architectures ahead of feature parity in vendor selection.
Subscription fatigue among Jakarta-headquartered enterprises is fragmenting long-term contract structures into modular annual renewals by functional component. Procurement teams are unbundling sales automation from customer support modules, evaluating each on standalone ROI rather than suite economics. This disaggregation pressures vendors to demonstrate discrete value per module or face churn to specialized alternatives.
Indonesia CRM Software Market Segmentation
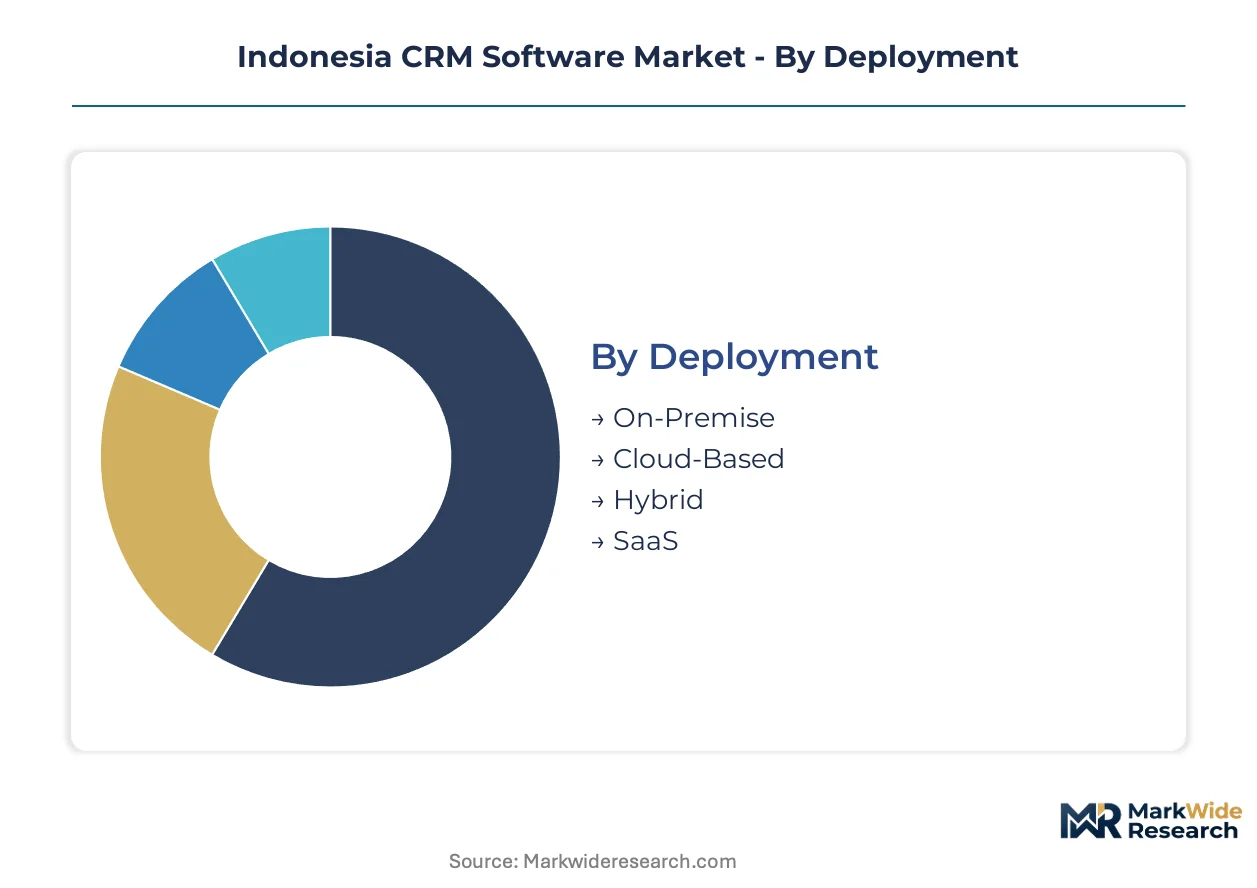
Segmentation in Indonesia's CRM software market reveals divergent procurement rhythms across deployment modes and solution types. Enterprise buyers in Jakarta cycle through cloud migrations faster than Surabaya manufacturers refresh on-premise licenses. Understanding these velocity differences shapes vendor resource allocation and partner network investments.
Deployment:
Cloud-based deployments turn over fastest as Jakarta enterprises pursue elastic scalability without capital expenditure, while on-premise installations exhibit the longest replacement cycles due to deep ERP integration requirements.
- On-Premise:Legacy infrastructure residing within enterprise data centers, requiring dedicated hardware maintenance and internal IT management. Surabaya manufacturing clusters favor this model for air-gapped production environments where BSSN data sovereignty rules intersect with operational continuity needs.
- Cloud-Based:Fully managed SaaS delivery through vendor-operated infrastructure, eliminating capital expenditure and enabling rapid scaling. Jakarta-headquartered banks and fintech lenders prioritize this deployment to accelerate digital onboarding workflows while meeting UU PDP compliance through localized edge presence.
- Hybrid:Architectures splitting sensitive customer data across sovereign local infrastructure and elastic cloud compute layers. Financial services adopters deploy hybrid models to satisfy OJK audit trail mandates while retaining cloud agility for non-regulated functions.
- SaaS:Subscription-native delivery with automatic feature updates and usage-based pricing tiers. Mid-market enterprises across the archipelago favor SaaS for its compressed implementation timelines and reduced dependency on scarce API architecture talent.
On-premise deployments anchor the volume base while cloud-based solutions gain share at the steepest rate.
Solution:
Margin concentration varies sharply across solution modules, with sales automation commanding premium pricing due to direct revenue-attachment metrics while customer support modules compete on volume economics.
- Sales Automation:Pipeline management tools tracking lead progression, opportunity forecasting, and quota attainment. Banking and fintech lenders in Jakarta attach these modules directly to loan origination ROI, justifying higher per-seat pricing through measurable revenue impact.
- Marketing Automation:Campaign orchestration platforms managing multi-channel customer engagement and behavioral segmentation. E-commerce platforms across the archipelago deploy these tools to manage high-velocity promotional cycles during Ramadan and year-end shopping festivals.
- Customer Support:Ticket resolution systems with knowledge base integration and omnichannel routing. High-volume deployment among marketplace operators managing customer inquiries across Indonesia's fragmented logistics networks.
- Analytics:Predictive engines and dashboard visualization for pipeline forecasting and churn prediction. Manufacturing enterprises in Surabaya adopt analytics modules to identify cross-sell opportunities within existing distributor relationships.
Sales automation generates the deepest margin pool while analytics solutions expand most quickly as AI-enabled forecasting capabilities mature.
End User:
Procurement sophistication diverges across verticals, with financial services demanding compliant architectures ahead of feature parity while retail prioritizes rapid deployment velocity.
- Retail:Omnichannel merchants requiring unified customer views across physical stores, marketplaces, and direct-to-consumer channels. Department store chains and fast-fashion operators in Jakarta deploy CRM to synchronize inventory visibility with loyalty program engagement.
- Healthcare:Hospital networks and clinic chains managing patient relationship continuity across referral pathways. Private healthcare groups prioritize CRM modules with UU PDP-compliant consent management for sensitive medical record integration.
- Manufacturing:Industrial producers and distributor networks tracking B2B account hierarchies and complex quotation workflows. Surabaya-based machinery and automotive parts manufacturers anchor this segment with lengthy implementation cycles tied to SAP ERP integration.
- Financial Services:Banks, insurers, and fintech lenders requiring audit-ready customer interaction records. OJK mandates for digital channel documentation tighten CRM specifications, favoring vendors with pre-built compliance frameworks.
Manufacturing anchors current installed base volume while financial services drives replacement demand at the fastest clip.
Service Type:
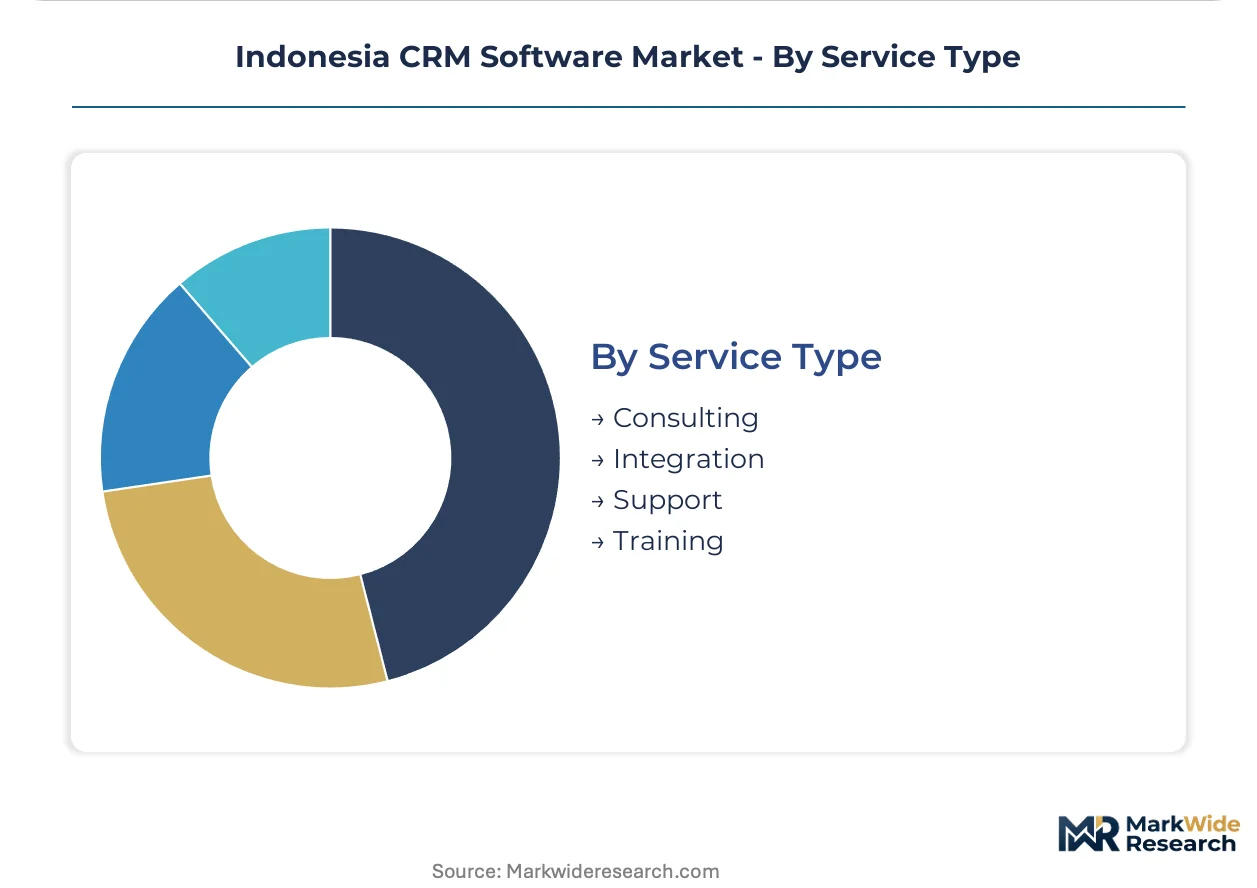
Revenue recurrence patterns separate high-margin recurring support contracts from one-time integration projects that strain professional services capacity.
- Consulting:Strategic advisory for CRM roadmap planning, vendor selection, and change management. Enterprises navigating UU PDP compliance timelines engage consultants to architect hybrid data residency solutions.
- Integration:Technical implementation connecting CRM platforms to legacy ERP, payment gateways, and communication channels. API-first architecture trends are fragmenting integration demand toward specialized microservices providers.
- Support:Ongoing maintenance, troubleshooting, and version upgrade management. Bahasa Indonesia-native support capabilities differentiate domestic implementation partners from foreign vendors.
- Training:End-user enablement and administrator certification programs. Low-code workflow builders are compressing traditional training dependencies as citizen developers assume greater customization autonomy.
Integration services anchor project revenue volume while support contracts gain share fastest as subscription models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in Indonesia CRM software splits sharply between Jakarta's enterprise headquarters and Surabaya's manufacturing mid-markets, with compliance mandates from BSSN and OJK reshaping procurement priorities across both corridors.
Jakarta Metropolitan Area
Jakarta-headquartered banks and fintech lenders drive cloud-native CRM demand for digital onboarding workflows. OJK audit trail mandates tighten platform specifications for customer-facing channels. The Sudirman Central Business District anchors enterprise deployments where SAP SE and Salesforce Inc. compete for large-scale financial services contracts.
Surabaya Manufacturing Belt
Surabaya-based machinery and automotive parts manufacturers favor on-premise CRM tied to legacy ERP systems. UU PDP compliance timelines compress vendor localization roadmaps for Bahasa Indonesia interfaces. The Rungkut industrial zone hosts mid-market clusters where HashMicro and domestic providers capture share through tax compliance modules.
Bandung Tech Corridor
Bandung's emerging startup ecosystem generates SaaS-native CRM demand from e-commerce platforms and logistics aggregators. BSSN data localization standards push foreign vendors toward Indonesian edge infrastructure. The Dago-Setiabudi corridor concentrates venture-backed adopters prioritizing rapid deployment over deep customization.
Makassar Eastern Hub
Makassar represents underpenetrated territory where first-mover vendors build localized implementation partner networks. General regional development programs support SME digitization initiatives. The Tanjung Bunga commercial district hosts early adopters among trading companies managing distributor relationships across Sulawesi and Maluku.
Medan Northern Gateway
Medan-based plantation conglomerates and commodity traders deploy CRM for B2B account hierarchy management. UU PDP data residency requirements complicate cross-border data flows with Singapore headquarters. The Medan Industrial Estate anchors manufacturing-linked demand where hybrid deployment architectures satisfy both compliance and cloud agility needs.
Indonesia CRM Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Indonesia's CRM software landscape, creating a tiered structure where integrated suite vendors anchor enterprise accounts while modular specialists penetrate mid-market gaps. The market fragments along deployment architecture lines—cloud-native platforms, legacy on-premise incumbents, and hybrid intermediaries each occupy distinct competitive space. Two strategic archetypes dominate: ERP-anchored suite providers leveraging existing enterprise relationships, and API-first specialists assembling best-of-breed modules. Competitive moves center on localization partnerships for UU PDP compliance and low-code workflow acquisitions to compress implementation timelines.
Within the ERP-anchored tier, SAP SE and Oracle Corp. occupy positions shaped by decades of Indonesian manufacturing integration. HashMicro and Barantum exemplify the localization-native archetype, competing through Bahasa Indonesia-native interfaces and tax compliance modules purpose-built for Indonesian regulatory requirements. These domestic specialists represent the competitive response to BSSN data sovereignty enforcement, anchoring hybrid deployment architectures that foreign SaaS vendors struggle to replicate without local infrastructure investment.
| Leading Market Players |
|---|
| SAP SE |
| Barantum |
| Salesforce Inc. |
| HashMicro |
| Mekari Qontak |
| Microsoft Dynamics 365 |
| Zoho Corporation Pvt. Ltd. |
| Pipedrive OU |
| Oracle Corp. |
| Others |
Pricing and Supply Chain Analysis
Jakarta's cloud infrastructure cluster concentrates SaaS delivery capacity for CRM platforms, with localized edge data center investments by foreign vendors translating into downstream pricing power compression for enterprise subscriptions. BSSN-mandated sovereign hosting requirements feed back into supply chain architecture decisions, forcing hybrid deployment models that reshape cost structures across the Indonesian archipelago.
Pricing Analysis
Cost-plus contracts with annual indexation to local data center operating costs dominate enterprise SaaS agreements, particularly for banking and insurance adopters facing OJK audit trail mandates. Price differentiation rests on Bahasa Indonesia localization depth and UU PDP compliance certification tier, with foreign vendors absorbing margin compression to match domestic providers on tax module integration. Pricing pressure intensifies in the mid-market manufacturing segment as HashMicro and Barantum bundle implementation services at rates below SAP SE's professional services tiers. Jakarta-headquartered financial services buyers exhibit lowest price sensitivity due to direct revenue-attachment metrics, while Surabaya manufacturers negotiate aggressively on per-seat licensing.
Supply Chain Analysis
Export-control restrictions on AI training hardware and advanced semiconductors from US Bureau of Industry and Security regulations limit predictive analytics module deployment for Indonesian CRM vendors. Supply draws from Singapore for cloud infrastructure orchestration, China for hardware assembly, and domestic Indonesian edge facilities for BSSN-compliant data residency. Raw material dependencies center on GPU compute capacity, submarine fiber capacity, and localized power generation for data centers. Single-source vulnerability concentrates in Singapore-Jakarta submarine cable routes, with redundancy gaps across Eastern Indonesia. Distribution runs through systems integrators and implementation partners with Bahasa Indonesia-native support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's CRM software market functions as a defensive-moat arena where regulatory entrenchment around UU PDP compliance and OJK audit mandates creates structural switching costs that protect incumbent positions.
For Market Incumbents: Build data residency moats through BSSN-certified sovereign infrastructure investments that foreign SaaS competitors cannot replicate without multi-year capital deployment. Deepen ERP integration lock-in with SAP SE manufacturing accounts in Surabaya to extend replacement cycle timelines. Counter API-first specialist entrants by acquiring low-code workflow capabilities that compress implementation timelines below independent module assembly economics. For New Entrants and Emerging Players: Build out localized implementation partner networks in Makassar and Medan before foreign vendors establish compliant edge presence, capturing first-mover reference architectures in underpenetrated Eastern Indonesia. Target plantation conglomerates and commodity traders in Medan with hybrid deployment architectures that resolve cross-border data flow friction with Singapore headquarters. Pursue direct sales-to-IT procurement officer relationships in Bandung's venture-backed startup ecosystem, bypassing systems integrator markups that inflate SAP SE and Salesforce Inc. pricing. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because UU PDP compliance timelines and OJK mandate expansion create durable competitive barriers for localization-native vendors. Acquisition targets should cluster around Bahasa Indonesia-native CRM specialists with pre-built tax compliance modules and existing BSSN infrastructure relationships. Watch BSSN enforcement intensity against foreign SaaS providers as the inflection signal—accelerated data sovereignty actions would compress exit timelines for non-compliant vendors and inflate domestic specialist valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Localization Partnership Formation | Bahasa Indonesia-native interfaces and tax modules satisfy UU PDP compliance timelines ahead of regulatory deadlines. |
| Hybrid Deployment Architecture | Splitting sensitive data across sovereign local infrastructure and cloud compute satisfies OJK mandates while retaining elasticity. |
| Low-Code Workflow Acquisition | Citizen developer capabilities compress implementation timelines and eliminate professional services dependencies that protect incumbents. |
| Edge Data Center Investment | BSSN-certified sovereign hosting creates defensible infrastructure moats that foreign SaaS vendors cannot replicate rapidly. |
| API-First Platform Integration | Microservices architecture enables best-of-breed module assembly that fragments monolithic suite vendor pricing power. |
Research Methodology
The analysis maps cloud-based, on-premise, hybrid, and SaaS deployment sub-sectors, each validated through CTO interviews, IT procurement officer discussions, systems integrator consultations, and channel partner assessments. Primary fieldwork combined with secondary validation from SEC filings, Indonesian Ministry of Communication and Informatics regulatory disclosures, BSSN compliance bulletins, and OJK circulars established demand-side and supply-side triangulation. Bottom-up sizing of vendor bookings and top-down reconciliation with enterprise IT spending surveys anchored volume estimates.
Assumptions held fixed include UU PDP enforcement timelines, BSSN data localization standards, and OJK audit trail mandate scope, while cloud adoption velocity and API-first architecture penetration were modeled as scenario variables across the analysis window. Segmentation dimensions covered deployment mode, solution module, end-user vertical, and service type, with CAGRs derived from logistic adoption curve fitting against historical replacement cycle data. Forecast inputs incorporated Jakarta-Surabaya enterprise corridor demand concentration and Eastern Indonesia underpenetration patterns.
Stress conditions across UU PDP penalty enforcement intensity, foreign vendor exit scenarios, and API architecture talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance timelines and infrastructure investment commitments. Material shifts in BSSN data sovereignty interpretation or OJK mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Global Customer Experience Management Software Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
Thailand CRM Market
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Global Salesforce CRM Document Generation Software Market
Customer Relationship Management (CRM)
Pharmaceutical Customer Relationship Management (CRM) Software Market
Customer Relationship Management (CRM)
Contact Center Software Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market