
 Europe Automotive E-Commerce Market | 2026-2036
Europe Automotive E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive E-Commerce Market Analytics
Multi-source parts procurement is rebalancing toward platform-centric aggregation as workshops and fleet buyers consolidate supplier relationships through digital channels. Amazon.com, Inc. leverages its fulfillment density to capture recurring maintenance orders across borderless European delivery zones. Autodoc SE anchors its position through specialized catalog depth in OEM-equivalent brake and suspension components. Robert Bosch GmbH competes by extending its authorized dealer network into direct-to-workshop digital portals, narrowing the gap between manufacturer and end-user.
Europe Automotive E-Commerce encompasses digitally transacted vehicle components, accessories, tires, and tools, typically specified by OEM part numbers or aftermarket interchange standards, with fulfillment requiring compatibility verification against vehicle identification numbers and emissions certification classes. The primary commercial purpose is to compress procurement cycles for fragmented automotive aftermarket demand while reducing inventory carrying costs for buyers. Parts and accessories lead transaction volume, though tires command premium logistics complexity due to weight and seasonal demand spikes. Marketplaces as a sales channel concentrate margin pools through commission structures and advertising placements, while workshops as a customer type drive the highest repeat-purchase frequency and bulk order values.
EU Green Deal emissions benchmarks, REACH chemical compliance for automotive materials, and CE marking for diagnostic tools collectively elevate product data requirements and restrict non-compliant seller access. GDPR data handling rules further shape customer account architectures and cross-border transaction record retention. Stakeholders must monitor evolving battery passport mandates and right-to-repair enforcement as these frameworks redefine parts traceability obligations and platform liability exposure.
Market Dynamics
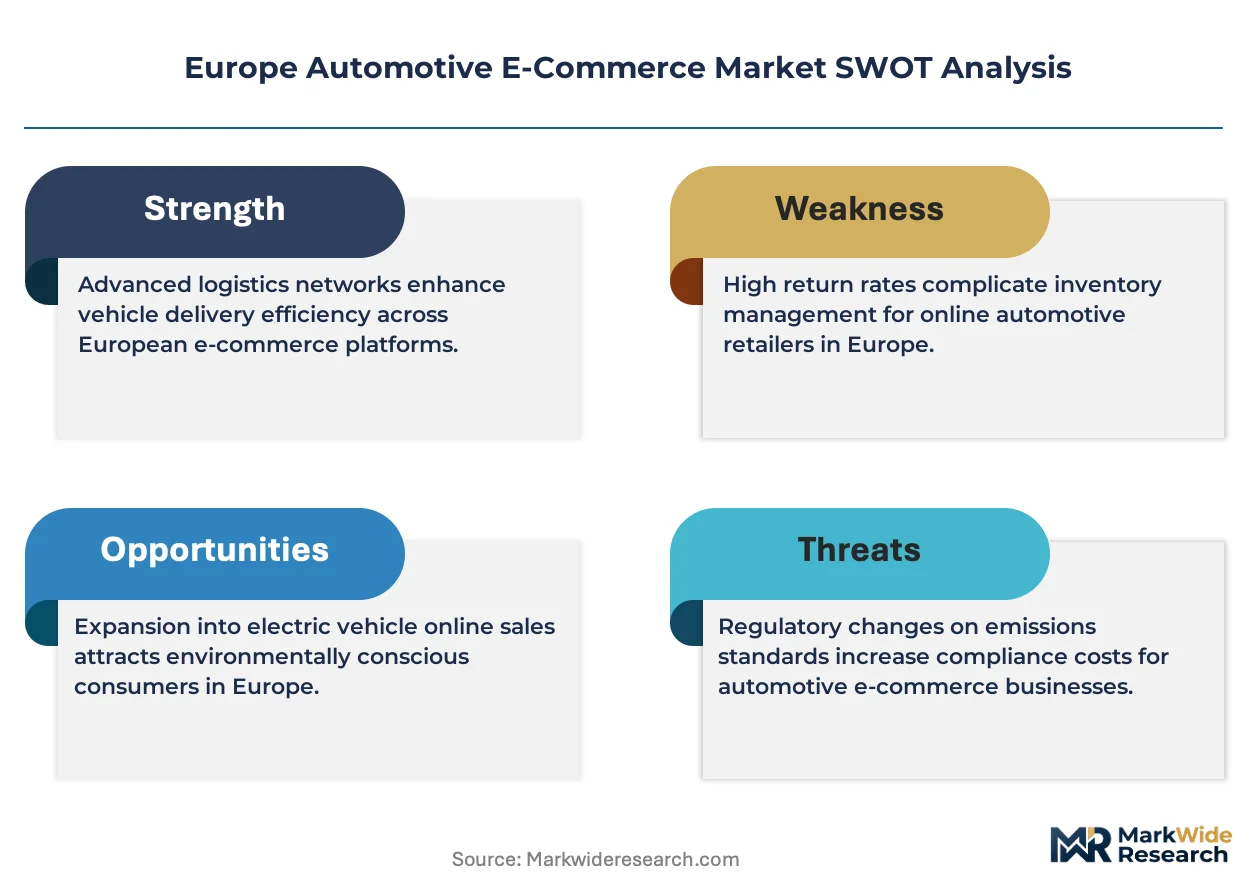
Platform consolidation is compressing supplier fragmentation as digital procurement migrates from bilateral relationships toward aggregated marketplaces, with EU Green Deal emissions standards redirecting parts demand toward EV-compatible components and battery traceability systems.
Growth Catalysts
- Fleet electrification mandates:Commercial vehicle operators in Germany, France, and the Netherlands face binding CO2 reduction targets under EU Green Deal benchmarks, forcing accelerated online procurement of EV drivetrain components and thermal management parts.
- REACH compliance digitization:Chemical substance restrictions for automotive materials are elevating data transparency requirements, advantaging platforms with structured product passports and automated certification verification.
- Workshop network density:Germany's concentrated independent repair sector generates recurring bulk orders for brake and suspension components, creating natural demand aggregation points for specialized e-commerce catalogs.
Market Restraints
- Last-mile logistics cost volatility:Tire and battery shipments face weight-based freight premiums and seasonal capacity constraints, compressing margins on high-volume, low-value orders.
- Cross-border VAT complexity:The EU's fragmented national tax regimes and distance-selling thresholds create compliance friction for marketplace sellers operating across multiple member states.
- Right-to-repair enforcement gaps:Incomplete implementation of diagnostic data access mandates limits independent workshops' ability to verify part compatibility digitally, slowing platform adoption.
Strategic Opportunities
- Polish and Romanian workshop penetration:Eastern European independent repair sectors remain underdigitized relative to Western counterparts, offering first-mover platform expansion potential.
- Battery passport integration:Upcoming EU battery regulation mandates will require end-to-end traceability systems, creating service revenue streams for platforms that embed compliance tools.
- AI-powered VIN matching:Machine learning compatibility engines are reducing return rates and enabling confident cross-border purchasing by non-technical buyers.
Industry Challenges
- Legacy ERP integration:Workshop management systems lack standardized APIs, forcing costly custom middleware development for real-time inventory synchronization.
- GDPR-compliant customer data architecture:Cross-border transaction record retention and consent management require platform infrastructure investments that strain mid-market operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive E-Commerce Market |
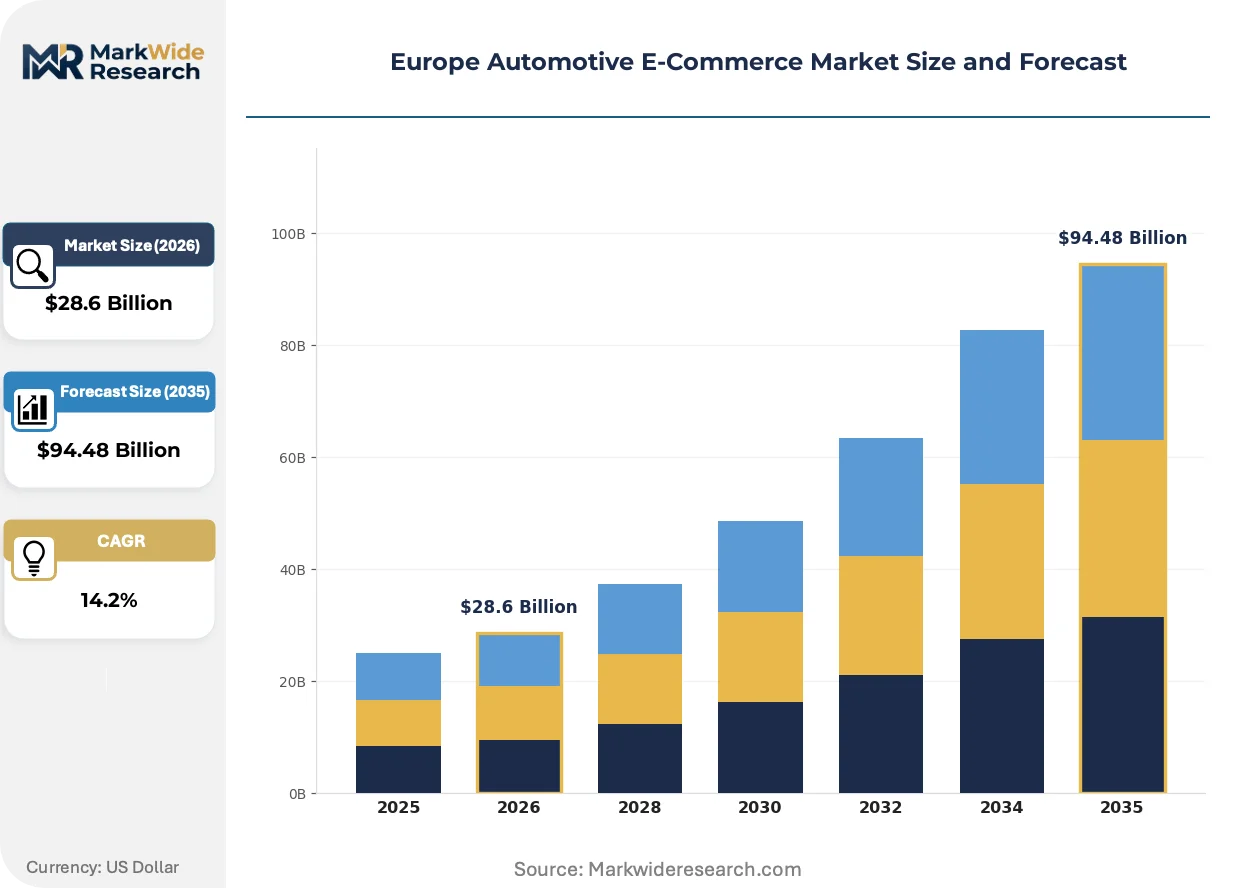
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parts, Accessories, Tires, Tools Sales Channel: Direct Sales, Marketplaces, Dealerships, Auctions Customer Type: Retail Consumers, Fleet Operators, Car Enthusiasts, Workshops Service Type: Repair Services, Maintenance Packages, Installation Services, Consultation |
| Companies Covered | eBay Inc., Oscaro, Amazon.com, Inc., Robert Bosch GmbH, Europarts, Autodoc SE, Mister Auto, Delticom AG, RockAuto, LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive E-Commerce Market Evolving Landscape
Artificial intelligence and regulatory data mandates are restructuring how automotive parts are specified, verified, and fulfilled across European digital supply chains.
Machine learning-based VIN decoding is automating compatibility verification at the point of search, reducing manual specification errors that previously drove high return rates. Independent workshops in Germany and France are adopting these tools fastest, drawn by time savings on complex multi-brand fleets. The technology is automating the translation of unstructured supplier data into structured fitment records, compressing catalog onboarding cycles from months to weeks.
The EU battery passport regulation is mandating end-to-end traceability for lithium-ion cells and modules entering the aftermarket, with phased implementation beginning in 2027. This forces platforms to integrate blockchain or centralized registry systems for origin verification and lifecycle documentation. EV component marketplaces face the steepest compliance burden, as battery chemistry and recycling pathway data must accompany every transaction.
Subscription-based procurement contracts are displacing spot purchasing among fleet operators managing predictable maintenance schedules. Large commercial vehicle lessors in the Benelux region are consolidating supplier relationships through multi-year digital agreements with guaranteed availability tiers. This model concentrates volume with platforms offering predictive inventory positioning and dedicated logistics lanes, marginalizing generalist distributors.
Europe Automotive E-Commerce Market Segmentation
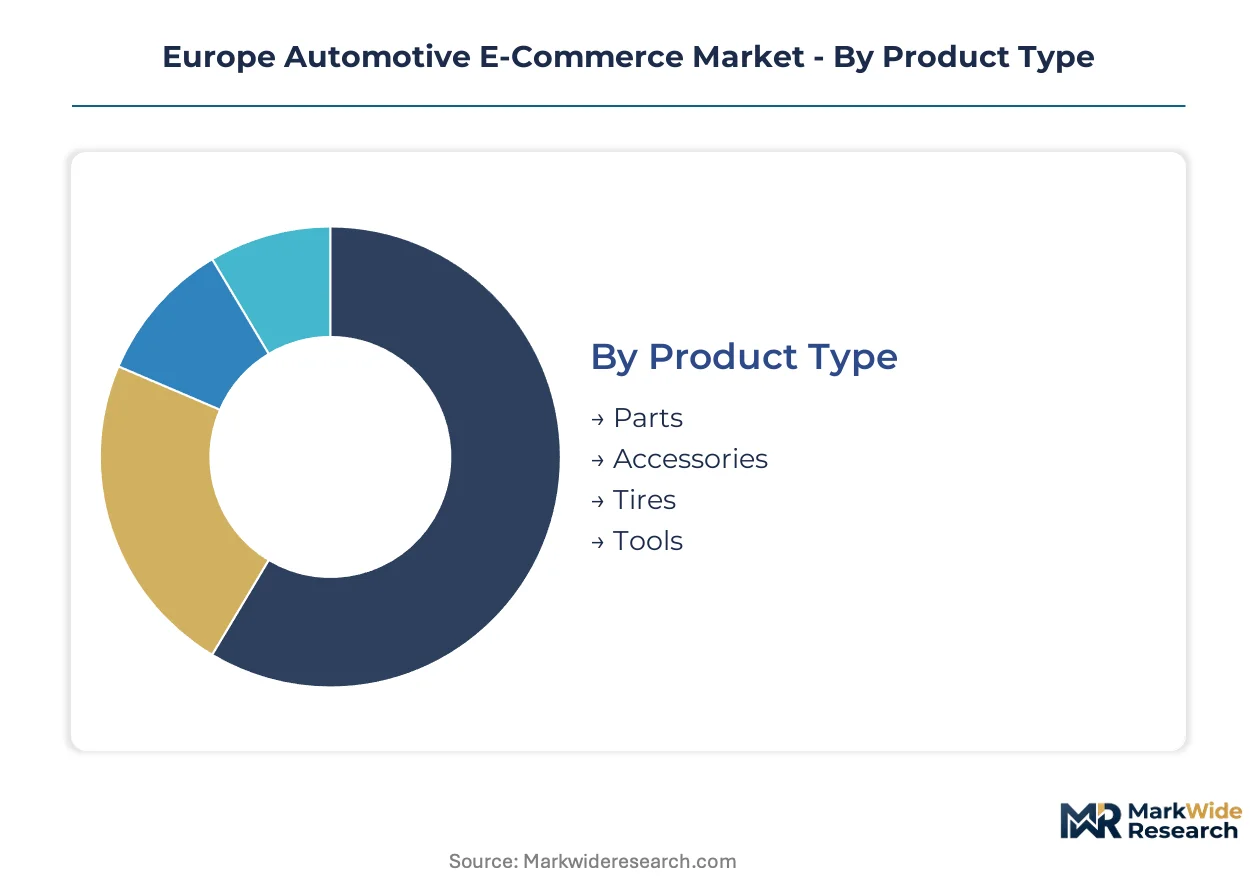
Segmentation in European automotive e-commerce reveals how procurement behavior fragments across technical complexity, buyer sophistication, and fulfillment requirements. Understanding these divisions exposes where platform investments in catalog depth, logistics infrastructure, and compliance tooling generate differential returns.
Product Type:
Integration depth varies sharply: parts and tires embed directly into vehicle systems demanding VIN-level verification, while accessories and tools operate as standalone purchases with lower compatibility risk.
- Parts:Brake rotors, suspension assemblies, and drivetrain components specified by OEM interchange numbers dominate transaction value. German workshops in the Rhine-Ruhr corridor drive bulk procurement of OEM-equivalent brake and suspension components, with EU Green Deal emissions standards redirecting demand toward EV-compatible thermal management and electric powertrain parts.
- Tires:Seasonal and all-season rubber specified by load index and speed rating carry premium logistics complexity due to weight-based freight costs and winter demand spikes. Benelux fleet operators consolidate annual tire procurement through subscription contracts, compressing spot-market volumes for generalist distributors.
- Accessories:Interior upgrades, exterior styling kits, and infotainment peripherals purchased without VIN verification. Polish retail consumers show rising appetite for aftermarket lighting and body modifications.
- Tools:Diagnostic equipment and workshop hand tools subject to CE marking mandates. French independent repairers invest in OBD scanners compatible with evolving EU diagnostic data access requirements.
Parts lead volumes today; tires are gaining share fastest on fleet electrification and seasonal replacement cycles.
Sales Channel:
Channel economics diverge by margin capture: direct sales retain full markup while marketplaces trade margin for reach, with cost-to-serve dictating which model dominates by transaction size.
- Direct Sales:Manufacturer-owned portals and authorized distributor websites serving established workshop accounts. Robert Bosch GmbH extends its authorized dealer network into direct-to-workshop digital portals, narrowing manufacturer-to-end-user distance.
- Marketplaces:Aggregated platforms capturing margin pools through commission structures and advertising placements. Amazon.com, Inc. leverages fulfillment density across borderless European delivery zones to capture recurring maintenance orders.
- Dealerships:OEM-captive digital channels with guaranteed genuine parts authentication. German premium brand networks dominate warranty-related parts procurement.
- Auctions:Disposition channels for obsolete inventory and insurance salvage components. Romanian and Bulgarian buyers concentrate demand for cost-sensitive repair operations.
Marketplaces lead volumes today; direct sales are expanding most quickly on subscription fleet contracts.
Customer Type:
Customer sophistication determines data requirements: technical buyers demand structured fitment databases while retail purchasers prioritize search convenience and return policies.
- Retail Consumers:Individual vehicle owners purchasing replacement parts and accessories with limited technical specification knowledge. AI-powered VIN matching tools reduce return rates among non-technical buyers.
- Fleet Operators:Commercial vehicle lessors and logistics companies managing predictable maintenance schedules through multi-year digital agreements. Large Benelux lessors consolidate supplier relationships through guaranteed availability tiers.
- Car Enthusiasts:Hobbyist buyers seeking performance upgrades and restoration components with high willingness to research compatibility. German and UK collectors drive demand for classic vehicle reproduction parts.
- Workshops:Independent repair facilities generating highest repeat-purchase frequency and bulk order values. Dense German workshop networks create natural demand aggregation points for specialized catalogs.
Workshops lead volumes today; fleet operators show the steepest expansion trajectory on electrification mandates.
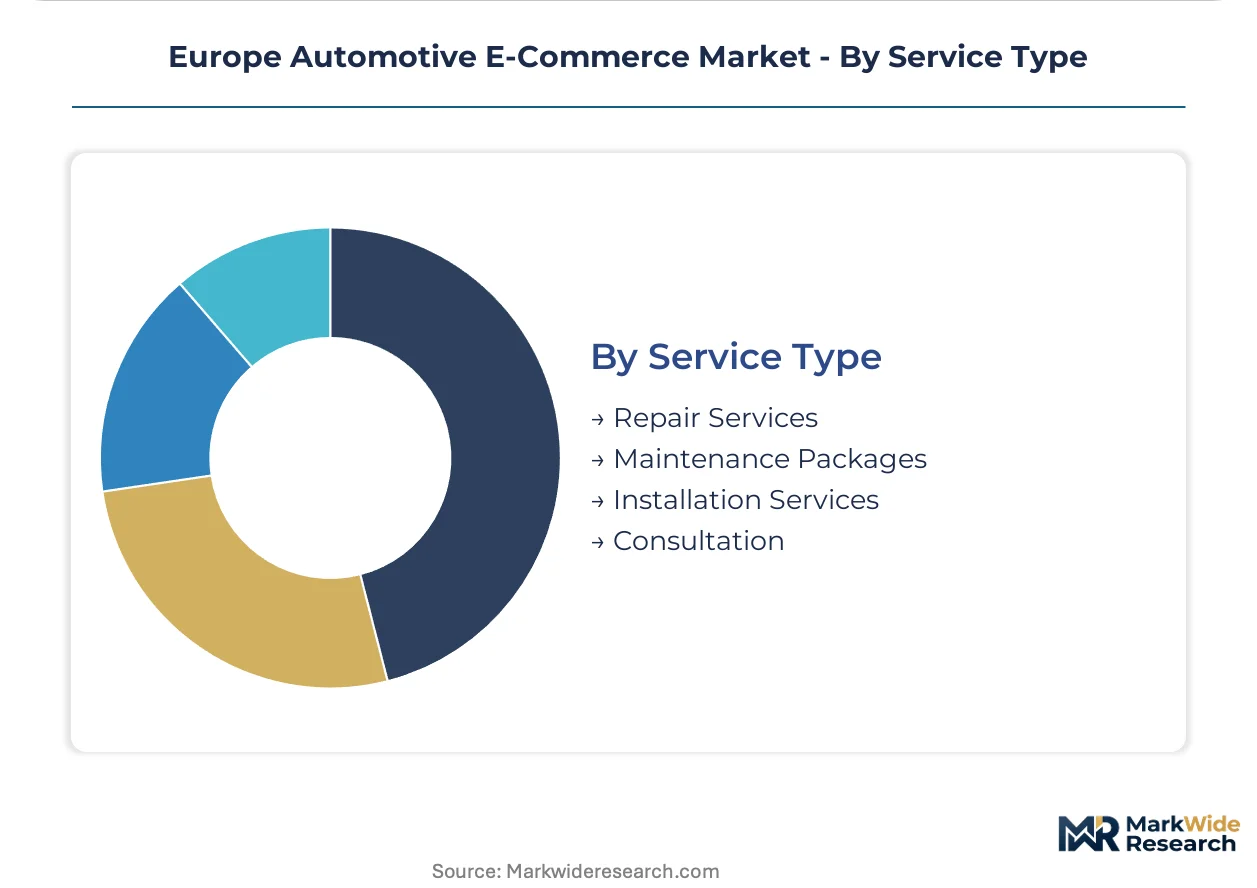
Service Type:
Service attachment rates climb with product complexity: physical installation and technical consultation attach highest to powertrain components, while routine maintenance packages standardize around predictable intervals.
- Repair Services:Post-failure component replacement coordinated through platform-scheduled technician dispatch. Eastern European markets show rising demand for mobile repair units.
- Maintenance Packages:Scheduled service bundles combining parts, labor, and fluid replacement at predictable intervals. Subscription models displace spot purchasing among fleet operators with predictable schedules.
- Installation Services:Physical fitting of purchased components at certified facilities. Tire mounting and balancing generate highest attachment rates due to equipment requirements.
- Consultation:Technical advisory on part compatibility, repair sequencing, and regulatory compliance. GDPR-compliant customer data architectures strain mid-market operators offering personalized guidance.
Repair services lead volumes today; maintenance packages are climbing the fastest on fleet subscription adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in the Europe Automotive E-Commerce Market remain muted given harmonized EU frameworks, though national implementation speed of Green Deal mandates and right-to-repair enforcement creates operational differentiation across member states. Workshop digitization rates and logistics infrastructure density determine where platform investments concentrate.
Germany
KBA vehicle registration databases enable seamless VIN-based parts matching for workshops in the Rhine-Ruhr corridor. The country's right-to-repair implementation through national trade ordinances grants independent repairers diagnostic data access ahead of neighbors. Stuttgart and Munich anchor premium OEM parts distribution networks serving southern German vehicle manufacturing clusters.
France
ANSM and CNIL oversight of health-adjacent automotive materials enforces REACH documentation standards that elevate platform compliance costs. French fleet operators face binding CO2 reduction timelines under EU Green Deal national allocation mechanisms. Lyon and Paris basin logistics hubs concentrate tire and battery fulfillment capacity for continental distribution.
United Kingdom
Post-Brexit customs friction redirects cross-border parts flows through dedicated UK warehousing rather than continental direct-ship models. The Driver and Vehicle Licensing Agency maintains VIN databases that enable domestic compatibility verification independent of EU systems. Midlands distribution centers serve dense independent workshop networks in Birmingham and Manchester conurbations.
Netherlands
Benelux fleet electrification mandates under EU Green Deal country-specific trajectories accelerate procurement of EV thermal management components through digital channels. Rotterdam port infrastructure enables consolidated import of Asian-manufactured aftermarket parts for redistribution. Eindhoven's automotive technology cluster drives demand for diagnostic tool e-commerce with embedded CE marking verification.
Poland
Underdigitized independent repair sectors in Warsaw and Krakow metropolitan areas present first-mover platform expansion opportunities relative to Western European saturation. Polish implementation of EU battery passport pre-registrations lags German and French timelines, creating temporary compliance cost advantages for domestic distributors. Silesian manufacturing zones generate growing aftermarket parts demand from aging vehicle fleets.
Europe Automotive E-Commerce Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized catalog depth and fleet subscription models as differentiation vectors. The market structure concentrates around three archetypes: horizontal marketplaces leveraging fulfillment density, vertical specialists commanding brake and suspension categories, and manufacturer-captive portals narrowing distributor layers. Platform consolidation and AI-powered VIN matching represent the dominant competitive moves reshaping procurement relationships.
Among Germany-based industrial participants, Robert Bosch GmbH and Autodoc SE exemplify contrasting archetypes within the same geography. Amazon.com, Inc. occupies a position representing horizontal marketplace scale across borderless European delivery zones. These three entities anchor the competitive spectrum from manufacturer-integrated to pure-platform models without implying specific strategic coordination or market share claims.
| Leading Market Players |
|---|
| eBay Inc. |
| Oscaro |
| Amazon.com, Inc. |
| Robert Bosch GmbH |
| Europarts |
| Autodoc SE |
| Mister Auto |
| Delticom AG |
| RockAuto, LLC |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up marketplace specialists concentrate procurement volume across German and Benelux logistics hubs, compressing distributor margins while enforcing contract-based pricing discipline on fragmented supplier bases. This ownership pattern channels working capital toward fulfillment density investments that reshape how workshops negotiate part costs.
Pricing Analysis
Distributor margin compression dominates channel economics as digital marketplaces disintermediate traditional two-step distribution. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with OEM-equivalent brake and suspension components commanding brand premiums. Cost compression in the economy tier is intensifying because Asian-manufactured aftermarket parts flood Benelux redistribution channels. Fleet operators show lowest price sensitivity due to guaranteed availability requirements, while Polish retail consumers drive aggressive spot-market bargaining.
Supply Chain Analysis
Workforce availability constraints in Czech and Hungarian packaging operations limit fulfillment scalability for seasonal tire demand spikes. Supply concentrates in Germany for OEM-equivalent components, China for aftermarket electronics, and Turkey for rubber and polymer inputs. Raw material dependencies rest on lithium carbonate for EV battery traceability systems, steel alloys for brake rotors, and synthetic rubber compounds. Single-source vulnerability around Asian-manufactured diagnostic tools creates regulatory exposure under CE marking enforcement gaps. Distribution runs through Rotterdam port consolidation for continental redistribution, with last-mile density determining final-mile cost allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polish and Romanian workshop digitization lags create a geographic-arbitrage play, as Western European compliance costs under REACH and EU battery passport mandates exceed Eastern European implementation timelines by several regulatory phases.
For Market Incumbents: Deepen catalog specialization in EV thermal management components before battery passport mandates reshape parts traceability obligations. Secure authorized dealer network exclusivity in Stuttgart and Munich manufacturing clusters to narrow manufacturer-to-end-user distance. Vertical integration into predictive inventory positioning for fleet subscription contracts defends against horizontal marketplace fulfillment density. For New Entrants and Emerging Players: The premium-to-economy price-point gap in diagnostic equipment offers entry space for CE-marking-compliant tool platforms serving French independent repairers. Target underdigitized Warsaw and Krakow metropolitan workshop networks with AI-powered VIN matching tools that reduce return rates among non-technical buyers. Anchor go-to-market strategy through mobile repair unit partnerships in Eastern European markets. For Investors and Strategic Acquirers: Tier 1 automotive suppliers are the most active acquirer in this space, seeking downstream channel control to offset OEM pricing pressure. Long-term viability centers on platforms with embedded compliance tooling for battery passport and right-to-repair traceability mandates. Target acquisition archetype: vertical specialists with brake and suspension catalog depth and established German workshop relationships. Monitor EU Green Deal national implementation speed as the critical inflection signal for parts demand redirection toward EV-compatible components.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Passport Integration | Blockchain traceability systems embedded in Autodoc SE catalogs capture 2027 EU regulatory compliance revenue. |
| AI-Powered VIN Matching | Machine learning compatibility engines reduce German workshop return rates and enable confident cross-border purchasing. |
| Fleet Subscription Contracts | Benelux commercial vehicle lessors consolidate supplier relationships through multi-year digital agreements with guaranteed availability tiers. |
| Eastern European Platform Expansion | First-mover penetration into underdigitized Polish and Romanian repair sectors captures pre-saturation growth. |
| Direct-to-Workshop Portal Development | Robert Bosch GmbH narrows manufacturer-to-end-user distance through authorized dealer network digitization. |
Research Methodology
Bottom-up workshop and fleet operator modeling reconciled against top-down marketplace transaction tracking forms the analytical core. Primary interviews with aftermarket distributors, OEM platform engineers, independent repair facility owners, and logistics coordinators combined with secondary validation from KBA vehicle registration databases, EU customs trade records, and REACH compliance filings. Triangulation across these sources anchors volume estimates.
Historical trendline analysis of digital procurement penetration rates across German, French, and Benelux markets establishes baseline trajectory assumptions. Segmentation dimensions modeled include product type integration depth, sales channel margin capture, customer sophistication tier, and service attachment complexity. CAGRs derive from fitted growth curves applied to electrification mandate timelines and workshop digitization saturation patterns, with EV component share evolution and fleet subscription adoption rates serving as key forecast inputs across the projection horizon.
Caveats apply where EU battery passport implementation delays or right-to-repair enforcement gaps could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization speed and logistics cost normalization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
E-Commerce Apparel Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Agricultural E-Commerce Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
E-Commerce Household Appliances Market