
 Omnichannel Commerce Software Market | 2026-2036
Omnichannel Commerce Software Market Size, Share, and Industry Trends Forecast 2026-2036
Omnichannel Commerce Software Market Insights
Specialty retail chains is restructuring how merchants evaluate order management and inventory synchronization capabilities. Shopify Plus leverages its native point-of-sale and online storefront convergence to anchor mid-market adoption across North American and European retail networks. Salesforce Commerce Cloud sustains enterprise-grade dominance through deep CRM-to-checkout integration that competes with standalone best-of-breed stacks.
Omnichannel commerce software orchestrates unified transaction, inventory, and customer engagement layers across physical and digital sales channels, typically deployed via API-first architectures that synchronize real-time stock levels, pricing, and fulfillment options across storefronts. Cloud-based and SaaS deployment modes now lead structural growth as retailers abandon on-premise maintenance overhead in favor of elastic infrastructure that scales with seasonal demand spikes. Order Management and CRM segments concentrate margin pools because these modules command premium pricing through their direct impact on fulfillment accuracy and repeat purchase rates.
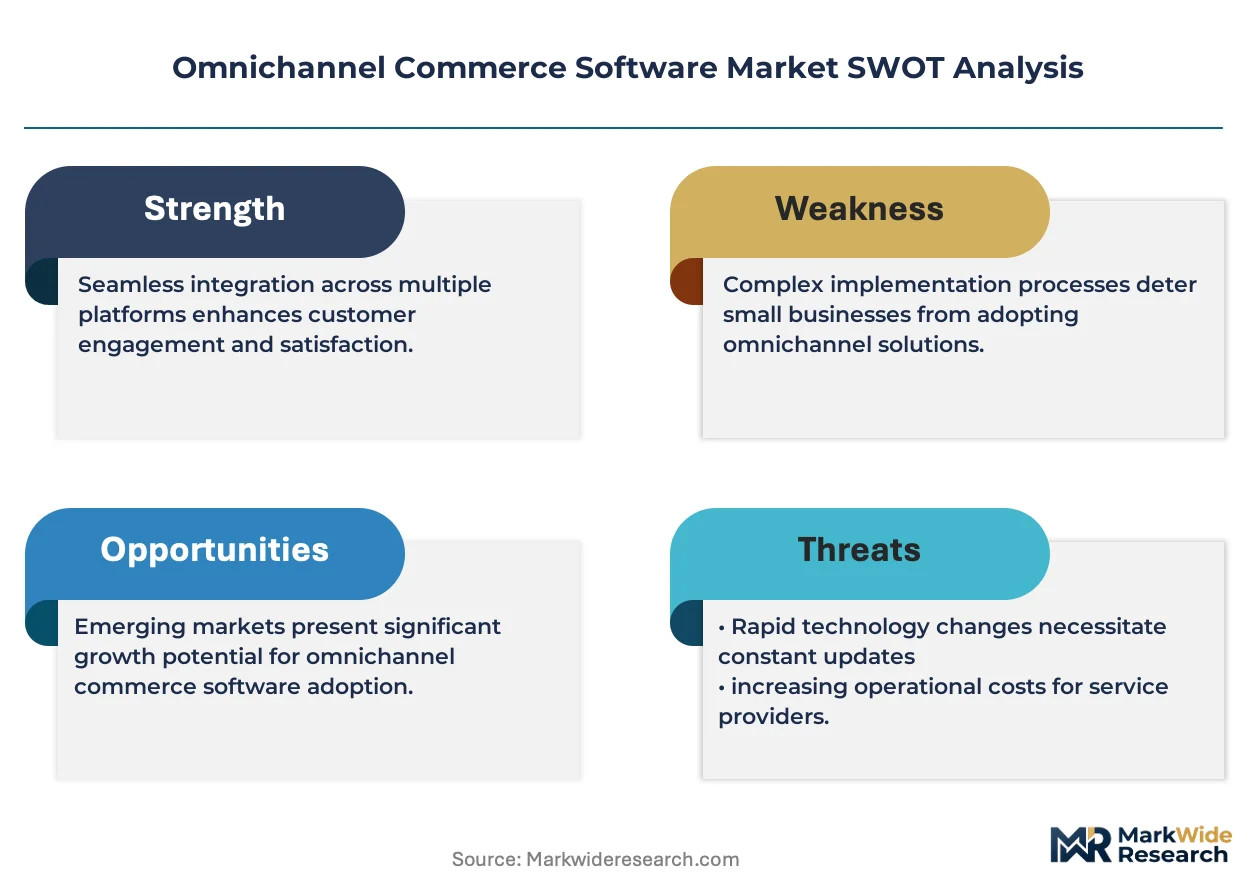
The EU AI Act and GDPR shape product development trajectories by mandating explainable recommendation engines and granular consent audit trails within customer data platforms. FDA oversight of software-as-medical-device claims and FTC truth-in-advertising enforcement on personalized pricing algorithms add compliance layers for health and wellness retailers operating omnichannel stacks. Stakeholders must weigh whether to consolidate around full-suite providers or maintain modular interoperability as regulatory fragmentation across jurisdictions intensifies integration complexity.
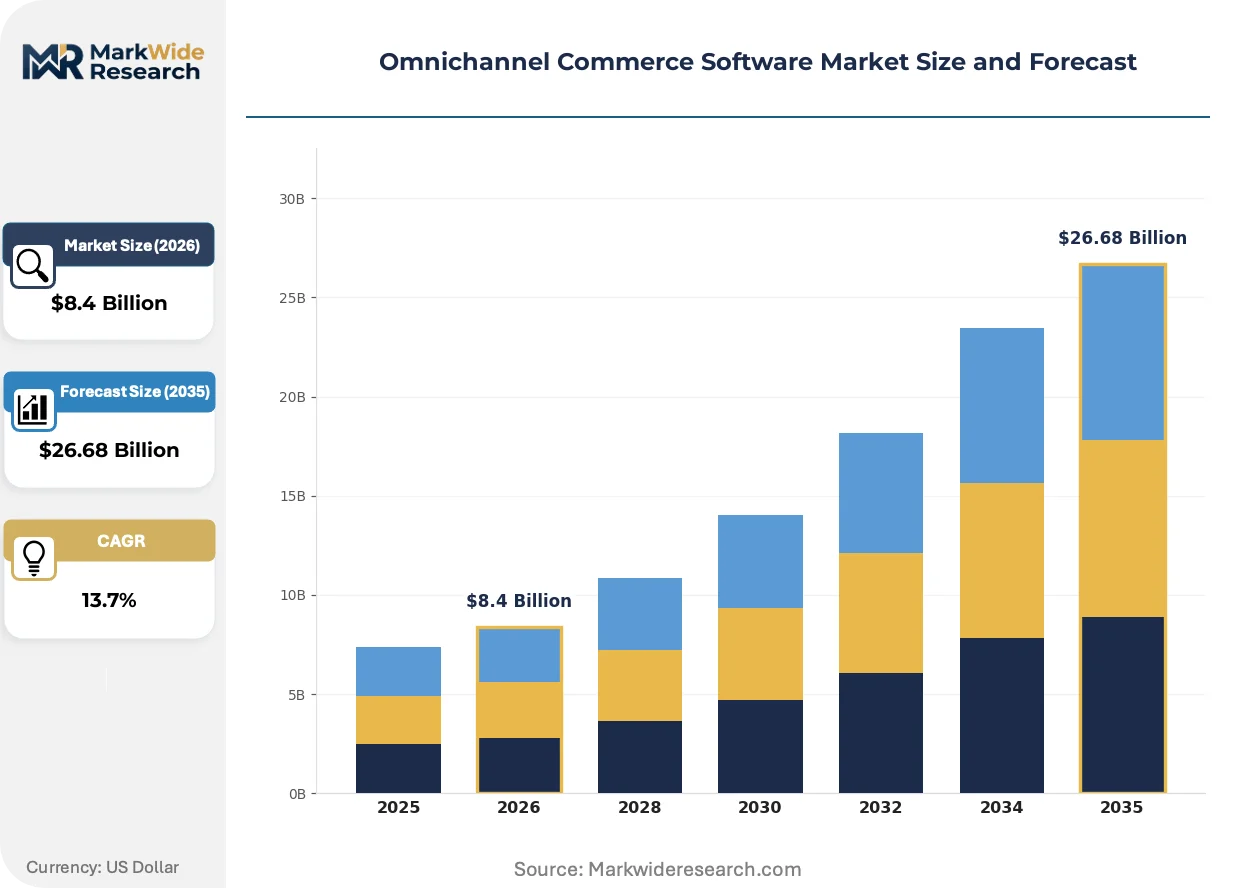
Market Dynamics
Unified inventory visibility requirements are forcing specialty retail chains to restructure fulfillment architectures around real-time synchronization between point-of-sale, warehouse management, and marketplace endpoints.
Growth Catalysts
- EU AI Act compliance mandates:Retailers accelerate investment in explainable recommendation engines and consent-managed customer data platforms to meet granular audit trail requirements.
- Mid-market consolidation in Germany:Specialty retailers consolidate point-of-sale, e-commerce, and marketplace integrations onto single-stack architectures to reduce integration overhead.
- Cloud-native API architectures:Elastic infrastructure adoption scales with seasonal demand spikes, replacing on-premise maintenance overhead with consumption-based SaaS models.
Market Restraints
- GDPR consent fragmentation:Granular data subject rights create operational friction in cross-border customer profiling and personalized pricing deployment.
- Integration complexity:Legacy ERP systems in established retail chains resist real-time API synchronization, extending implementation timelines.
- Specialized talent scarcity:Shortage of engineers fluent in both retail operations and distributed systems architecture drives compensation inflation.
Strategic Opportunities
- Health and wellness vertical expansion:FDA software-as-medical-device oversight creates compliance moats for platforms serving regulated wellness retailers.
- Unified CRM-to-fulfillment convergence:Platforms integrating customer lifetime value analytics with inventory positioning capture premium pricing.
- FTC truth-in-advertising enforcement:Transparent algorithmic pricing documentation becomes competitive differentiator against opaque competitors.
Industry Challenges
- Multi-jurisdiction regulatory fragmentation:Divergent AI transparency requirements across EU member states complicate single-codebase deployment.
- Legacy system interoperability:Decades-old warehouse management systems lack native API endpoints, requiring expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omnichannel Commerce Software Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shopping Cart, Payment Gateway, CRM, Order Management Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Industry Vertical: Retail, E-Commerce, Hospitality, Telecommunications Customer Type: Small Enterprises, Medium Enterprises, Large Enterprises, Non-Profit |
| Companies Covered | BigCommerce Enterprise, HubSpot, Shopify Plus, ActiveCampaign, Insider One, Salesforce Commerce Cloud, Klaviyo, Omnisend, Adobe Commerce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omnichannel Commerce Software Market Trends and Innovations
Composable commerce architectures are displacing monolithic suites as retailers demand modular components that swap without full-platform replacement.
Headless commerce platforms separate frontend presentation from backend transaction processing, enabling brands to deploy channel-specific experiences without duplicating inventory logic. Mid-market specialty retailers in North America and Europe adopt these architectures fastest, driven by marketplace expansion requirements. This technology is consolidating vendor landscapes by collapsing point solutions into unified orchestration layers.
The EU AI Act mandates explainable logic for automated product recommendations and dynamic pricing algorithms, forcing platform providers to document decision pathways. Retailers operating cross-border face divergent implementation timelines as member states transpose framework provisions into national law. Health and wellness segments encounter the steepest compliance burden due to overlapping FDA software-as-medical-device claims.
Buy-now-pay-later integration at checkout has become table stakes for conversion optimization, with specialty apparel and electronics retailers leading deployment. Embedded finance partnerships displace traditional credit offerings by reducing friction in high-consideration purchases. German and UK markets show the densest adoption, where consumer protection frameworks already govern installment lending transparency.
Omnichannel Commerce Software Market Segmentation
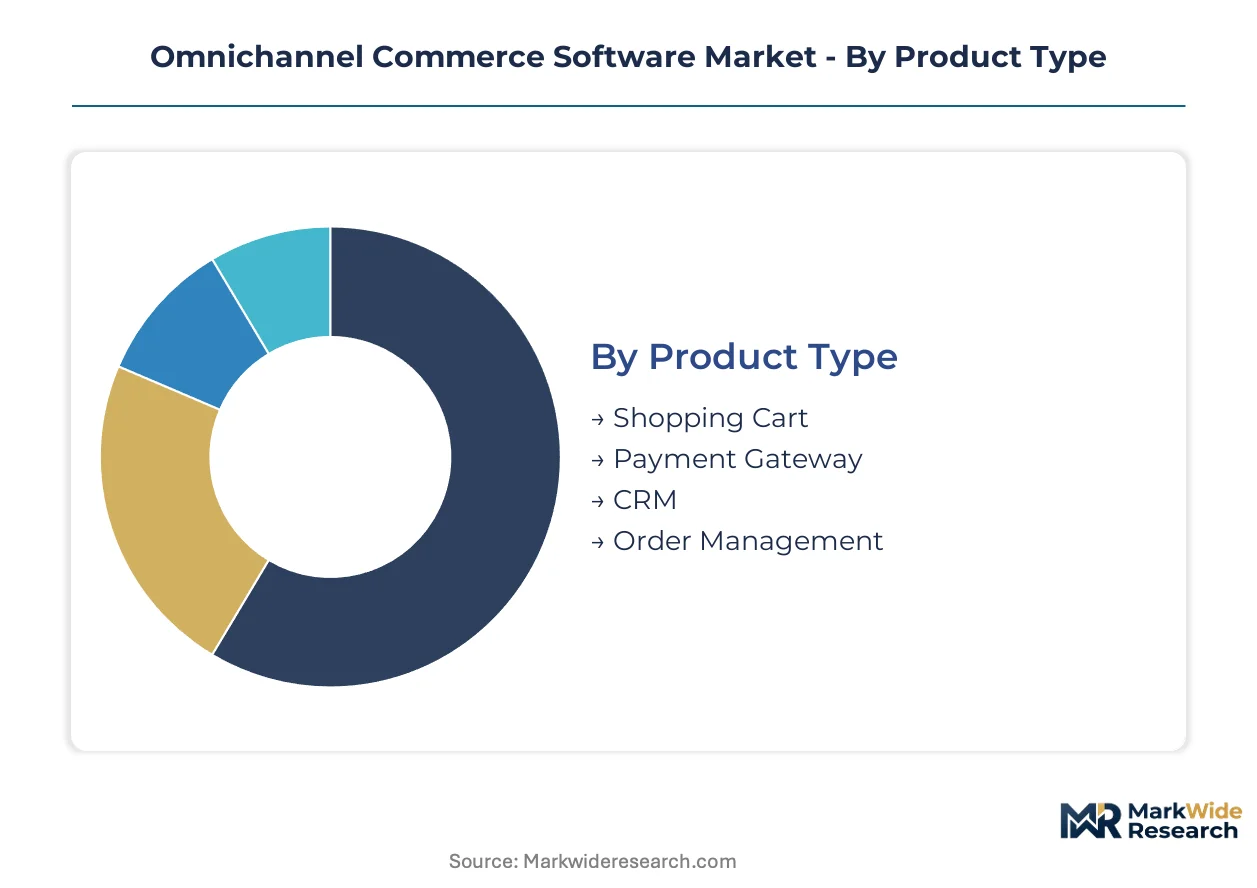
Specialty retail chains select omnichannel commerce modules based on fulfillment complexity and customer data governance requirements. The report examines four segmentation dimensions that determine vendor selection criteria and implementation timelines across deployment environments.
Product Type:
Volume deployment concentrates in transaction processing layers, while premium pricing accrues to modules governing customer relationships and inventory orchestration.
- Shopping Cart:Frontend transaction interface handling product selection, cart persistence, and checkout initiation. German mid-market retailers prioritize this module for marketplace integration speed.
- Payment Gateway:Encrypted transaction routing layer managing authorization, settlement, and fraud detection across card networks and alternative payment methods. Hospitality verticals in France and Spain drive demand for split-tender and buy-now-pay-later compatibility.
- CRM:Customer data platform unifying profile history, consent preferences, and lifetime value analytics across touchpoints.
- Order Management:Inventory-aware fulfillment orchestration engine synchronizing stock positions across warehouses, stores, and drop-ship partners.
Mature deployment sits with Shopping Cart and Payment Gateway modules. Newer deployment is concentrated in Order Management as specialty retailers restructure around unified inventory visibility.
Deployment:
Application context determines architecture choice, with seasonal demand patterns and data residency requirements shaping cloud versus on-premise decisions.
- Cloud-Based:Elastic infrastructure hosted on third-party hyperscaler networks with consumption-based pricing. Retailers in Italy and Netherlands adopt this mode fastest for marketplace scaling flexibility.
- On-Premise:Self-managed server infrastructure within retailer data centers, maintaining direct control over transaction data and customization depth. Established retail chains in Belgium retain this model for legacy ERP interoperability.
- Hybrid:Split architecture placing sensitive customer data on-premise while routing transaction spikes through cloud burst capacity.
- SaaS:Fully managed software subscriptions with vendor-controlled updates and multi-tenant infrastructure sharing.
Cloud-Based and SaaS models capture expanding share fastest. On-Premise retains foothold where GDPR data localization mandates intersect with legacy system dependencies.
Industry Vertical:
Customer journey complexity and regulatory exposure differentiate vertical adoption patterns, with health-adjacent segments facing steepest compliance burdens.
- Retail:Physical and digital storefront convergence with unified inventory and fulfillment optimization. Specialty apparel and electronics chains across Germany, UK, and France anchor demand for real-time stock synchronization.
- E-Commerce:Pure-play digital merchants operating without physical footprint, prioritizing marketplace multi-homing and conversion rate optimization.
- Hospitality:Hotel, restaurant, and experience providers integrating booking, payment, and guest preference management.
- Telecommunications:Device financing, plan management, and omnichannel support for subscription-based consumer services.
Retail verticals show deepest penetration of full-suite platforms. E-Commerce represents the steepest expansion trajectory as marketplace sellers consolidate point solutions.
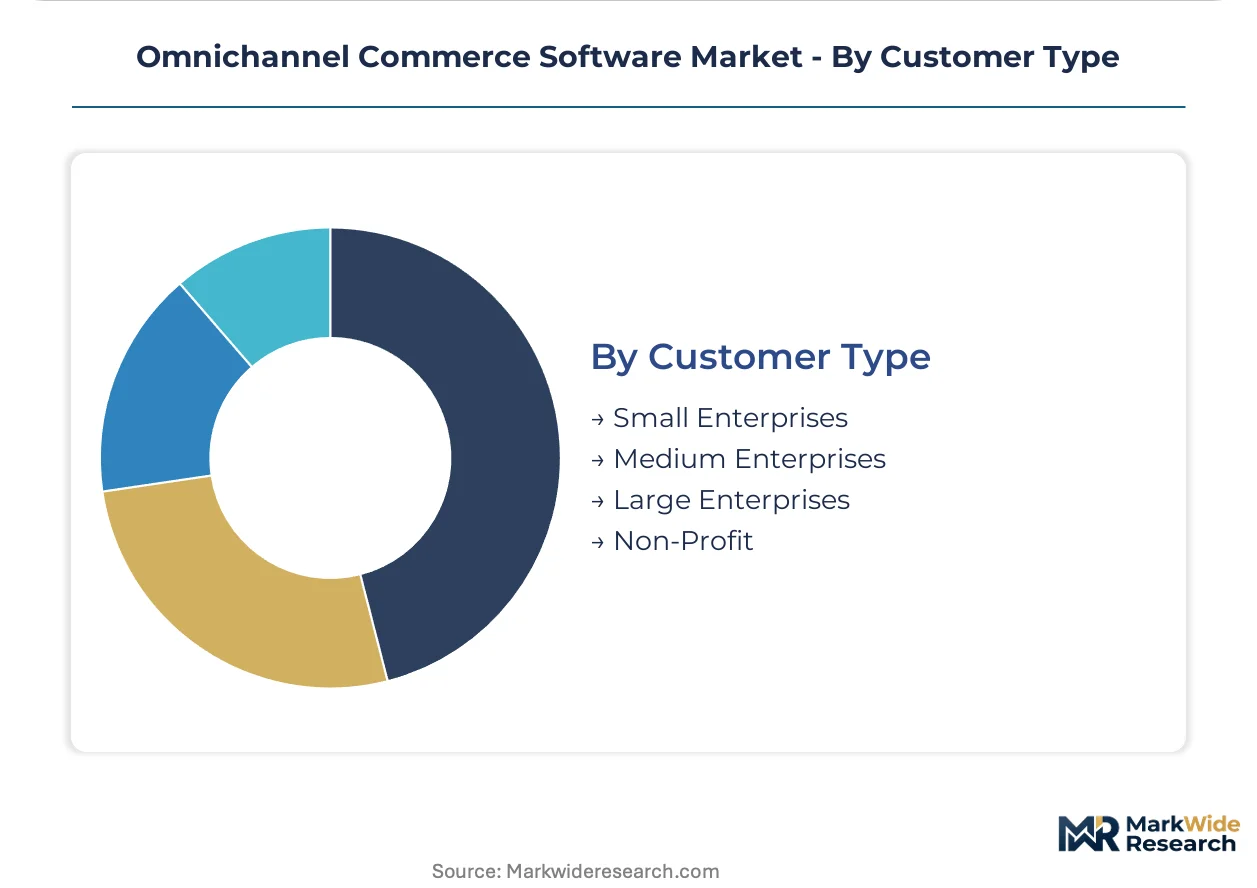
Customer Type:
Organizational scale dictates integration complexity tolerance and customization requirements, with mid-market segments driving fastest vendor switching.
- Small Enterprises:Limited IT staff and standardized workflows favoring plug-and-play configurations with minimal implementation support. Independent retailers in Portugal and Greece cluster here.
- Medium Enterprises:Sufficient scale for dedicated e-commerce operations yet constrained by legacy point-of-sale infrastructure. This segment in Germany and Poland drives single-stack consolidation demand.
- Large Enterprises:Multi-brand, multi-geography operations requiring enterprise-grade SLA guarantees and dedicated customer success management.
- Non-Profit:Donation processing and membership management with constrained procurement budgets and volunteer-dependent operations.
Large Enterprises anchor premium vendor revenues. Medium Enterprises concentrate fastest platform switching activity as consolidation pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free-trade zones and Dutch innovation hubs concentrate European omnichannel software investment, while US coastal tech corridors anchor North American deployment velocity.
Germany
Mid-market specialty retailers in Bavaria and North Rhine-Westphalia drive single-stack consolidation demand, merging point-of-sale with marketplace integrations. The EU AI Act mandates explainable recommendation engines, forcing Munich-based vendors to document algorithmic decision pathways. Berlin's startup density supports rapid prototyping of consent-managed customer data platforms.
United States
Shopify Plus adoption concentrates among direct-to-consumer brands scaling from social commerce origins. FTC truth-in-advertising enforcement on personalized pricing algorithms shapes compliance roadmaps for California-based health and wellness retailers. Greater Los Angeles and New York Metro clusters host dense networks of embedded finance partnerships.
United Kingdom
Buy-now-pay-later integration at checkout dominates conversion optimization strategies for London-headquartered apparel merchants. GDPR consent fragmentation creates operational friction in cross-border customer profiling, particularly affecting Manchester-based e-commerce operations. The Southeast England corridor sustains highest cloud-native SaaS migration rates.
France
Hospitality verticals in Paris and Lyon prioritize split-tender payment compatibility and guest preference management unification. ANSM and CNIL oversight intersects with EU AI Act provisions, complicating deployment timelines for wellness-focused retail stacks. The Île-de-France region anchors demand for API-first inventory synchronization.
Netherlands
Rotterdam and Amsterdam logistics hubs accelerate real-time stock synchronization requirements across warehouse-to-storefront chains. Cloud-based deployment modes capture fastest adoption among Dutch marketplace sellers scaling seasonal demand spikes. Randstad metropolitan infrastructure supports elastic infrastructure provisioning for mid-market consolidation.
Omnichannel Commerce Software Market Competitive Landscape
Top-tier vendors anchor enterprise-grade suites, while mid-market specialists compete on implementation speed and modular flexibility. The market structures around three distinct tiers: full-stack incumbents with CRM-to-checkout convergence, API-native challengers emphasizing headless architectures, and vertical specialists targeting regulated segments. Dominant competitive moves include strategic partnerships with embedded finance providers and geographic expansion through localized compliance tooling.
Within the full-stack tier, Salesforce Commerce Cloud and Shopify Plus occupy positions as archetypal solutions for enterprise and mid-market segments respectively. Adobe Commerce sits within the open-source-flexibility archetype, serving merchants requiring deep customization. HubSpot represents the CRM-native convergence pattern, anchoring customer lifetime value analytics integration.
| Leading Market Players |
|---|
| BigCommerce Enterprise |
| HubSpot |
| Shopify Plus |
| ActiveCampaign |
| Insider One |
| Salesforce Commerce Cloud |
| Klaviyo |
| Omnisend |
| Adobe Commerce |
| Others |
Pricing and Supply Chain Analysis
Engineers fluent in distributed systems architecture and retail operations concentrate in Berlin and Munich, where labor-cost differentials widen spreads between premium enterprise suites and mid-market SaaS tiers. German vendor density anchors high-margin pricing for consent-managed customer data platforms, while Polish and Portuguese development centers enable competitive standard-tier offerings.
Pricing Analysis
Short lead-time deployment commands premium pricing, with German mid-market retailers paying standard-tier rates for six-month implementations versus economy-tier discounts for twelve-month phased rollouts. Pricing stratifies across premium, standard, and economy tiers based on integration complexity and GDPR consent audit depth. Cost compression in the economy tier intensifies because hyperscaler infrastructure commoditizes base transaction processing. Small enterprises in Southern Europe exhibit highest price sensitivity, while German large enterprises absorb premium pricing for unified CRM-to-fulfillment convergence.
Supply Chain Analysis
Single-source vulnerability sits with Ireland-based hyperscaler data centers hosting EU customer data residency requirements. Software development draws from India, Poland, and Portugal for implementation engineering, while core platform R&D concentrates in Germany, the United States, and the United Kingdom. Tariff exposure on cloud infrastructure licensing creates margin pressure for vendors serving cross-border retailers. Distribution runs through direct vendor sales teams for enterprise accounts and agency partner networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Headless commerce architectures are displacing monolithic suites as retailers abandon legacy point-of-sale-to-e-commerce stitching in favor of API-native orchestration layers.
For Market Incumbents: Cement defensive moats by deepening vertical integration into consent-managed customer data platforms that preempt EU AI Act compliance mandates. Extend capacity addition in Berlin and Munich innovation hubs to capture German mid-market consolidation demand. Prioritize certification investment for FDA software-as-medical-device claims in health and wellness verticals before challenger platforms establish regulated-segment footholds. For New Entrants and Emerging Players: Mid-market specialty retailers in Poland and the Czech Republic represent underserved buyer archetypes with legacy ERP dependencies and limited vendor switching history. Target this geography with rapid-implementation SaaS offerings priced below German incumbent rates. Pursue embedded finance partnerships as primary go-to-market angle, leveraging buy-now-pay-later integration gaps in Central European markets. For Investors and Strategic Acquirers: The window for entry favors API-native challengers with headless architecture expertise and established marketplace integration connectors. Long-term viability hinges on consolidation plays that collapse point solutions into unified orchestration layers. Watch FTC enforcement patterns on personalized pricing algorithm transparency as early signal of compliance-cost inflection that favors full-suite providers over modular stacks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies point-of-sale, e-commerce, and marketplace endpoints for German mid-market retailers. |
| Strategic Partnership | Embedded finance alliances with buy-now-pay-later providers accelerate checkout conversion in UK apparel. |
| Acquisition of Specialist Firm | Captures consent-management tooling required for GDPR audit trail compliance across EU operations. |
| Geographic Expansion | Establishes localized compliance tooling for divergent EU AI Act implementation timelines. |
| Product Launch | Introduces explainable recommendation engines documenting algorithmic pathways for ANSM oversight. |
Research Methodology
Document review covered SEC filings of publicly traded commerce platforms, EU regulatory transposition documents, and hyperscaler capex disclosures, complemented by interviews with CTOs at German mid-market retailers, integration specialists at system integrators, platform engineers at API-native vendors, and procurement officers at French hospitality chains. Secondary validation drew from App Annie/Sensor Tower mobile commerce metrics, customs records on software licensing imports, and trade association reports from national retail federations. Bottom-up deployment counts triangulated against top-down addressable market estimates.
Segmentation outputs across deployment model, organization size, vertical, and integration complexity shaped the analytical framework over the projection horizon. CAGRs derived from modeled adoption curves weighted by German consolidation velocity and cloud-native migration rates in the Netherlands. Forecast inputs incorporated EU AI Act implementation phasing and FTC enforcement intensity on algorithmic pricing transparency.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to multi-jurisdiction regulatory fragmentation and legacy ERP interoperability breakthroughs. Assumptions underlying projections reflect current compliance cost trajectories and hyperscaler infrastructure pricing trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
India E-Commerce Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
South Korea Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
E-Commerce Fashion Accessories Market
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market