
 Latvia E-Commerce Market | 2026-2036
Latvia E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Latvia E-Commerce Market Foresight
Biodegradable packaging materials are replacing conventional plastics and is expanding fulfillment cost structures for Latvian online retailers. Pigu Latvia Sia leverages its pan-Baltic logistics network to sustain cross-border delivery economics. 220.lv anchors consumer electronics sales through specialized warehouse operations in Riga. Barbora.lv dominates grocery e-commerce with temperature-controlled last-mile infrastructure.
Latvia E-Commerce encompasses digitally mediated transactions for goods and services conducted through web-based platforms and mobile applications, relying on integrated payment gateways, inventory management systems, and multi-node distribution networks to complete commercial exchanges. Fashion and electronics categories lead transaction volumes, while home goods captures expanding margin pools as consumers invest in domestic spaces. Online marketplaces compete with direct-to-consumer channels for customer acquisition, with mobile payments emerging as the preferred settlement mechanism among younger demographics.
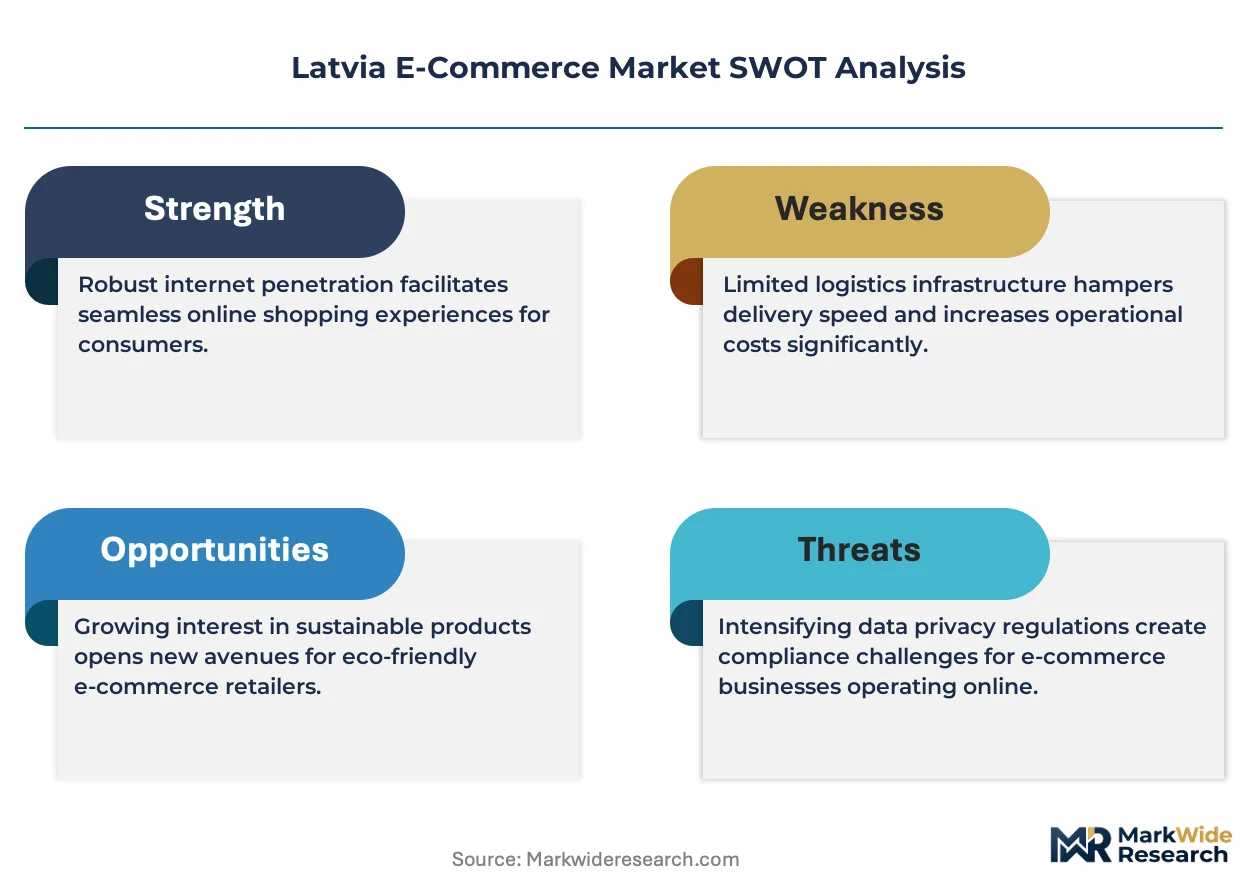
The EU Digital Services Act and GDPR shape platform liability and data handling requirements for Latvian operators, while the country's Consumer Rights Protection Centre enforces local distance-selling standards. The EU Green Deal packaging directives are forcing fulfillment networks to adopt sustainable materials and reverse logistics capabilities. Stakeholders must monitor regulatory alignment between national enforcement and Brussels-level platform governance as the compliance burden intensifies.
Market Dynamics
The EU Digital Services Act is tightening platform accountability across Latvia, forcing marketplace operators to restructure content moderation systems and algorithmic transparency protocols ahead of enforcement deadlines.
Growth Catalysts
- EU Green Deal packaging directives:Sustainable material mandates are accelerating warehouse retrofits for biodegradable fulfillment materials across Riga logistics hubs.
- Mobile wallet penetration:Swish and Apple Pay adoption among 18-34 demographics is compressing checkout abandonment rates in fashion and electronics categories.
- Urban household density:Riga metropolitan corridor concentration enables same-day grocery delivery economics for temperature-controlled last-mile networks.
Market Restraints
- Last-mile labor scarcity:Driver availability constraints in Latvian secondary cities inflate per-delivery costs beyond Riga baseline rates.
- Cross-border VAT complexity:Distance-selling thresholds and OSS registration requirements create compliance friction for pan-Baltic inventory pooling.
- Reverse logistics infrastructure:Limited specialized returns processing capacity outside the capital region extends refund cycle times.
Strategic Opportunities
- GDPR-compliant personalization engines:First-party data activation tools offer differentiation as third-party cookie deprecation advances.
- Daugavpils and Liepaja penetration:Underdeveloped e-commerce saturation in Latvia's second-tier cities presents customer acquisition cost advantages.
- CSRD-aligned sustainability reporting:Early adoption of supply chain carbon disclosure creates B2B procurement eligibility with EU institutional buyers.
Industry Challenges
- Warehouse automation integration:Legacy WMS platforms require costly API redevelopment to coordinate with robotic picking systems.
- Temperature certification timelines:GDP compliance for pharmaceutical and fresh food segments extends facility qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latvia E-Commerce Market |
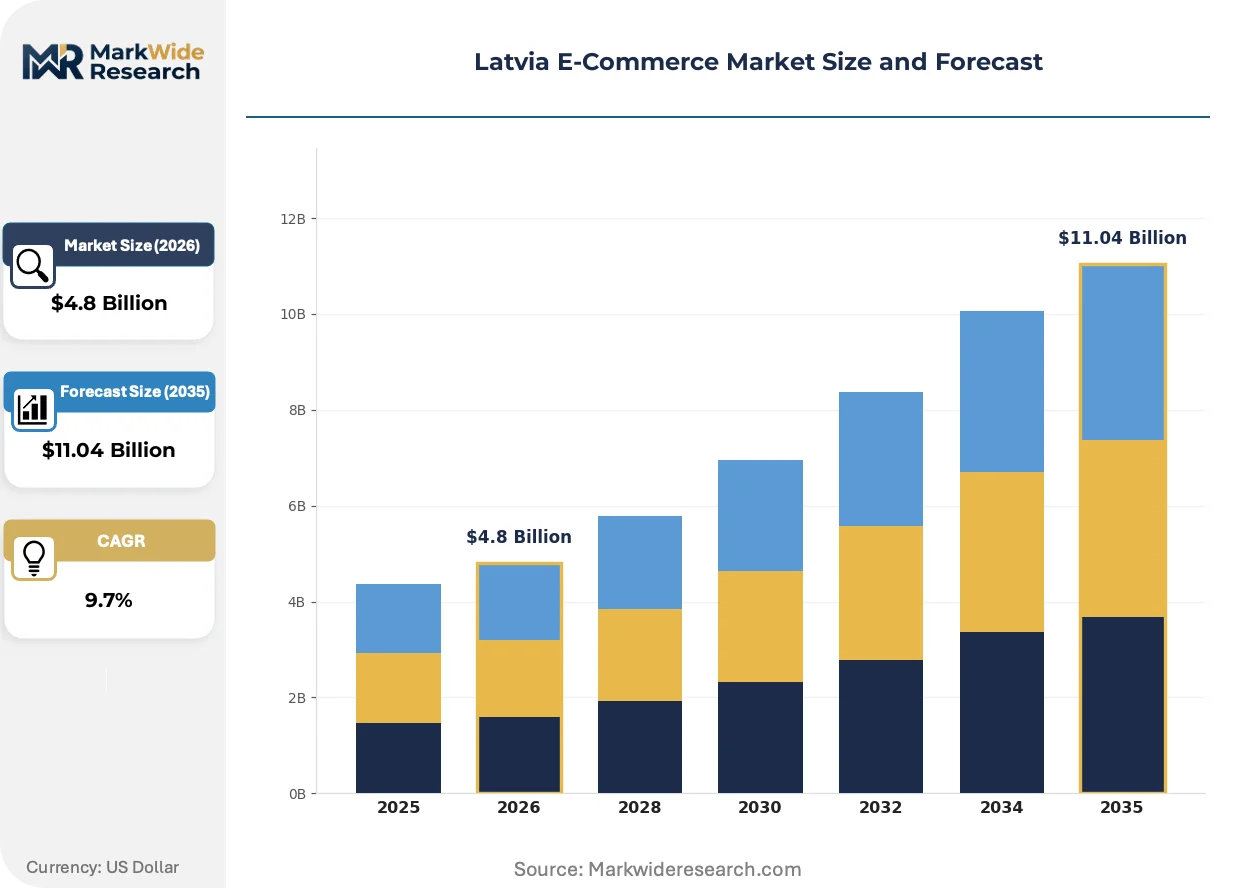
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Electronics, Home Goods, Beauty Sales Channel: Direct-to-Consumer, Online Marketplaces, Social Media, B2B Platforms Payment Method: Credit Card, PayPal, Bank Transfer, Mobile Payments Delivery Mode: Curbside Pickup, Home Delivery, Same-Day Delivery, Locker Pickup |
| Companies Covered | Pigu Latvia Sia, 220.lv, 1a.lv, Barbora.lv, e-Maxima, Euronics.lv, Dateks.lv, Elkor Retail AS, Rimi Latvia SIA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latvia E-Commerce Market Shifts & Advancements
Latvian e-commerce infrastructure is pivoting toward predictive fulfillment and embedded finance, with platform operators restructuring around real-time inventory visibility and checkout-integrated lending products.
AI-powered demand forecasting is rewriting inventory positioning strategies for seasonal categories. Mid-size fashion retailers in Riga are deploying machine learning models to pre-position stock in neighborhood micro-fulfillment nodes. This compression of safety stock requirements is freeing working capital for marketing spend reallocation.
The EU Digital Services Act disclosure requirements are mandating algorithmic audit trails for product recommendation engines. Latvian marketplace operators must now document ranking logic and provide user-facing explanation interfaces. Consumer electronics and comparison shopping platforms face the heaviest documentation burden as they re-engineer backend systems.
Subscription-based replenishment models are displacing one-off grocery purchases among dual-income households. Barbora.lv and competing platforms are bundling household staples into weekly auto-delivery schedules with flexible skip options. This behavioral shift concentrates most visibly in Riga's central districts where delivery density supports variable route optimization.
Latvia E-Commerce Market Segmentation
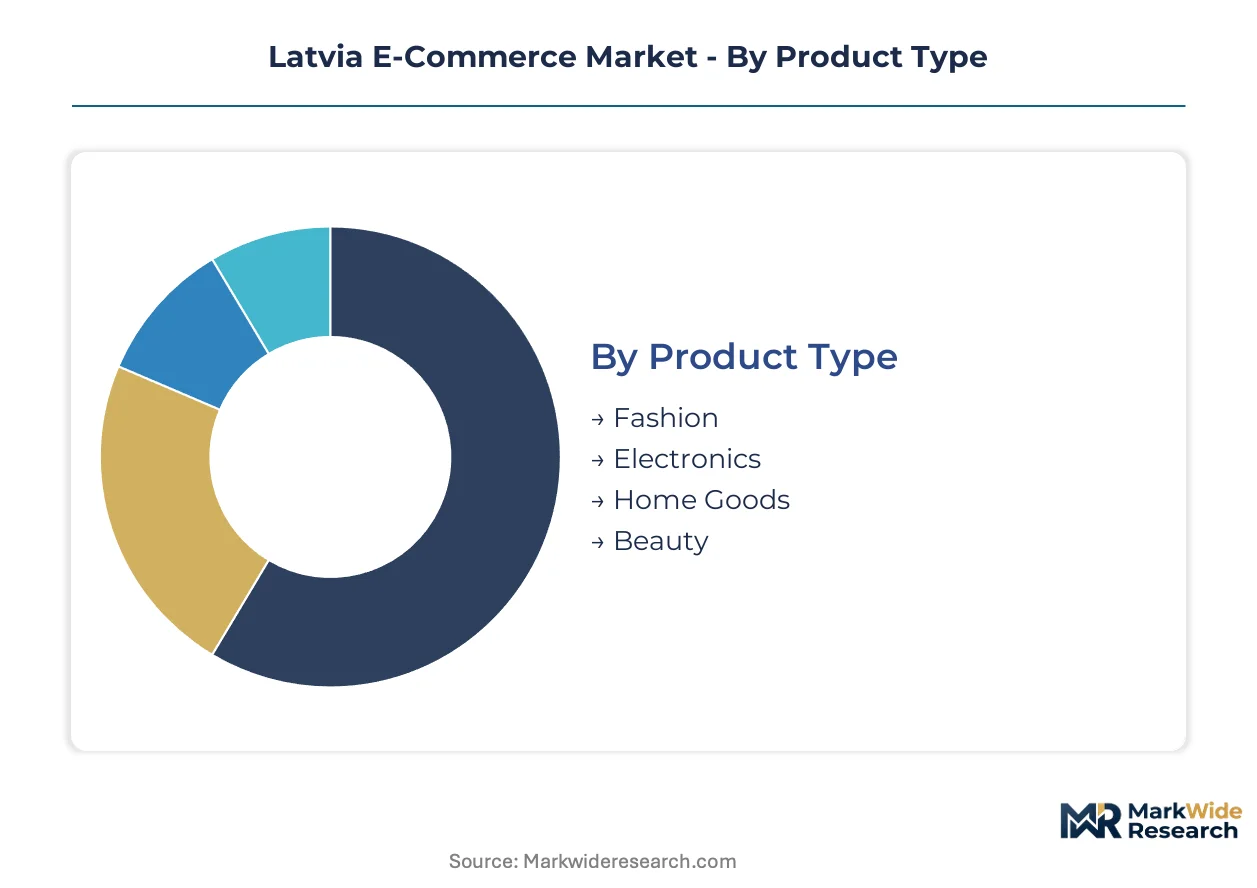
Segmentation in Latvia's e-commerce landscape reveals how purchasing behavior fragments across product preferences, channel loyalty, and fulfillment expectations. Understanding these divides enables operators to allocate warehouse capacity and marketing spend against actual revenue concentration rather than assumed uniformity.
Product Type:
Price sensitivity and purchase frequency diverge sharply across merchandise categories, with some segments rewarding inventory depth while others demand rapid trend responsiveness.
- Fashion:Apparel and accessories dominate transaction volumes through seasonal refresh cycles. Riga's urban households drive demand for international fast-fashion brands, with returns rates exceeding other categories due to sizing uncertainty.
- Electronics:Consumer devices and computing equipment carry higher average order values with extended research phases. 220.lv anchors this segment through specialized warehouse operations and technical support infrastructure.
- Home Goods:Furniture and domestic furnishings capture expanding margin pools as Latvian households invest in interior spaces. Delivery logistics complexity limits pure-play penetration.
- Beauty:Cosmetics and personal care products exhibit strong subscription and replenishment potential. Temperature-sensitive fulfillment requirements favor platforms with GDP-compliant storage.
Electronics leads on scale; home goods leads on momentum.
Sales Channel:
Customer acquisition economics vary dramatically by channel structure, with some routes offering scale efficiency while others provide margin protection through direct relationships.
- Direct-to-Consumer:Brand-owned websites and applications capture first-party data and full margin. Barbora.lv exemplifies this model with proprietary temperature-controlled last-mile infrastructure.
- Online Marketplaces:Aggregator platforms aggregate demand across multiple sellers, with Pigu Latvia Sia leveraging pan-Baltic logistics networks to sustain cross-border delivery economics.
- Social Media:Instagram and TikTok commerce channels convert impulse purchases through influencer integration. Younger demographics in Riga's central districts show highest conversion rates.
- B2B Platforms:Wholesale procurement systems serve business customers with volume pricing and invoice terms. CSRD-aligned sustainability reporting creates procurement eligibility with EU institutional buyers.
Online marketplaces lead on scale; social media leads on momentum.
Payment Method:
Checkout abandonment patterns correlate strongly with payment friction, making method availability a direct revenue determinant rather than passive infrastructure.
- Credit Card:Visa and Mastercard networks remain dominant for higher-value transactions. Chargeback protection appeals to electronics purchasers conducting substantial research.
- PayPal:Digital wallet option reduces credential entry friction for cross-border purchases. Buyer protection policies attract fashion customers concerned with merchant reliability.
- Bank Transfer:Direct debit arrangements prevail in B2B procurement and high-value home goods. Settlement delays extend merchant working capital cycles.
- Mobile Payments:Swish and Apple Pay adoption among 18-34 demographics compresses checkout abandonment rates. GDPR-compliant tokenization addresses data handling requirements.
Credit card leads on scale; mobile payments leads on momentum.
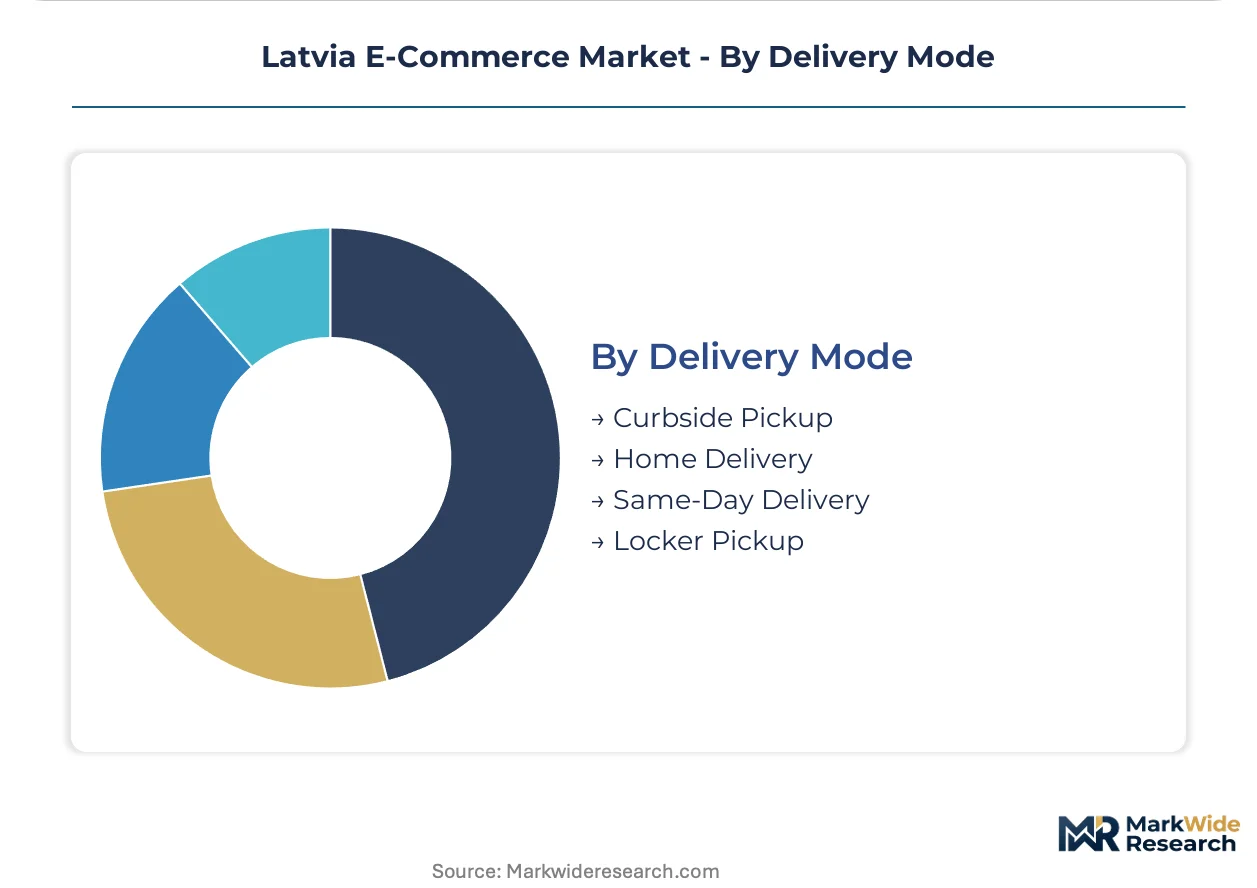
Delivery Mode:
Urban household density in the Riga metropolitan corridor enables fulfillment economics that collapse in Latvia's secondary cities, creating geographic stratification in service availability.
- Curbside Pickup:Customer collection from designated retail points eliminates last-mile costs. Grocery platforms deploy this option to extend reach beyond same-day delivery zones.
- Home Delivery:Doorstep fulfillment remains the default expectation for non-grocery categories. Driver availability constraints in Daugavpils and Liepaja inflate per-delivery costs beyond Riga baseline rates.
- Same-Day Delivery:Expedited fulfillment requires micro-fulfillment node placement and predictive inventory positioning. Temperature-controlled networks for fresh food demand GDP compliance certification.
- Locker Pickup:Automated collection points address failed delivery attempts and customer schedule constraints. Limited specialized returns processing capacity outside Riga extends refund cycle times.
Home delivery leads on scale; same-day delivery leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riga anchors Latvia's e-commerce demand through concentrated urban household density and temperature-controlled logistics infrastructure serving the metropolitan corridor.
Riga Metropolitan Area
Dual-income households and young professionals drive same-day grocery delivery adoption through platforms with GDP-compliant cold chain networks. The Consumer Rights Protection Centre enforces distance-selling standards alongside GDPR data handling requirements. Micro-fulfillment nodes in Teika and Purvciems compress last-mile delivery windows for electronics and fashion categories.
Vidzeme Region
Secondary city households in Valmiera and Cēsis generate growing cross-border purchase volumes through pan-Baltic marketplace access. EU Green Deal packaging directives mandate biodegradable fulfillment materials for warehouse operations serving this corridor. Logistics providers face driver scarcity inflating per-delivery costs above capital region baselines.
Kurzeme Region
Liepaja's port infrastructure supports import-dependent electronics retailers with specialized customs clearance capabilities. The EU Digital Services Act imposes algorithmic transparency requirements on marketplace operators serving this western coastal market. Limited returns processing capacity extends refund cycle times compared to Riga-based fulfillment.
Latgale Region
Daugavpils presents underdeveloped e-commerce saturation with customer acquisition cost advantages for early platform entrants. Distance-selling VAT thresholds and OSS registration requirements create compliance friction for inventory pooling across this eastern border zone. Temperature-controlled last-mile networks remain sparse outside grocery delivery corridors.
Zemgale Region
Jelgava's agricultural processing heritage shapes B2B procurement platform demand among food sector enterprises. CSRD-aligned sustainability reporting creates eligibility with EU institutional buyers sourcing through regional distributors. Home goods retailers target domestic investment trends as households upgrade interior spaces.
Latvia E-Commerce Market Competitive Landscape
Global majors compete with regional champions across fulfillment infrastructure and cross-border logistics capabilities, producing a tiered structure where pan-Baltic networks face off against localized direct-to-consumer platforms. Consolidation pressures intensify around last-mile density and temperature-controlled warehouse certification. Three archetypes dominate: grocery specialists with proprietary cold chain assets, electronics retailers with technical support integration, and marketplace aggregators leveraging cross-border inventory pooling. M&A activity targets logistics automation capabilities, while strategic partnerships address GDPR-compliant personalization engine development.
Among Baltic-anchored marketplace operators, Pigu Latvia Sia exemplifies the pan-Baltic logistics archetype through cross-border delivery network economics. Barbora.lv occupies the grocery specialist tier with temperature-controlled last-mile infrastructure serving urban density corridors. The 220.lv designation represents electronics-focused retailing through specialized warehouse operations and technical support capabilities.
| Leading Market Players |
|---|
| Pigu Latvia Sia |
| 220.lv |
| 1a.lv |
| Barbora.lv |
| e-Maxima |
| Euronics.lv |
| Dateks.lv |
| Elkor Retail AS |
| Rimi Latvia SIA |
| Others |
Supply & Pricing Matrix
EU Green Deal packaging mandates are compelling Latvian retailers to absorb biodegradable material premiums, forcing warehouse operators to renegotiate supplier contracts and pass selective cost adjustments to Riga's price-sensitive grocery segments while preserving electronics margins through service bundling.
Pricing Analysis
Input-cost pass-through dynamics in Latvia's e-commerce sector center on biodegradable packaging premiums and last-mile labor inflation. Three-tier pricing structure across premium, standard, and economy levels segments customers by delivery speed and temperature-control requirements. Price differentiation hinges on GDP certification for pharmaceutical fulfillment and urban density for same-day eligibility. Pricing pressure stems from driver scarcity in Daugavpils and Liepaja, compressing margins on home delivery orders outside Riga. Fashion purchasers exhibit highest price sensitivity, while B2B procurement platforms serving Zemgale's food enterprises tolerate premium positioning for CSRD-aligned sustainability documentation.
Supply Chain Analysis
EU Green Deal local-content rules for sustainable packaging materials are redirecting Latvian fulfillment networks toward certified Baltic suppliers and away from conventional plastic importers. Geographic supply concentration draws from Estonia, Lithuania, and Poland for cross-border inventory pooling, with Germany anchoring specialized electronics components. Raw material dependencies rest on biodegradable films, temperature-controlled packaging, and automated sorting equipment. Single-source vulnerability concentrates in GDP-compliant cold chain infrastructure for pharmaceutical and fresh food segments. Distribution runs through Riga's micro-fulfillment nodes, with secondary cities dependent on less frequent consolidated routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latvia's e-commerce trajectory offers margin expansion through automation-driven fulfillment cost reduction and premium-tier same-day delivery penetration among Riga's dual-income households.
For Market Incumbents: Deploy predictive inventory positioning to compress safety stock requirements and free working capital for customer acquisition in underserved secondary cities. Incumbent operators should consolidate temperature-controlled warehouse certification capabilities ahead of GDP enforcement tightening, while integrating AI-powered demand forecasting to defend against pan-Baltic marketplace entrants leveraging cross-border logistics scale. For New Entrants and Emerging Players: AI-powered personalization engines present a technology-first wedge for new entrants seeking differentiation as third-party cookie deprecation advances. White-space opportunity concentrates in Daugavpils and Liepaja, where e-commerce saturation remains underdeveloped and customer acquisition costs run below Riga baselines. New entrants should pursue GDPR-compliant first-party data activation as their go-to-market anchor, targeting fashion and beauty segments with subscription-based replenishment models. For Investors and Strategic Acquirers: Asymmetric upside sits with logistics automation specialists and GDP-certified cold chain operators as consolidation pressures intensify. Long-term viability favors platform operators with proprietary last-mile infrastructure and pan-Baltic network optionality. Investors should monitor EU Digital Services Act enforcement timelines as the inflection signal for compliance-driven M&A activity targeting content moderation and algorithmic audit capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Integration | Robotic picking systems reduce per-order fulfillment costs in Riga's micro-fulfillment nodes. |
| GDP Certification Investment | Temperature-controlled compliance opens pharmaceutical and fresh food premium segments. |
| Pan-Baltic Logistics Partnership | Cross-border inventory pooling extends product assortment without capital-intensive warehousing. |
| GDPR-Compliant Personalization Engine | First-party data activation addresses cookie deprecation while satisfying Brussels data governance. |
| Secondary City Penetration Program | Daugavpils and Liepaja entry captures customer acquisition cost advantages before saturation. |
Research Methodology
Bottom-up SKU-level demand modeling reconciled against top-down logistics capacity tracking forms the analytical core of this study. Primary interviews with e-commerce platform executives, warehouse operations directors, last-mile logistics providers, and Consumer Rights Protection Centre officials combined with secondary validation from EU Digital Services Act filings, Latvian customs trade data, and pan-Baltic retail association reports. Triangulation between bottom-up transaction volume estimates and top-down fulfillment infrastructure capacity ensures methodological robustness.
Historical trendline analysis of category-level transaction growth and delivery density patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, sales channel, payment method, and delivery mode, with regional urban density and GDP certification status as industry-specific overlays. CAGRs derive from fitted growth curves adjusted for regulatory enforcement timelines and technology adoption S-curves. Forecast inputs incorporate mobile wallet penetration trajectories and EU Green Deal packaging compliance cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Digital Services Act enforcement intensity, last-mile labor availability in secondary cities, and biodegradable packaging cost trajectories. Forecasts reflect documented assumptions regarding regulatory alignment between national enforcement and Brussels-level platform governance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
Belgium E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
United States E-Commerce Logistics Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
Retail E-Commerce Market
E-Commerce Solutions
E-Commerce in Nigeria Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Online on-Demand Laundry Service Market