
 Global Shopping Cart Market | 2026-2036
Global Shopping Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shopping Cart Market Foresight
ISO 9001 quality management certification is redrawing competitive boundaries in the shopping cart supply base. Wanzl India Pvt Ltd leverages its integrated steel-and-plastics manufacturing footprint to serve major retail chains across South Asia and the Middle East. Marmon Retail Solutions anchors its position through captive distribution networks in North America, while Sambo Corp. competes aggressively on lightweight aluminum-frame designs for Asian hypermarket operators.
Shopping carts are wheeled material-handling devices constructed from zinc-plated steel tubing, aluminum extrusions, or high-density polyethylene frames, typically rated for 80–120 kilogram load capacity and fitted with castor-mounted wheels for consumer self-service merchandise transport in retail environments. Deployment through cloud-based inventory synchronization is gaining traction among large enterprises seeking real-time cart fleet telemetry, whereas on-premises systems still dominate mid-sized retailers with legacy IT infrastructure. The hosted solution segment leads in new installations for small business applications, while self-hosted configurations retain margin strength among digital agencies managing multi-tenant retail platforms.
The US EPA regulates recycled content claims under Green Guides enforcement, while China's SAMR enforces GB standards for load-bearing consumer products; India's BIS certification mandates structural testing for imported metal carts. These frameworks compel manufacturers to document material provenance and fatigue-test protocols before market entry. Stakeholders must track evolving extended producer responsibility schemes in the European Union and emerging state-level recycled-content thresholds in California and New York.
Market Dynamics
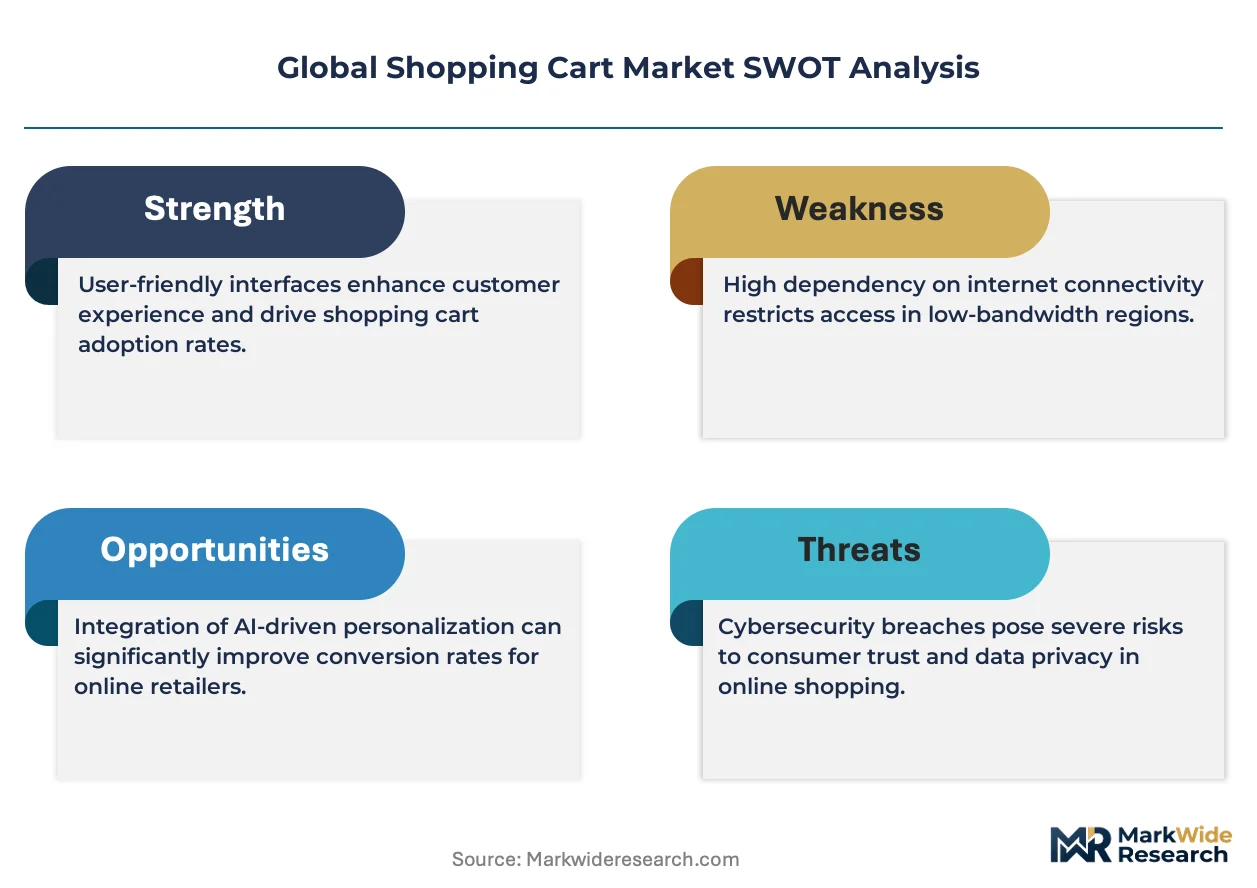
EU Green Deal circular economy mandates are forcing manufacturers to abandon virgin polymer frames and redesign for modular repairability, compressing margins for suppliers without recycled-material certification pathways.
Growth Catalysts
- Recycled polymer mandates:EU Green Deal extended producer responsibility schemes now require documented material provenance for all polymer components entering European retail supply chains.
- Fleet modernization waves:Supermarket chains in Brazil, India, and Indonesia are replacing legacy steel carts with corrosion-resistant hybrid designs rated for tropical humidity conditions.
- ISO 9001 certification barriers:Quality management certification requirements are filtering out uncertified suppliers from procurement shortlists at major retail chains across South Asia and the Middle East.
Market Restraints
- Aluminum price volatility:Lightweight frame producers face margin compression when London Metal Exchange aluminum futures spike, forcing pass-through clauses that alienate price-locked retail buyers.
- Guangdong-Zhejiang supply concentration:Metal and hybrid cart production clusters in China's eastern manufacturing corridor create single-region dependency risk for global buyers.
- Load-bearing fatigue limits:GB standards enforced by China's SAMR mandate structural testing protocols that extend product development timelines for new frame geometries.
Strategic Opportunities
- Cloud-based fleet telemetry:Real-time cart tracking via hosted inventory synchronization platforms opens recurring revenue streams among large enterprise retailers seeking asset utilization data.
- California recycled-content thresholds:Emerging state-level mandates in California and New York create first-mover advantage for suppliers with documented closed-loop polymer supply chains.
- Mid-sized retailer legacy gaps:On-premises system dominance among mid-sized retailers with dated IT infrastructure presents migration-service revenue for hybrid cloud providers.
Industry Challenges
- GB certification timelines:China's SAMR structural testing mandates create 4-6 month approval delays for imported metal cart designs, freezing inventory commitments.
- Polymer provenance documentation:Extended producer responsibility schemes require chain-of-custody records that many suppliers cannot generate without backward integration into recycling operations.
- Legacy castor integration:Wheel assembly standards vary across regional supplier bases, complicating modular repairability designs promised under circular economy frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shopping Cart Market |
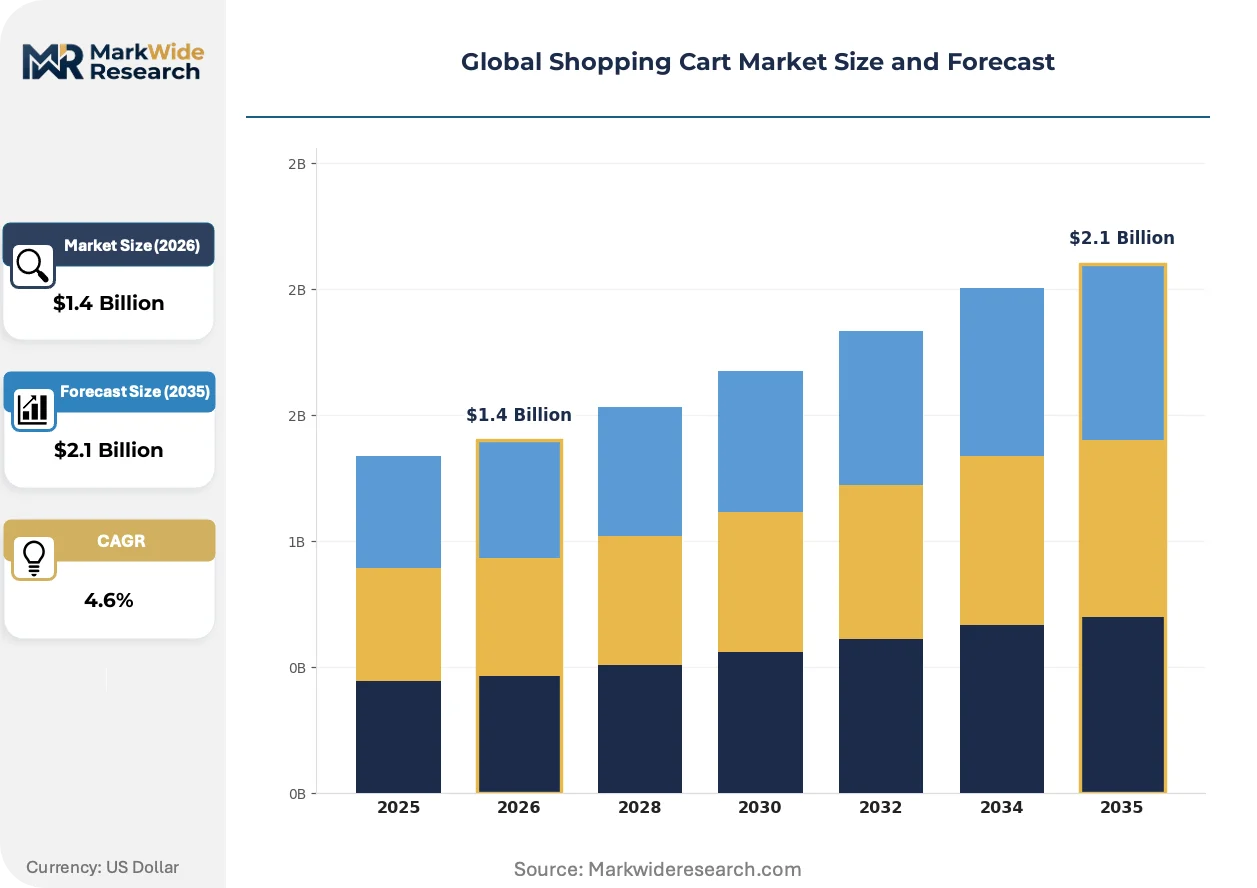
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Solution Type: Open Source, Hosted, Self-Hosted, Custom-built Application: Small Business, Mid-Sized Enterprises, Large Enterprises, Non-Profit Organizations Customer Segment: Retailers, Wholesalers, Manufacturers, Digital Agencies |
| Companies Covered | Wanzl India Pvt Ltd, Sambo Corp., Marmon Retail Solutions, Cefla s.c., Versacart Systems, Inc., Advance Carts, Inc., NATIONAL CART, Metro Carts, Cart Source, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shopping Cart Market Shifts & Advancements
Telemetry-enabled fleet management is dissolving the boundary between hardware procurement and software service contracts, rewiring how retailers evaluate total cost of ownership for material-handling assets.
RFID-embedded frame tracking is decomposing the traditional cart-as-commodity model. Mass merchandisers in North America are piloting chip-integrated zinc-plated steel designs that transmit location and utilization metrics to centralized asset platforms. This sensor convergence is compressing procurement decisions toward integrated hardware-software bundles rather than discrete unit purchases.
REACH substance restrictions are tightening allowable coatings for metal tubing used in consumer-facing retail environments. ECHA enforcement against hexavalent chromium plating is accelerating adoption of trivalent alternatives and powder-coated finishes across European supplier bases. Frame manufacturers serving EU supermarket chains are reformulating surface treatments to maintain corrosion resistance under stricter chemical authorization protocols.
Buyers are unbundling after-sales service from initial hardware contracts, forcing suppliers to compete on discrete maintenance and parts-replacement terms. Large-format retailers in Brazil and Indonesia are separating fleet refresh cycles from repair service agreements, creating standalone revenue pools for regional maintenance specialists. This procurement fragmentation is most pronounced among hypermarket operators managing multi-thousand-unit cart deployments across distributed store networks.
Global Shopping Cart Market Segmentation
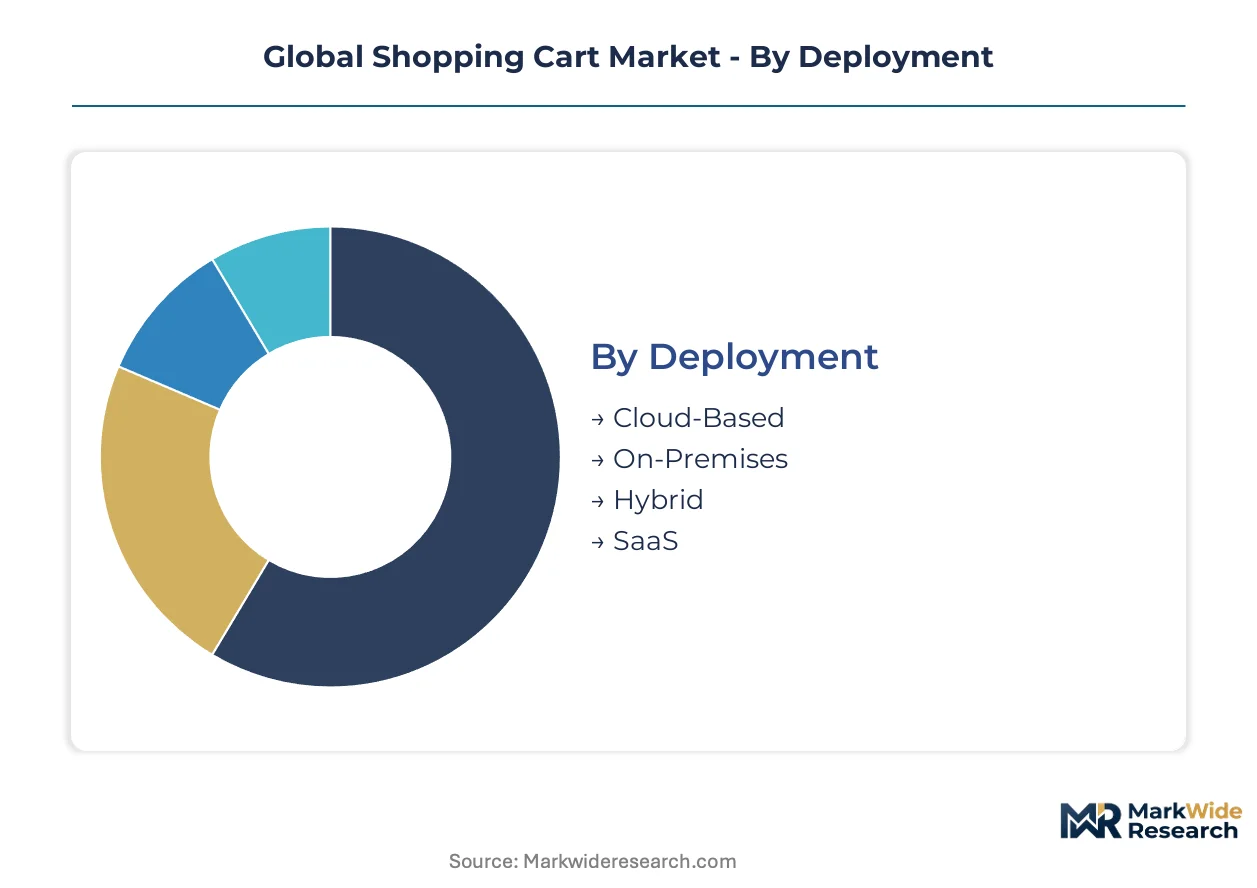
Shopping cart procurement decisions increasingly hinge on IT infrastructure maturity and compliance architecture rather than unit economics alone. Retailers segment their fleet investments across deployment models and solution architectures that align with regulatory exposure and telemetry requirements.
Deployment:
GDPR's data residency mandates and China's PIPL localization rules are forcing retailers to map deployment choices against jurisdictional data sovereignty requirements.
- Cloud-Based:Hosted inventory synchronization platforms transmit real-time cart location and utilization metrics through centralized dashboards. Large-format retailers in Germany and France select these configurations to satisfy EU Green Deal asset-tracking mandates while outsourcing infrastructure maintenance to specialized providers.
- On-Premises:Legacy server installations retain dominance among mid-sized retailers with dated IT infrastructure and limited cloud migration budgets. Brazilian supermarket chains favor these setups to avoid recurring subscription costs and maintain direct control over fleet data under ANVISA audit protocols.
- Hybrid:Split architectures process sensitive transaction data locally while pushing anonymized utilization analytics to cloud dashboards. Japanese retailers deploy these models to satisfy METI data governance guidelines without sacrificing predictive maintenance capabilities.
- SaaS:Fully managed software layers eliminate hardware procurement for digital agencies operating multi-tenant retail platforms across Southeast Asia.
On-Premises handles the majority of throughput; Cloud-Based is climbing the fastest on share.
Solution Type:
Margin structures diverge sharply between commoditized open-source implementations and captive self-hosted configurations requiring specialized integration labor.
- Open Source:Community-developed telemetry frameworks reduce licensing overhead for cost-constrained retailers. Indonesian hypermarket operators leverage these tools to pilot RFID-enabled fleet tracking without vendor lock-in, though GB certification delays for imported sensor hardware complicate deployment timelines.
- Hosted:Third-party managed platforms abstract infrastructure complexity through standardized APIs. Small business adoption concentrates in India's western states where BIS-certified suppliers bundle hardware with pre-configured software layers.
- Self-Hosted:Proprietary installations command premium pricing through customization depth and direct vendor accountability. North American mass merchandisers select these arrangements to integrate cart telemetry with existing ERP systems while satisfying EPA Green Guides documentation requirements for recycled-content claims.
- Custom-built:Bespoke development engagements serve digital agencies managing white-label retail platforms across distributed geographic footprints.
Hosted solutions capture the volume base; Self-Hosted commands the steepest expansion trajectory among enterprise accounts.
Application:
Fleet scale dictates procurement sophistication, with large enterprises unbundling hardware from software and maintenance contracts while smaller operators seek bundled simplicity.
- Small Business:Single-location retailers prioritize upfront cost minimization over telemetry depth. Hosted solutions dominate this tier, particularly among independent grocers in India's tier-2 cities where BIS certification costs for imported metal carts strain capital budgets.
- Mid-Sized Enterprises:Regional chains with 10-50 locations represent the migration-services opportunity, bridging legacy on-premises infrastructure toward hybrid cloud architectures. Brazilian operators in this bracket are separating fleet refresh cycles from repair service agreements under pressure from ANVISA operational audit requirements.
- Large Enterprises:Multi-thousand-unit deployments across distributed networks drive demand for integrated hardware-software bundles with real-time asset utilization data. EU supermarket chains in this category face EU Green Deal extended producer responsibility mandates that require documented polymer provenance across entire cart fleets.
- Non-Profit Organizations:Cooperative retail structures and social enterprise grocers select open-source or hosted solutions to minimize overhead while maintaining basic inventory visibility.
Large Enterprises absorb the dominant procurement volume; Small Business is expanding most quickly as cloud-hosted entry points lower technology barriers.
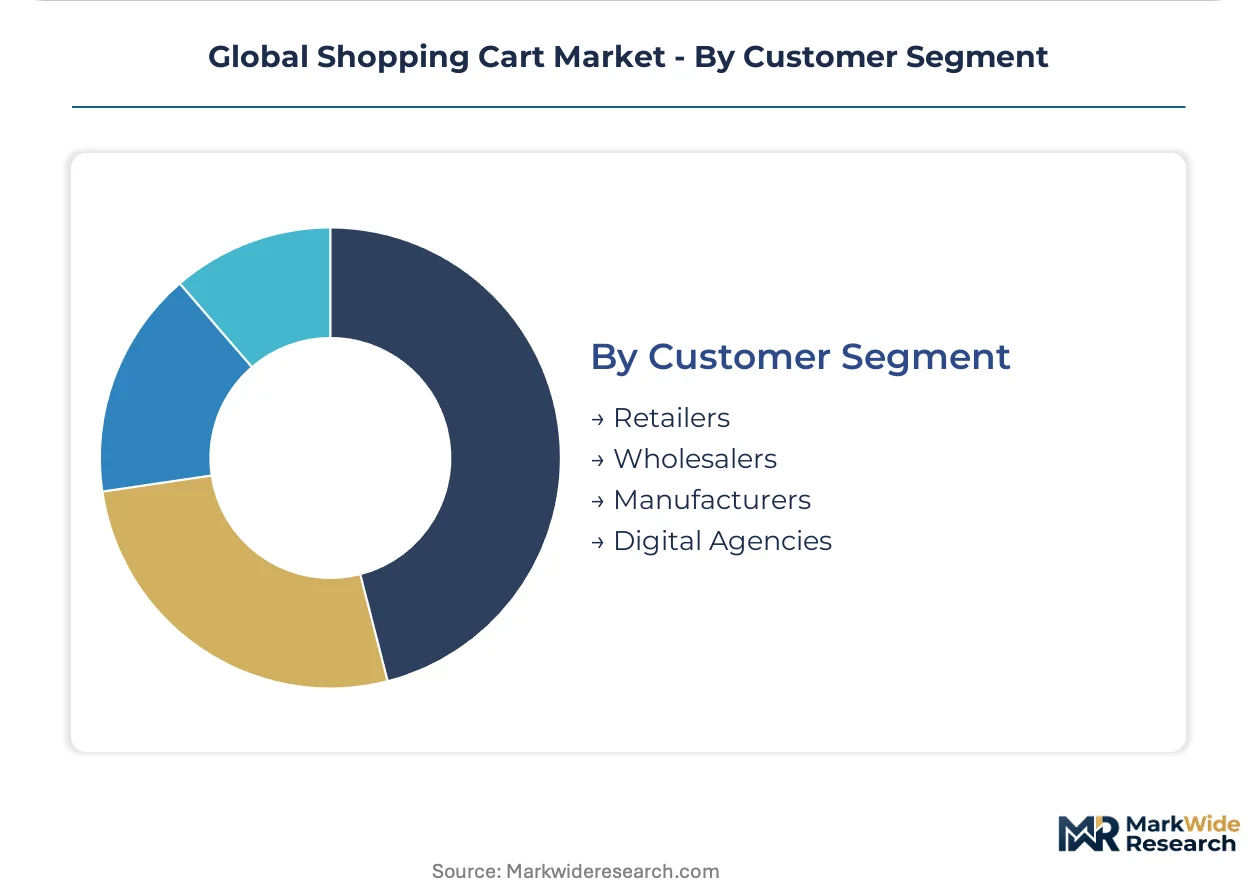
Customer Segment:
End-user technical sophistication determines whether procurement emphasizes hardware durability specifications or software integration flexibility.
- Retailers:Supermarket and hypermarket operators drive specification standards for load-bearing capacity, corrosion resistance, and modular repairability. China's SAMR GB standards enforcement creates 4-6 month approval delays that freeze inventory commitments for these buyers.
- Wholesalers:Cash-and-carry operators prioritize high-volume cart durability under intensive daily use cycles. Indonesian and Brazilian wholesalers are replacing legacy steel designs with corrosion-resistant hybrid frames rated for tropical humidity conditions.
- Manufacturers:Industrial supply houses and B2B distributors select specialized cart configurations for warehouse-to-floor merchandise transport, often integrating with existing material-handling equipment fleets.
- Digital Agencies:Multi-tenant platform operators procure cart telemetry as a service layer, reselling integrated hardware-software bundles to downstream retail clients under white-label arrangements.
Retailers command the predominant procurement volume; Digital Agencies are gaining share fastest as telemetry-enabled fleet management dissolves boundaries between hardware and software contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hypermarket operators and supermarket chains in Brazil, India, and Indonesia are accelerating fleet modernization programs, while EU retailers face circular economy mandates that reshape procurement specifications. Quality certification requirements and recycled-content thresholds are fragmenting supplier access across major demand centers.
United States
Mass merchandisers are piloting RFID-embedded frame tracking systems that transmit utilization metrics to centralized asset platforms. EPA Green Guides enforcement compiles documentation requirements for recycled-content claims on polymer components. Chicago and Dallas distribution corridors host the densest fleet telemetry integration specialists serving North American retail networks.
Germany
Supermarket chains face EU Green Deal extended producer responsibility mandates requiring documented polymer provenance across entire cart fleets. ECHA enforcement against hexavalent chromium plating accelerates adoption of trivalent alternatives and powder-coated finishes. Stuttgart and Hamburg manufacturing zones concentrate modular repairability design specialists serving EU-wide retail procurement.
China
Guangdong and Zhejiang provinces host the densest supplier clusters for metal and hybrid cart production serving export markets. SAMR enforces GB standards for load-bearing consumer products that mandate structural testing protocols extending product development timelines. Shenzhen and Ningbo industrial parks concentrate corrosion-resistant frame fabricators rated for tropical humidity conditions.
Brazil
Supermarket chains are replacing legacy steel carts with corrosion-resistant hybrid designs rated for tropical humidity conditions. ANVISA operational audit requirements pressure operators to separate fleet refresh cycles from repair service agreements. São Paulo and Rio de Janeiro metropolitan areas concentrate regional maintenance specialists managing multi-thousand-unit cart deployments.
India
Major retail chains filter procurement shortlists through ISO 9001 quality management certification requirements that exclude uncertified suppliers. BIS certification mandates structural testing for imported metal carts, straining capital budgets for independent grocers in tier-2 cities. Mumbai and Delhi-NCR logistics hubs anchor integrated steel-and-plastics manufacturing footprints serving South Asian and Middle Eastern markets.
Global Shopping Cart Market Competitive Landscape
Player mix skews toward integrated manufacturers with captive material processing capabilities and specialized regional fabricators with certification depth. The competitive structure concentrates around three strategic archetypes: integrated steel-and-plastics manufacturers serving multi-regional retail chains, aluminum-frame specialists competing on lightweight designs for tropical markets, and captive distribution networks anchoring North American service coverage. Dominant competitive moves include backward integration into recycled polymer supply chains and geographic expansion through localized certification acquisition.
Among integrated manufacturers, Wanzl India Pvt Ltd occupies a position exemplifying the steel-and-plastics fabrication archetype with multi-regional reach. Sambo Corp. represents the lightweight aluminum-frame specialization vector targeting Asian hypermarket operators. Marmon Retail Solutions anchors the captive distribution network archetype with concentrated North American presence. These three entities collectively illustrate how certification pathways, material integration, and regional service density define competitive positioning in procurement decisions.
| Leading Market Players |
|---|
| Wanzl India Pvt Ltd |
| Sambo Corp. |
| Marmon Retail Solutions |
| Cefla s.c. |
| Versacart Systems, Inc. |
| Advance Carts, Inc. |
| NATIONAL CART |
| Metro Carts |
| Cart Source |
| Others |
Supply & Pricing Matrix
Recycled polymer substitution for virgin polypropylene frames is redrawing supplier economics by compressing margins for uncertified producers while rewarding backward-integrated recyclers with pricing power in EU procurement.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange aluminum futures dominate lightweight frame procurement, forcing pass-through clauses that alienate price-locked retail buyers during commodity spikes. Three-tier pricing structure across premium ISO 9001-certified, standard BIS-compliant, and economy non-certified levels stratifies the market. Cost compression in economy-tier steel tubing intensifies because Guangdong suppliers absorb margin erosion to maintain volume commitments. Small independent grocers in India's tier-2 cities exhibit highest price sensitivity, while EU supermarket chains prioritize certified provenance over unit cost.
Supply Chain Analysis
Strategic stockpiling of corrosion-resistant polymer compounds prevails over just-in-time approaches among Brazilian and Indonesian operators managing tropical humidity exposure. Manufacturing concentrates in China, India, and Germany, with raw material dependencies spanning aluminum extrusions, high-density polyethylene resin, and zinc-plated steel tubing. Single-region vulnerability in Guangdong-Zhejiang clusters creates inventory freeze risk when SAMR extends GB certification timelines. Distribution runs through captive regional maintenance networks in North America and specialized logistics hubs serving South Asian retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry-enabled fleet management transforms hardware procurement into recurring service contracts, with cloud-based asset utilization analytics expanding faster than cart unit sales among large-format retailers.
For Market Incumbents: Consolidate backward integration into closed-loop polymer recycling operations to defend margin position against EU Green Deal extended producer responsibility mandates. Acquire ISO 9001 certification depth in South Asian supplier bases before quality barriers harden procurement shortlists at major retail chains.
For New Entrants and Emerging Players: Lead with lightweight aluminum-frame designs targeting Indonesian and Brazilian hypermarket operators replacing legacy steel fleets under tropical humidity requirements. Pursue white-label telemetry integration partnerships with digital agencies managing multi-tenant retail platforms across Southeast Asia.
For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors integrated steel-and-plastics manufacturers with captive material processing capabilities. Long-term viability hinges on documented polymer provenance systems rather than commodity fabrication scale. Watch for California and New York recycled-content threshold enforcement as the inflection signal triggering premium pricing for closed-loop suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polymer Supply | EU Green Deal mandates render virgin polymer frames non-compliant, rewarding closed-loop recyclers with procurement preference. |
| Cloud-Based Fleet Telemetry Platform Launch | German and French retailers outsource infrastructure maintenance while satisfying real-time asset-tracking requirements under circular economy frameworks. |
| ISO 9001 Certification Acquisition in South Asia | Quality management barriers filter uncertified suppliers from Mumbai and Delhi-NCR procurement shortlists serving Middle Eastern export markets. |
| Corrosion-Resistant Hybrid Frame Manufacturing Scale-Up | São Paulo and Rio de Janeiro maintenance specialists require tropical-rated designs as Brazilian chains abandon legacy steel cart fleets. |
| Strategic Partnership with Digital Agency Networks | Southeast Asian multi-tenant platform operators resell integrated hardware-software bundles under white-label arrangements. |
Research Methodology
A standing panel of retail fleet procurement directors, aftermarket maintenance specialists, polymer recycling operations managers, and BIS certification auditors provided ongoing calibration against secondary validation from customs trade records, SEC filings of listed retail equipment suppliers, SAMR GB standards documentation, and EU ECHA substance restriction updates. Bottom-up unit shipment estimates triangulated with top-down retail square footage expansion projections across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across deployment model, solution architecture, fleet scale tier, and regional regulatory cluster segmentation dimensions. CAGRs derived from logistic curve fitting to technology adoption patterns and replacement cycle analysis, with aluminum price volatility and certification timeline assumptions stress-tested against historical SAMR approval data.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt aluminum supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding fleet modernization waves and telemetry adoption curves. Revision becomes warranted when recycled-content threshold implementation crosses enforcement thresholds in California or New York.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Europe Dropshipping Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
LAMEA Dropshipping Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
Serbia E-Commerce Market