
 Global Ecommerce Platform Market | 2026-2036
Global Ecommerce Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ecommerce Platform Market Foresight
Enterprise buyer concentration around omnichannel retail is hardening as legacy merchants consolidate digital operations onto fewer platforms. Shopify leverages its merchant services ecosystem to sustain recurring revenue from mid-market sellers. Alibaba Group anchors cross-border trade infrastructure between Chinese manufacturers and overseas buyers. JD.com competes through captive logistics networks that guarantee same-day fulfillment in tier-one Chinese cities.
An ecommerce platform is a software application enabling online commercial transactions through catalog management, payment processing, and order fulfillment orchestration, typically deployed via cloud infrastructure with API extensibility for third-party integrations. SaaS and cloud-based deployments now dominate new vendor selection due to lower capital requirements and automatic security patching cycles. Self-hosted platforms retain traction among large corporations demanding data sovereignty and custom checkout flows. Subscription services and B2B services represent the fastest-expanding application segments as recurring billing engines and procurement portals mature.
The EU Digital Services Act and GDPR impose content moderation and data localization obligations that elevate compliance costs for platform operators serving European consumers. The FTC in the United States scrutinizes marketplace fee structures and seller data usage under antitrust frameworks, pressuring revenue model transparency. China's SAMR enforces anti-monopoly provisions against dominant domestic platforms, constraining exclusive merchant agreements. Stakeholders must monitor regulatory divergence across jurisdictions when architecting multi-region deployment strategies and local entity structures.
Market Dynamics
Merchant consolidation onto unified commerce stacks is compressing vendor count as enterprises abandon fragmented point solutions for integrated SaaS suites with native payment, logistics, and analytics modules.
Growth Catalysts
- GDPR and EU Digital Services Act:Compliance mandates are forcing European merchants toward certified platform providers with built-in data localization and content moderation tooling, accelerating vendor switching cycles.
- Mobile-first commerce penetration:Smartphone transaction volumes in India, Southeast Asia, and Brazil are hardening demand for lightweight, low-bandwidth storefront architectures optimized for emerging market connectivity.
- Headless commerce architecture:API-first decoupling of frontend presentation from backend commerce engines is enabling brands to deploy custom experiences across IoT, social, and voice channels without platform migration.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud control the underlying compute layers for most SaaS platforms, creating single-point-of-failure exposure during regional outages or price hikes.
- Payment processor lock-in:Proprietary gateway ecosystems at major platforms impose switching costs that trap mid-market merchants in suboptimal fee structures and limited currency support.
- Technical debt in self-hosted legacy:On-premise Magento and WooCommerce installations accumulate security patch backlogs that expose merchants to PCI-DSS audit failures and breach liability.
Strategic Opportunities
- B2B procurement portal expansion:Wholesale and manufacturing buyers in Germany and the United States are migrating from EDI networks to self-service ecommerce portals with contract pricing and approval workflows.
- Embedded finance convergence:Integration of lending, insurance, and treasury services directly into checkout flows is opening new revenue streams for platforms serving cash-constrained SMBs.
- India's ONDC protocol:The Open Network for Digital Commerce is dismantling marketplace monopolies by enabling decentralized, interoperable transactions between independent sellers and logistics providers.
Industry Challenges
- Platform engineering talent scarcity:Shortages of engineers skilled in distributed systems, payment security, and multi-tenant architecture are inflating compensation and slowing product roadmaps.
- Cross-border tax automation complexity:Real-time calculation of VAT, GST, and sales tax across hundreds of jurisdictions requires continuous regulatory monitoring and frequent rule-engine updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ecommerce Platform Market |
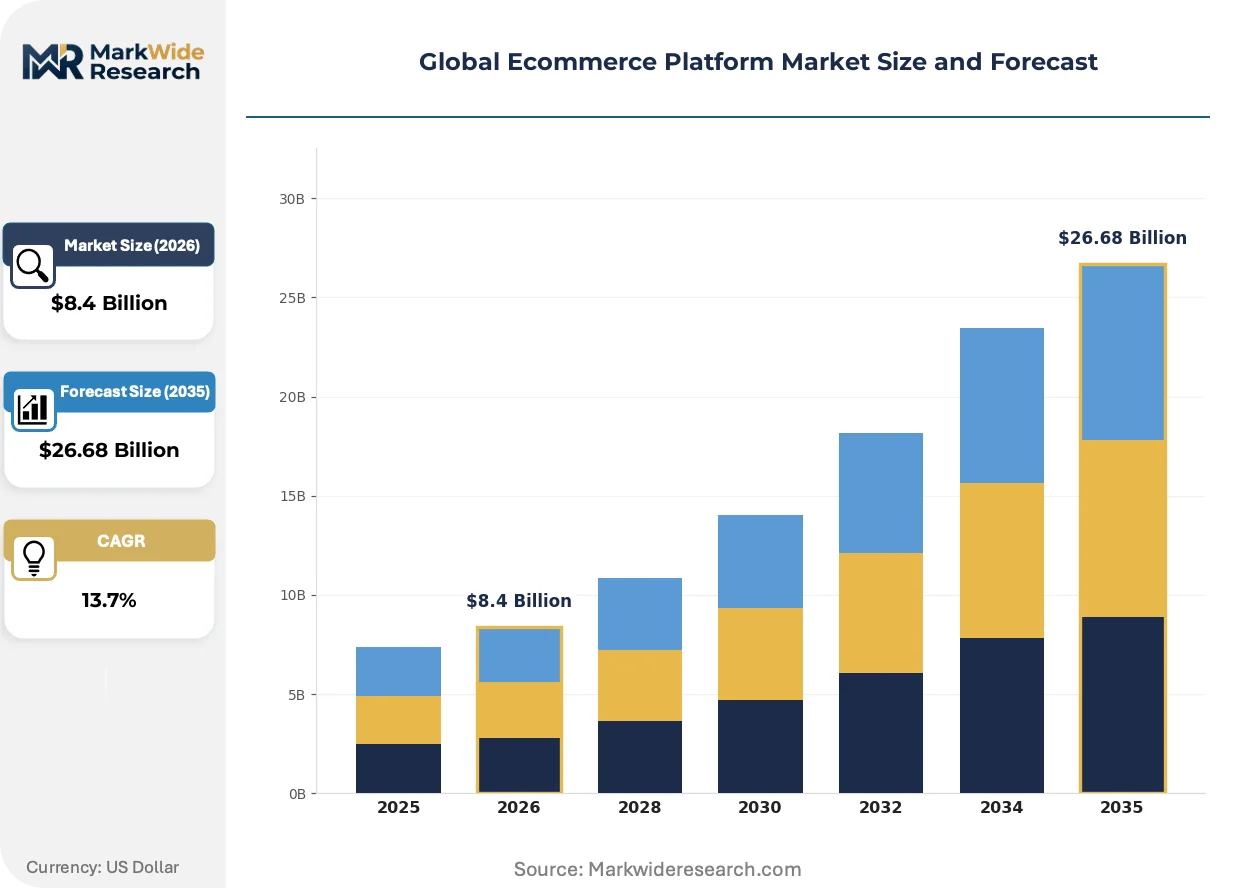
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Hosted, Self-Hosted, Cloud-Based, Open Source, SaaS Customer Type: Small Enterprises, Mid-Sized Businesses, Large Corporations, Freelancers, Nonprofit Organizations Distribution Channel: Direct Sales, Online Marketplaces, Affiliate Networks, Social Media Commerce, Mobile Commerce Application: Retail, Wholesale, Subscription Services, Digital Goods, B2B Services |
| Companies Covered | Amazon, Shopify, Alibaba Group, Pinduoduo, Shopee, eBay, Walmart Marketplace, JD.com, MercadoLibre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ecommerce Platform Market Shifts & Advancements
Composable commerce stacks are displacing monolithic suites as merchants demand granular control over customer data and experience layers without vendor lock-in.
Headless content management systems are consolidating storefront presentation across mobile apps, smart displays, and social commerce endpoints. Retailers in fashion and consumer electronics are adopting these architectures fastest, deploying React or Vue.js frontends that consume unified commerce APIs. This consolidation is collapsing the traditional boundary between content marketing and transactional commerce, compressing vendor relationships into fewer strategic contracts.
China's SAMR anti-monopoly enforcement is prohibiting exclusive merchant agreements and forced "choose one of two" arrangements that previously locked sellers into single platforms. Domestic marketplace operators must now permit multi-homing without retaliation. Cross-border sellers targeting Chinese consumers are restructuring partnership strategies to comply while maintaining fulfillment efficiency through JD.com's captive logistics or Cainiao's open network.
Subscription billing models are displacing perpetual licenses and transaction-percentage pricing among mid-market software buyers. Merchants in wellness, pet supplies, and specialty foods are demanding native recurring revenue engines with pause, skip, and churn prediction features. This shift is most pronounced in the United States and United Kingdom, where venture-backed DTC brands prioritize predictable cash flow over upfront platform investment.
Global Ecommerce Platform Market Segmentation
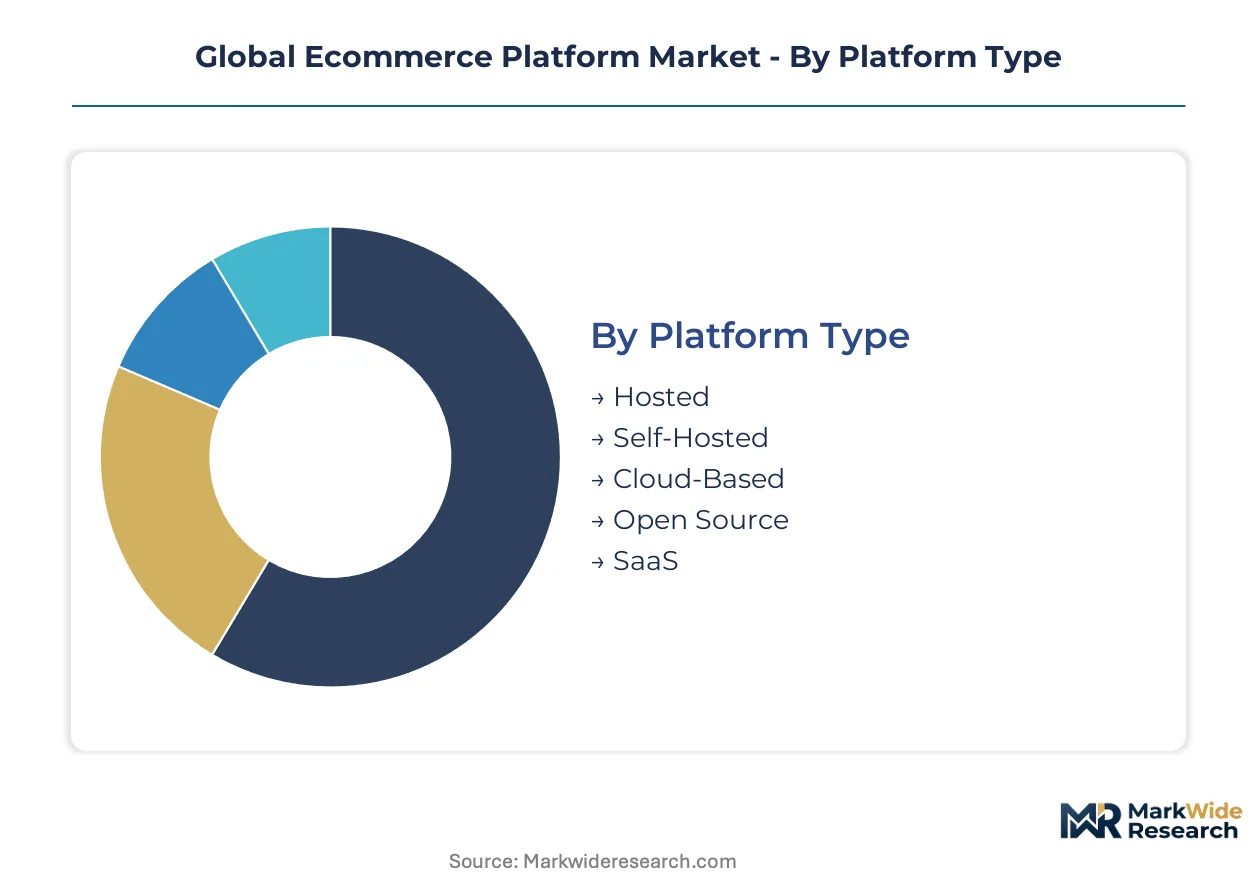
Platform selection criteria diverge sharply across merchant scale and technical maturity, with deployment architecture and customer type together determining vendor switching costs and lifetime value profiles. Segmentation reveals where SaaS consolidation concentrates versus where self-hosted sovereignty retains pricing power.
Platform Type:
Technical ownership models separate buyers by capital intensity, compliance burden, and customization depth.
- Hosted:Fully managed infrastructure where vendors control server provisioning, security patching, and CDN optimization. German and French retailers facing GDPR data localization mandates drive demand for EU-zone hosted deployments with certified data residency.
- Cloud-Based:Elastic compute resources provisioned across AWS, Azure, or Google Cloud with auto-scaling storefront capacity during traffic spikes. Indian and Brazilian merchants prioritize cloud architectures that minimize upfront infrastructure spend while accommodating volatile mobile transaction volumes.
- SaaS:Subscription licensing with bundled feature updates and native payment integrations. Mid-market sellers in the United States and United Kingdom favor predictable operating expenditure over capital-intensive platform builds.
- Self-Hosted:On-premise or dedicated private cloud installations granting full data sovereignty and custom checkout flow control. Large Japanese and South Korean conglomerates demand self-hosted stacks to satisfy METI data governance expectations and integrate with legacy ERP systems.
- Open Source:Community-developed codebases permitting unrestricted modification and zero licensing fees. Developer-heavy merchant segments in Poland and Ukraine leverage open source to avoid platform commission structures.
SaaS leads volumes today; cloud-based deployments are gaining share fastest.
Customer Type:
Organizational scale dictates feature complexity requirements and sales cycle duration.
- Large Corporations:Enterprise merchants with multi-brand portfolios requiring unified commerce orchestration across dozens of regional storefronts. These buyers command dedicated customer success teams and negotiate custom SLA terms.
- Mid-Sized Businesses:Revenue-stable merchants with 10-100 employees seeking integrated payment, logistics, and analytics without engineering overhead. This segment shows the steepest expansion trajectory as formerly self-hosted merchants migrate to managed solutions.
- Small Enterprises:Owner-operated businesses with sub-million-dollar annual revenue prioritizing template-based storefront launch speed over customization depth.
- Freelancers:Individual sellers and side-project operators utilizing free tiers and marketplace-style onboarding with minimal configuration.
- Nonprofit Organizations:Mission-driven entities requiring donation-optimized checkout flows, tax-exempt payment processing, and grant-funded platform subsidies.
Mid-sized businesses lead volumes today; large corporations are expanding contract values fastest.
Distribution Channel:
Customer acquisition mechanics determine platform native tooling requirements and revenue share economics.
- Mobile Commerce:Smartphone-optimized storefronts with biometric checkout and wallet integration. Southeast Asian and Nigerian merchants depend on mobile channels where smartphone penetration outpaces desktop infrastructure.
- Social Media Commerce:Native purchasing within Instagram, TikTok, and WeChat environments without platform exit. Brazilian and Indonesian DTC brands build entire operations around social discovery-to-purchase funnels.
- Direct Sales:Merchant-controlled traffic through owned domains and email marketing with minimal intermediary commission.
- Online Marketplaces:Amazon, Mercado Libre, and Shopee storefronts requiring multi-channel inventory synchronization and fee optimization tooling.
- Affiliate Networks:Performance-based partner programs with commission tracking and influencer payout automation.
Direct sales leads volumes today; social media commerce is climbing the fastest.
Application:
Transaction archetype shapes platform architecture around inventory models, billing cadence, and buyer-seller relationship depth.
- B2B Services:Procurement portals with contract pricing tiers, approval workflows, and punchout catalog integration. German manufacturing buyers and United States healthcare distributors are migrating from EDI networks to self-service ecommerce portals.
- Subscription Services:Recurring billing engines with pause, skip, and churn prediction capabilities. Wellness and pet supply merchants in the United States and United Kingdom prioritize predictable cash flow over upfront platform investment.
- Retail:Standard consumer goods transactions with SKU-based inventory and promotional pricing engines.
- Wholesale:Bulk quantity pricing, minimum order thresholds, and net-term payment scheduling for reseller networks.
- Digital Goods:License-key distribution, download access control, and usage-based metering for software and media products.
Retail leads volumes today; B2B services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's mobile-first commerce expansion contrasts with Germany's B2B procurement digitization, revealing divergent regional growth vectors. Regulatory fragmentation shapes vendor certification requirements across jurisdictions. Merchant platform selection increasingly depends on local data residency mandates and payment infrastructure maturity.
United States
Subscription commerce engines and DTC brand proliferation drive platform demand among mid-market merchants. FTC antitrust scrutiny of marketplace fee structures pressures revenue model transparency. Austin and Los Angeles host dense clusters of venture-backed ecommerce operators migrating to composable SaaS stacks.
China
Live-streaming commerce integration and same-day fulfillment networks anchor domestic platform competition. SAMR anti-monopoly enforcement prohibits exclusive merchant agreements previously locking sellers to single platforms. Shenzhen and Hangzhou concentrate cross-border export operators leveraging JD.com captive logistics and Cainiao open networks.
Germany
Industrial B2B procurement portal adoption accelerates as manufacturing buyers abandon legacy EDI systems. GDPR data localization mandates push merchants toward EU-zone hosted deployments with certified residency. Munich and Stuttgart harbor dense concentrations of automotive and machinery suppliers deploying self-service ecommerce workflows.
Brazil
Social commerce penetration and mobile wallet integration dominate merchant platform requirements. Central bank PIX instant payment infrastructure reduces checkout friction for smartphone-first consumers. São Paulo anchors the ecosystem of DTC brands building operations around Instagram and TikTok discovery-to-purchase funnels.
United Kingdom
Mid-market merchant consolidation onto unified commerce stacks drives vendor switching cycles toward integrated SaaS suites. FCA consumer credit regulations shape embedded finance integration at checkout. London and Manchester concentrate fashion and wellness brands prioritizing recurring revenue engines with churn prediction capabilities.
Global Ecommerce Platform Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base organizes around three strategic archetypes: horizontal marketplace operators with captive logistics, vertical SaaS providers with merchant service ecosystems, and open-source platform specialists serving developer-heavy segments. Consolidation pressure intensifies as mid-market merchants abandon fragmented point solutions. Dominant competitive moves include strategic partnerships between payment processors and logistics networks, plus geographic expansion through localized compliance certification.
Within the horizontal marketplace tier, Amazon and Alibaba Group occupy positions defined by fulfillment infrastructure scale and cross-border trade facilitation. Shopify exemplifies the vertical SaaS archetype through recurring revenue models anchored to merchant services rather than transaction percentages. These three companies represent divergent strategic bets on whether commerce value concentrates in logistics control, software subscription, or marketplace liquidity.
| Leading Market Players |
|---|
| Amazon |
| Shopify |
| Alibaba Group |
| Pinduoduo |
| Shopee |
| eBay |
| Walmart Marketplace |
| JD.com |
| MercadoLibre |
| Others |
Supply & Pricing Matrix
Cloud infrastructure spend flows from AWS, Azure, and Google Cloud through SaaS platform vendors into tiered subscription pricing for mid-market merchants, with EU data localization requirements adding compliance premiums to hosted deployments serving German and French retailers.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for lightweight, mobile-optimized storefront architectures as local cloud regions mature. SaaS subscription tiers dominate, separating enterprise merchants with custom SLA negotiations from mid-market sellers on standardized plans. Price differentiation rests on data residency certification and native payment gateway integration. Pricing pressure stems from India's ONDC protocol enabling decentralized, zero-commission transactions. Freelancers and small enterprises exhibit highest price sensitivity, while large corporations prioritize sovereignty over cost.
Supply Chain Analysis
Single-source vulnerability sits with AWS's us-east-1 and eu-west-1 regions, where concentrated outages cascade through dependent SaaS platforms. Cloud infrastructure draws from United States, Ireland, and Singapore data center clusters. Raw material dependencies span server-grade silicon, submarine fiber capacity, and renewable energy credits for carbon-neutral hosting claims. Tariff exposure runs through cross-border data transfer mechanisms under GDPR adequacy decisions. Distribution runs through API-first delivery models with edge CDN nodes localizing storefront rendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ecommerce Platform Market functions as a geographic-arbitrage play where EU compliance costs exceed Southeast Asian infrastructure spend by multiples, rewarding vendors with modular deployment architectures that port across regulatory regimes.
For Market Incumbents: Lock in mid-market merchants through embedded finance convergence, bundling lending and treasury services that raise switching costs. Expand EU-zone hosted capacity to capture GDPR-mandated vendor switching cycles. Defend against headless commerce specialists by acquiring API management platforms.
For New Entrants and Emerging Players: Capture B2B procurement portal white space in German manufacturing and United States healthcare distribution, segments abandoning EDI networks for self-service workflows. Target India's ONDC protocol integration as the most penetrable geography, where decentralized infrastructure dismantles incumbent marketplace lock-in. Lead with open-source storefront cores and revenue models anchored to logistics orchestration rather than transaction percentages.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized businesses abandon fragmented point solutions for unified SaaS suites, compressing vendor counts. Long-term viability favors platforms with captive logistics networks or merchant services ecosystems rather than pure software licensing. Watch India's ONDC transaction volume growth as the signal indicating whether decentralized protocols can dismantle marketplace monopolies at scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion | EU data residency certification captures GDPR-mandated vendor switching among German and French retailers. |
| Platform Integration | Headless commerce API consolidation enables custom IoT and social channel deployments without migration. |
| Strategic Partnership | Payment processor alliances with logistics networks compress checkout-to-delivery latency for same-day fulfillment. |
| Acquisition of Specialist Firm | Recurring billing engine specialists add churn prediction capabilities for wellness and pet supply merchants. |
| Product Launch | B2B procurement portals with contract pricing tiers capture manufacturing buyers migrating from EDI systems. |
Research Methodology
Direct dialogue with platform engineering directors, merchant services executives, cloud infrastructure procurement leads, and regulatory compliance officers grounded the qualitative assessment. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, EU Digital Services Act implementation guidance, and customs data on cross-border SaaS licensing. Bottom-up merchant adoption modeling triangulated against top-down market sizing across deployment architectures.
Segment-level projections emerged from modeling deployment type, customer scale, application archetype, and regional regulatory cluster interactions across the analysis window. CAGRs derived from logistic curve fitting to mobile commerce penetration rates and B2B portal adoption velocity in manufacturing verticals. Forecast inputs incorporated India's ONDC transaction protocol diffusion and EU GDPR enforcement intensity indices.
SAMR anti-monopoly enforcement escalation, FTC marketplace fee scrutiny, and ONDC protocol adoption velocity are the dominant revision risks that could compress or extend vendor consolidation timelines. Forecasts reflect documented assumptions about mobile-first commerce penetration and cloud infrastructure regionalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
India E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
India E-Commerce Warehousing Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
Global Omnichannel Retail Commerce Platform Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market