
 E-Commerce Buy Now Pay Later Market | 2026-2036
E-Commerce Buy Now Pay Later Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Buy Now Pay Later Market Foresight
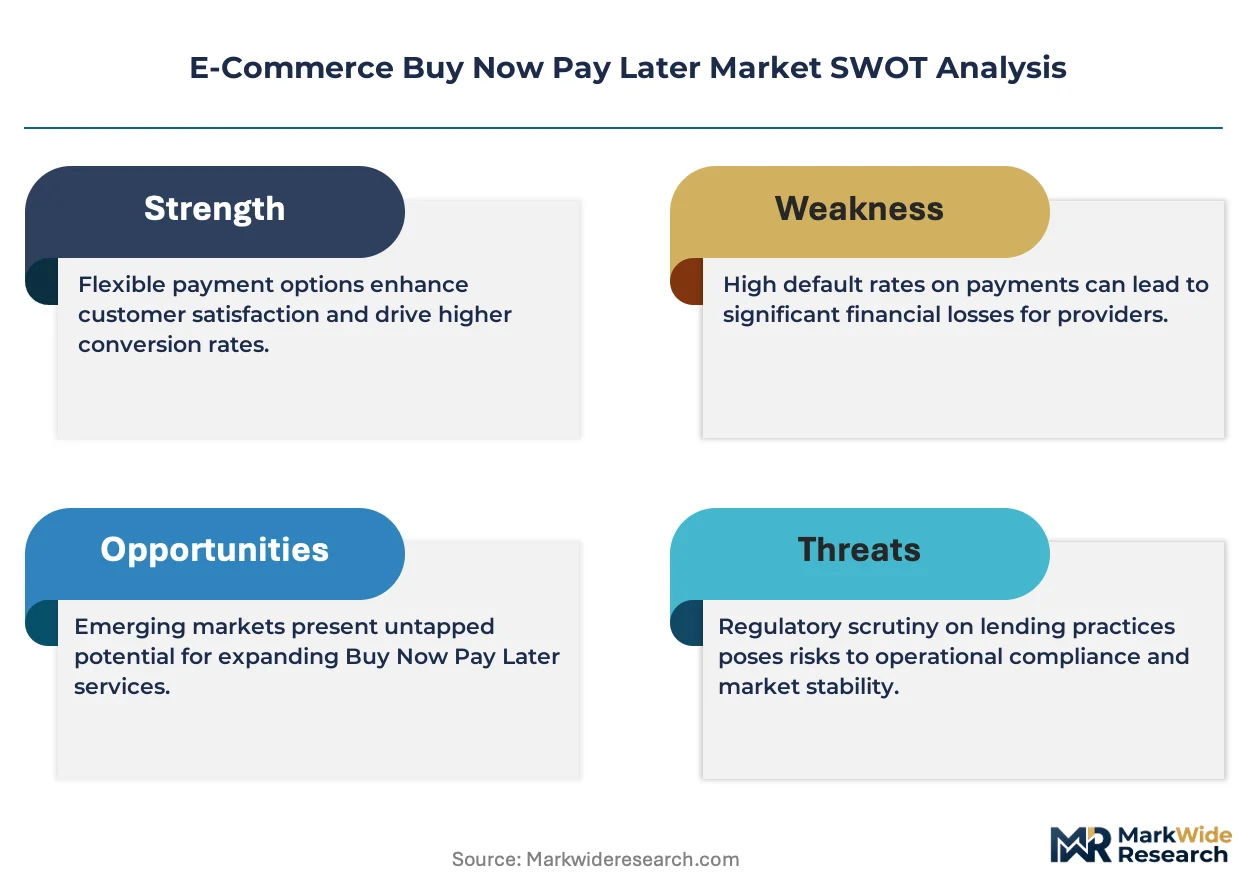
The capital-intensity gap between bank-backed platforms and pure-play fintechs is collapsing as balance-sheet requirements for funding installment loans escalate. Klarna leverages its European banking license to sustain lower cost of funds across multiple jurisdictions. Affirm differentiates through proprietary risk models and direct merchant integrations with large retailers. PayPal anchors its BNPL expansion within an existing two-sided network of consumers and merchants.
E-Commerce Buy Now Pay Later denotes a point-of-sale financing mechanism enabling consumers to split purchases into multiple installments, typically interest-free for short terms, with underwriting decisions rendered in milliseconds via algorithmic risk assessment. The primary commercial purpose is to reduce checkout friction and increase conversion rates for online merchants while generating revenue through merchant fees and, in some cases, consumer interest charges. Digital wallet-funded BNPL transactions are capturing disproportionate growth as smartphone-native payment behaviors displace card-on-file preferences among younger cohorts. Fintech companies dominate service provision in terms of user-facing brand recognition, yet traditional banks are building embedded offerings that exploit existing deposit bases and regulatory compliance infrastructure.
The Consumer Financial Protection Bureau in the United States, the Financial Conduct Authority in the United Kingdom, and the Australian Securities and Investments Commission are each developing sector-specific disclosure and affordability rules that will reshape product design and marketing practices. The EU's Consumer Credit Directive revision extends similar oversight across continental European markets, tightening eligibility checks and cooling-off period requirements. Stakeholders must monitor how divergent national implementations of open banking standards affect data portability and underwriting model performance across borders.
Market Dynamics
Open banking APIs and real-time credit decisioning engines are collapsing the latency between checkout and approval, compressing underwriting from days to milliseconds while forcing incumbent card networks to rearchitect their authorization stacks.
Growth Catalysts
- Consumer Financial Protection Bureau disclosure mandates:Standardized fee transparency in the United States is reducing consumer confusion and accelerating merchant adoption of regulated BNPL providers over informal installment schemes.
- Fashion and apparel checkout integration:Younger consumers driving discretionary e-commerce volume are selecting retailers based on embedded installment availability at point-of-sale.
- Real-time account-to-account payment rails:Open banking infrastructure in the United Kingdom and Australia is enabling direct bank-linked repayment without card network intermediation.
Market Restraints
- Balance-sheet funding concentration:Pure-play fintechs face escalating capital costs as warehouse credit facilities reprice against rising base rates, compressing net interest margins.
- EU Consumer Credit Directive cooling-off requirements:Mandatory 14-day withdrawal periods in continental Europe extend capital commitment cycles and increase operational complexity.
- Credit loss volatility in subprime segments:Algorithmic risk models exhibit performance decay during macroeconomic stress, requiring dynamic reserve provisioning.
Strategic Opportunities
- Embedded B2B trade credit:Small business procurement platforms in Germany and the Netherlands represent underpenetrated verticals for invoice financing integration.
- Regulatory arbitrage via banking licenses:European Union passporting rights enable cross-border lending authorization without duplicative national registrations.
- Convergence of BNPL with subscription management:Recurring payment orchestration tools are merging with installment logic to capture SaaS and membership commerce flows.
Industry Challenges
- Affordability assessment skill gaps:Real-time income verification engineering talent concentrates in London and Stockholm, creating recruitment bottlenecks for expansion markets.
- Legacy core banking integration:Middleware development for traditional lender partnerships consumes 12-18 month implementation timelines, delaying product launches.
- Model explainability compliance:Australian Securities and Investments Commission requirements for algorithmic decision transparency demand expensive documentation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Buy Now Pay Later Market |
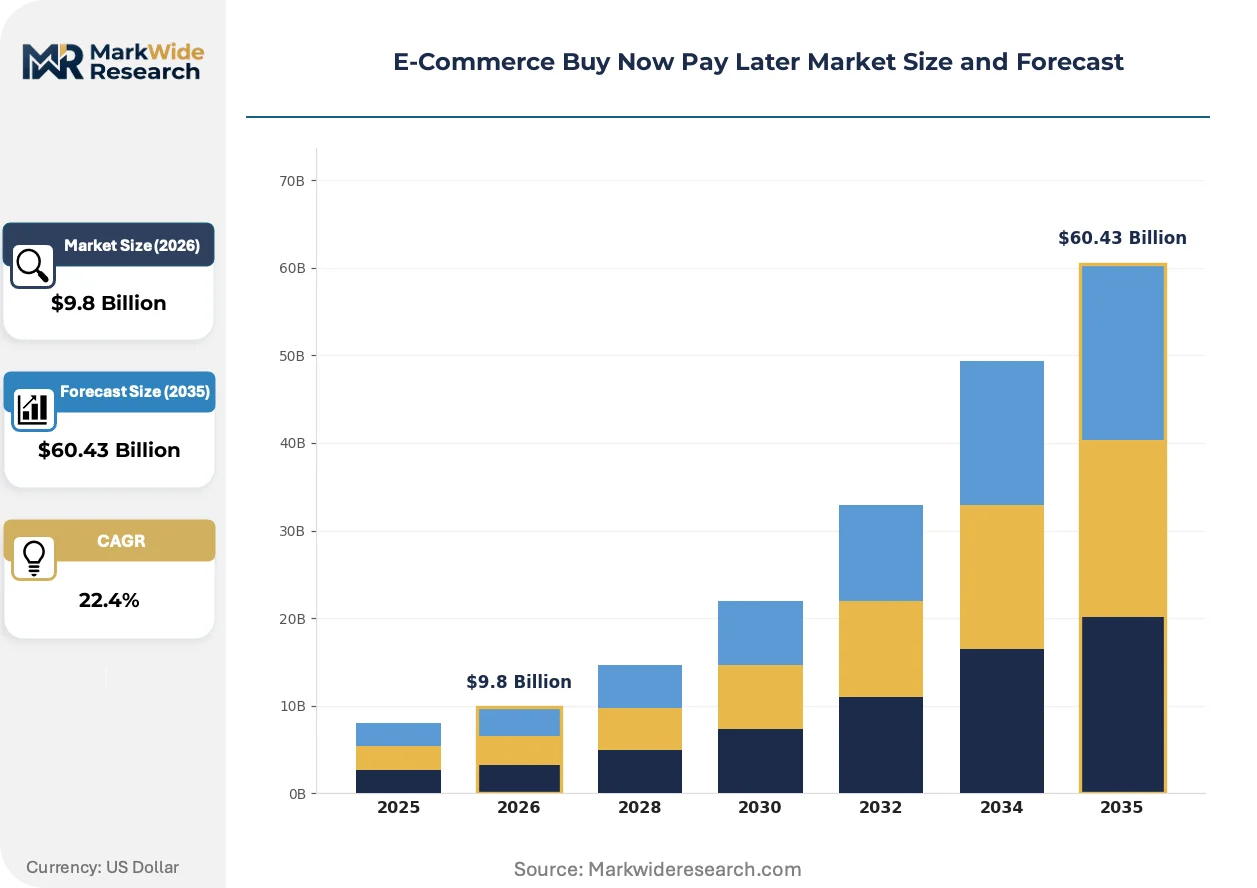
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $60.43 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Bank Transfer, Digital Wallet Consumer Type: Millennials, Gen Z, Working Professionals, Students Merchant Size: Small Businesses, Medium Enterprises, Large Corporations, Online Marketplaces Service Provider: Fintech Companies, Traditional Banks, Payment Processors, Online Lenders |
| Companies Covered | PayPal, Klarna, Affirm, Afterpay, Zip Co, Sezzle, Kredivo, Tabby, Splitit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Buy Now Pay Later Market Shifts & Advancements
Algorithmic underwriting architectures are fragmenting along regulatory jurisdictional lines, forcing providers to maintain parallel risk engines rather than unified global models.
Machine learning-based alternative data scoring is bifurcating the competitive landscape between thin-file specialists and traditional bureau-dependent lenders. Smartphone-native consumers without established credit histories are migrating to providers integrating cash-flow analytics and behavioral biometrics. This technology is compressing the addressable market for legacy FICO-centric underwriting while expanding financial inclusion metrics.
The EU's Consumer Credit Directive revision is mandating standardized Annual Percentage Rate disclosure across all member states. Installment providers must reprice merchant fee structures to absorb compliance costs while maintaining consumer-facing simplicity. Continental European markets are responding with product redesigns that embed regulatory disclosures directly into checkout interfaces.
Digital wallet-first payment behaviors are displacing card-on-file preferences among cohorts under 35. Retailers integrating Apple Pay and Google Pay with native BNPL options are capturing higher checkout completion rates than standalone web implementations. This shift is most pronounced in Australian and United Kingdom metropolitan markets where contactless penetration exceeds 80 percent.
E-Commerce Buy Now Pay Later Market Segmentation
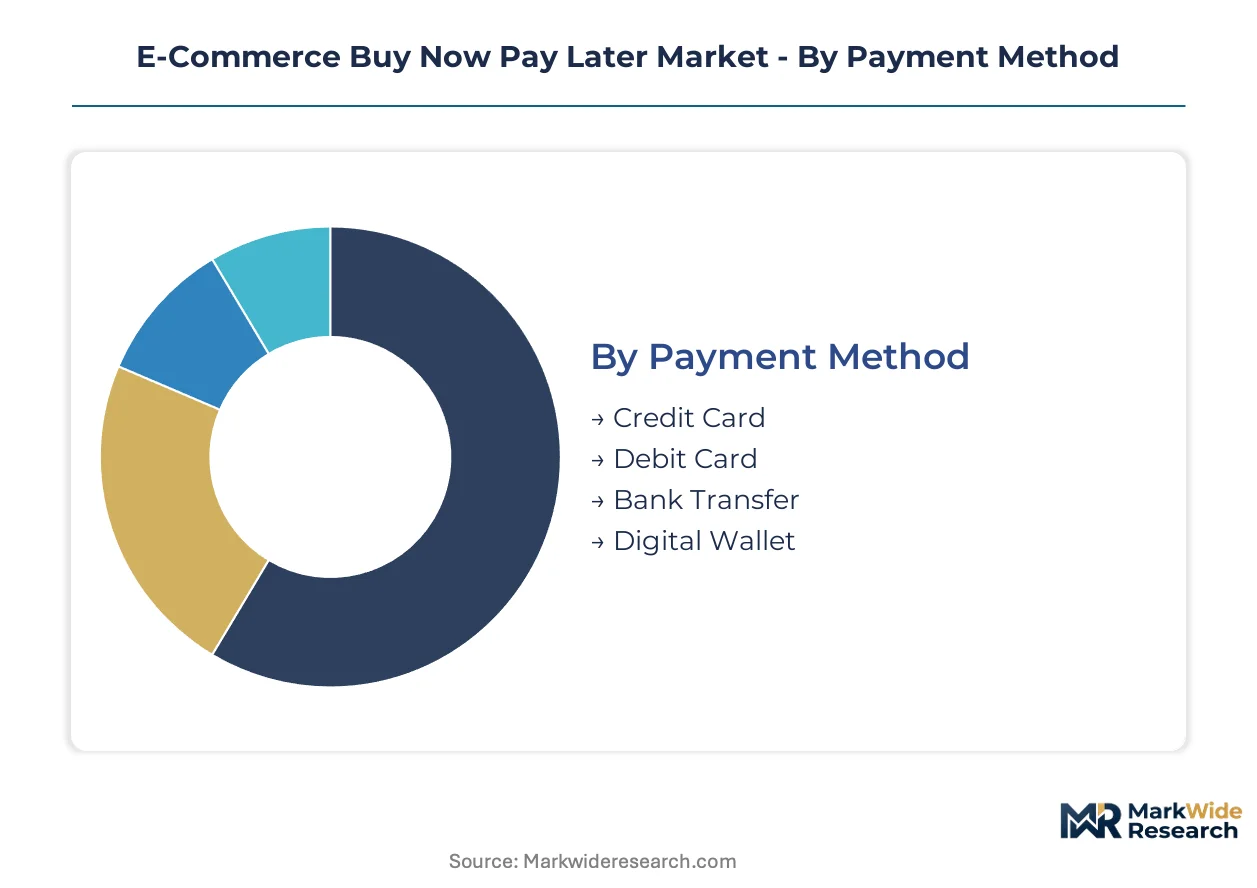
BNPL market segmentation reveals divergent growth trajectories across payment rails and consumer cohorts. Each dimension carries distinct underwriting economics, regulatory exposure, and merchant acquisition cost structures that reshape competitive positioning.
Payment Method:
Digital wallet-linked BNPL concentrates in metropolitan Australia and United Kingdom markets where contactless penetration exceeds thresholds for smartphone-native checkout. Bank transfer modalities dominate domestic German and Dutch procurement platforms seeking to bypass card network interchange.
- Credit Card:Card-on-file BNPL leverages existing network rails and consumer familiarity, reducing merchant integration friction. Demand clusters among United States retailers serving established FICO-score consumers where card-based installment preserves loyalty program continuity.
- Debit Card:Debit-tied installment draws from deposit-linked underwriting models using real-time balance verification. United Kingdom open banking APIs enable this segment to expand fastest among thin-file consumers lacking revolving credit histories.
- Bank Transfer:Direct account-to-account repayment eliminates interchange fees entirely. Australian NPP infrastructure and United Kingdom Faster Payments support this modality's domestic concentration.
- Digital Wallet:Apple Pay and Google Pay native BNPL compresses checkout steps to biometric authentication. Younger cohorts in Sydney, Melbourne, and London drive disproportionate volume through this channel.
Credit card commands the established base. The steepest expansion runs through digital wallet.
Consumer Type:
Generational segmentation maps directly to income volatility profiles and credit bureau penetration. Working professionals generate the most predictable repayment streams, while students present the highest acquisition lifetime value despite near-term loss rates.
- Millennials:This cohort balances established credit histories with platform-native shopping behaviors. United States and Australian markets concentrate demand among suburban homeowners financing discretionary durables.
- Gen Z:Cash-flow-based underwriting replaces bureau dependency for consumers without FICO scores. Behavioral biometric models from Stockholm and London engineering clusters enable this segment's expansion.
- Working Professionals:Stable income verification through payroll APIs reduces default probability. Medium-ticket fashion and electronics purchases dominate this segment's transaction mix.
- Students:Educational institution partnerships provide acquisition channels with embedded affordability checks. Seasonal repayment schedules align with disbursement timing.
Working professionals anchor current profitability. Gen Z is climbing the fastest as thin-file underwriting matures.
Merchant Size:
Merchant scale determines integration complexity and fee negotiation leverage. Large corporations demand white-label implementations, while small businesses prioritize plug-and-play checkout widgets with minimal technical resource requirements.
- Small Businesses:SaaS-embedded BNPL widgets require zero developer hours for deployment. United Kingdom and Australian independent retailers adopt this segment to match enterprise competitor checkout options.
- Medium Enterprises:Custom API integrations balance branding control with implementation speed. Direct sales teams from fintech providers concentrate pursuit on this tier for unit economics optimization.
- Large Corporations:Bespoke underwriting partnerships and exclusive network arrangements characterize this segment. United States department stores and Australian retail chains negotiate proprietary risk-sharing structures.
- Online Marketplaces:Multi-merchant platforms require unified BNPL infrastructure across heterogeneous seller bases. Marketplace-native checkout integration creates winner-take-most dynamics in this segment.
Small businesses represent the broadest installed base. Online marketplaces are gaining share fastest through platform consolidation effects.
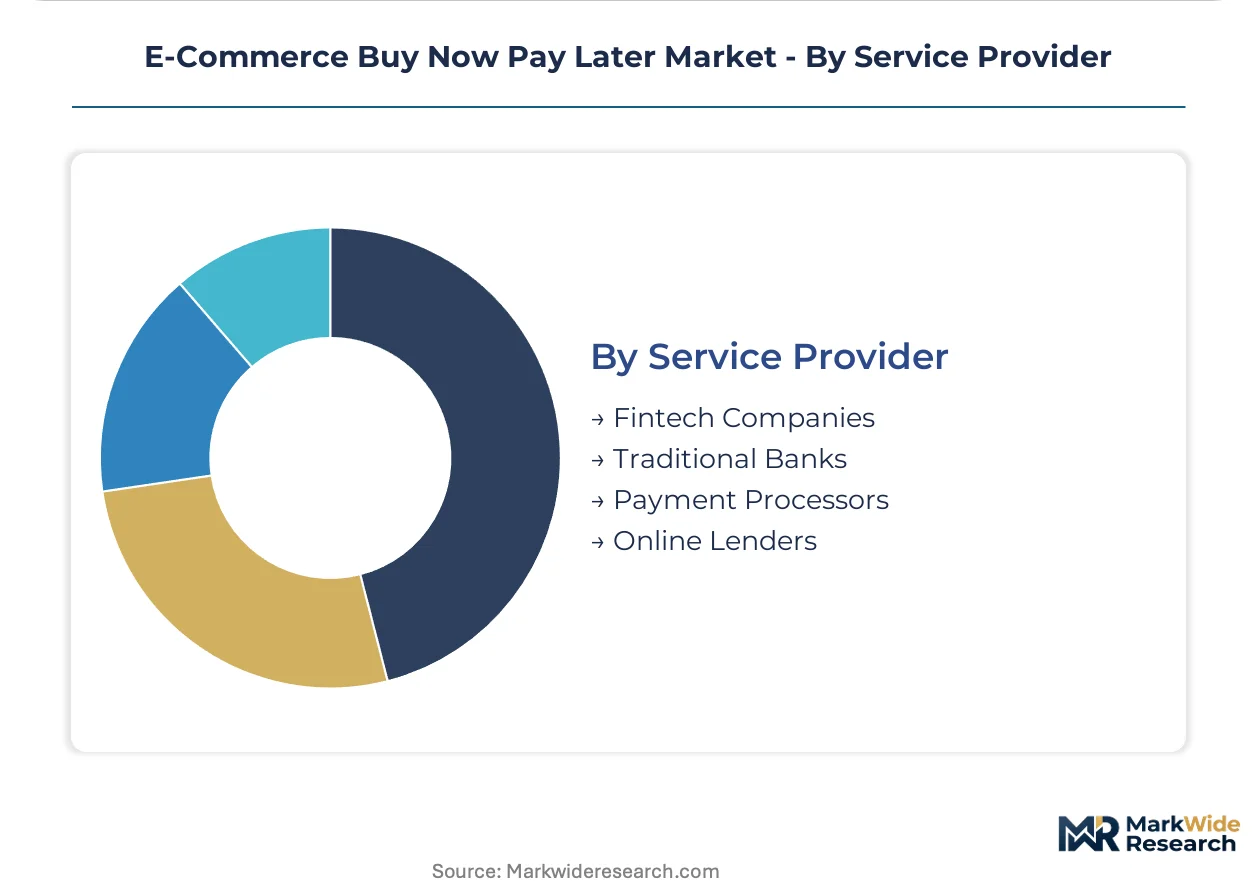
Service Provider:
Provider category shapes capital cost structure and regulatory compliance burden. Banking license holders access ECB and Federal Reserve funding windows unavailable to balance-sheet-constrained fintechs.
- Fintech Companies:Algorithmic-native underwriting and direct-to-consumer brand recognition define this segment. Pure-play providers face escalating warehouse facility pricing against base rate movements.
- Traditional Banks:Deposit-funded balance sheets and existing compliance infrastructure lower marginal funding costs. United States regional banks and European universal banks are building embedded offerings through middleware partnerships.
- Payment Processors:Two-sided network effects from existing merchant relationships accelerate distribution. PayPal's consumer and merchant base exemplifies this segment's acquisition efficiency.
- Online Lenders:Specialty consumer finance platforms extend installment logic from personal loans to point-of-sale. Cross-selling infrastructure from existing loan servicing operations reduces unit acquisition costs.
Fintech companies hold the established volume position. Traditional banks are expanding most quickly through embedded partnership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers deploy BNPL primarily for discretionary durables, while Australian and United Kingdom shoppers concentrate usage on fashion and apparel, creating divergent merchant integration priorities across mature markets.
United States
Suburban millennials financing home electronics and furniture drive transaction volume. The Consumer Financial Protection Bureau mandates standardized fee transparency, reducing consumer confusion and accelerating merchant migration toward regulated providers. New York and Los Angeles metro areas concentrate fintech engineering talent developing real-time income verification systems.
Australia
Contactless payment penetration above 80 percent in Sydney and Melbourne propels digital wallet-native BNPL adoption among Gen Z consumers. The Australian Securities and Investments Commission enforces algorithmic decision transparency requirements, demanding expensive documentation infrastructure from providers. Sydney hosts the domestic headquarters of major BNPL platforms engineering behavioral biometric underwriting models.
United Kingdom
Open banking APIs enable direct account-to-account repayment without card network intermediation, attracting thin-file consumers lacking revolving credit histories. The Financial Conduct Authority develops sector-specific affordability rules reshaping product design and marketing practices. London concentrates engineering clusters building cash-flow analytics for thin-file underwriting expansion.
Germany
Bank transfer modalities dominate domestic procurement platforms seeking to bypass card network interchange, particularly among small business SaaS-embedded widgets. The EU Consumer Credit Directive revision mandates standardized Annual Percentage Rate disclosure and 14-day cooling-off periods, extending capital commitment cycles. Berlin and Hamburg fintechs target embedded B2B trade credit for underpenetrated invoice financing verticals.
Sweden
Stockholm engineering clusters supply machine learning talent for alternative data scoring systems displacing legacy bureau dependency. EU passporting rights enable cross-border lending authorization without duplicative national registrations. The capital region anchors Nordic BNPL platform development leveraging European banking licenses for lower funding costs across multiple jurisdictions.
E-Commerce Buy Now Pay Later Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the capital-intensity gap between bank-backed platforms and pure-play fintechs collapsing as balance-sheet requirements escalate. The market structure stratifies across three archetypes: algorithmic-native underwriters with direct-to-consumer brands, deposit-funded traditional banks building embedded offerings, and two-sided network processors exploiting existing merchant relationships. Dominant competitive moves include strategic partnerships with large retailers for exclusive network arrangements and middleware development compressing legacy core banking integration timelines from 18 months toward 12.
Within the integrated leader tier, Klarna and Affirm exemplify contrasting regulatory arbitrage strategies. The Stockholm-based European banking license holder sustains lower cost of funds through EU passporting rights across multiple jurisdictions. San Francisco-based Affirm anchors its position through proprietary risk models and direct merchant integrations with United States department stores. PayPal occupies a distinct network-effects position, embedding BNPL expansion within an existing two-sided consumer and merchant base that accelerates distribution without standalone acquisition costs.
| Leading Market Players |
|---|
| PayPal |
| Klarna |
| Affirm |
| Afterpay |
| Zip Co |
| Sezzle |
| Kredivo |
| Tabby |
| Splitit |
| Others |
Supply & Pricing Matrix
Millisecond-level underwriting latency requirements compress merchant integration timelines from 18 months toward 12, concentrating pricing power with providers possessing pre-built API infrastructure and forcing late entrants toward premium partnership fees. This lead-time compression reshapes supply chain priorities toward real-time data pipeline investments and away from legacy core banking middleware.
Pricing Analysis
Long-term offtake contracts between BNPL providers and merchant platforms dominate enterprise relationships, while spot-rate merchant fee negotiations characterize small business onboarding. Three-tier pricing structure across premium white-label, standard API-integrated, and economy checkout-widget levels separates large retailers from mid-market merchants from independent sellers. Cost compression in the economy tier intensifies because pure-play fintechs reprice warehouse facilities against rising base rates. Small businesses exhibit highest price sensitivity, while large corporations leverage exclusive network arrangements for fee concessions.
Supply Chain Analysis
Just-in-time capital deployment through securitization markets contrasts with strategic stockpiling of banking licenses for EU passporting rights among established providers. Engineering talent concentrates in Stockholm, London, and Sydney, anchoring algorithmic underwriting development in these clusters. Funding sources draw from warehouse credit facilities, whole-loan sales, and deposit bases at licensed institutions. Single-source vulnerability in real-time income verification APIs poses structural risk as open banking standards diverge across jurisdictions. Distribution runs through direct merchant sales teams, platform partnerships, and embedded SaaS integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open banking API proliferation and real-time credit decisioning engines are disrupting traditional card-network authorization stacks, creating high-growth disruption with regulatory frameworks at inflection across multiple jurisdictions.
For Market Incumbents: Shield core merchant relationships through exclusive underwriting partnerships and proprietary risk model investments that emerging entrants cannot replicate. Vertical integration into banking licenses reduces funding cost exposure as warehouse facility repricing accelerates. Accelerate middleware development to compress legacy core integration timelines before balance-sheet-constrained fintechs lose distribution access. For New Entrants and Emerging Players: Differentiate on cash-flow analytics for thin-file Gen Z consumers in Australian and United Kingdom metropolitan markets where contactless penetration exceeds thresholds. Embedded B2B trade credit in German and Dutch procurement platforms represents the most penetrable white-space vertical. Pursue SaaS-embedded widget distribution to bypass direct merchant sales cost structures. For Investors and Strategic Acquirers: Carve-out targets emerge from regional banks seeking to divest consumer installment lending operations amid escalating compliance costs. Long-term viability hinges on regulatory license portability and algorithmic underwriting scalability rather than brand recognition alone. Watch for divergence in national open banking implementations as the signal triggering consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Banking License Acquisition | EU passporting rights enable cross-border lending authorization without duplicative national registrations. |
| Real-Time Income Verification API Development | Open banking infrastructure in United Kingdom and Australia supports thin-file underwriting expansion. |
| Embedded B2B Trade Credit Launch | German and Dutch procurement platforms represent underpenetrated invoice financing verticals. |
| Behavioral Biometric Underwriting Investment | Stockholm and London engineering clusters supply machine learning talent displacing legacy bureau dependency. |
| Digital Wallet-Native Checkout Integration | Apple Pay and Google Pay native BNPL captures higher completion rates among smartphone-native cohorts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, open banking infrastructure disclosures, and merchant platform integration documentation. Interviews with BNPL risk officers, merchant acquisition leads, open banking API developers, and compliance directors at licensed institutions inform demand-side and supply-side assessments. Secondary validation draws from Consumer Financial Protection Bureau rulemaking records, Financial Conduct Authority consultation papers, Australian Securities and Investments Commission enforcement actions, and EU Consumer Credit Directive revision texts. Bottom-up transaction volume modeling and top-down addressable market sizing provide triangulation.
Segmentation dimensions modeled include payment method, consumer cohort, merchant scale, and service provider category across the analysis window. CAGRs derive from regression analysis against macroeconomic indicators and sector-specific adoption curves. Forecast inputs incorporate open banking penetration rates, contactless payment adoption thresholds, and regulatory implementation timelines without year-specific assumptions.
The analysis sits within stated boundaries; outcomes outside sustained open banking infrastructure investment and stable regulatory treatment of algorithmic underwriting would require recalibration. Forecasts assume continued merchant fee compression tolerance and consumer repayment behavior stability. Revision becomes warranted when credit loss volatility in subprime segments crosses reserve provisioning thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
B2C E-Commerce Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market