
 M-Commerce Market | 2026-2036
M-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
M-Commerce Market Outlook
PCI DSS Level 1 certification is collapsing as the baseline barrier for payment processors seeking direct merchant relationships. Amazon leverages its captive logistics network to sustain same-day delivery promises in dense urban corridors. Alibaba anchors cross-border settlement infrastructure between Chinese manufacturers and emerging-market consumers. Google competes through embedded checkout APIs that reduce friction inside third-party applications.
M-commerce denotes commercial transactions executed through wireless handheld devices, relying on encrypted tokenization protocols, near-field communication chips, and responsive adaptive interfaces to complete purchases without desktop intermediation. Its primary purpose is to monetize fragmented consumer attention spans through instantaneous, context-aware purchasing pathways. The payment method dimension shows e-wallet volumes outpacing card-based flows in emerging economies where banking infrastructure remains sparse. Device type segmentation reveals wearables as the fastest-growing access point, though smartphones still capture the dominant share of transaction value.
The US Federal Trade Commission scrutinizes dark-pattern interface designs that manipulate mobile checkout behavior, while the EU Digital Services Act imposes transparency obligations on algorithmic product recommendations inside marketplace applications. India's Reserve Bank mandates two-factor authentication for all wallet transactions exceeding specified thresholds, elevating compliance costs for foreign entrants. Stakeholders must weigh localization investments against the operational burden of fragmented national regulatory regimes.
Market Dynamics
PCI DSS Level 1 certification is collapsing as the baseline barrier for payment processors seeking direct merchant relationships, while India's PLI scheme for electronics manufacturing actively reshapes supply chain geography away from traditional assembly hubs.
Growth Catalysts
- Social Commerce Platforms:Gen Z consumers drive adoption through integrated checkout experiences embedded inside short-form video applications, converting passive browsing into immediate transactions.
- India's PLI Scheme:The production-linked incentive framework for electronics manufacturing attracts component suppliers to domestic assembly corridors, reducing import dependency for smartphone production.
- Near-Field Communication Chips:Contactless payment terminals are proliferating across retail point-of-sale infrastructure, enabling tap-to-pay functionality without network latency.
Market Restraints
- Fragmented Regulatory Regimes:India's Reserve Bank mandates divergent authentication protocols from EU Digital Services Act transparency obligations, forcing parallel compliance architectures.
- Banking Infrastructure Gaps:Sparse branch networks in emerging economies limit card-based payment penetration, constraining addressable consumer bases outside major urban corridors.
- Dark-Pattern Scrutiny:The US Federal Trade Commission's enforcement against manipulative interface designs elevates legal risk for conversion-optimization tactics in mobile checkout flows.
Strategic Opportunities
- Tier-2 Indian Cities:Deepening smartphone penetration in secondary urban centers creates first-mover advantages for localized payment and logistics infrastructure.
- Wearable Access Points:Smartwatches and fitness bands represent underexploited transaction surfaces beyond handset-dependent commerce models.
- Cross-Border Settlement Infrastructure:Anchor platforms connecting Chinese manufacturers directly to emerging-market consumers bypass traditional correspondent banking layers.
Industry Challenges
- Two-Factor Authentication Implementation:RBI-mandated verification thresholds for wallet transactions impose technical complexity and latency costs on foreign payment entrants.
- Embedded Checkout Integration:API compatibility across third-party application ecosystems requires sustained engineering investment to maintain friction reduction.
- Captive Logistics Scaling:Same-day delivery promises in dense urban corridors demand fixed-cost warehouse networks that strain capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | M-Commerce Market |
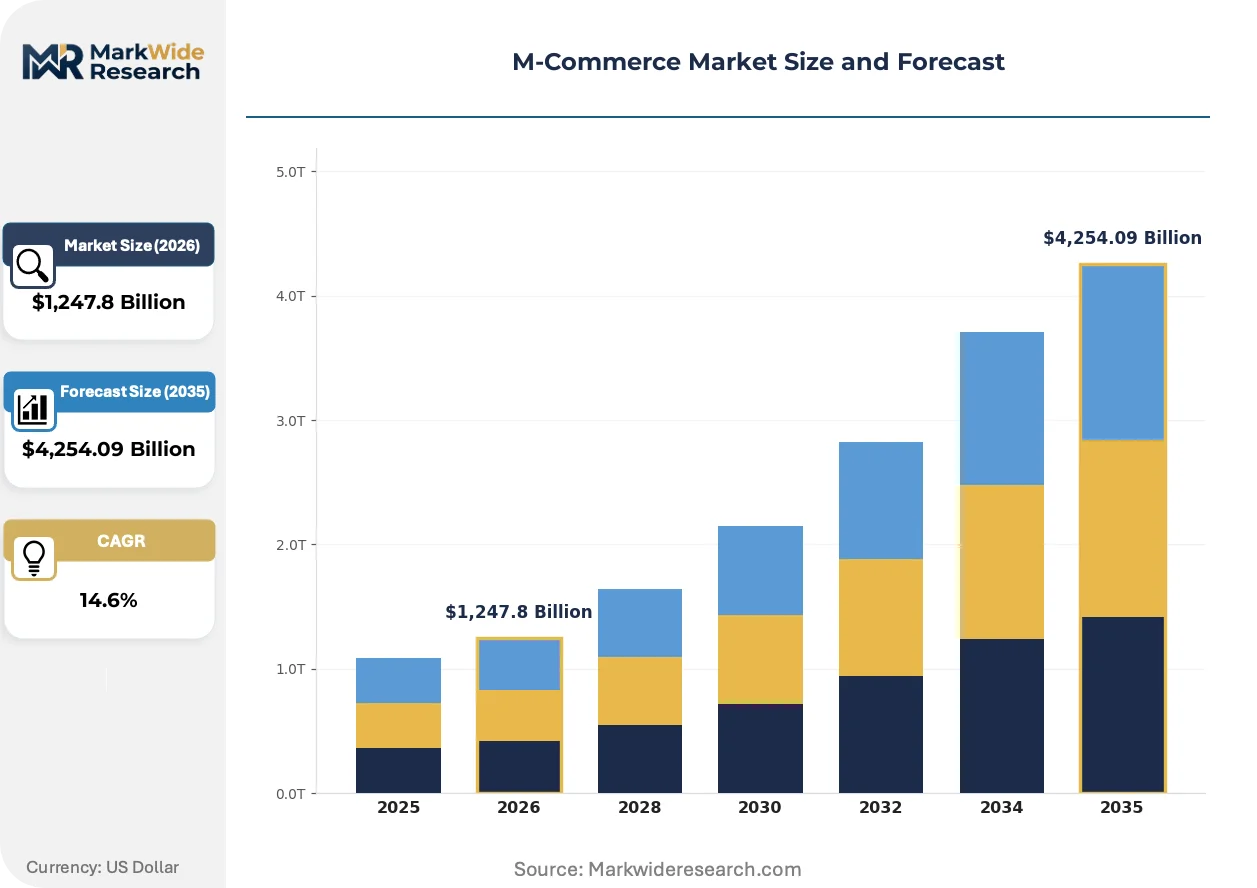
| Market Size in 2026 | $1,247.8 Billion |
| Market Size in 2035 | $4,254.09 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Goods, Physical Goods, Services, Subscription Payment Method: Credit Card, Debit Card, E-Wallet, Cryptocurrency Customer Type: Millennials, Gen Z, Professionals, Retirees Device Type: Smartphone, Tablet, Wearable, Smart TV |
| Companies Covered | Amazon, Alibaba, Apple, Walmart, JD.com, Mastercard, PayPal, Google, Shopify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
M-Commerce Market Strategic Shifts
Encrypted tokenization protocols are actively displacing static card credentials as the dominant security architecture, while responsive adaptive interfaces compress the distance between discovery and purchase.
Tokenization infrastructure is decomposing the traditional merchant-acquirer relationship by enabling direct credential vaulting. Payment processors and large marketplace operators are adopting this shift fastest, building proprietary token repositories that bypass incumbent network routing. This compression is fragmenting interchange fee pools and concentrating value capture among platforms with sufficient transaction density to justify dedicated security infrastructure.
The EU Digital Services Act imposes transparency obligations on algorithmic product recommendations inside marketplace applications. Industrial consequence includes mandatory disclosure of ranking parameters and advertising integration. Fashion and electronics verticals within European marketplace applications are most affected, responding by segregating recommendation engines from advertising auction systems to isolate audit trails.
Social commerce procurement patterns are rotating purchase initiation away from search-intent toward discovery-intent interfaces. Influencer-mediated product curation is displacing traditional category browsing inside mobile applications. This behavioral pivot is most visible in beauty and apparel verticals across Southeast Asian markets, where live-streaming commerce now commands disproportionate transaction share relative to conventional storefront interfaces.
M-Commerce Market Segmentation
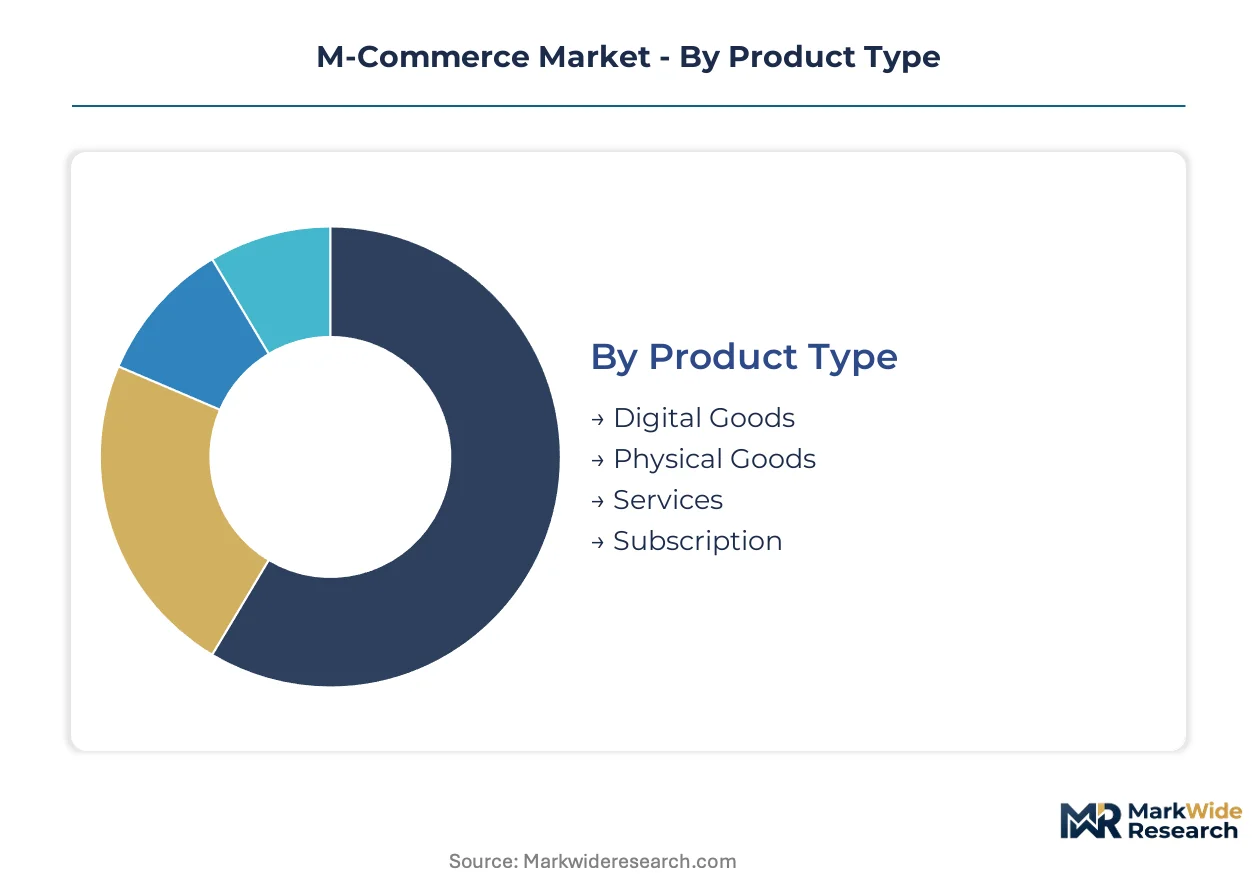
M-commerce monetization pathways diverge sharply across product formats and access devices, with each segment demanding distinct payment rails and interface architectures. Channel-mix optimization requires matching transaction velocity to authentication friction tolerance.
Product Type:
Digital goods flow through instant-delivery infrastructure with zero logistics overhead, while physical goods anchor fulfillment networks that determine working capital intensity.
- Digital Goods:Software licenses, streaming media, and in-app purchases execute through encrypted token vaults with immediate credential verification. Demand concentrates in India's tier-2 cities where smartphone-first consumers bypass physical retail infrastructure entirely.
- Physical Goods:Tangible merchandise requires last-mile coordination through captive or third-party logistics networks. Amazon's urban warehouse density enables same-day delivery promises in dense corridors, though inventory carrying costs strain margin structures.
- Services:On-demand labor and professional service bookings integrate calendar APIs with payment escrow functionality.
- Subscription:Recurring revenue models depend on stored credential persistence and churn-optimized dunning management.
By volume, Physical Goods leads. By growth pace, Digital Goods is expanding most quickly.
Payment Method:
Cost tier stratification separates high-friction traditional rails from low-friction emerging alternatives, with regulatory compliance burden as the primary differentiator.
- E-Wallet:Closed-loop and open-loop wallet architectures dominate emerging economies where banking branch density remains sparse. India's RBI mandates two-factor authentication above specified thresholds, elevating technical complexity for foreign entrants seeking wallet market share.
- Credit Card:Revolving credit instruments maintain premium transaction value concentration in developed markets with mature underwriting infrastructure. PCI DSS Level 1 certification requirements are compressing as baseline barriers for direct merchant relationships.
- Debit Card:Direct-account-drawing instruments face network latency constraints in real-time authorization environments.
- Cryptocurrency:Blockchain-settlement mechanisms occupy regulatory gray zones with volatile acceptance rates across jurisdictions.
By transaction count, E-Wallet leads in emerging economies. By value per transaction, Credit Card retains dominance.
Customer Type:
Application design patterns diverge across generational cohorts, with interface density and social proof integration as primary segmentation variables.
- Gen Z:Native mobile users initiate purchases through discovery-intent interfaces rather than search-intent pathways. Social commerce platforms with integrated checkout inside short-form video applications convert passive browsing into immediate transactions across Southeast Asian markets.
- Millennials:Transition cohorts balance convenience expectations with established trust markers from desktop-era commerce.
- Professionals:Time-constrained segments prioritize one-tap reordering and subscription automation over exploratory browsing.
- Retirees:Late-adopter segments require amplified authentication feedback and simplified navigation architectures.
By engagement frequency, Gen Z leads. By average transaction value, Professionals generates highest per-session revenue.
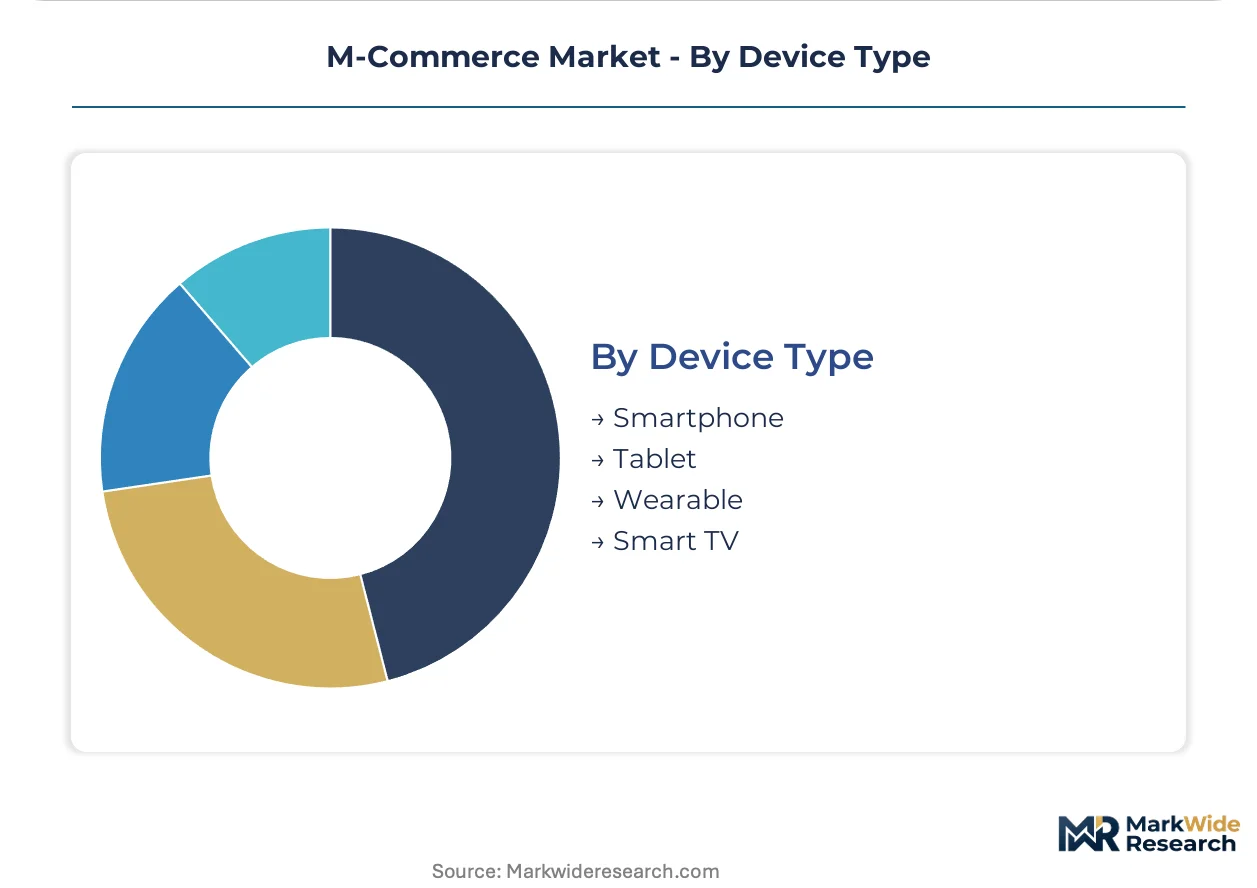
Device Type:
Supply concentration in semiconductor fabrication shapes hardware availability, while interface adaptation costs scale inversely with screen real estate.
- Smartphone:Handset-dependent commerce captures dominant transaction value share through responsive adaptive interfaces that compress discovery-to-purchase distance. India's PLI scheme for electronics manufacturing is reshaping supply chain geography toward domestic assembly corridors.
- Wearable:Smartwatches and fitness bands represent underexploited transaction surfaces beyond handset models. Near-field communication chip proliferation enables tap-to-pay functionality without network latency in retail point-of-sale environments.
- Tablet:Larger-format devices retain niche positioning for high-consideration purchases requiring extended evaluation.
- Smart TV:Living-room commerce interfaces struggle with input friction despite large display advantages.
By installed base, Smartphone leads. By expansion trajectory, Wearable is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
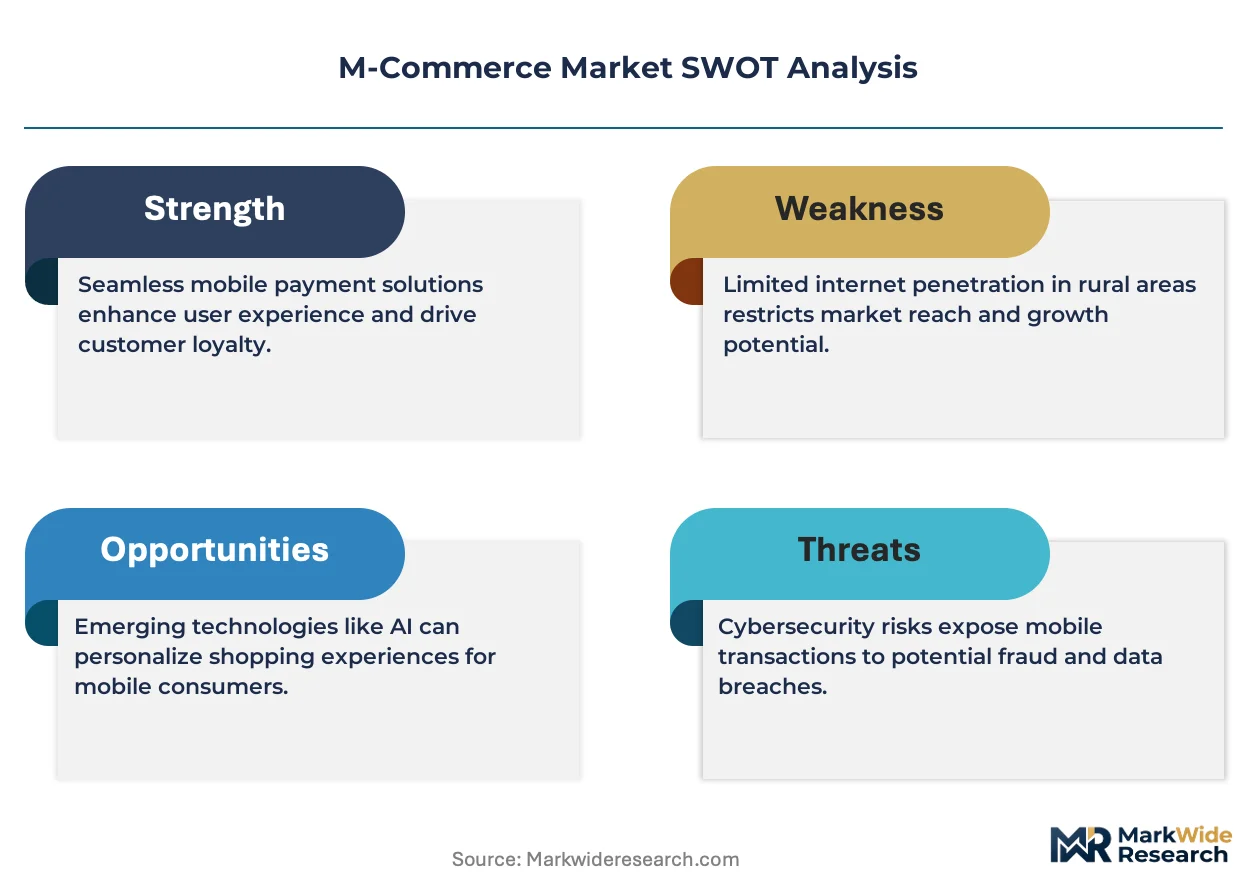
Buyer-archetype concentration clusters around Gen Z digital natives in emerging economies and time-constrained professionals in mature markets. Smartphone-first consumers in India's secondary cities drive volume expansion. Established markets prioritize friction reduction over acquisition.
United States
Gen Z and millennial cohorts dominate transaction initiation through social commerce platforms embedded in short-form video applications. The FTC scrutinizes dark-pattern interface designs that manipulate mobile checkout behavior, elevating compliance costs for conversion-optimization tactics. Amazon's warehouse density in dense urban corridors enables same-day delivery infrastructure that strains competitor capital efficiency.
India
Tier-2 city consumers bypass physical retail entirely through smartphone-first commerce pathways. The RBI mandates two-factor authentication for wallet transactions above specified thresholds, forcing foreign payment entrants into parallel technical architectures. Karnataka and Maharashtra anchor domestic electronics assembly corridors reshaped by the PLI scheme for component suppliers.
China
Live-streaming commerce commands disproportionate transaction share in beauty and apparel verticals through influencer-mediated product curation. SAMR oversight of algorithmic recommendation transparency constrains advertising integration inside marketplace applications. The Yangtze River Delta and Pearl River Delta concentrate cross-border settlement infrastructure connecting manufacturers to emerging-market consumers.
Germany
Professional segments prioritize one-tap reordering and subscription automation over exploratory browsing behaviors. The EU Digital Services Act imposes ranking parameter disclosure obligations on marketplace recommendation engines. Berlin and Munich host segregated technical architectures isolating advertising auction systems from recommendation engines for audit trail compliance.
Brazil
E-wallet volumes outpace card-based flows where banking branch density remains sparse outside major urban corridors. ANVISA and the central bank coordinate on payment system oversight without mandating equivalent authentication friction. São Paulo anchors logistics network investments required for last-mile coordination of physical goods fulfillment.
M-Commerce Market Competitive Environment
Player mix skews toward integrated marketplace operators with captive logistics networks and payment infrastructure providers with token vaulting capabilities. Market structure concentrates among platforms with sufficient transaction density to justify dedicated security architecture and fulfillment assets. Two strategic archetypes dominate: vertically integrated retailers controlling end-to-end customer experience, and embedded checkout API providers reducing friction inside third-party applications. Competitive moves center on M&A for logistics capacity and strategic partnerships for cross-border settlement rails.
Within the integrated marketplace tier, Amazon and Alibaba anchor divergent geographic footprints. Amazon exemplifies the captive logistics model through urban warehouse density enabling delivery velocity promises. Alibaba occupies a position connecting Chinese manufacturing supply to emerging-market demand through settlement infrastructure bypassing traditional correspondent banking. PayPal represents the payment infrastructure archetype, sitting within the embedded finance layer where tokenization protocols displace static card credentials.
| Leading Market Players |
|---|
| Amazon |
| Alibaba |
| Apple |
| Walmart |
| JD.com |
| Mastercard |
| PayPal |
| Shopify |
| Others |
Value Chain & Pricing Dynamics
Encrypted tokenization protocols displacing static card credentials simultaneously compress payment processor margins and relocate value capture toward platforms with captive vault infrastructure, redrawing competitive economics across authentication tiers.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate hardware procurement for NFC chipsets and secure elements, insulating assemblers from wafer price volatility. Three-tier pricing structure across premium token-vault services, standard gateway APIs, and economy payment routing separates PCI DSS Level 1 certified processors from uncertified entrants. Pricing pressure stems from interchange fee compression as direct credential vaulting fragments traditional merchant-acquirer relationships. Gen Z consumers in emerging economies exhibit lowest price sensitivity for friction-reduced checkout experiences, while small merchants in tier-2 Indian cities face acute cost pressure on authentication overhead.
Supply Chain Analysis
Inventory lead times for near-field communication chips and secure authentication modules stretch 18-24 weeks, tethering fulfillment velocity to Taiwan Semiconductor and Samsung Foundry capacity allocation. Component sourcing draws from South Korea for memory modules, Vietnam for final handset assembly, and India for domestic electronics corridors reshaped by PLI scheme incentives. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through captive logistics networks for same-day delivery promises and third-party aggregators for tier-2 city penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
M-commerce traces a cyclical recovery pattern tied to smartphone replacement cycles and emerging market banking infrastructure buildout, with Gen Z purchasing behavior normalizing post-pandemic acceleration.
For Market Incumbents: Shield token vault market share through backward integration into secure element manufacturing and exclusive partnerships with India's PLI scheme beneficiaries for domestic assembly capacity. Certification investment in RBI-mandated two-factor authentication architectures raises defensive barriers against foreign payment entrants. Channel control over tier-2 city logistics networks locks in merchant switching costs. For New Entrants and Emerging Players: Differentiate on wearable-native checkout experiences bypassing handset-dependent commerce models. White-space concentration sits in cross-border settlement infrastructure connecting Chinese manufacturers to Latin American e-wallet ecosystems. Go-to-market leverage through embedded finance APIs inside short-form video applications captures discovery-intent purchase initiation before search-based incumbents respond. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with sufficient transaction density to justify dedicated security infrastructure. Long-term viability over a 5-10 year window hinges on regulatory compliance automation at national scale. Acquisition target archetype: embedded checkout providers with existing API penetration in Southeast Asian social commerce platforms. Signal to watch: RBI authentication threshold adjustments that would elevate technical complexity for sub-scale foreign entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Token Vault Infrastructure Buildout | Proprietary credential repositories bypass incumbent network routing and capture interchange margin compression. |
| PLI Scheme Manufacturing Partnership | Domestic electronics assembly corridors in Karnataka and Maharashtra reduce import dependency for smartphone production. |
| Embedded Checkout API Integration | Friction reduction inside third-party applications converts passive browsing into immediate transactions for Gen Z cohorts. |
| Wearable Payment Surface Development | Smartwatch and fitness band interfaces expand transaction surfaces beyond handset-dependent commerce models. |
| Cross-Border Settlement Rail Anchoring | Direct manufacturer-to-consumer infrastructure bypasses traditional correspondent banking layers in emerging markets. |
Study Parameters
The analysis maps payment infrastructure, device manufacturing, and logistics fulfillment sub-sectors, each validated through mobile platform executives, payment processor technical leads, semiconductor procurement managers, and tier-2 city logistics operators. Primary interview intelligence triangulates against secondary sources including RBI circulars, EU Digital Services Act transparency filings, FTC enforcement actions, and smartphone production data from India's Ministry of Electronics. Bottom-up merchant adoption modeling and top-down transaction value estimation cross-validate volume assumptions.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions span payment method architecture, device type access points, customer generational cohorts, and product format delivery requirements. CAGRs derive from installed base penetration curves and wallet transaction velocity assumptions. Forecast inputs incorporate PLI scheme capacity addition schedules and NFC terminal deployment trajectories in retail point-of-sale infrastructure.
Material uncertainties — regulatory authentication threshold revisions, semiconductor supply disruptions, and dark-pattern enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these vectors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Europe E-Commerce Apparel Market
E-Commerce Solutions
China Alcohol E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
Retail E-Commerce Market
E-Commerce Solutions
Asia Pacific E-Commerce Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
Bulgaria E-Commerce Market