
 Palonosetron Hydrochloride Market | 2026-2036
Palonosetron Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Palonosetron Hydrochloride Market Analytics
Indian API manufacturers is recalibrating bulk production capacity to meet rising procurement from European and North American finished-dose makers. Wavelength Pharmaceuticals leverages backward integration into key starting materials to protect margin structures against raw material volatility. Fresenius Kabi anchors its position through hospital channel control in Western Europe, while Merck competes on brand recognition in oncology supportive care protocols across major academic medical centers.
Palonosetron hydrochloride is a second-generation 5-HT3 receptor antagonist with a molecular formula of C19H24N2O·HCl and extended plasma half-life exceeding 40 hours, designed for prevention of acute and delayed chemotherapy-induced nausea and vomiting. The injection segment dominates hospital procurement due to perioperative and oncology unit preference for controlled IV administration, while the oral solution format shows structural momentum in outpatient and home healthcare settings where patient self-administration reduces infusion center burden. Therapy area segmentation reveals chemotherapy-induced nausea and vomiting as the mature revenue core, with postoperative nausea applications representing a narrower but defensible margin pool in ambulatory surgical centers.
FDA bioequivalence standards and EMA GMP inspections shape manufacturing location decisions and batch release protocols for palonosetron hydrochloride producers seeking multi-regional market access. India's CDSCO and China's NMPA impose distinct stability testing and labeling requirements that filter which manufacturers qualify for tender participation in Asia's largest hospital systems. Stakeholders must monitor evolving pharmacopeial monograph revisions and biosimilar substitution policies that could restructure competitive dynamics across dosage form categories.
Market Dynamics
Hospital procurement departments in Germany, Japan, and India are consolidating antiemetic purchasing around single-dose IV palonosetron, compressing demand for multi-day oral alternatives and rewiring competitive positioning around formulary control rather than brand equity.
Growth Catalysts
- CMS reimbursement shifts:Oncology clinics in the United States are expanding prophylactic antiemetic protocols ahead of value-based chemotherapy support mandates, anchoring IV palonosetron in outpatient infusion protocols.
- EMA GMP inspections:European hospital formularies are prioritizing single-dose IV regimens that reduce nursing labor and medication error exposure in perioperative settings.
- API backward integration:Indian bulk manufacturers are recalibrating production capacity to serve rising procurement from European and North American finished-dose makers, shortening supply lead times.
Market Restraints
- Raw material volatility:Key starting material costs for palonosetron synthesis fluctuate with petrochemical feedstock pricing, squeezing margin structures for non-integrated manufacturers.
- Supply concentration risk:Injectable formulation capacity clusters among a limited set of European and Indian sterile facilities, creating vulnerability to batch release delays.
- Substitution threat:NK1 receptor antagonists and olanzapine-based regimens compete for delayed CINV prophylaxis, particularly in academic medical centers with protocol flexibility.
Strategic Opportunities
- Home healthcare expansion:Oral solution formats show structural momentum in outpatient settings where patient self-administration reduces infusion center burden and extends therapy reach.
- Postoperative nausea protocols:Ambulatory surgical centers represent a narrower but defensible margin pool as same-day discharge requirements intensify antiemetic prophylaxis standards.
- Pharmacopeial harmonization:Revisions to USP and EP monographs for palonosetron hydrochloride could enable streamlined multi-regional batch release for qualified manufacturers.
Industry Challenges
- Stability testing complexity:India's CDSCO and China's NMPA impose distinct labeling and stability requirements that filter tender participation in Asia's largest hospital systems, extending registration timelines.
- Biosimilar substitution policy uncertainty:Evolving pharmacopeial standards and generic substitution frameworks across dosage form categories create forecasting complexity for capacity planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palonosetron Hydrochloride Market |
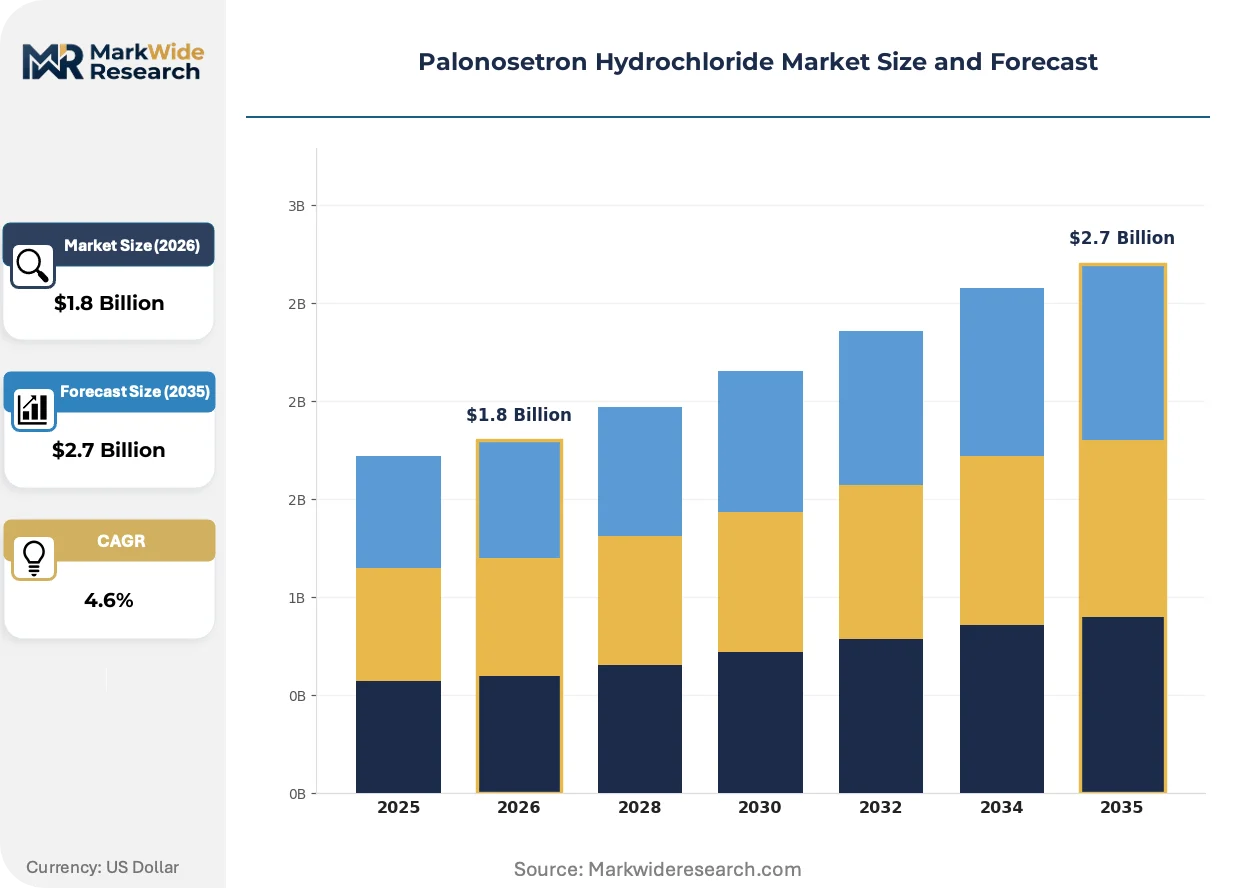
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injections, Oral Solutions, Infusions End User: Hospitals, Clinics, Outpatient Facilities, Home Healthcare Delivery Mode: Intravenous, Oral, Subcutaneous, Topical Therapy Area: Cancer, Postoperative Nausea, Chemotherapy Induced, Radiation Therapy |
| Companies Covered | Wavelength Pharmaceuticals, Farmihispania Group, Tyche Industries, ALP Pharm, Qilu Pharmaceutical, Shanghai Jinhe Bio-Pharmaceutical, Tecoland, Fresenius Kabi, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palonosetron Hydrochloride Market Evolving Landscape
Formulation science and administration modality are converging to shift where palonosetron therapy occurs, compressing the boundary between institutional and home-based care while regulatory frameworks scramble to keep pace with clinical practice evolution.
Subcutaneous depot formulations of 5-HT3 antagonists are decentralizing chemotherapy-induced nausea prophylaxis from infusion centers to patient homes. Oncology practices in the United States are piloting these extended-release alternatives for moderately emetogenic regimens. This modality is decentralizing site-of-care revenue and rewiring pharmacy benefit structures around self-administered supportive care.
REACH and EU Green Deal chemical sustainability mandates are pressuring API manufacturers to document solvent recovery rates and carbon intensity in palonosetron synthesis. EMA inspections now incorporate environmental risk assessments into GMP compliance evaluations. European contract manufacturers are responding by retrofitting batch reactors with closed-loop solvent systems and submitting enhanced substance volume tracking to ECHA.
Hospital purchasing cooperatives in Germany and Japan are unbundling antiemetic procurement from bundled chemotherapy support contracts, creating direct price visibility between generic injectable suppliers and pharmacy directors. This disintermediation is compressing traditional wholesaler margins and accelerating formulary switches based on unit-cost rather than historical brand relationships. The shift is most visible in university hospital networks with centralized pharmacy and therapeutics committees.
Palonosetron Hydrochloride Market Segmentation
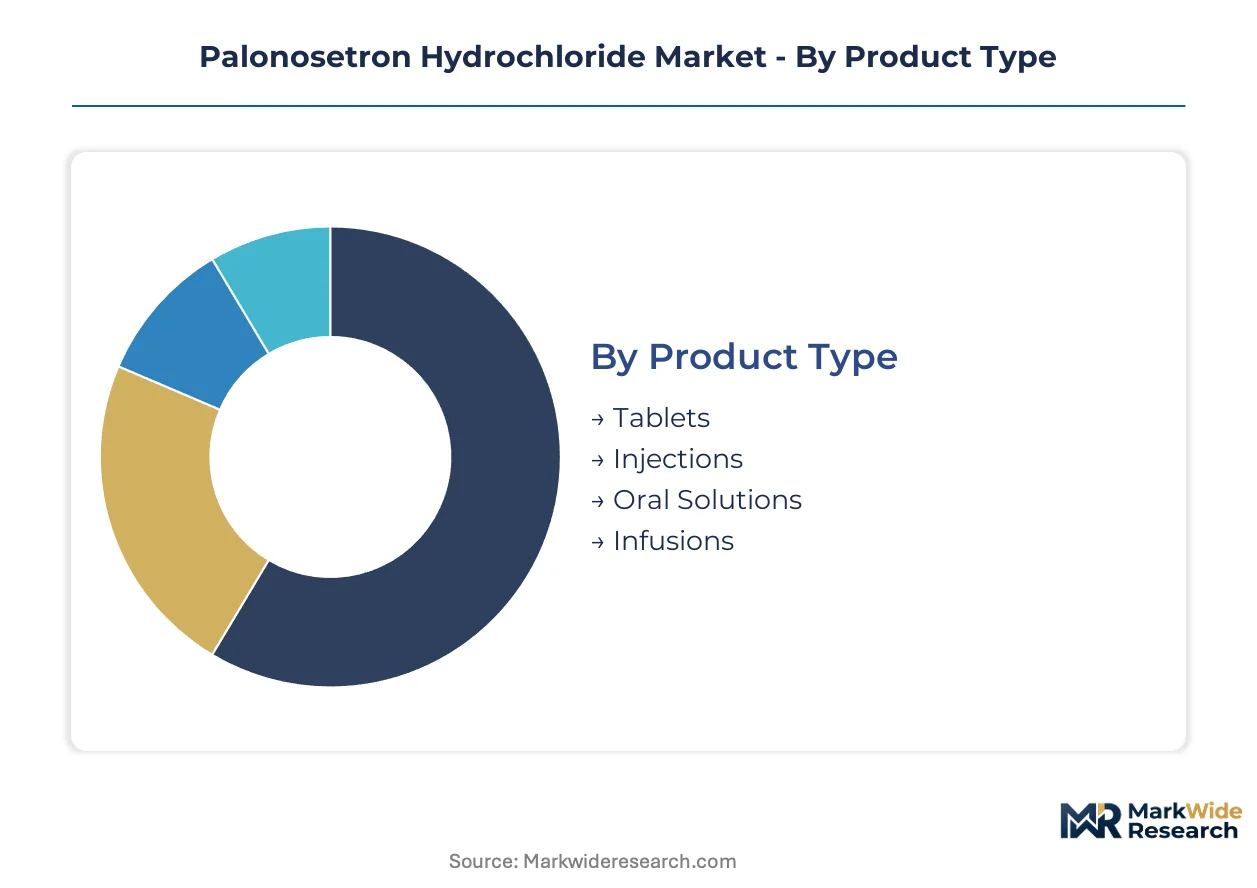
Palonosetron hydrochloride's commercial structure fractures across administration modality, care setting, and therapeutic indication. Each segmentation axis carries distinct margin profiles, regulatory pathways, and competitive intensity that shape manufacturer resource allocation.
Product Type:
Supply concentration clusters around sterile injectable capacity in Western Europe and India, with oral formats dispersing across broader contract manufacturing networks.
- Injections:Single-dose IV vials and prefilled syringes dominate hospital procurement in Germany, Japan, and India. Perioperative and oncology units prioritize controlled administration with nursing labor reduction. EMA GMP inspections filter qualified suppliers, compressing competition around sterile facility ownership.
- Oral Solutions:Self-administered formats expand into outpatient and home healthcare settings where patient convenience reduces infusion center burden. Formulation stability requirements and taste-masking technology differentiate supplier capabilities.
- Tablets:Solid oral dosage forms serve markets with established generic substitution frameworks and pharmacy-driven procurement.
- Infusions:Ready-to-use bag presentations minimize compounding steps in high-volume chemotherapy units.
Today's leader: Injections. Tomorrow's challenger: Oral Solutions.
End User:
Customer type determines pricing leverage, with institutional buyers consolidating purchasing power through cooperative frameworks.
- Hospitals:University medical centers and acute care facilities anchor demand through formulary control and protocol standardization. Centralized pharmacy and therapeutics committees in Germany and Japan unbundle antiemetic procurement from bundled chemotherapy contracts.
- Clinics:Outpatient oncology clinics in the United States expand prophylactic protocols ahead of CMS reimbursement shifts toward value-based chemotherapy support.
- Outpatient Facilities:Ambulatory surgical centers intensify antiemetic standards for same-day discharge requirements.
- Home Healthcare:Dispensing pharmacies and home infusion services extend therapy reach for oral and subcutaneous formats.
Hospitals command volume. Home Healthcare climbs fastest.
Delivery Mode:
Route of administration locks into site-of-care economics and patient mobility constraints.
- Intravenous:Controlled infusion in institutional settings remains the clinical standard for moderately and highly emetogenic regimens.
- Oral:Swallowable and sublingual formats enable patient self-management outside facility walls.
- Subcutaneous:Depot formulations piloting in United States oncology practices decentralize prophylaxis from infusion centers to patient homes.
- Topical:Transdermal delivery remains exploratory for 5-HT3 antagonist class pharmacokinetics.
Intravenous holds share. Subcutaneous gains protocol penetration.
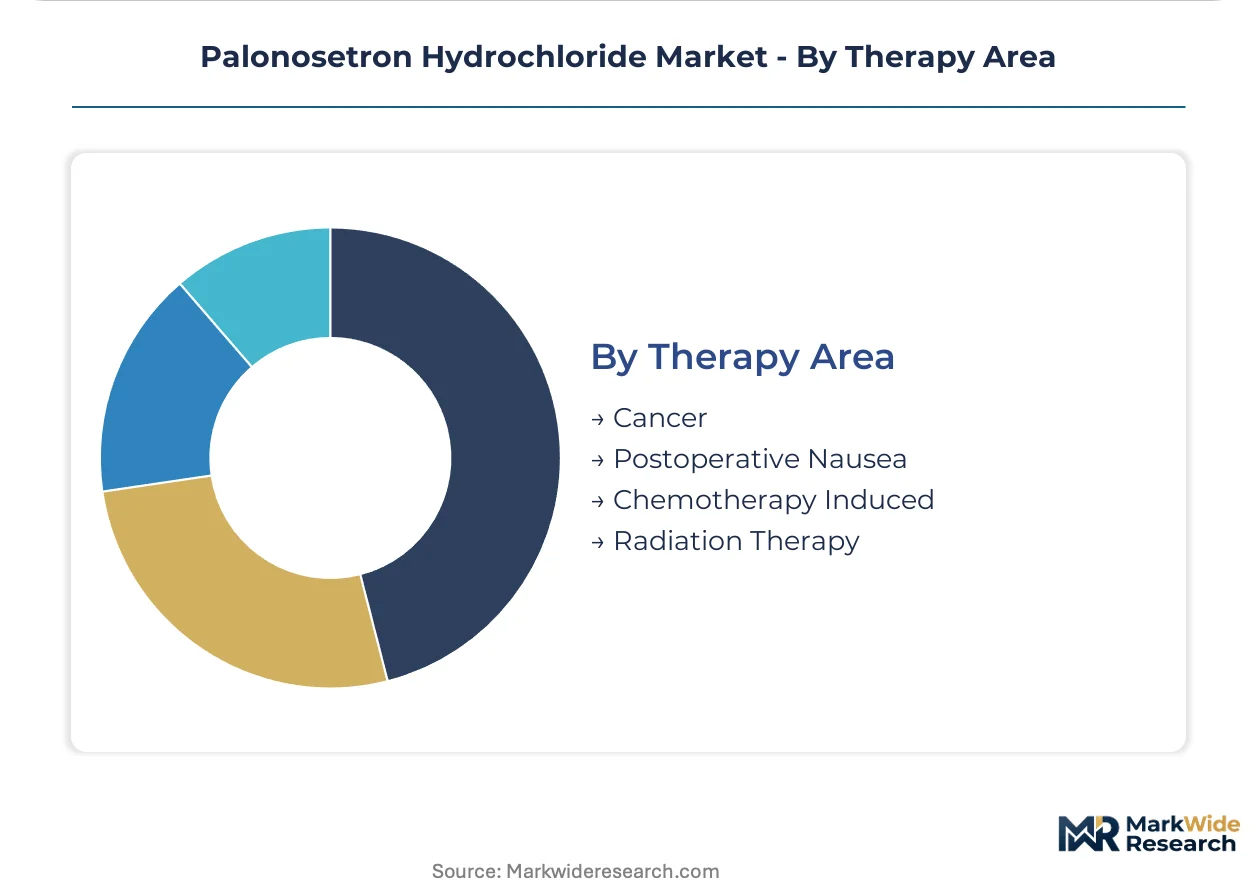
Therapy Area:
Indication maturity separates established revenue cores from narrower margin pools with expansion potential.
- Chemotherapy Induced:Acute and delayed CINV prophylaxis anchors the therapeutic franchise with extended plasma half-life exceeding 40 hours enabling single-dose coverage. NK1 receptor antagonists and olanzapine-based regimens compete for delayed emesis control in academic centers with protocol flexibility.
- Postoperative Nausea:Ambulatory surgical centers represent a defensible but volume-constrained segment as PONV prophylaxis standards tighten.
- Cancer:Broad oncology supportive care indication overlaps with CINV but extends to radiation-induced and other cancer-related nausea.
- Radiation Therapy:Smaller patient population with distinct emetogenic risk profiling.
Chemotherapy Induced dominates revenue. Postoperative Nausea offers margin defense.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and India anchor contrasting supply tiers for palonosetron hydrochloride, with European sterile manufacturing capacity commanding formulary premiums while Indian API producers recalibrate bulk output for North American and European finished-dose demand.
United States
Outpatient oncology clinics expand prophylactic antiemetic protocols ahead of CMS reimbursement shifts toward value-based chemotherapy support. FDA bioequivalence standards filter qualified suppliers for hospital formulary inclusion. The Boston-Cambridge corridor anchors academic medical center procurement with protocol standardization around single-dose IV regimens.
Germany
University hospital networks consolidate antiemetic purchasing through centralized pharmacy and therapeutics committees. EMA GMP inspections incorporate environmental risk assessments under REACH and EU Green Deal mandates. The Rhine-Ruhr industrial cluster hosts retrofitting of batch reactors with closed-loop solvent systems for enhanced substance volume tracking.
Japan
Hospital purchasing cooperatives unbundle antiemetic procurement from bundled chemotherapy support contracts, creating direct price visibility between generic injectable suppliers and pharmacy directors. PMDA stability requirements govern batch release protocols for multi-regional market access. The Kansai region concentrates perioperative formulary control in high-volume surgical centers.
India
API manufacturers recalibrate bulk production capacity to meet rising procurement from European and North American finished-dose makers. CDSCO imposes distinct labeling and stability testing requirements that filter tender participation in Asia's largest hospital systems. The Mumbai-Pune pharmaceutical belt anchors backward integration into key starting materials for margin protection.
China
NMPA pharmacopeial monograph revisions shape manufacturing location decisions for producers seeking multi-regional market access. Dual carbon goals pressure API manufacturers to document solvent recovery rates in palonosetron synthesis. The Yangtze River Delta clusters sterile injectable capacity serving domestic hospital procurement and export qualification.
Palonosetron Hydrochloride Market Competitive Landscape
European producers anchor one tier; Indian specialists hold API supply leverage; North American firms compete on brand recognition in oncology supportive care protocols. The vendor base splits between sterile manufacturing asset owners and bulk synthesis specialists, with hospital channel control and backward integration into key starting materials as the dominant competitive vectors. Three archetypes dominate: integrated API-to-finished-dose manufacturers, sterile facility operators with EMA-qualified capacity, and brand-anchored oncology supportive care franchises. Capacity expansion in qualified sterile facilities and strategic backward integration into synthesis intermediates represent the primary competitive moves.
Among European hospital channel operators, Fresenius Kabi anchors formulary positioning through Western European acute care penetration. Merck occupies the brand-anchored tier, representing oncology supportive care recognition across major academic medical centers. Wavelength Pharmaceuticals exemplifies the backward-integrated archetype, with Zhengzhou-based Qilu Pharmaceutical and Shanghai Jinhe Bio-Pharmaceutical representing Chinese manufacturing scale. Indian specialists Tyche Industries and Tecoland sit within the API supply tier, while Farmihispania Group and ALP Pharm exemplify European regional positioning.
| Leading Market Players |
|---|
| Wavelength Pharmaceuticals |
| Farmihispania Group |
| Tyche Industries |
| ALP Pharm |
| Qilu Pharmaceutical |
| Shanghai Jinhe Bio-Pharmaceutical |
| Tecoland |
| Fresenius Kabi |
| Merck |
| Others |
Value Network & Pricing Analysis
Backward integration into key starting materials anchors both supply security and margin protection for palonosetron hydrochloride manufacturers navigating raw material volatility. Indian API producers leveraging captive synthesis of quinuclidine intermediates command pricing power over non-integrated competitors dependent on spot market procurement.
Pricing Analysis
Capacity additions in India are reshaping price floors for generic injectable palonosetron across European hospital formularies. Three-tier pricing structure across EMA-qualified sterile manufacturers, FDA-approved finished-dose makers, and non-integrated API suppliers reflects certification grade and sterile facility ownership. Cost compression in the oral solution segment is intensifying because outpatient self-administration protocols reduce infusion center reimbursement capture. Ambulatory surgical centers exhibit highest price sensitivity due to bundled procedure economics, while academic medical centers with protocol standardization mandates show lowest sensitivity to unit-cost variation.
Supply Chain Analysis
Single-source vulnerability sits with European sterile injectable capacity concentrated among EMA-qualified facilities in Germany and Italy. API synthesis feeds from Indian bulk manufacturers and Chinese intermediate producers, with final sterile filling resting on Western European contract manufacturing networks. Tariff exposure on quinuclidine derivatives sourced from Chinese chemical parks threatens margin structures for non-backward-integrated formulators. Distribution runs through hospital purchasing cooperatives in Germany and Japan that unbundle antiemetic procurement from bundled chemotherapy contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palonosetron hydrochloride production economics favor geographic arbitrage between Indian API synthesis costs and European sterile manufacturing premiums, with EMA GMP compliance costs creating a regulatory moat that justifies margin capture across the value chain.
For Market Incumbents: Anticipate NK1 receptor antagonist substitution threats in academic medical centers by deepening backward integration into quinuclidine starting materials and securing EMA environmental risk assessment pre-qualification ahead of REACH solvent recovery mandates. Channel control through hospital purchasing cooperative participation in Germany and Japan remains the priority defensive lever against generic injectable price erosion. For New Entrants and Emerging Players: Home healthcare dispensing pharmacies represent an underserved buyer archetype with limited formulary gatekeeper interference and direct patient access. Oral solution formats for moderately emetogenic regimens offer the most penetrable entry point, with subcutaneous depot development partnerships providing differentiation against institutional IV dominance. For Investors and Strategic Acquirers: Roll-up economics work for Indian API-to-finished-dose integrators because CDSCO and EMA inspection backlogs create scarcity value for multi-regional qualified capacity. The long-term viability window favors platforms with sterile facility ownership and captive intermediate supply. Watch EMA GMP inspection queue lengths as the inflection signal for capacity valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quinuclidine Intermediates | Captive supply of key starting materials insulates margin structures against petrochemical feedstock volatility. |
| EMA GMP Pre-Qualification for Sterile Injectable Capacity | Environmental risk assessment compliance under REACH enables formulary access in German university hospital networks. |
| Oral Solution Formulation Development | Home healthcare channel penetration reduces dependence on infusion center procurement consolidation. |
| Hospital Purchasing Cooperative Direct Contracts | Unbundled antiemetic procurement in Japan creates price visibility bypassing traditional wholesaler margins. |
| Subcutaneous Depot Partnership Licensing | Extended-release modality pilots in United States oncology practices decentralize site-of-care revenue capture. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital pharmacy directors, oncology formulary committee members, CDSCO regulatory affairs leads, and sterile manufacturing plant managers with secondary validation against FDA 483 inspection observations, EMA GMP certificates, CDSCO stability testing guidelines, and hospital procurement database tender records. Bottom-up patient volume modeling and top-down API production capacity estimates were triangulated for segment-level demand assessment.
Segment-weighting across the projection horizon applied dosage form, administration route, therapy area indication, and regional regulatory cluster dimensions to distribute volume and value outputs. CAGRs were derived from regression analysis of historical procurement trends and forward projection of reimbursement policy shifts. Forecast inputs incorporated CMS value-based chemotherapy support mandate timelines and EMA inspection capacity constraints.
Underlying measurement precision varies by segment; injectable hospital procurement carries tighter precision than emerging oral solution home healthcare channels. Forecasts reflect documented assumptions regarding regulatory approval timelines and substitution therapy penetration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Opioid Analgesics Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Global Loratadine Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Global Dengue Vaccine Market