
 Asia-Pacific Anesthesia Drugs Market | 2026-2036
Asia-Pacific Anesthesia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Anesthesia Drugs Market Outlook
Multi-source API procurement is pivoting toward captive manufacturing across leading anesthesia drug suppliers. Fresenius SE & Co. KGaA leverages its vertically integrated hospital supply chain to secure consistent propofol distribution. Piramal Enterprises Limited anchors its position through specialized injectable manufacturing at Indian facilities. B. Braun SE competes via controlled European sourcing paired with regional filling operations.
Asia-Pacific anesthesia drugs comprise pharmacological agents inducing reversible loss of consciousness or sensation, including intravenous formulations such as propofol emulsions and inhalational agents like sevoflurane vapor, manufactured under aseptic conditions with stringent purity controls for surgical and procedural sedation. General anesthetics sustain the largest revenue pool given their irreplaceable role in major surgical protocols across hospitals. Intravenous delivery dominates fastest-growing share as ambulatory surgery centers adopt rapid-recovery protocols. Local anesthetics occupy mature positioning in pain management applications with stable margin profiles.
India's CDSCO mandates bioequivalence documentation for generic anesthetic injectables, tightening market access for non-compliant manufacturers. China's NMPA enforces Good Manufacturing Practice certification for inhalational anesthetic production facilities, elevating capital requirements for domestic entrants. Australia's TGA aligns with ISO 13485 for device-drug combination products used in target-controlled infusion systems. Stakeholders must monitor evolving pharmacovigilance reporting obligations as regional regulators harmonize post-market surveillance frameworks.
Market Dynamics
India's PLI scheme for pharmaceutical manufacturing is forcing anesthesia API suppliers to reconfigure sourcing strategies around captive production facilities rather than merchant market procurement.
Growth Catalysts
- Propofol emulsion demand:Tertiary hospitals in China's tier-one cities are upgrading to advanced intravenous anesthetic agents for rapid-recovery surgical protocols.
- CDSCO bioequivalence mandates:India's tightened documentation requirements for generic anesthetic injectables are consolidating compliant domestic manufacturers.
- Sevoflurane vapor infrastructure:Hospital infrastructure upgrades across South Korea and Japan are accelerating inhalational anesthetic adoption in ambulatory settings.
Market Restraints
- API import concentration:China's NMPA Good Manufacturing Practice certification requirements elevate capital barriers for domestic entrants seeking inhalational production capabilities.
- Aseptic filling capacity scarcity:Specialized injectable manufacturing lines for propofol emulsions concentrate among limited European-sourced equipment suppliers.
- Target-controlled infusion standardization:Australia's TGA alignment with ISO 13485 for device-drug combinations creates compliance friction for non-integrated vendors.
Strategic Opportunities
- Vietnam's surgical infrastructure expansion:Underpenetrated central provinces present white space for intravenous anesthetic distribution partnerships with private hospital chains.
- PLI backward integration incentives:India's production-linked incentive scheme rewards domestic API synthesis for sevoflurane and propofol precursors.
- Tele-anesthesia protocols:Remote perioperative monitoring convergence with AI-assisted dosing algorithms is opening peri-urban and rural service models.
Industry Challenges
- Pharmacovigilance reporting harmonization:Regional regulators are synchronizing post-market surveillance frameworks, forcing manufacturers to unify adverse event documentation across CDSCO, NMPA, and TGA jurisdictions.
- Aseptic process validation timelines:Sterile injectable facility qualification for propofol emulsions demands extended batch consistency studies before commercial release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Anesthesia Drugs Market |
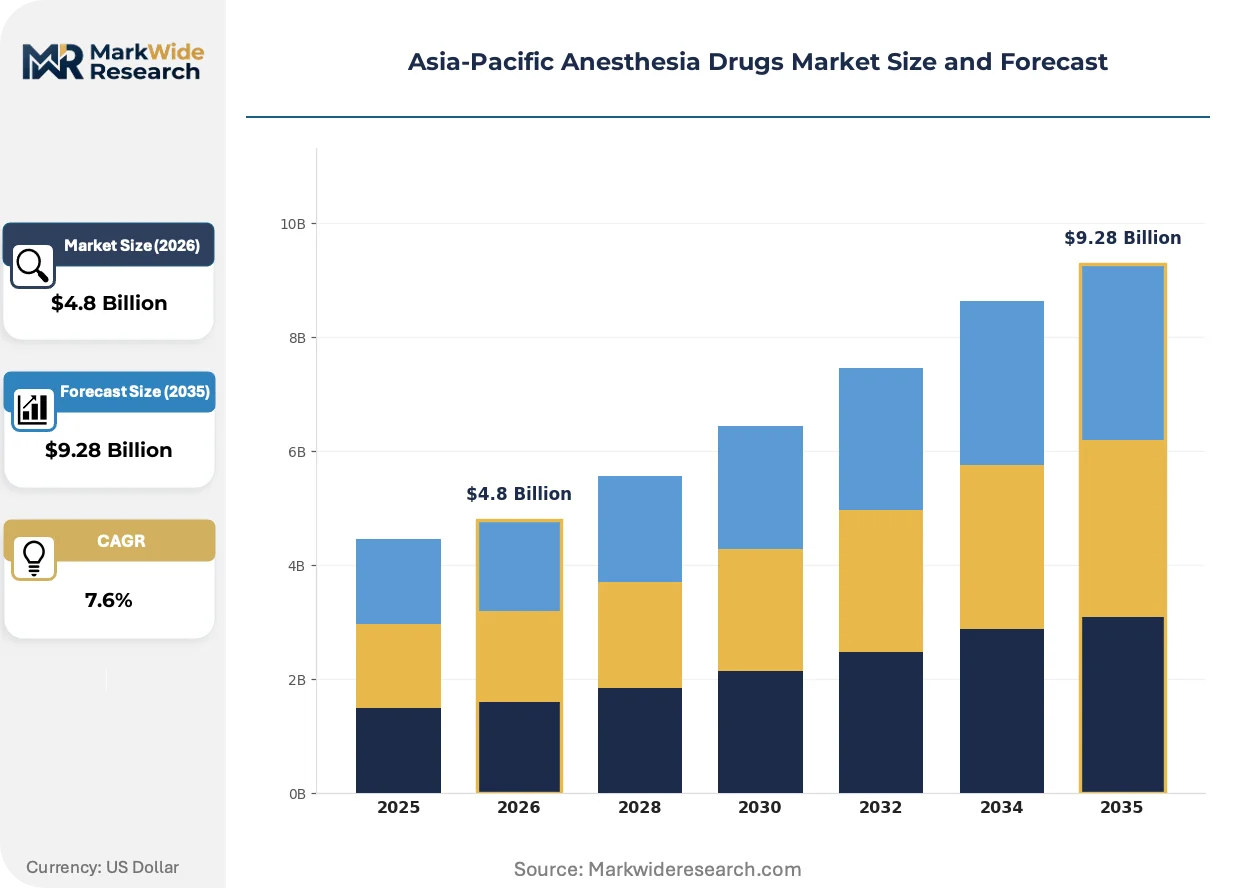
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Anesthetics, Local Anesthetics, Regional Anesthetics, Sedatives Delivery Mode: Intravenous, Inhalation, oral, Transdermal End User: Hospitals, Ambulatory Surgery Centers, Clinics, Homecare Application: Major Surgery, Minor Surgery, Diagnostic Procedures, Pain Management |
| Companies Covered | B. Braun SE, Novartis AG (Sandoz), Fresenius SE & Co. KGaA, Piramal Enterprises Limited, Aspen Holdings, Baxter International, F. Hoffmann-La Roche AG, Eisai Co Ltd, AbbVie Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Anesthesia Drugs Market Strategic Shifts
Technology convergence between drug delivery systems and digital monitoring platforms is compressing traditional boundaries between anesthesia pharmaceuticals and perioperative devices across Asia-Pacific tertiary care networks.
Closed-loop anesthesia delivery systems incorporating real-time bispectral index monitoring are modularizing the traditional anesthesiologist workflow. Major tertiary hospitals in Shanghai and Tokyo are piloting these integrated platforms for high-volume orthopedic and cardiac procedures. This modularization is compressing staffing ratios per operating theater while elevating capital equipment bundling requirements for pharmaceutical suppliers.
NMPA's 2023 revised Good Manufacturing Practice annex for sterile medicinal products is mandating continuous environmental monitoring systems in aseptic filling suites. Domestic Chinese manufacturers of sevoflurane and propofol must retrofit facilities with automated particle detection and alert systems. The inhalational anesthetic segment bears disproportionate compliance costs given vapor handling complexity and facility classification requirements.
Hospital procurement committees across India's corporate hospital chains are consolidating anesthesia drug purchasing through centralized pharmacy and therapeutics committees. Single-source contracts for propofol and sevoflurane are displacing multi-vendor spot purchasing that dominated private hospital supply historically. This concentration is most visible in Bengaluru and Hyderabad, where Apollo and Narayana Health networks have implemented annual tender frameworks with volume commitment clauses.
Asia-Pacific Anesthesia Drugs Market Segmentation
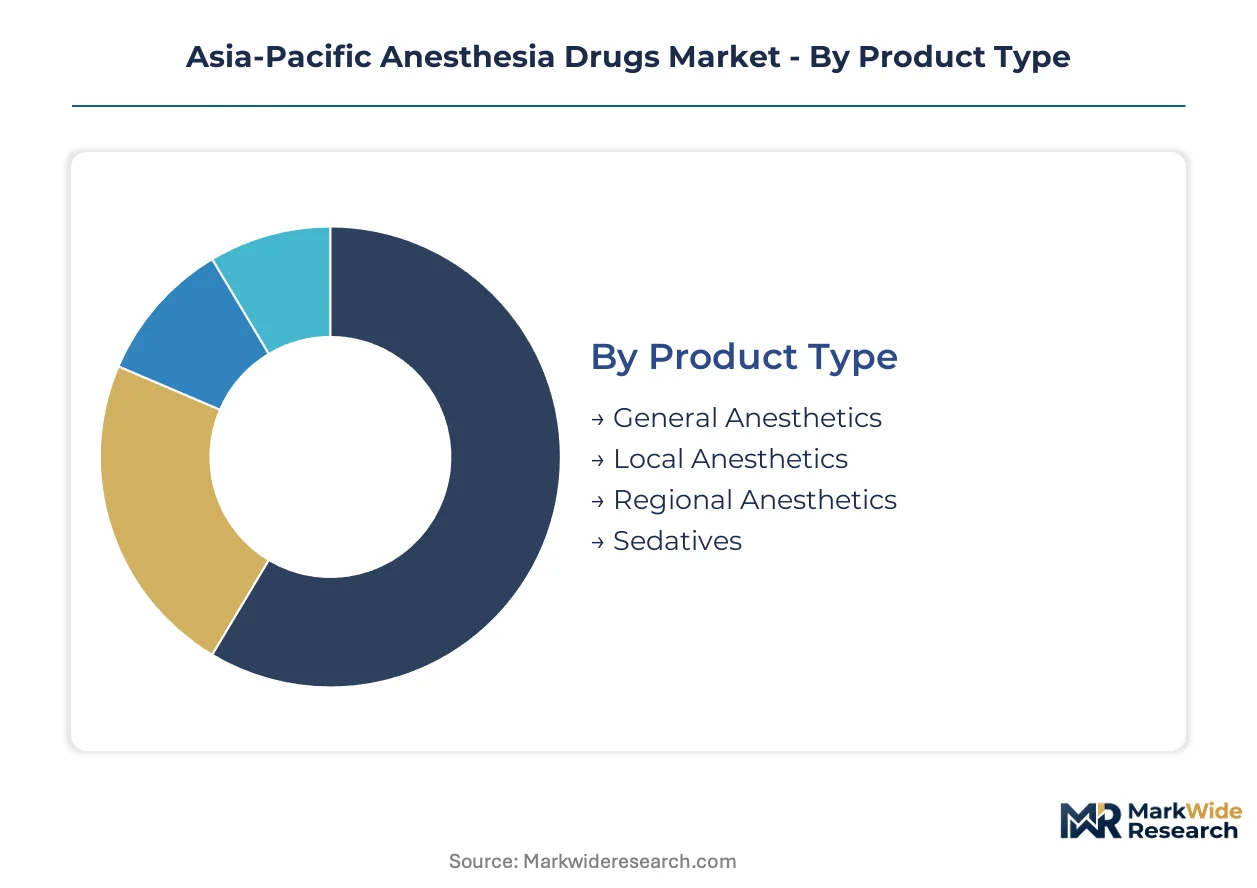
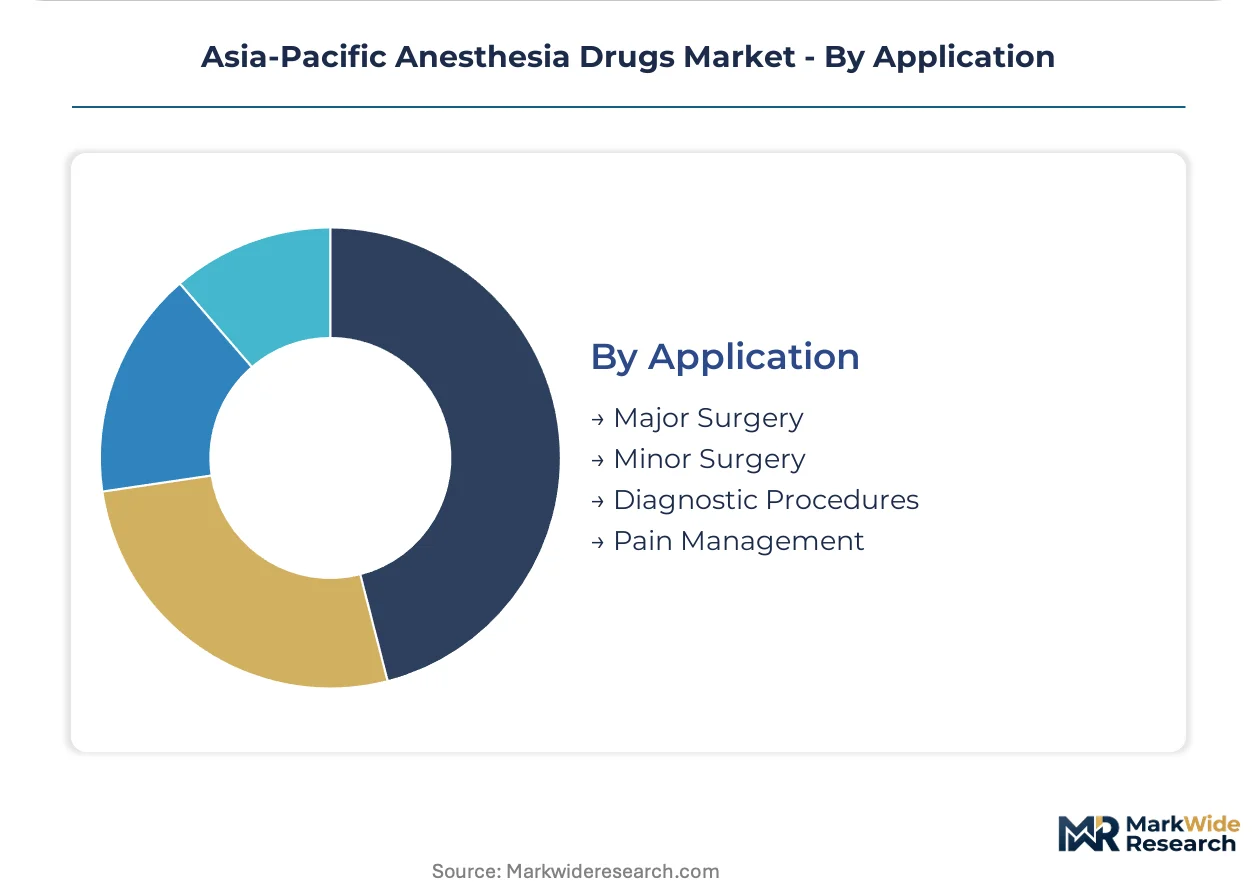
Segmentation in Asia-Pacific anesthesia drugs reveals distinct procurement patterns across hospital tiers and surgical settings. Understanding these divides enables suppliers to align formulation portfolios with specific facility capabilities and regulatory compliance requirements.
Product Type:
Hospital pharmacy committees prioritize product type based on surgical volume mix and anesthesiologist training depth.
- General Anesthetics:Pharmacological agents inducing reversible unconsciousness through intravenous propofol emulsions or inhalational sevoflurane vapor. Tertiary hospitals in Shanghai, Mumbai, and Seoul concentrate demand for these agents as cardiac and orthopedic procedure volumes expand.
- Local Anesthetics:Peripheral nerve-blocking compounds including lidocaine and bupivacaine formulations. Day surgery centers across Australia's eastern seaboard and India's corporate hospital chains drive procurement for dermatological and ophthalmological interventions.
- Regional Anesthetics:Spinal and epidural formulations targeting specific anatomical regions. Maternity wards and orthopedic units in Thailand's private hospital sector generate consistent volume.
- Sedatives:Benzodiazepine and alpha-agonist derivatives for procedural anxiety management. Endoscopy suites in Japan's metropolitan hospitals favor these for patient comfort protocols.
Volume sits with General Anesthetics; growth tilts toward Sedatives as ambulatory procedural sedation protocols proliferate.
Delivery Mode:
Capital equipment compatibility and recovery speed requirements determine delivery mode selection across facility types.
- Intravenous:Rapid-onset formulations including propofol lipid emulsions and etomidate solutions. China's tier-one city hospitals are upgrading target-controlled infusion infrastructure to support these agents for same-day discharge protocols.
- Inhalation:Volatile liquid anesthetics administered via calibrated vaporizers. Sevoflurane dominates this segment as Japanese and South Korean facilities modernize operating theater ventilation systems.
- Oral:Preoperative anxiolytic tablets for pediatric and needle-averse adult populations. India's mid-tier private hospitals source these for minor dental and dermatological procedures.
- Transdermal:Patch-based lidocaine delivery for chronic pain adjunct therapy. Australia's regional clinics utilize these for outpatient pain management where injection access is limited.
Intravenous commands current volume leadership; Inhalation gains share fastest as vaporizer technology standardizes across newly constructed surgical suites.
End User:
Procurement scale and formulary control intensity vary sharply across end user categories.
- Hospitals:Multi-specialty tertiary institutions with centralized pharmacy and therapeutics committees. Apollo and Narayana Health networks in Bengaluru and Hyderabad consolidate annual tender contracts for propofol and sevoflurane with volume commitment clauses.
- Ambulatory Surgery Centers:Focused facilities optimized for rapid turnover procedures. South Korea's expanding ASC sector drives demand for short-acting intravenous agents compatible with streamlined discharge protocols.
- Clinics:Limited-procedure outpatient settings with restricted storage capabilities. Vietnam's provincial private chains source single-dose vial formats to minimize cold chain requirements.
- Homecare:Postoperative pain management and palliative sedation settings. Australia's community nursing services utilize patient-controlled analgesia pumps with morphine and fentanyl formulations.
Hospitals anchor absolute volume; Ambulatory Surgery Centers represent the steepest expansion trajectory as same-day surgery protocols penetrate Asia-Pacific markets.
Application:
Surgical complexity and reimbursement tiering shape application-specific demand patterns.
- Major Surgery:Open cardiac, neurosurgical, and oncological procedures requiring deep anesthesia maintenance. China's top-tier municipal hospitals in Beijing and Guangzhou concentrate consumption of advanced inhalational and intravenous combination protocols.
- Minor Surgery:Laparoscopic, arthroscopic, and soft tissue procedures with shorter duration requirements. India's high-volume cataract and hernia repair centers favor rapid-recovery intravenous formulations.
- Diagnostic Procedures:Endoscopy, imaging-guided biopsy, and electrophysiological studies. Japan's aging population drives colonoscopy and gastroscopy sedation demand in metropolitan diagnostic centers.
- Pain Management:Chronic and acute pain protocols including epidural infusion and nerve block maintenance. Thailand's medical tourism hospitals utilize multimodal analgesia for postoperative recovery differentiation.
Major Surgery retains volume dominance; Diagnostic Procedures climb fastest as screening program expansion and aging demographics multiply procedure counts across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propofol precursor manufacturing clusters in Gujarat and Jiangsu anchor regional supply chains for intravenous anesthetic formulation across the Asia-Pacific.
China
Shanghai's tertiary hospitals are retrofitting operating theaters with target-controlled infusion infrastructure for rapid-recovery protocols. NMPA's 2023 revised Good Manufacturing Practice annex mandates continuous environmental monitoring in aseptic filling suites. Domestic manufacturers in Jiangsu province face disproportionate compliance costs for sevoflurane vapor handling and facility classification upgrades.
India
Apollo and Narayana Health networks in Bengaluru and Hyderabad consolidate annual tender contracts with volume commitment clauses for propofol and sevoflurane. CDSCO mandates bioequivalence documentation for generic anesthetic injectables, tightening market access for non-compliant manufacturers. The PLI scheme rewards domestic API synthesis for anesthesia precursors at captive facilities in Gujarat and Telangana.
Japan
Metropolitan diagnostic centers in Tokyo and Osaka drive colonoscopy and gastroscopy sedation demand from aging demographics. PMDA oversight aligns with international standards for device-drug combination products in target-controlled infusion systems. Major tertiary hospitals are piloting closed-loop anesthesia delivery platforms for high-volume orthopedic and cardiac procedures.
South Korea
The expanding ambulatory surgery center sector drives procurement of short-acting intravenous agents compatible with streamlined discharge protocols. MFDS enforces pharmacovigilance reporting harmonization with regional surveillance frameworks. Hospital infrastructure upgrades in Seoul are accelerating inhalational anesthetic adoption with modernized operating theater ventilation systems.
Australia
Community nursing services utilize patient-controlled analgesia pumps with morphine and fentanyl formulations for postoperative pain management. TGA aligns with ISO 13485 for device-drug combination products used in target-controlled infusion systems. Eastern seaboard day surgery centers concentrate demand for local anesthetic formulations in dermatological and ophthalmological interventions.
Asia-Pacific Anesthesia Drugs Market Competitive Environment
Backward integration into API manufacturing dominates the current landscape as suppliers reconfigure sourcing strategies around captive production facilities. The vendor base concentrates among European-origin multinationals with regional filling operations and Indian specialists with injectable manufacturing expertise. Three archetypes define positioning: vertically integrated hospital supply chains, specialized aseptic injectable manufacturers, and European-sourced regional assemblers. Portfolio diversification and geographic expansion through distribution partnerships constitute the dominant competitive moves.
Among European-origin healthcare conglomerates, Fresenius SE & Co. KGaA and B. Braun SE exemplify the vertically integrated archetype with controlled sourcing paired with regional operations. Piramal Enterprises Limited occupies a position within the specialized injectable tier, anchoring domestic manufacturing capabilities at Indian facilities. These three entities represent distinct strategic postures in a market where aseptic filling capacity scarcity concentrates specialized manufacturing lines among limited equipment suppliers.
| Leading Market Players |
|---|
| B. Braun SE |
| Novartis AG (Sandoz) |
| Fresenius SE & Co. KGaA |
| Piramal Enterprises Limited |
| Aspen Holdings |
| Baxter International |
| F. Hoffmann-La Roche AG |
| Eisai Co Ltd |
| AbbVie Inc |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up injectable specialists anchor supply-side discipline across Asia-Pacific anesthesia markets, translating concentrated aseptic filling capacity into pricing power while captive API investments compress merchant procurement arbitrage. Their ownership structures reward volume commitment clauses over spot-market flexibility, binding tertiary hospital networks to multi-year contracts.
Pricing Analysis
Warranty and service bundling separates premium propofol emulsions from economy-grade alternatives, with European-origin suppliers including calibration support and vaporizer maintenance in tier-one contracts. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and cold-chain reliability rather than active ingredient differentiation alone. Cost compression in economy intravenous segments is intensifying because India's PLI-scheme entrants undercut legacy importers on API synthesis. Ambulatory surgery centers exhibit highest price sensitivity, while cardiac surgery units in Shanghai and Seoul prioritize rapid-recovery pharmacokinetics over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with European equipment suppliers for aseptic filling lines, constraining capacity expansion for propofol lipid emulsion manufacturers in India and China. Propofol precursor synthesis clusters in Gujarat and Jiangsu, while sevoflurane vapor handling equipment draws from German and Japanese engineering bases. Regulatory restriction risk emanates from NMPA's continuous environmental monitoring mandates requiring facility retrofits. Distribution runs through hospital pharmacy and therapeutics committees consolidating annual tenders with volume commitment clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into API manufacturing defines competitive positioning across Asia-Pacific anesthesia markets, with PLI incentives and GMP compliance costs forcing captive production investments over merchant sourcing.
For Market Incumbents: Deepen captive propofol precursor manufacturing at Gujarat and Telangana facilities to offset CDSCO bioequivalence documentation costs eroding generic injectable margins. Secure aseptic filling line capacity reservations with European equipment suppliers before NMPA environmental monitoring mandates trigger facility retrofit bottlenecks. For New Entrants and Emerging Players: Begin with Vietnam's underpenetrated central provinces where private hospital chains lack intravenous anesthetic distribution partnerships. Target single-dose vial formats for provincial clinics minimizing cold chain infrastructure, leveraging India's PLI backward integration incentives for domestic API synthesis cost positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier Indian injectable manufacturers facing CDSCO compliance cost pressures but holding validated aseptic capacity in Telangana and Andhra Pradesh. Monitor NMPA facility certification timelines as inflection signal for domestic Chinese manufacturer consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | CDSCO bioequivalence mandates and PLI incentives reward captive propofol precursor synthesis at Indian facilities. |
| Aseptic Filling Capacity Expansion | NMPA environmental monitoring requirements trigger retrofit demand for automated particle detection systems in Jiangsu. |
| Target-Controlled Infusion Partnerships | Shanghai and Tokyo tertiary hospitals pilot closed-loop platforms elevating device-drug combination procurement bundles. |
| Centralized Tender Consolidation | Apollo and Narayana Health networks displace multi-vendor spot purchasing with annual volume commitment frameworks. |
| Tele-Anesthesia Protocol Development | AI-assisted dosing algorithms open peri-urban service models beyond metropolitan diagnostic center concentration. |
Study Parameters
CDSCO regulatory filings, NMPA GMP certification databases, and hospital procurement contract registries formed the secondary backbone, cross-referenced with primary interviews across anesthesiologists, hospital pharmacy directors, regulatory affairs specialists, and API manufacturing executives. Bottom-up and top-down triangulation validated volume estimates against aseptic filling capacity utilization and surgical procedure databases.
Bottom-up modeling anchored forecast construction, segmenting by product type, delivery mode, end user tier, and application complexity across the analysis window. CAGRs derived from surgical volume projections, facility upgrade pipelines, and regulatory compliance cost trajectories. Propofol emulsion demand curves incorporated target-controlled infusion infrastructure deployment timelines in China's tier-one cities.
Regulatory timeline slippage, API import disruption, and pharmacovigilance reporting harmonization delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding PLI scheme continuity and NMPA enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
P2X7 Receptor Antagonists Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Global HER2 Antibodies Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Hospital Pharmaceuticals Market